
 Colombia Commercial Vehicles Lubricants Market | 2026-2036
Colombia Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Commercial Vehicles Lubricants Market Outlook
The gap between premium synthetic formulations and mineral-based commodity lubricants is expanding across Colombia's commercial fleet sector. Royal Dutch Shell leverages its synthetic portfolio to target temperature-stressed Andean operations. Terpel anchors its position through extensive fuel-station distribution networks that bundle lubricant sales.
Colombia commercial vehicles lubricants encompass refined petroleum-based and synthetic formulations engineered to reduce friction, dissipate heat, and prevent wear in diesel and gasoline engines operating under high load factors. These products typically meet SAE viscosity grades and API service categories formulated for extended drain intervals under tropical and high-altitude conditions. Engine oil dominates volume consumption across heavy-duty trucks and buses, while hydraulic oil captures concentrated margin pools in mining and construction fleet applications. Transmission fluid competes for share as automated manual transmissions penetrate urban bus and delivery van segments.
Colombia's Ministry of Mines and Energy enforces fuel quality and biofuel blending standards that directly alter lubricant additive requirements, while the National Institute of Metrology enforces product labeling and performance claims. Fleet operators and suppliers must monitor regulatory shifts around biofuel compatibility and emissions standards that redefine product certification pathways.
Market Dynamics
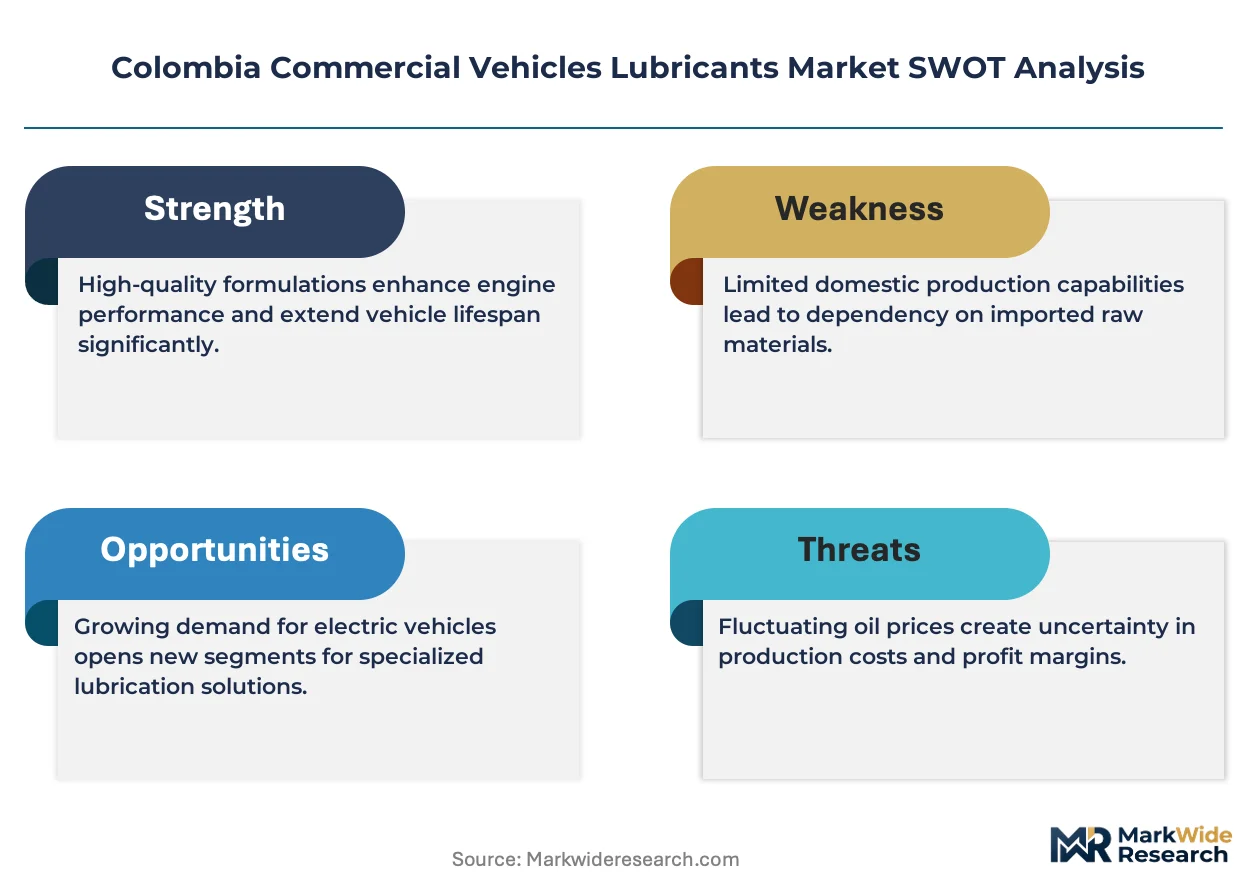
Biofuel blending mandates from Colombia's Ministry of Mines and Energy are forcing lubricant reformulation across commercial fleets, while synthetic additive packages displace mineral bases in temperature-stressed Andean corridors.
Growth Catalysts
- Extended drain interval technology:Synthetic formulations certified for longer service cycles reduce downtime for Bogotá-Medellín-Cali corridor operators. Heavy-duty truck fleets prioritize total cost of ownership over unit price.
- Biofuel compatibility mandates:Colombia's Ministry of Mines and Energy enforces ethanol and biodiesel blending standards that require corrosion-resistant additive packages. Lubricant suppliers reformulate detergent-dispersant systems to maintain engine protection.
- Mining fleet expansion:Antioquia and Boyacá mining operations drive hydraulic fluid consumption for excavators and haul trucks. High-load equipment specifications favor premium anti-wear formulations.
Market Restraints
- Base oil import dependency:Colombia lacks domestic Group III and PAO synthetic base stock production. Formulators rely on US Gulf Coast and Asian suppliers, exposing margins to freight rate volatility and currency fluctuation.
- Commodity lubricant price compression:Unbranded mineral oil distributors in peripheral urban centers undercut certified products. Fleet procurement officers face pressure to sacrifice specification compliance for immediate cost reduction.
- Technical service capacity gaps:Rural service stations in Amazonian and Pacific regions lack oil analysis laboratories. Extended drain interval warranties require condition monitoring that infrastructure cannot support.
Strategic Opportunities
- Automated manual transmission fluid penetration:Urban bus fleets in Cali and Barranquilla adopt AMT systems to reduce driver fatigue. Dedicated transmission fluids with synchronized friction modification capture margin pools absent from conventional gear oils.
- Used oil collection and re-refining infrastructure:Colombia's environmental licensing authority incentivizes circular economy investments. Re-refined base stocks qualify for carbon credit offsets under national climate commitments.
- Direct fleet contracting bypassing fuel-station networks:Large transport cooperatives negotiate bulk supply agreements with formulators. Volume commitments secure price stability and technical support unavailable through retail channels.
Industry Challenges
- Lubricant engineer talent scarcity:Colombian universities produce limited graduates with tribology and additive chemistry specialization. Formulators compete with petroleum refiners and mining companies for technical personnel.
- API certification timeline compression:New engine categories require updated service classifications. Test stand availability at North American laboratories creates bottlenecks for product launch schedules.
- Legacy fleet compatibility management:Pre-2010 commercial vehicles operate on obsolete viscosity grades. Suppliers must maintain parallel inventory for mixed-age fleet customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Commercial Vehicles Lubricants Market |
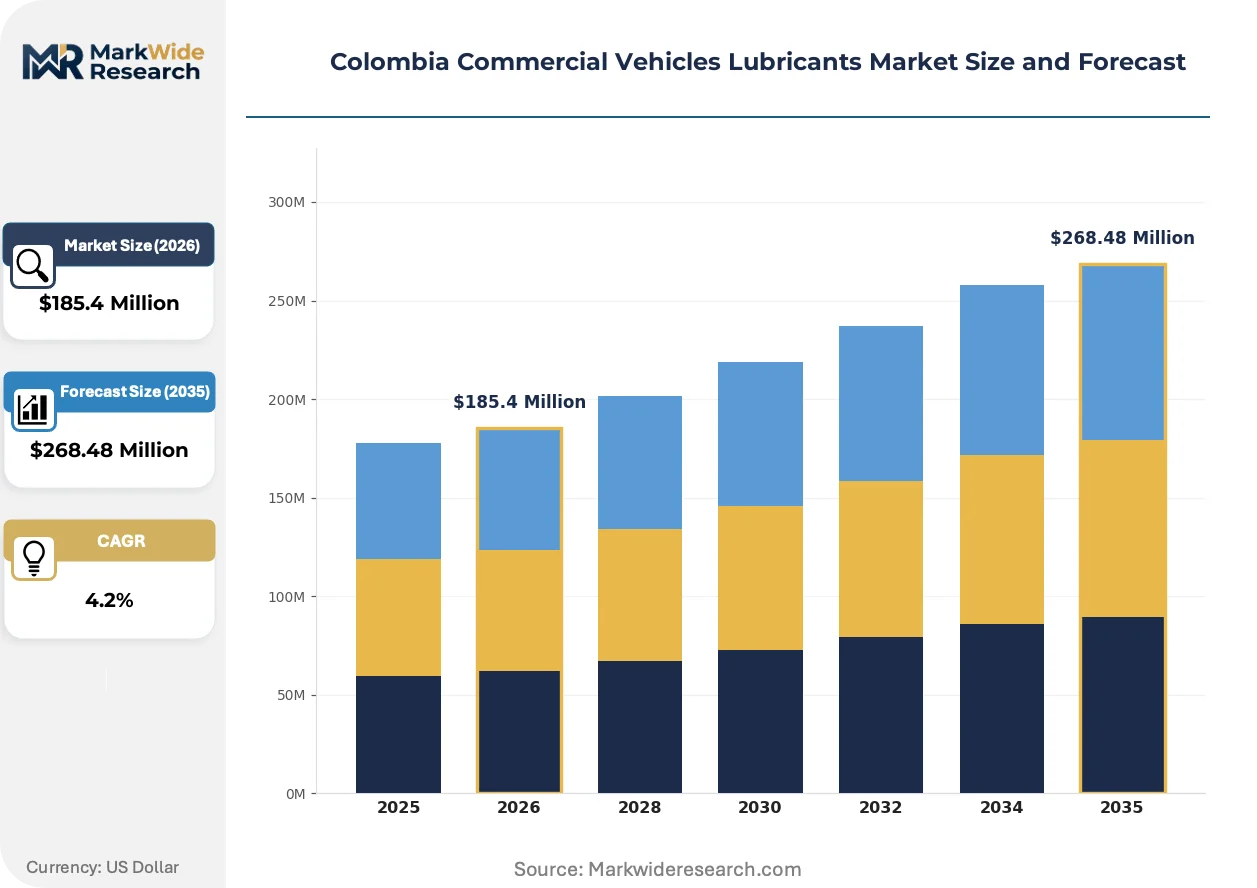
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $268.48 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Oil, Transmission Fluid Application: Heavy-Duty Trucks, Light-Duty Trucks, Buses, Vans Service Type: Preventive Maintenance, Routine Checkups, Emergency Repairs, Specialized Services End User: Fleet Operators, Independent Garages, OEMs, Transport Companies |
| Companies Covered | Royal Dutch Shell, BP (Castrol), TotalEnergies, Chevron Corporation, ExxonMobil, Terpel, Petromil SA, Petrobras, Motul, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Commercial Vehicles Lubricants Market Strategic Shifts
Synthetic formulation chemistry and digital condition monitoring are compressing traditional service intervals while regulatory pressure on emissions intensifies product performance requirements.
Low-ash, low-sulfurated ash, phosphorus and sulfur (SAPS) engine oils are consolidating specification authority across Euro VI-equivalent truck fleets operating in Colombia's high-altitude corridors. Fleet maintenance managers specify these formulations to protect exhaust aftertreatment systems from premature degradation. The technology is consolidating aftermarket demand around certified suppliers capable of demonstrating compatibility with selective catalytic reduction systems.
Colombia's Ministry of Mines and Energy enforces progressive biofuel blending mandates that alter lubricant additive requirements for corrosion inhibition and oxidation stability. Industrial consequence includes accelerated testing protocols for fuel dilution resistance and base number retention. Heavy-duty diesel engine oils face reformulation pressure most acutely, with suppliers submitting updated product data sheets to demonstrate compliance with national fuel quality regulations.
Consolidated procurement through transport cooperatives and mining contractors is displacing fragmented spot purchasing at retail fuel stations. Large fleet operators negotiate annual volume contracts with technical service attachments. This concentration is most visible in Antioquia's mining belt and the coffee region's agricultural logistics corridors, where cooperative buying power exceeds individual station distribution networks.
Colombia Commercial Vehicles Lubricants Market Segmentation
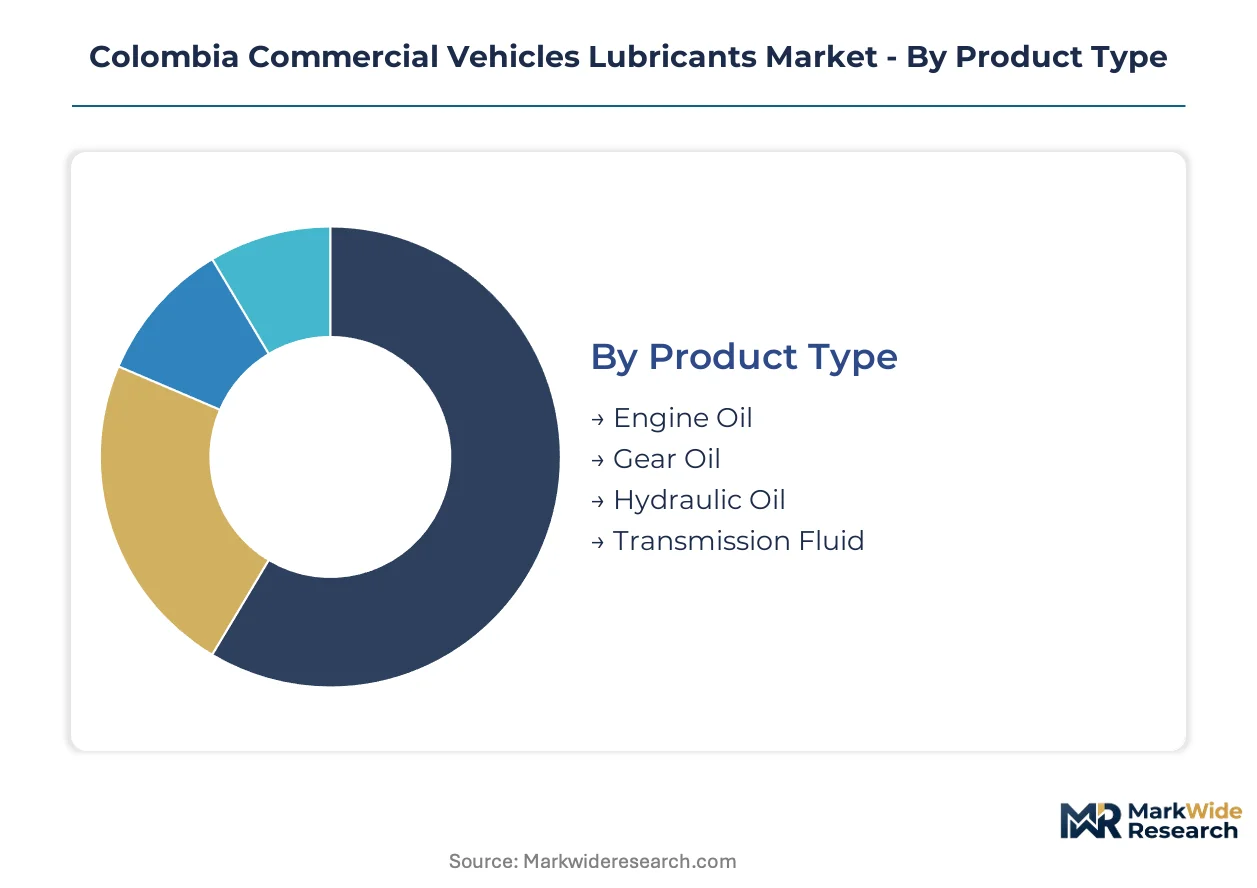
Colombia's commercial vehicle lubricants market fragments across equipment specifications, duty cycles, and procurement structures. Fleet operators in the Andean corridor demand formulations calibrated to high-altitude thermal stress, while mining contractors prioritize hydraulic fluid performance over unit cost.
Product Type:
Cost tier separates commodity mineral bases from premium synthetic formulations with extended drain certifications.
- Engine Oil:Formulations meeting API CK-4 and FA-4 service categories dominate volume consumption across Bogotá-Medellín-Cali trucking corridors. Colombia's Ministry of Mines and Energy biofuel mandates force additive package reformulation for corrosion resistance in ethanol-blended diesel operations.
- Hydraulic Oil:Anti-wear formulations with ISO VG 46 and 68 viscosity grades capture concentrated margin pools in Antioquia and Boyacá mining belts. High-load excavator and haul truck specifications favor zinc-based additive chemistry over ashless alternatives for extreme pressure protection.
- Gear Oil:SAE 80W-90 and 85W-140 multigrade formulations serve differential and final drive applications in legacy heavy-duty fleets.
- Transmission Fluid:Dedicated AMT fluids with synchronized friction modification penetrate urban bus fleets in Cali and Barranquilla as automated manual transmission adoption reduces driver fatigue.
Volume sits with engine oil across the trucking corridor; growth tilts toward transmission fluid as AMT penetration accelerates in municipal bus contracts.
Application:
Geography dictates duty cycle severity and formulation requirements across Colombia's fragmented terrain.
- Heavy-Duty Trucks:Bogotá-Medellín-Cali corridor operators specify low-SAPS synthetic formulations to protect Euro VI-equivalent exhaust aftertreatment systems from premature degradation in high-altitude thermal cycling.
- Buses:Urban transit fleets in Cali and Barranquilla adopt extended drain interval synthetics to minimize depot downtime. Colombia's Ministry of Mines and Energy emissions enforcement drives specification upgrades for SCR system compatibility.
- Light-Duty Trucks:Last-mile delivery operators in peripheral urban centers balance specification compliance against procurement cost pressure from unbranded mineral oil distributors.
- Vans:Small fleet operators and independent contractors in coffee region agricultural logistics corridors favor conventional mineral formulations for pre-2010 vehicle compatibility.
Revenue concentrates in heavy-duty trucks; steepest expansion trajectory belongs to buses as municipal electrification timelines extend diesel fleet utilization.
Service Type:
Customer type determines contract structure and technical attachment intensity.
- Preventive Maintenance:Large transport cooperatives negotiate annual volume contracts with oil analysis laboratory access and drain interval warranty support unavailable through retail fuel-station channels.
- Routine Checkups:Independent garages in secondary cities perform specification-compliant services for mixed-age fleet customers requiring parallel inventory for obsolete viscosity grades.
- Emergency Repairs:Roadside service providers in Amazonian and Pacific regions face technical capacity gaps for condition monitoring infrastructure required by extended drain warranties.
- Specialized Services:Mining contractors in Antioquia demand hydraulic system flushing and contamination control protocols for high-value equipment uptime guarantees.
Margin pools concentrate in preventive maintenance; volume expansion tracks emergency repairs as rural fleet penetration outpaces service infrastructure.
End User:
Procurement scale separates direct formulator negotiations from fragmented retail purchasing.
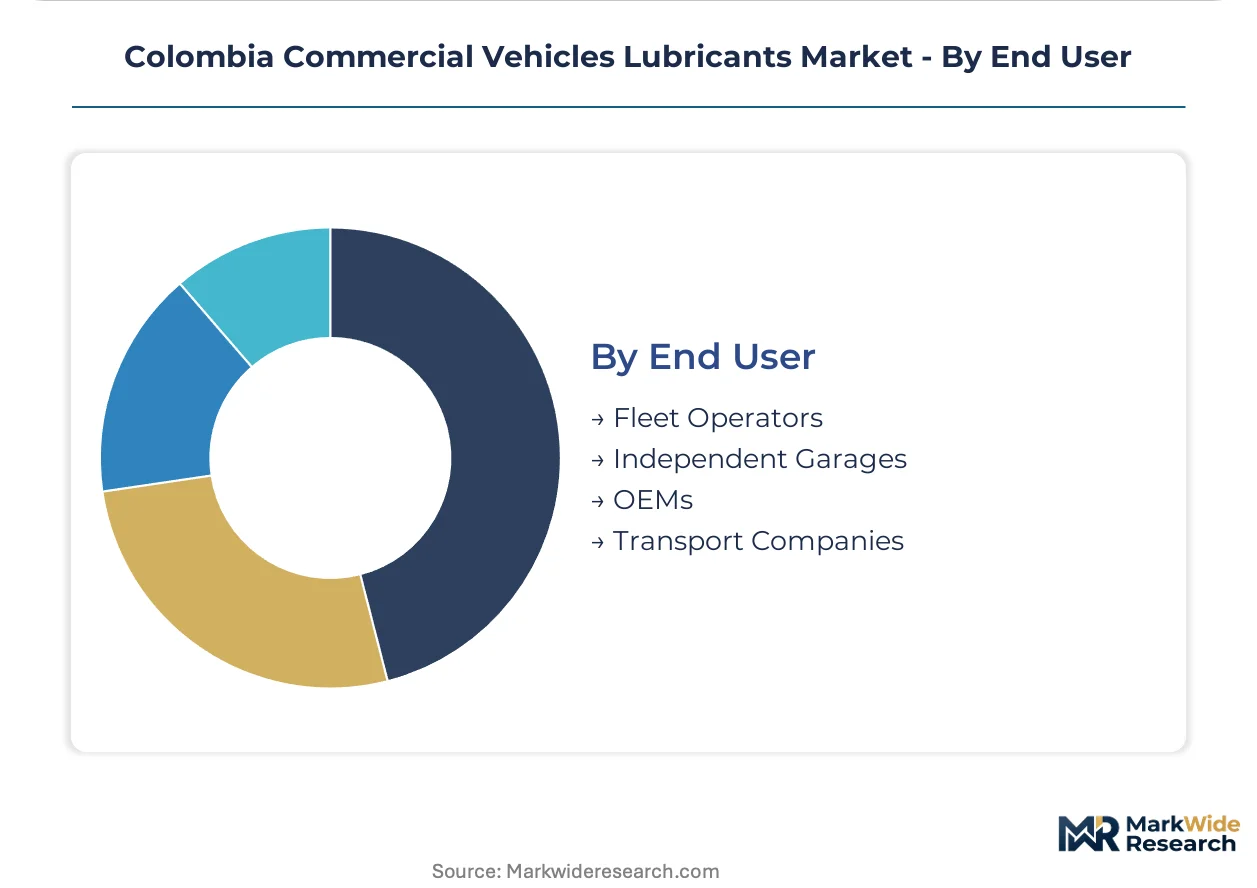
- Fleet Operators:Consolidated buying power in transport cooperatives exceeds individual fuel-station distribution networks, securing price stability and dedicated technical service attachments.
- Transport Companies:Long-haul specialists prioritize total cost of ownership calculations over unit price, driving synthetic formulation adoption for reduced downtime in temperature-stressed Andean operations.
- Independent Garages:Peripheral urban centers face commodity lubricant price compression from unbranded mineral oil distributors undercutting certified products.
- OEMs:Factory-fill specifications and warranty requirements lock in approved supplier relationships for first-fill and service-fill lubricant categories.
Procurement volume concentrates with fleet operators; specification authority is shifting toward OEMs as factory-fill requirements extend into aftermarket service intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bogotá-Medellín-Cali Andean corridor concentrates Colombia's commercial vehicle lubricant consumption, with high-altitude thermal stress driving specification requirements across this trucking artery.
Andean Highland Corridor
Heavy-duty truck fleets operating between Bogotá, Medellín, and Cali specify low-SAPS synthetic formulations to protect exhaust aftertreatment systems from thermal cycling degradation. Colombia's Ministry of Mines and Energy enforces progressive biofuel blending mandates that force additive package reformulation for corrosion resistance. Fleet maintenance depots in Bogotá's Fontibón industrial zone anchor technical service capacity for extended drain interval warranties.
Caribbean Coastal Region
Port logistics fleets in Barranquilla and Cartagena prioritize salt-air corrosion protection in lubricant specifications for container handling equipment. The National Institute of Metrology enforces product labeling standards that certified suppliers must navigate for coastal distribution. Urban bus operators in Barranquilla adopt automated manual transmission fluids as municipal contracts upgrade fleet specifications.
Pacific Lowlands
Agricultural logistics corridors in Valle del Cauca drive diesel engine oil consumption for coffee and sugarcane transport fleets. Colombia's environmental licensing authority incentivizes used oil collection infrastructure investments through carbon credit mechanisms. Independent garages in Buenaventura face technical capacity gaps for oil analysis laboratories required by synthetic formulation warranties.
Amazonian and Orinoquia Frontiers
Oil and gas exploration fleets in Meta and Casanare provinces consume hydraulic fluids for drilling equipment under remote service conditions. The Ministry of Mines and Energy regulates fuel quality standards that indirectly shape lubricant additive requirements for exploration vehicles. Roadside service providers in Villavicencio struggle with condition monitoring infrastructure for extended drain interval programs.
Antioquia Mining Belt
Excavator and haul truck operations in Antioquia and Boyacá capture concentrated margin pools for anti-wear hydraulic oil formulations. Colombia's mining regulator enforces equipment uptime standards that favor premium lubricant specifications with contamination control protocols. Mining contractors in Medellín's eastern periphery negotiate direct bulk supply agreements bypassing retail fuel-station networks.
Colombia Commercial Vehicles Lubricants Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation technology and distribution reach, with synthetic-certified suppliers commanding pricing power in temperature-stressed Andean operations while unbranded mineral distributors compress margins in peripheral urban centers. The market structure fragments between multinational formulators with API certification authority and domestic distributors leveraging fuel-station bundling. Three archetypes dominate: technology-led synthetic specialists, network-anchored fuel retailers, and mining-focused hydraulic fluid suppliers. Competitive moves concentrate on direct fleet contracting bypassing retail channels and re-refining infrastructure investments qualifying for carbon credit offsets.
Among multinational formulators, Royal Dutch Shell and BP (Castrol) exemplify the technology-led archetype through synthetic portfolio positioning, while Terpel anchors the network-anchored domestic tier through fuel-station distribution bundling. Chevron Corporation occupies a position bridging premium formulation technology with regional supply chain scale. These three represent distinct strategic postures without implying specific market share claims or operational details beyond their visible industry positioning.
| Leading Market Players |
|---|
| Royal Dutch Shell |
| BP (Castrol) |
| TotalEnergies |
| Chevron Corporation |
| ExxonMobil |
| Terpel |
| Petromil SA |
| Petrobras |
| Motul |
| Others |
Value Chain & Pricing Dynamics
Synthetic-commodity formulation divergence in Colombia's commercial vehicle lubricants market manifests through extended drain interval warranties commanding premium positioning against mineral-based spot purchases, with this bifurcation feeding directly into import-dependent supply configurations and fuel-station bundling economics.
Pricing Analysis
Total cost of ownership calculations anchor value-based pricing for Bogotá-Medellín-Cali corridor fleet operators prioritizing uptime over unit cost. Pricing stratifies across premium synthetic certifications, standard mineral formulations, and economy unbranded alternatives. Cost compression in commodity tiers intensifies as peripheral urban distributors undercut certified products. Independent garages and small fleet operators exhibit highest price sensitivity; mining contractors and large transport cooperatives demonstrate lowest sensitivity given equipment uptime guarantees.
Supply Chain Analysis
Colombia's domestic content limitations reshape sourcing patterns as formulators lack Group III and PAO synthetic base stock production capacity. Supply draws from US Gulf Coast refineries and Asian petrochemical complexes for premium inputs. Base oil import dependency creates exposure to freight rate volatility and peso-dollar fluctuation. Distribution runs through Terpel's fuel-station network bundling lubricant sales alongside petroleum products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's commercial vehicle lubricants market has become a vertical-integration race as players pursue captive supply of synthetic base stocks to escape import dependency and currency exposure.
For Market Incumbents: Anticipate biofuel mandate acceleration by securing corrosion-resistant additive package R&D partnerships before regulatory timelines compress. Backward integration into re-refining infrastructure captures carbon credit offsets under national climate commitments. Defend against unbranded mineral distributors through direct fleet contracting with oil analysis laboratory attachments. For New Entrants and Emerging Players: Launch via direct bulk supply agreements with Antioquia mining contractors bypassing fuel-station networks. Target hydraulic fluid specifications for excavator and haul truck applications where zinc-based anti-wear chemistry commands margin premiums. Penetrate through technical service bundling unavailable through retail channels. For Investors and Strategic Acquirers: Re-rating potential sits with re-refining specialists given carbon credit monetization under Colombia's environmental licensing authority framework. Long-term viability favors assets with circular economy infrastructure and direct fleet contracting relationships. Monitor biofuel blend rate announcements from the Ministry of Mines and Energy as inflection indicators for additive reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Re-refining | Captures carbon credit offsets under Colombia's environmental licensing authority incentives. |
| Direct Fleet Contracting | Bypasses Terpel's fuel-station bundling to secure volume commitments from transport cooperatives. |
| AMT Fluid Certification Investment | Addresses automated manual transmission penetration in Cali and Barranquilla municipal bus fleets. |
| Biofuel Compatibility Reformulation | Aligns additive packages with Ministry of Mines and Energy ethanol and biodiesel blending mandates. |
| Oil Analysis Laboratory Expansion | Supports extended drain interval warranties for synthetic formulations in temperature-stressed Andean operations. |
Study Parameters
Multi-period observation of base oil import volumes, synthetic formulation adoption rates, and fleet procurement contract structures anchored the trend analysis, supplemented by interviews with lubricant formulator technical directors, mining fleet maintenance managers, fuel-station network procurement leads, and Ministry of Mines and Energy regulatory officials. Secondary validation drew from customs trade data, API certification registries, National Institute of Metrology labeling standards, and transport cooperative annual reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Input-output matrices modeled consumption across product type, application severity, service contract structure, and end-user procurement scale dimensions over the projection horizon. CAGRs derived from regression analysis of historical volume trends against fleet expansion forecasts and biofuel mandate implementation schedules. Industry-specific inputs incorporated mining equipment utilization rates and Andean corridor trucking density metrics.
The model assumes a particular technology adoption path; alternative pathways for synthetic base stock domestic production would alter the outlook. Forecasts reflect assumptions regarding biofuel blend rate progression, currency stability, and API certification timeline compression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Automotive Suspension System Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Automotive All Wheel Drive Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market