
 Automotive Electric Vacuum Pump Market | 2026-2036
Automotive Electric Vacuum Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electric Vacuum Pump Market Analysis
The capital-intensity divergence between integrated system suppliers and standalone component makers is collapsing as module consolidation redefines competitive boundaries. Continental AG leverages its brake-system integration capabilities to bundle electric vacuum pumps with ESC modules. Robert Bosch GmbH sustains R&D intensity across 12V and 48V architectures. Denso Corporation anchors its position through captive supply to Toyota and Lexus hybrid platforms.
An automotive electric vacuum pump is an electromechanical device that generates negative pressure for brake boosters, HVAC controls, and emission management systems, typically operating at 12V to 48V with flow rates between 20 and 80 liters per minute depending on vehicle class. The unit replaces engine-driven mechanical pumps in hybrid and electric vehicles where internal combustion operation is intermittent or absent. Multi-stage diaphragm configurations lead the product type landscape due to superior energy efficiency and noise suppression in passenger EVs. The OEM channel dominates end-user value capture, though aftermarket retrofit demand is accelerating as aging hybrid fleets require component replacement outside warranty periods.
The EPA, NHTSA, and EU Green Deal collectively mandate reduced auxiliary power draw and electrification of vehicle subsystems, directly expanding addressable demand for electric vacuum pumps. ISO 26262 functional-safety requirements shape product development roadmaps as suppliers integrate ASIL-rated motor controls. Stakeholders must monitor 48V mild-hybrid proliferation and solid-state brake booster displacement timelines to calibrate capacity commitments and partnership strategies.
Market Dynamics
Module consolidation is collapsing the boundary between integrated brake-system suppliers and standalone electric vacuum pump manufacturers, forcing component makers to develop ESC-compatible architectures or exit the OEM channel entirely.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants mandates electrification of vehicle auxiliary systems, expanding retrofit and factory-fit demand for electric vacuum pumps in HVAC and brake applications.
- Hybrid powertrain proliferation:Toyota and Lexus hybrid platforms operate internal combustion engines intermittently, requiring on-demand vacuum generation that mechanical pumps cannot provide during electric-only operation.
- 48V mild-hybrid architectures:The voltage class supports higher-flow electric vacuum pumps without full high-voltage electrification, opening a cost-optimized pathway for mass-market passenger vehicles.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese export markets compress motor manufacturing margins and destabilize long-term supply agreements.
- Supplier concentration in East Asia:Diaphragm material specialists and precision motor winding capacity cluster in China and South Korea, creating single-source vulnerability for Western Tier-1 integrators.
- Solid-state brake booster substitution:Continental and Bosch are developing electromechanical brake systems that eliminate vacuum dependency entirely, threatening the addressable market for electric vacuum pumps in premium segments.
Strategic Opportunities
- India two-wheeler electrification:The country's PLI scheme for automotive components incentivizes local electric vacuum pump production for emerging electric scooter brake boosters and cabin pressure management.
- Commercial vehicle idle-reduction mandates:EPA SmartWay certification and EU CO2 standards for heavy-duty trucks create demand for electric auxiliary systems that maintain brake readiness during engine-off periods.
- Aftermarket hybrid fleet aging:First-generation Toyota Prius and Honda Insight vehicles exiting warranty coverage generate replacement demand for brake booster vacuum pumps outside OEM service networks.
Industry Challenges
- ISO 26262 ASIL-D certification timelines:Functional safety validation for motor control electronics extends product development cycles and requires specialized automotive software engineering talent.
- Legacy 12V electrical architecture integration:Electric vacuum pumps must coexist with aging vehicle network protocols and power distribution systems without triggering false fault codes in diagnostic modules.
- Diaphragm material qualification:Fluorocarbon elastomer suppliers face extended automotive OEM validation periods for new compound formulations, delaying cost-reduction initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric Vacuum Pump Market |
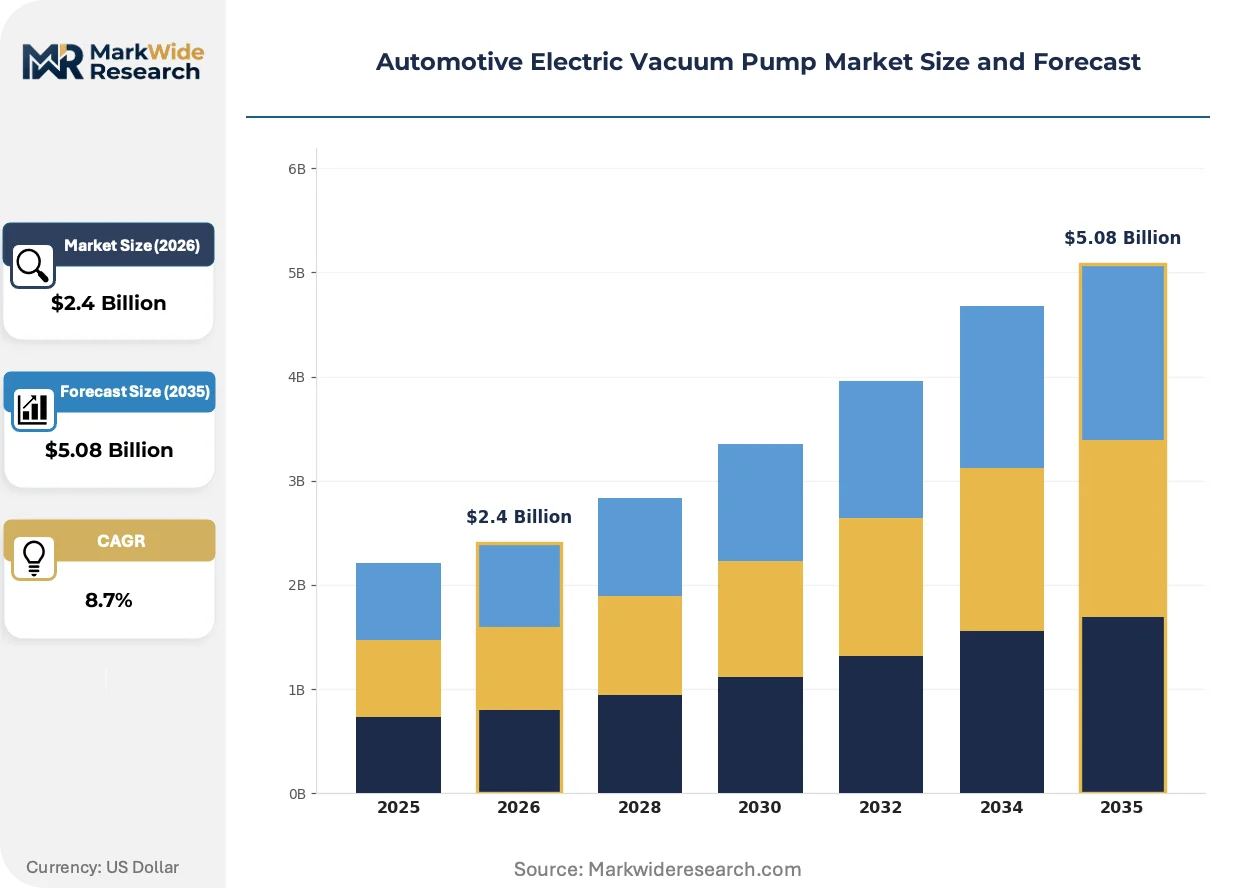
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multi Stage, Gear Driven, Diaphragm End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation: Integrated, Standalone, Bolt-On, Retrofit Power Rating: 12V, 24V, 48V, 60V |
| Companies Covered | Continental AG, Robert Bosch GmbH, HELLA GmbH & Co. KGaA, Rheinmetall Automotive AG, Johnson Electric, Valeo SA, Denso Corporation, Ningbo Tuopu Group, Youngshin Precision Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric Vacuum Pump Market Emerging Trajectories
Electrification of auxiliary systems is fragmenting the competitive landscape between dedicated component suppliers and full-system integrators, with technology choices increasingly dictated by brake architecture roadmaps rather than standalone pump optimization.
Multi-stage diaphragm electric vacuum pump technology is bifurcating the product landscape. The configuration delivers superior energy efficiency and acoustic performance for passenger EVs. Premium OEMs in Germany and California are specifying these units for luxury electric sedans. The technology is bifurcating procurement patterns as buyers separate noise-sensitive passenger applications from cost-driven commercial vehicle segments.
EPA vehicle emissions standards and the EU Green Deal are tightening auxiliary power draw limits simultaneously. These frameworks force suppliers to demonstrate watt-per-liter efficiency gains in regulatory filings. Brake booster applications face the most stringent scrutiny, driving motor control algorithm development toward predictive load sensing rather than constant-speed operation.
Fleet procurement managers are consolidating brake system sourcing decisions at the platform level rather than component level. This behavior compresses the supplier base and elevates system integrators over standalone pump manufacturers. The shift is most visible in North American commercial vehicle procurement, where Volvo and Daimler specify vacuum generation as part of integrated brake module contracts.
Automotive Electric Vacuum Pump Market Segmentation
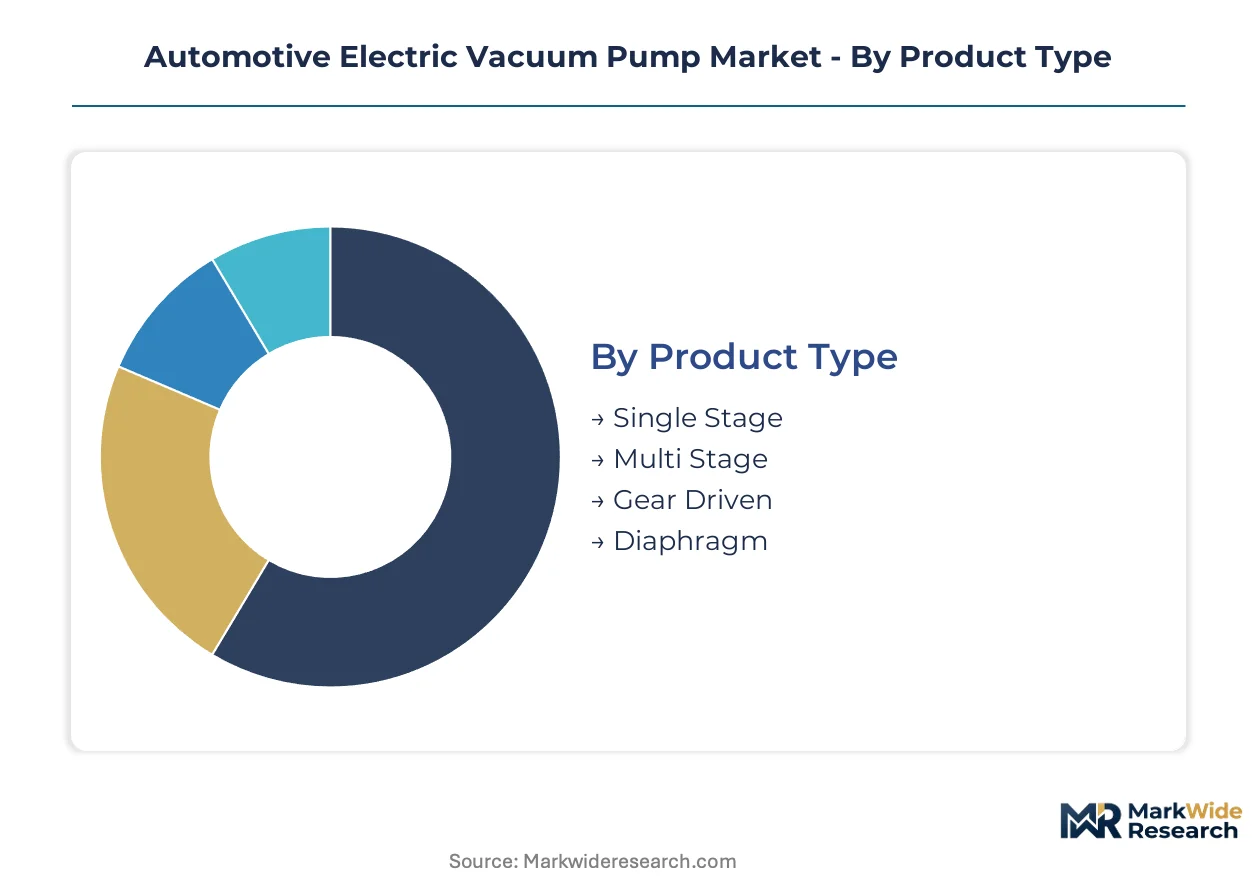
Segmentation reveals how electric vacuum pump procurement diverges between integrated brake system contracts and standalone component orders. Technology choices, voltage architectures, and channel strategies vary sharply across passenger EVs, commercial vehicles, and aftermarket retrofit applications.
Product Type:
Single-stage units dominate domestic assembly in Germany and the United States for cost-sensitive fleet vehicles, while multi-stage configurations anchor export-led supply to premium OEMs in Japan and South Korea.
- Single Stage:These pumps operate with one compression chamber, delivering flow rates of 20-40 liters per minute suitable for compact passenger vehicles. Demand concentrates in North American light-duty truck brake boosters where 12V electrical systems remain standard and cost optimization overrides acoustic performance targets.
- Multi Stage:Sequential diaphragm chambers generate higher vacuum levels with reduced energy consumption and noise output. German and Japanese luxury EV manufacturers specify these units for cabin-quietness compliance, driving export volume from Tier-1 suppliers with captive diaphragm material partnerships.
- Gear Driven:Positive displacement rotary mechanisms suit commercial vehicle applications requiring continuous duty cycles.
- Diaphragm:Oscillating membrane designs dominate hybrid vehicle installations for their tolerance of intermittent operation.
Multi-stage configurations hold the largest share; momentum sits with diaphragm technology as hybrid platform volumes climb fastest.
End User:
Cost-tier stratification separates platform-level brake system integrators from component distributors serving price-sensitive retrofit demand.
- OEMs:Vehicle manufacturers specify electric vacuum pumps as part of consolidated brake module contracts, locking in multi-year supply agreements with ASIL-D certified suppliers. German and Chinese OEMs drive the highest specification density for 48V architectures.
- Aftermarket Providers:Independent distributors serve aging hybrid fleets exiting warranty coverage, particularly first-generation Toyota and Honda vehicles in California and the northeastern United States where state inspection requirements mandate brake system functionality.
- Tier-1 Suppliers:System integrators bundle vacuum generation with ESC modules for just-in-time delivery to assembly plants.
- Vehicle Assemblers:Contract manufacturers in emerging markets source standalone units for localized EV production.
OEM channel concentration is deepest; aftermarket providers are expanding most quickly as hybrid fleet age accelerates replacement demand.
Installation:
Volume distribution skews toward integrated architectures in high-volume passenger platforms while standalone and retrofit segments serve niche applications.
- Integrated:Vacuum generation embedded within brake booster housings reduces packaging volume and wiring complexity. Continental and Bosch specify this approach for European premium platforms where space constraints and weight reduction targets dominate design criteria.
- Standalone:Self-contained units with dedicated mounting brackets serve commercial vehicle upfitters and specialty vehicle manufacturers requiring modular subsystem replacement.
- Bolt-On:Standardized flange interfaces enable rapid assembly line installation without custom tooling.
- Retrofit:Conversion kits adapt mechanical vacuum systems to electric operation for engine-swapped classic vehicles and aftermarket EV conversions.
Integrated installations command the greatest volume; retrofit applications are gaining share fastest within specialty vehicle and classic EV conversion niches.
Power Rating:
Supply concentration for motor winding capacity and magnet materials shapes which voltage classes achieve cost parity across manufacturing geographies.
- 12V:Legacy electrical architecture compatibility preserves this segment's dominance in internal combustion and mild-hybrid vehicles. North American and European mass-market platforms specify 12V pumps to avoid electrical system redesign costs, though flow rate limitations constrain brake booster sizing.
- 48V:Mild-hybrid voltage class enables higher motor speeds and flow rates without full high-voltage electrification expense. Chinese and German OEMs are expanding 48V architecture deployment across C-segment and D-segment passenger vehicles, driving motor control semiconductor demand.
- 24V:Commercial vehicle electrical standards support heavier-duty vacuum generation for truck brake boosters.
- 60V:Specialized industrial and heavy-duty applications outside mainstream automotive deployment.
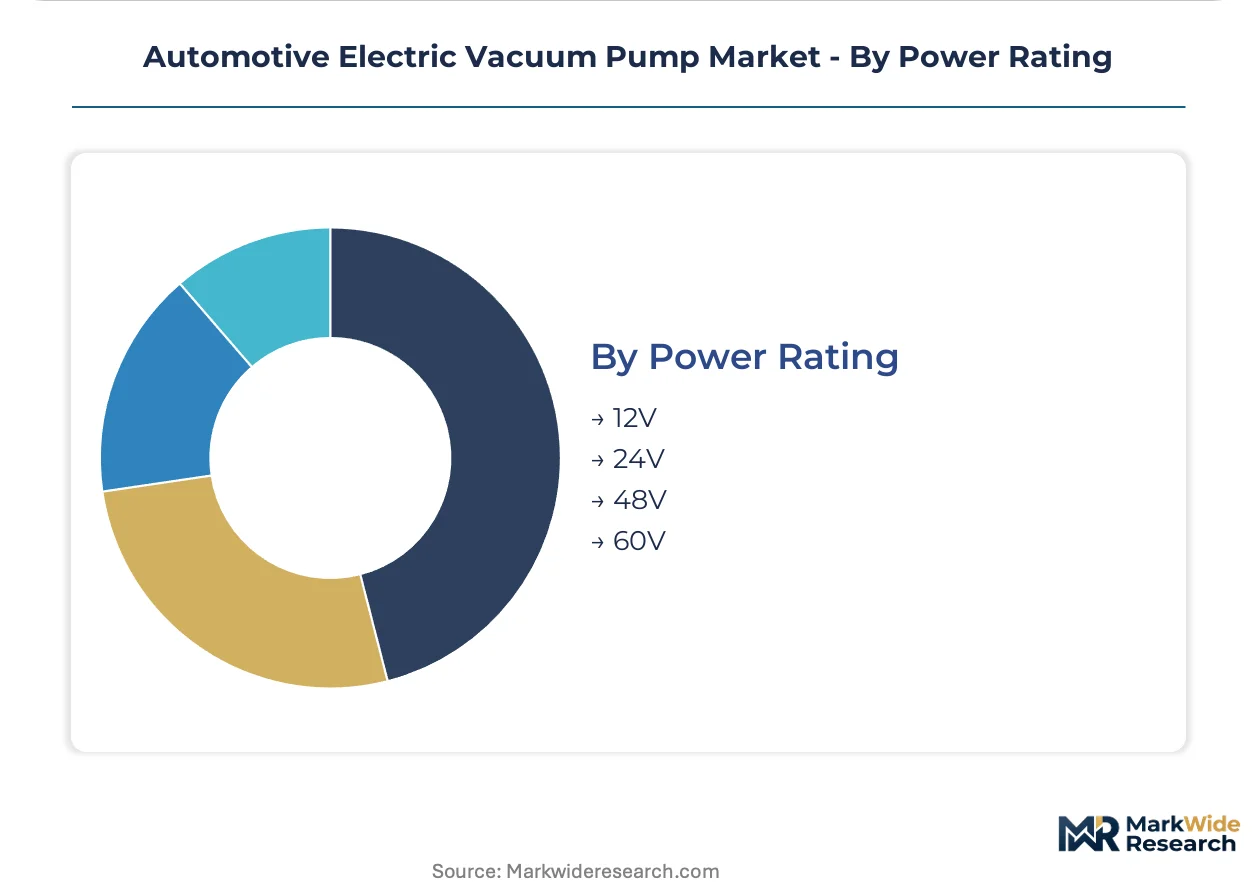
12V ratings retain the largest installed base; 48V architectures are climbing the fastest as mild-hybrid production scales across German and Chinese assembly plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German system integrators commanding premium platform contracts, while Chinese component suppliers capture volume through 48V mild-hybrid scale deployment. This asymmetry shapes regional investment flows and partnership hierarchies across the value chain.
United States
EPA SmartWay certification and NHTSA idle-reduction mandates drive commercial vehicle demand for engine-off brake readiness. The IRA's clean vehicle tax credits accelerate hybrid platform production in Michigan and Tennessee assembly corridors. Detroit-based brake module integrators specify 12V electric vacuum pumps for light-duty truck platforms where cost optimization overrides acoustic targets.
Germany
KBA type-approval requirements and EU F-Gas Regulation enforcement position the country as the regulatory benchmark for auxiliary system electrification. Stuttgart and Munich anchor premium OEM specification activity where multi-stage diaphragm configurations meet cabin-quietness compliance. Continental and Bosch leverage captive ESC integration capabilities to bundle vacuum generation within consolidated brake module contracts.
China
MIIT new energy vehicle mandates and dual carbon goals propel 48V mild-hybrid architecture deployment across C-segment and D-segment passenger vehicles. Yangtze River Delta manufacturing clusters concentrate diaphragm material specialists and precision motor winding capacity. Ningbo and Shanghai house Tier-1 integrators serving BYD, Geely, and SAIC platform requirements with localized supply chain configurations.
Japan
METI carbon neutrality roadmaps and JIS functional-safety standards shape product development timelines for ASIL-rated motor controls. Toyota City and Nagoya anchor hybrid platform production where intermittent combustion operation necessitates on-demand vacuum generation. Denso Corporation maintains captive supply relationships for Lexus and Toyota hybrid architectures.
India
PLI scheme incentives for automotive components attract electric vacuum pump production for emerging two-wheeler brake booster applications. Tamil Nadu and Gujarat assembly clusters serve domestic EV manufacturers and export markets simultaneously. BIS certification requirements for motor control electronics extend validation timelines for new market entrants.
Automotive Electric Vacuum Pump Market Vendor Landscape
Concentration sits with integrated brake-system suppliers who bundle vacuum generation within ESC module contracts, compressing the standalone component vendor base. Module consolidation is collapsing competitive boundaries between full-system integrators and dedicated pump manufacturers. Two strategic archetypes dominate: captive suppliers aligned with single OEM platforms, and independent component specialists serving aftermarket retrofit demand. Dominant competitive moves include strategic partnerships for diaphragm material qualification and geographic expansion into 48V mild-hybrid production clusters.
Among German-based system integrators, Continental AG and Robert Bosch GmbH occupy positions exemplifying the consolidated brake-module archetype. Denso Corporation anchors the captive-supply tier through exclusive hybrid platform relationships. Youngshin Precision Co. Ltd. represents the Korean specialist segment focused on precision motor manufacturing. Ningbo Tuopu Group sits within the Chinese volume-scale tier supplying domestic OEM assembly requirements.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| HELLA GmbH & Co. KGaA |
| Rheinmetall Automotive AG |
| Johnson Electric |
| Valeo SA |
| Denso Corporation |
| Ningbo Tuopu Group |
| Youngshin Precision Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at precision motor winding facilities in Ningbo and Shanghai directly shapes price floors for 12V and 48V architectures, compressing margins for standalone component makers while integrated brake-system suppliers capture premium bundling power through captive ESC module contracts.
Pricing Analysis
The customization-premium spread separates ASIL-D certified multi-stage diaphragm configurations for German luxury OEMs from commodity single-stage units serving North American fleet procurement. Price differentiation rests on ISO 26262 functional-safety certification tier and volume scale, with certified suppliers commanding 40-60% premiums over uncertified competitors. Pricing pressure intensifies from rare earth magnet cost volatility in Chinese export markets, forcing motor manufacturers toward long-term offtake agreements. Aftermarket retrofit distributors exhibit highest price sensitivity due to warranty-expired hybrid fleet budget constraints, while OEM platform engineers prioritize brake-system integration over unit cost.
Supply Chain Analysis
Just-in-time delivery preferences dominate OEM channel procurement, with Tier-1 integrators maintaining 3-5 days of diaphragm material inventory at German and Chinese assembly plants to align with vehicle production schedules. Supply concentrates in China, South Korea, and Germany for precision motor winding, fluorocarbon elastomer compounding, and ASIL-rated semiconductor sourcing. Raw material dependencies include neodymium-dysprosium magnet alloys, high-temperature diaphragm polymers, and automotive-grade motor control ICs. Single-source vulnerability concentrates in East Asian rare earth processing capacity. Distribution runs through consolidated brake module contracts to OEM assembly plants, with aftermarket channels served by independent distributors in California and northeastern United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from aftermarket diagnostic tooling and predictive maintenance subscriptions for aging hybrid fleets expands faster than hardware unit sales, repositioning component suppliers toward recurring-revenue models.
For Market Incumbents: Shield consolidated brake-module positions by deepening captive supply of diaphragm materials through backward integration into fluorocarbon elastomer compounding, and accelerate ASIL-D certification coverage ahead of solid-state brake booster displacement timelines. Priority investment belongs to 48V motor control algorithm development for Chinese and German mild-hybrid platform capture.
For New Entrants and Emerging Players: Anchor in India's two-wheeler electrification corridor under PLI scheme incentives, where BIS certification barriers favor local production partnerships over import competition. Target electric scooter brake booster and cabin pressure management applications with modular 12V standalone units. Go-to-market leverage rests on Tamil Nadu and Gujarat assembly cluster proximity to domestic EV manufacturers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket diagnostic service providers with captive installation networks for hybrid fleet maintenance. Long-term viability favors targets with ISO 26262 software engineering depth and geographic positioning in 48V production clusters. The signal to watch is Continental and Bosch solid-state brake booster development milestones as vacuum pump displacement timeline indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces tooling costs for multi-stage diaphragm configurations across German OEM brake module contracts. |
| Battery Supply Agreement | Secures neodymium magnet allocation from Chinese processors for 48V motor manufacturing scale. |
| Software-Defined Vehicle Investment | Enables predictive load sensing algorithms for EPA auxiliary power draw compliance. |
| Geographic Manufacturing Footprint | Positions assembly capacity in Yangtze River Delta clusters serving BYD and Geely platform requirements. |
| Charging Infrastructure Partnership | Expands aftermarket service network access for hybrid fleet diagnostic and replacement demand capture. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, EPA SmartWay certification filings, and EU F-Gas Regulation implementation records. Interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and motor control semiconductor specialists informed demand-side validation. Bottom-up unit volume estimates triangulated against top-down market value reconstruction across product type, voltage architecture, and installation configuration segments.
Segmentation dimensions modeled include propulsion architecture, vehicle class, content per vehicle, OEM tier positioning, and regional production cluster concentration. CAGRs derived from regression analysis of historical platform deployment rates and regulatory mandate phase-in schedules. Industry-specific forecast inputs incorporate MIIT new energy vehicle mandate trajectories and KBA type-approval specification trends.
Decision-makers should treat outputs as directional under assumptions of sustained 48V mild-hybrid architecture proliferation and stable rare earth export licensing from Chinese processors; material deviation would warrant model refresh. Revision becomes warranted when solid-state brake booster commercialization timelines accelerate or fluorocarbon elastomer qualification periods extend beyond baseline OEM validation cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Wiper Systems Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Automotive Tonneau Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market