
 Harmonic Gearboxes Market | 2026-2036
Harmonic Gearboxes Market Size, Share, and Industry Trends Forecast 2026-2036
Harmonic Gearboxes Market Insights
ISO 9409-1 robot flange compatibility certification is reorganizing supplier eligibility for harmonic gearbox procurement in precision automation. Harmonic Drive LLC leverages its Japanese manufacturing heritage and captive machining capabilities to sustain premium positioning in semiconductor wafer handling systems. Nabtesco Corporation anchors large-format robotic applications through integrated RV and harmonic drive portfolios. Leaderdrive Technologies competes on cost-engineered strain wave variants for domestic Chinese robot OEMs.
Harmonic gearboxes transmit motion through the elastic deformation of a thin-walled flexspline engaged with a rigid circular spline, achieving single-stage reduction ratios exceeding 100:1 in packages under 50 mm diameter. Their zero-backlash characteristic and 30-arc-second repeatability make them indispensable for articulated robot joints, satellite antenna positioning, and CT scanner gantries. Strain wave configurations dominate unit volume across robotics and medical device applications where compact torque density outweighs absolute load capacity. Electromechanical servo-motor pairings capture the fastest expansion as machine builders abandon pneumatic actuation for programmable motion profiles. Semiconductor equipment represents the most concentrated margin pool given cleanroom-rated lubrication and ion-contamination thresholds that limit supplier switching.
FDA 21 CFR Part 820 quality system regulations govern harmonic gearbox integration into Class II medical devices including surgical robots and proton therapy systems. Japan's METI safety standards for collaborative robots and the EU Machinery Directive 2006/42/EC impose functional safety validation on gearbox-integrated joints sold into European automation lines. China's GB/T 12643 robot performance standards further fragment compliance requirements for suppliers serving domestic integrators. Stakeholders must monitor how regional certification divergence affects platform standardization strategies for multinational robot OEMs.
Market Dynamics
ISO 9409-1 flange standard tightening is forcing precision robotics manufacturers to requalify motion control suppliers, compressing the approved vendor list for automotive assembly lines and semiconductor wafer handling equipment.
Growth Catalysts
- Strain wave machining advances:Diamond-coated cutting tools are improving transmission accuracy in flexspline production, enabling tighter tolerances for medical imaging gantries.
- Electromechanical servo pairings:Machine builders are abandoning pneumatic actuation for programmable motion profiles in articulated robot joints, expanding addressable gearbox volume.
- Japan METI collaborative robot standards:Safety certification requirements for human-robot interaction are mandating zero-backlash joints in domestic manufacturing cells.
Market Restraints
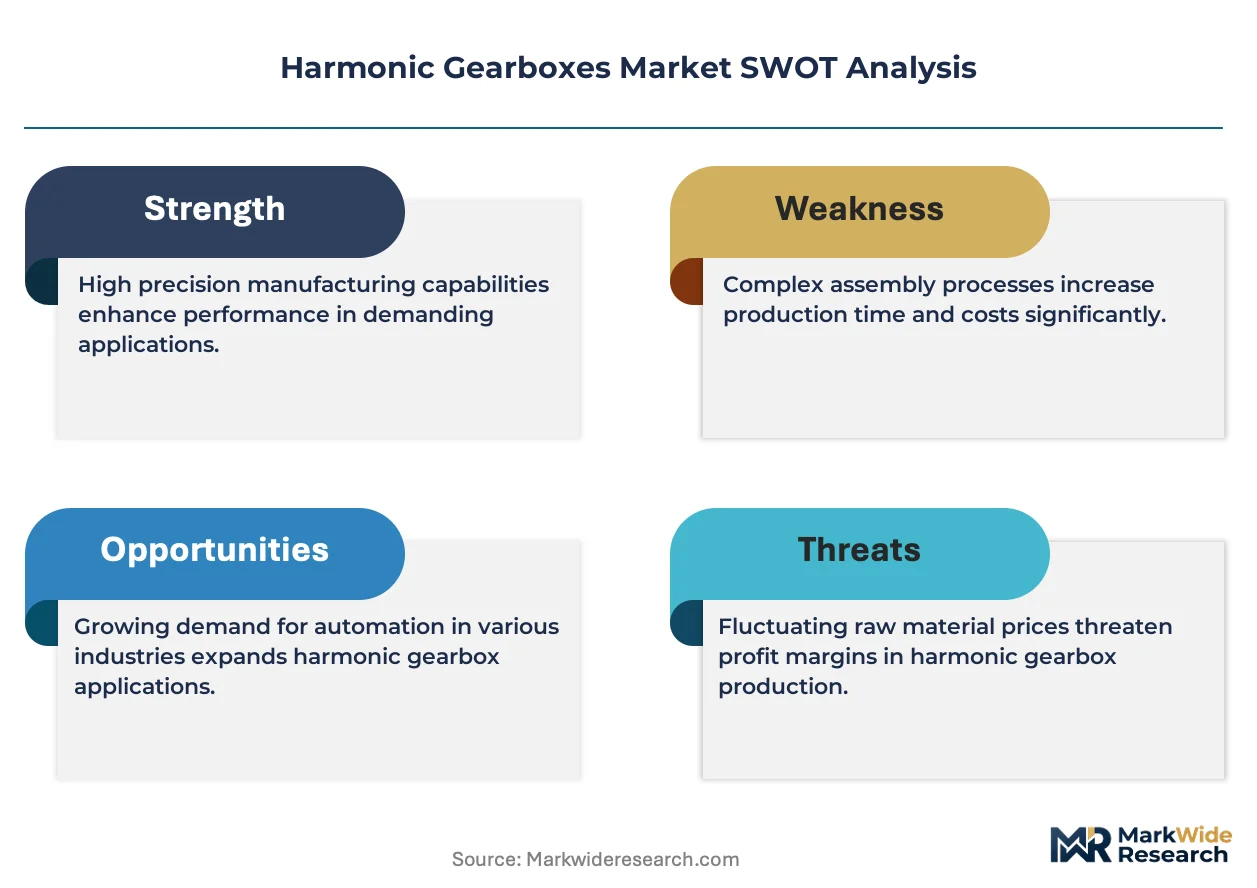
- Specialized alloy input costs:Thin-walled flexspline production requires maraging steel and specialty alloys subject to aerospace-industry demand spikes.
- Supplier geographic concentration:Captive machining capabilities for diamond-tool finishing remain concentrated among Japanese and German precision component houses.
- Load capacity ceiling:Strain wave configurations sacrifice absolute torque density versus planetary alternatives in heavy-payload material handling.
Strategic Opportunities
- Chinese domestic robot OEM expansion:GB/T 12643 performance standard compliance creates procurement windows for cost-engineered strain wave variants serving local integrators.
- Proton therapy system integration:FDA 21 CFR Part 820 quality system requirements for Class II medical devices are expanding cleanroom-rated gearbox demand in radiation oncology equipment.
- Satellite antenna positioning convergence:Miniaturized harmonic drives paired with solid-state power amplifiers are displacing traditional slew drive assemblies in low-earth orbit ground stations.
Industry Challenges
- Functional safety validation timelines:EU Machinery Directive 2006/42/EC compliance documentation for gearbox-integrated joints extends qualification cycles by 8-14 months for European automation lines.
- Cross-platform standardization friction:Divergent regional certification requirements between Japan METI, EU CE marking, and China GB standards fragment R&D allocation for multinational robot OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harmonic Gearboxes Market |
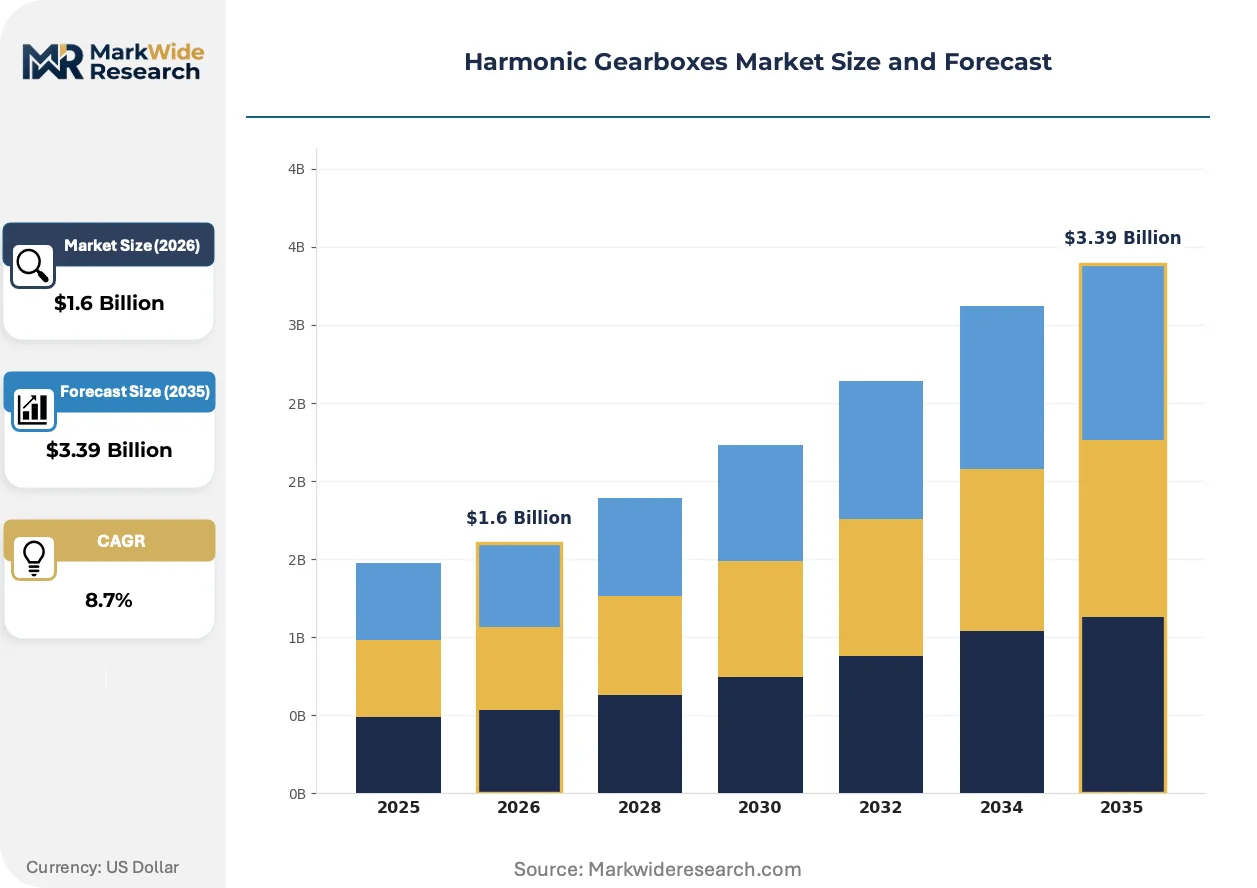
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.39 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strain Wave, Flexspline, Circular Spline, Wave Generator, Harmonic Drive Technology: Electromechanical, Pneumatic, Hydraulic, Servo Motor, Stepper Motor Application: Robotics, Aerospace Systems, Semiconductor Equipment, Medical Devices, Printing Machinery End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Laboratories, Automation Firms |
| Companies Covered | Harmonic Drive LLC, Nabtesco Corporation, Nidec-Shimpo Corporation, Leaderdrive Technologies, Zhejiang Laifual Harmonic, Neugart GmbH, WITTENSTEIN SE, Harmonic Drive SE, Beijing CTKM Harmonic Drive Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harmonic Gearboxes Market Trends and Innovations
Diamond-coated machining processes and electromechanical integration architectures are compressing gearbox form factors while tightening motion control tolerances across robotics and medical equipment.
Thin-walled flexspline geometries fabricated via wire electrical discharge machining are achieving sub-30-arc-second repeatability in packages under 35 mm diameter. Semiconductor wafer handling system manufacturers in South Korea and Germany are specifying these configurations for vacuum-compatible robot joints. Strain wave gear topology is miniaturizing torque density into spaces previously reserved for micro-planetary alternatives.
EU Machinery Directive 2006/42/EC functional safety requirements are mandating validated failure-mode documentation for integrated robot joints sold into European automation lines. Manufacturers must demonstrate mean-time-between-failures calculations for flexspline fatigue under collaborative robot duty cycles. Automotive assembly integrators in Stuttgart and Wolfsburg are prioritizing suppliers with pre-certified safety documentation to compress line qualification schedules.
Robot OEM procurement departments are consolidating supplier relationships around motion control vendors offering integrated encoder-feedback packages. Tier-one automotive manufacturers in Bavaria and Toyota City are specifying single-source accountability for joint-level performance rather than sourcing gearboxes and sensors separately. This bundling preference favors captive machining houses with in-house metrology and assembly capabilities over component specialists.
Harmonic Gearboxes Market Segmentation
Harmonic gearbox procurement channels vary sharply by segment. Strain wave configurations flow through precision component distributors into robot OEMs, while integrated electromechanical packages move via direct sales to semiconductor equipment manufacturers. Understanding these channel dynamics reveals where margin pools concentrate and which segments justify captive machining investments.
Product Type:
Channel mix for product types splits between catalog sales for standard flexsplines and engineered-to-order contracts for complete harmonic drive assemblies.
- Strain Wave:The elastic deformation mechanism achieves single-stage reduction ratios exceeding 100:1 through a thin-walled flexspline engaged with a rigid circular spline. Demand concentrates in articulated robot joints produced by automotive assembly integrators in Stuttgart and Wolfsburg, driven by ISO 9409-1 flange standard tightening that mandates zero-backlash motion control.
- Flexspline:Thin-walled cylindrical components fabricated from maraging steel undergo diamond-coated tool machining to achieve sub-30-arc-second repeatability. Procurement clusters among semiconductor wafer handling system manufacturers in South Korea, constrained by cleanroom-rated lubrication requirements that limit supplier switching.
- Circular Spline:Rigid ring gears with internal teeth provide the stationary engagement surface for strain wave transmission.
- Wave Generator:Elliptical cams with ball bearings induce controlled flexspline deformation to create progressive tooth engagement.
- Harmonic Drive:Integrated assemblies combining all three functional elements into sealed units for direct motor mounting.
Strain Wave dominates installed base. Harmonic Drive is where expansion concentrates.
Technology:
Cost tier stratification separates premium electromechanical pairings from legacy pneumatic actuation in end-use applications.
- Electromechanical:Servo-motor-integrated harmonic drives deliver programmable motion profiles with position feedback. Machine builders in Toyota City and Bavaria specify these configurations for collaborative robot joints, abandoning pneumatic actuation under Japan METI safety standards for human-robot interaction.
- Servo Motor:Closed-loop velocity and torque control enables arc-second positioning accuracy for CT scanner gantries and proton therapy systems. Demand clusters in radiation oncology equipment manufacturing, governed by FDA 21 CFR Part 820 quality system documentation requirements that extend qualification timelines.
- Pneumatic:Compressed air actuation persists in legacy material handling where absolute precision is secondary to cost.
- Hydraulic:Fluid power transmission serves heavy-payload applications exceeding strain wave torque density limits.
- Stepper Motor:Open-loop position control suits low-cost automation where encoder feedback is not mandatory.
Electromechanical captures the steepest expansion trajectory. Pneumatic retains residual volume in cost-constrained segments.
Application:
Volume concentration maps directly to robot density rates in manufacturing clusters and medical device regulatory jurisdictions.
- Robotics:Articulated industrial arms and collaborative robots consume the majority of compact harmonic drive output. Automotive assembly lines in Germany and Japan drive replacement cycles as ISO 9409-1 standards force requalification of motion control suppliers.
- Semiconductor Equipment:Vacuum-compatible robot joints for wafer handling command the most concentrated margin pool. South Korean and German equipment manufacturers specify cleanroom-rated lubrication and ion-contamination thresholds that restrict approved vendor lists.
- Medical Devices:Surgical robots and proton therapy systems require FDA-validated quality systems for Class II device integration.
- Aerospace Systems:Satellite antenna positioning applications demand miniaturized drives with radiation tolerance for low-earth orbit ground stations.
- Printing Machinery:High-speed registration systems utilize harmonic drives for precise paper transport synchronization.
Robotics anchors volume demand. Semiconductor Equipment is where margin expansion concentrates.
End User Industry:
Customer type determines contract structure, with OEMs demanding single-source accountability and aftermarket providers sourcing replacement flexsplines through distribution.
- OEMs:Robot manufacturers and semiconductor equipment builders consolidate procurement around motion control vendors offering integrated encoder-feedback packages. Tier-one automotive manufacturers specify joint-level performance accountability rather than sourcing gearboxes and sensors separately.
- Tier-1 Suppliers:Subsystem integrators for automotive and aerospace programs require certified safety documentation to compress EU Machinery Directive 2006/42/EC qualification schedules.
- Aftermarket Providers:Replacement component distributors serve maintenance cycles for installed industrial robot bases.
- Research Laboratories:Academic and government facilities procure small-batch custom configurations for experimental robotics platforms.
- Automation Firms:System integrators bundle harmonic drives into custom material handling and assembly line solutions.
OEMs dominate primary demand. Tier-1 Suppliers is where procurement consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision automation buyers cluster in manufacturing corridors where robot density rates drive replacement cycles for compact motion control systems. Automotive assembly integrators and semiconductor equipment manufacturers command procurement volumes across three dominant national markets. Regional regulatory divergence fragments supplier qualification requirements.
Germany
Automotive assembly lines in Stuttgart and Wolfsburg drive ISO 9409-1 requalification cycles for zero-backlash joint suppliers. EU Machinery Directive 2006/42/EC functional safety validation extends gearbox-integrated joint documentation timelines by 8-14 months. Bavarian robot OEMs consolidate procurement around vendors offering integrated encoder-feedback packages.
Japan
Collaborative robot manufacturers in Toyota City respond to METI safety standards mandating validated failure-mode documentation for human-robot interaction joints. JIS performance standards govern domestic wafer handling equipment specifications. Nagoya-area precision component houses retain captive diamond-tool finishing capabilities for sub-30-arc-second repeatability.
South Korea
Semiconductor equipment builders in Suwon and Pyeongtaek specify vacuum-compatible harmonic drives with cleanroom-rated lubrication. MFDS-equivalent quality thresholds for medical device integration create procurement windows for validated cleanroom suppliers. Domestic robot OEMs expand strain wave procurement for GB/T 12643-compliant export platforms.
China
Domestic robot manufacturers in Shenzhen and Shanghai source cost-engineered strain wave variants for local integrators. GB/T 12643 robot performance standards fragment compliance requirements versus export-market specifications. Jiangsu and Zhejiang machining clusters develop captive flexspline production for tier-one automotive customers.
United States
Surgical robot manufacturers in Boston and Minneapolis navigate FDA 21 CFR Part 820 quality system documentation for Class II medical device integration. Proton therapy system builders specify cleanroom-rated gearboxes for radiation oncology equipment. Southwest satellite ground station projects miniaturize harmonic drives for low-earth orbit antenna positioning.
Harmonic Gearboxes Market Competitive Landscape
Player mix skews toward Japanese and German heritage manufacturers with captive precision machining capabilities. Supplier concentration remains elevated among diamond-tool finishing specialists serving semiconductor and medical device qualification requirements. Three strategic archetypes dominate: integrated motion control vendors bundling encoder feedback, component specialists supplying catalog flexsplines, and cost-engineered challengers serving price-sensitive domestic OEMs. Competitive moves center on backward integration into flexspline production and geographic expansion through distributor partnerships in emerging automation corridors.
Among Japanese heritage manufacturers, Harmonic Drive LLC and Nabtesco Corporation occupy positions exemplifying the integrated motion control archetype with decades of strain wave transmission heritage. Nidec-Shimpo Corporation represents the precision component specialist tier serving catalog-driven replacement markets. Chinese fabricators including Leaderdrive Technologies and Zhejiang Laifual Harmonic exemplify cost-engineered challengers targeting domestic robot OEM expansion under GB/T 12643 compliance frameworks. German precision houses Neugart GmbH and WITTENSTEIN SE anchor European supply for EU Machinery Directive-validated safety documentation.
| Leading Market Players |
|---|
| Harmonic Drive LLC |
| Nabtesco Corporation |
| Nidec-Shimpo Corporation |
| Leaderdrive Technologies |
| Zhejiang Laifual Harmonic |
| Neugart GmbH |
| WITTENSTEIN SE |
| Harmonic Drive SE |
| Beijing CTKM Harmonic Drive Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Twenty-six-week lead times for diamond-coated tool finishing concentrate pricing power among Nagoya-area and Bavarian captive machining houses serving ISO 9409-1 requalification cycles. Days-of-inventory compression at maraging steel processors amplifies input cost pass-through to flexspline contracts indexed to aerospace alloy benchmarks.
Pricing Analysis
Cost-plus contracts indexed to LME specialty alloy benchmarks dominate procurement for thin-walled flexspline production. Pricing stratifies across semiconductor-grade cleanroom certification, automotive assembly line validation, and standard industrial robot replacement tiers. Cost compression in economy-tier strain wave variants intensifies because Chinese domestic OEMs expand captive machining capacity. Tier-one automotive manufacturers in Stuttgart and Wolfsburg exhibit lowest price sensitivity given single-source accountability requirements for joint-level performance validation.
Supply Chain Analysis
Inbound logistics costs from Yokohama port congestion elevate landed costs for Japanese diamond-tool finishing equipment serving German and South Korean robot OEMs. Supply concentrates in Japan, Germany, and China for strain wave gear machining. Raw material dependencies center on maraging steel from specialty alloy foundries, diamond-coated cutting inserts, and cleanroom-rated lubrication formulations. Single-source vulnerability persists for sub-30-arc-second repeatability finishing capabilities. Distribution runs through precision component distributors for catalog flexsplines and direct engineered-to-order contracts for integrated harmonic drive assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Harmonic gearbox demand sits in early-cycle expansion as collaborative robot deployment accelerates under Japan METI safety standards mandating zero-backlash joint validation.
For Market Incumbents: Consolidate backward integration into flexspline production to defend margin position against cost-engineered Chinese challengers. Prioritize captive diamond-tool finishing capacity expansion in Nagoya and Bavaria to compress lead times for ISO 9409-1 requalification windows. Lock in long-term maraging steel offtake agreements before aerospace demand spikes tighten specialty alloy availability. For New Entrants and Emerging Players: Aftermarket service layer gaps in flexspline replacement and field calibration present white-space entry points. Target Chinese domestic robot OEMs in Shenzhen and Shanghai sourcing GB/T 12643-compliant cost-engineered variants below premium-tier pricing. Pursue distributor partnerships with precision component houses lacking in-house metrology capabilities to bypass direct OEM qualification barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized precision machining divisions serving medical device and semiconductor equipment qualifications. Long-term viability hinges on exposure to collaborative robot and surgical robot adoption curves rather than legacy industrial replacement cycles. Watch FDA 21 CFR Part 820 quality system audit pass rates as inflection indicator for cleanroom-rated supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flexspline Production | Captive machining of maraging steel components insulates margin from aerospace alloy demand spikes. |
| Cleanroom Certification Investment | FDA and MFDS-equivalent validation opens proton therapy and surgical robot procurement channels. |
| Integrated Encoder-Feedback Packaging | Single-source joint accountability meets tier-one automotive OEM consolidation preferences in Bavaria. |
| GB/T 12643 Compliance Engineering | Chinese domestic robot OEM expansion creates volume anchors for cost-engineered strain wave variants. |
| Diamond-Coated Tooling Partnership | Sub-30-arc-second repeatability capabilities differentiate suppliers for semiconductor wafer handling systems. |
Research Methodology
The analysis maps strain wave gear configurations, electromechanical servo pairings, and pneumatic legacy systems, each validated through primary interviews with robot OEM procurement directors, semiconductor equipment manufacturing engineers, and medical device quality assurance leads. Secondary validation draws from ISO 9409-1 standard documentation, METI collaborative robot safety filings, FDA 21 CFR Part 820 quality system records, and SEC filings of listed precision component manufacturers. Bottom-up unit demand estimates from end-use applications triangulate against top-down market value assessments.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include product type, technology pairing, application sector, and end-user industry. CAGRs derive from fitted growth curves incorporating robot density replacement cycles, regulatory requalification timelines, and electromechanical adoption substitution rates. Industry-specific inputs capture ISO standard revision schedules and cleanroom certification audit frequencies.
Underlying assumptions cover stable specialty alloy supply conditions and continued collaborative robot safety standard harmonization, with deviation risk concentrated in maraging steel price volatility and cross-regional certification divergence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
Odometer Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
High Level Brake Lamp Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
South Africa Electric Power Steering Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Automotive Surface Coated Brake Market