
 Automotive AHSS Market | 2026-2036
Automotive AHSS Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive AHSS Market Analysis
Multi-source procurement for advanced high-strength steel grades is pivoting toward tighter qualification partnerships with mills capable of consistent tensile performance. ArcelorMittal leverages its integrated R&D pipeline across European and North American melt shops to sustain dual-phase and press-hardenable supply contracts. POSCO anchors Asia-Pacific availability through dedicated automotive service centers in South Korea and China. Nippon Steel Corporation competes on ultra-high-tensile products above 980 MPa, where Japanese OEMs specify proprietary chemistries.
Automotive advanced high-strength steel encompasses micro-alloyed grades achieving yield strengths from 500 MPa to over 1,500 MPa through controlled thermomechanical processing and rapid quenching, primarily serving vehicle mass reduction without sacrificing crashworthiness. Hot stamping dominates structural applications where complex geometries require post-forming strength retention, while cold forming retains cost advantages for less severe chassis components. OEM direct sourcing from Tier-1 suppliers is shifting as automakers specify grade-certified coils earlier in program development, compressing supplier margins but securing supply continuity.
EPA Corporate Average Fuel Economy standards and NHTSA safety ratings jointly compel OEMs to adopt AHSS at escalating rates, with non-compliance triggering fleet-level penalties. EU Green Deal carbon-border adjustments and REACH chemical disclosures add compliance layers for imported coil and coating chemistries. Stakeholders must monitor evolving EPA rulemakings and EU CBAM implementation timelines to anticipate grade-mix shifts and regional capacity investments.
Market Dynamics
OEM pressure to reduce fleet mass while maintaining crashworthiness is compressing supplier qualification timelines and forcing mills to certify grades earlier in vehicle program development cycles.
Growth Catalysts
- EPA CAFE Standards:Fleet-level penalties for non-compliance compel automakers to substitute AHSS for conventional mild steel in body-in-white structures, tightening grade specifications across North American assembly plants.
- Hot Stamping Technology:Post-forming strength retention above 1,500 MPa enables complex structural geometries previously unattainable with cold forming, expanding application scope into A-pillars and roof rails.
- German Stamping Clusters:BMW and Volkswagen concentration around Munich and Wolfsburg creates anchor demand for dual-phase and press-hardenable coil, pulling capacity investment toward Central European melt shops.
Market Restraints
- Nickel and Molybdenum Input Volatility:Alloy surcharges on micro-alloyed grades fluctuate with mining output from Indonesian and Chilean concentrate, destabilizing contract pricing for multi-year vehicle programs.
- Mill Concentration Risk:Three integrated producers control over 70 percent of global ultra-high-tensile capacity above 980 MPa, creating single-source vulnerability for Japanese OEMs specifying proprietary chemistries.
- Aluminum Substitution Threat:Cast and extruded aluminum solutions achieve comparable mass reduction in hood and door applications, displacing AHSS where stamping complexity exceeds cold-forming limits.
Strategic Opportunities
- Indian Passenger Vehicle Light-Weighting:BIS adoption of global crash-test protocols and tightening CAFE-equivalent norms create first-mover advantage for mills establishing domestic automotive service centers.
- Battery Enclosure Applications:Emerging electric vehicle architectures specify 1,180 MPa martensitic grades for underfloor protection, opening volume demand outside traditional body-structure procurement.
- EU CBAM Implementation:Carbon-border adjustments on imported coil incentivize regional melt-shop modernization, rewarding European mills with lower-emission thermomechanical processing routes.
Industry Challenges
- Press-Hardening Die Engineering Shortage:Tooling design for hot-stamped complex geometries requires specialized thermal-mechanical simulation expertise concentrated at Tier-1 suppliers in Germany and Japan.
- REACH Coating Compliance Timeline:ECHA disclosure requirements for hexavalent chromium alternatives in corrosion protection delay new grade qualification by 8-14 months, compressing model-year launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive AHSS Market |
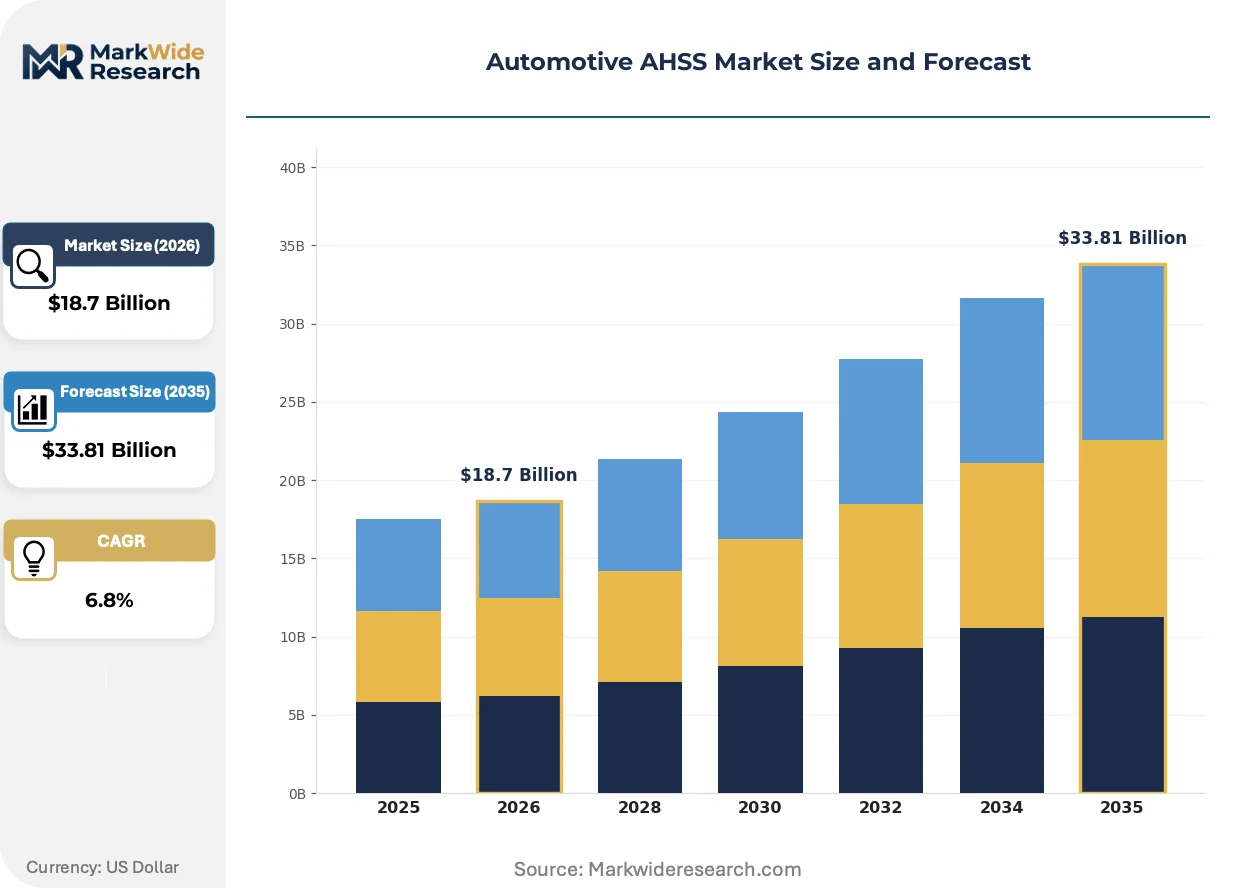
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Stamping, Cold Forming, Galvanized, Coated Application: Body Structure, Chassis, Crash Management, Fuel System End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Manufacturing Stage: Forming, Assembly, Stamping, Finishing |
| Companies Covered | ArcelorMittal, POSCO, Nippon Steel Corporation, Thyssenkrupp AG, Tata Steel, SSAB AB, Cleveland-Cliffs Inc., United States Steel Corporation, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive AHSS Market Emerging Trajectories
Thermomechanical processing advances and regulatory carbon accounting are rewriting how mills compete for automotive supply contracts. Three developments are restructuring competitive advantage.
Third-generation AHSS grades combining high strength with enhanced formability are rewriting the trade-off between crash performance and stamping yield. OEMs in Germany and Japan now specify these grades for floor pan and tunnel reinforcements where complex draws previously required mild steel. The technology is compressing the traditional three-grade vehicle mix into two-grade architectures, reducing logistics complexity but demanding tighter coil-to-coil consistency from mills.
EU Green Deal carbon-border adjustment mechanisms are forcing coil importers to document embedded emissions across mining, melting, and rolling stages. Mills with electric-arc furnace routes and renewable power purchase agreements gain cost advantage over integrated blast-furnace competitors. Japanese and South Korean exporters face particular pressure as their grid carbon intensity exceeds European benchmarks, redirecting investment toward European melt-shop joint ventures.
Direct OEM specification of grade-certified coils is displacing Tier-1 supplier discretion in steel selection. Automakers now mandate mill certificates at program kickoff, compressing Tier-1 margins but securing supply continuity for multi-year production runs. This pattern is most visible in North American truck and SUV platforms where program volumes justify dedicated coil stocking arrangements at stamping plants.
Automotive AHSS Market Segmentation
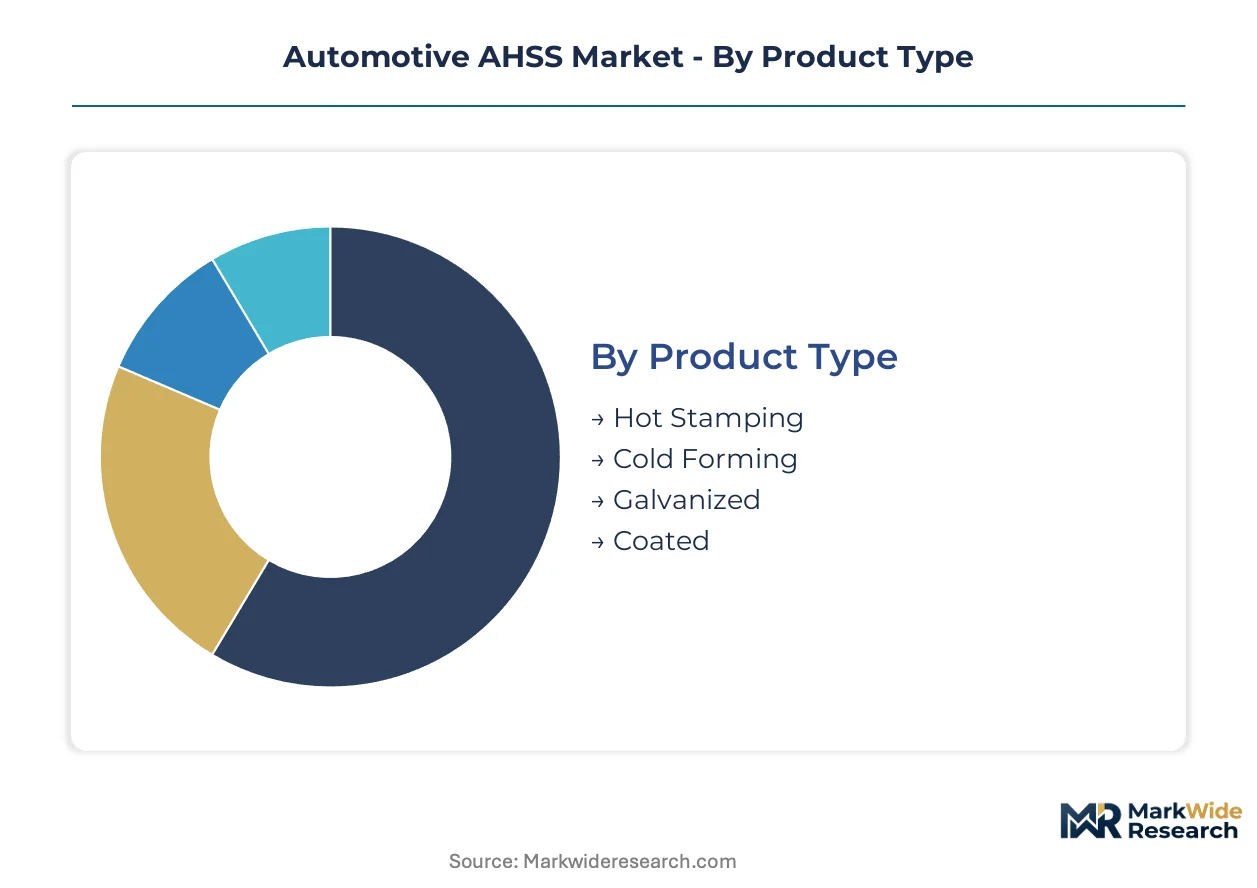
AHSS procurement patterns diverge sharply across processing routes and vehicle integration points. Grade certification requirements from EPA and NHTSA in the United States, alongside EU Green Deal carbon-border adjustments, create distinct compliance burdens that reshape segment economics and supplier qualification timelines.
Product Type:
EPA CAFE compliance documentation and EU CBAM embedded-emissions declarations apply differentially across processing technologies, with hot-stamped grades facing the most intensive thermal-cycle disclosure requirements.
- Hot Stamping:Controlled austenitization followed by die quenching produces martensitic microstructures exceeding 1,500 MPa tensile strength. BMW and Volkswagen stamping facilities around Munich and Wolfsburg anchor European demand, driven by A-pillar and roof rail specifications where post-forming strength retention is non-negotiable.
- Cold Forming:Retained austenite and bainitic ferrite microstructures achieve 500-980 MPa through controlled rolling without thermal processing. North American truck platforms specify these grades for floor pan reinforcements where cost efficiency outweighs extreme strength requirements.
- Galvanized:Zn-Al coating layers provide corrosion protection for exposed underbody components, with REACH-compliant hexavalent chromium alternatives extending qualification timelines by 8-14 months.
- Coated:Organic and metallic surface treatments tailored to specific forming lubricants and weldability requirements, specified by Japanese OEMs for proprietary chemistries above 980 MPa.
Leading the category by volume: Cold Forming. Growing fastest: Hot Stamping.
Application:
Crash-test protocol adoption in India and tightening fuel-economy norms across major automotive markets are redirecting grade mixes toward structural reinforcement applications.
- Body Structure:Floor pans, tunnel reinforcements, and pillar assemblies consume the majority of dual-phase and press-hardenable tonnage. German OEMs specify third-generation AHSS grades here to compress traditional three-grade architectures into two-grade vehicle programs.
- Chassis:Suspension cradles and subframe components balance fatigue resistance with formability. North American assembly plants favor cold-formed grades for these applications where stamping complexity remains moderate.
- Crash Management:Front and rear crush zones engineered for controlled deformation energy absorption. NHTSA safety ratings compel specific strength gradients through these sections.
- Fuel System:Tank bands and protective shields requiring corrosion resistance alongside structural integrity, with aluminum substitution threatening in hood and door adjacent zones.
Body Structure commands the largest share. Battery enclosure applications are expanding fastest outside traditional body-structure procurement.
End User:
Direct OEM specification of grade-certified coils is compressing traditional Tier-1 supplier discretion and reshaping margin distribution across the value chain.
- OEMs:Direct procurement from mills with dedicated coil stocking arrangements at stamping plants, particularly visible in North American truck and SUV platforms where program volumes justify supply continuity investments.
- Tier-1 Suppliers:Stamping specialists facing margin compression as automakers mandate mill certificates at program kickoff, though retaining advantage in press-hardening die engineering concentrated in Germany and Japan.
- Aftermarket Providers:Repair-grade coils for collision replacement, with BIS certification requirements in India creating qualification barriers for non-domestic suppliers.
- Dealerships:Minimal direct involvement, primarily channeling replacement part demand toward certified Tier-1 networks.
OEMs dominate procurement value. Tier-1 Suppliers face the steepest margin pressure.
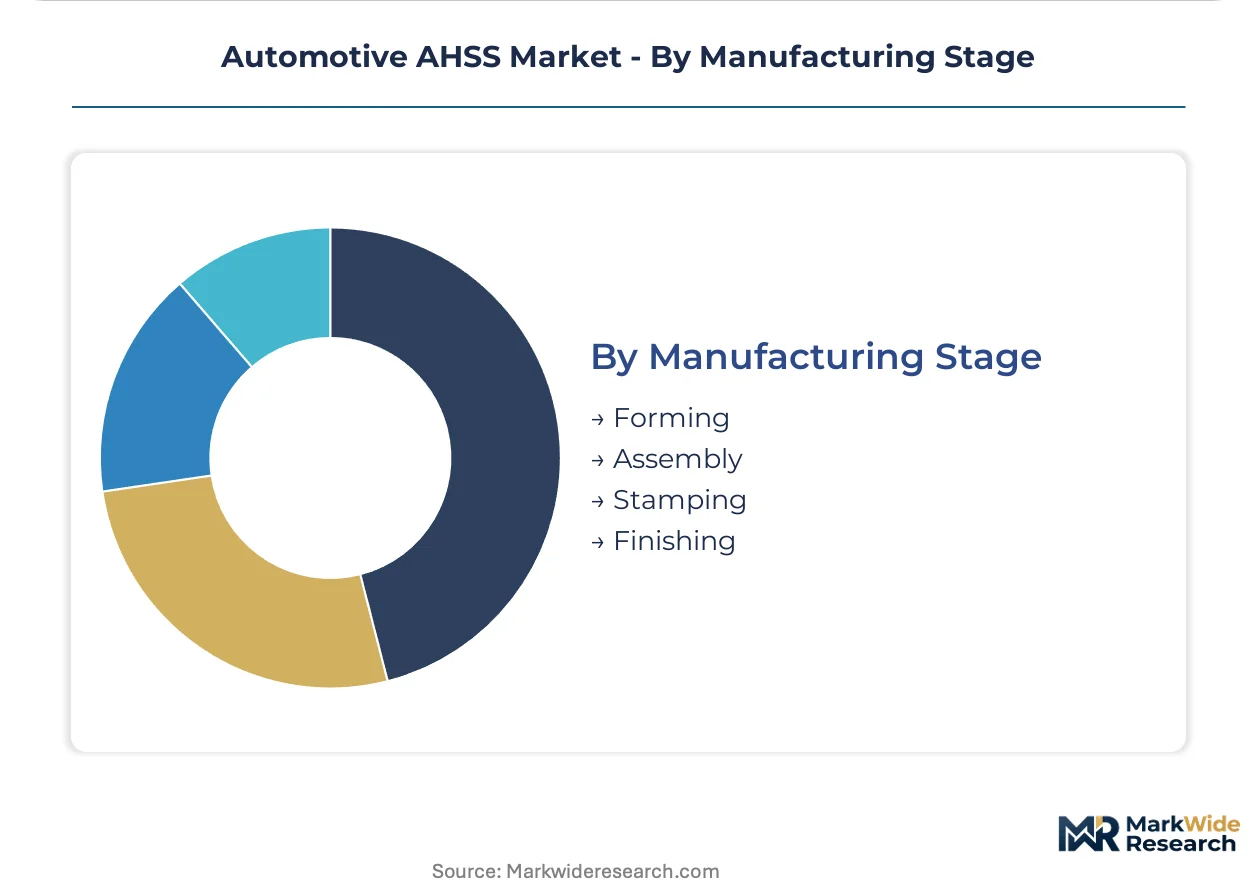
Manufacturing Stage:
Process integration decisions determine whether mills capture value through coil supply alone or extend into downstream services.
- Forming:Hot and cold stamping operations where press-hardening die engineering scarcity concentrates expertise at German and Japanese Tier-1 suppliers.
- Assembly:Welding and joining of AHSS components, with laser welding protocols specified for ultra-high-tensile grades above 980 MPa.
- Stamping:Precision die operations requiring thermal-mechanical simulation expertise for complex geometries in A-pillar and roof rail production.
- Finishing:Surface treatment and corrosion protection stages where ECHA REACH disclosure requirements for coating chemistries delay new grade qualification.
Stamping absorbs the greatest capital investment. Forming offers the highest technical barrier to entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in the Pilbara region of Western Australia and the Mesabi Range in Minnesota anchor the upstream material flows that feed automotive-grade steel production worldwide.
United States
EPA CAFE standards and NHTSA safety ratings compel Detroit automakers to specify dual-phase grades for truck and SUV platforms. Cleveland-Cliffs and U.S. Steel operate integrated mills around the Great Lakes. Michigan stamping plants serve Ford and General Motors assembly lines with dedicated coil stocking arrangements.
Germany
BMW and Volkswagen procurement concentrates in Munich and Wolfsburg clusters. EU Green Deal carbon-border adjustments pressure mills to document embedded emissions across thermomechanical processing. Thyssenkrupp maintains melt-shop capacity in Duisburg to serve press-hardenable demand for A-pillar and roof rail applications.
Japan
Nippon Steel Corporation competes on ultra-high-tensile products above 980 MPa where domestic OEMs specify proprietary chemistries. METI industrial standards shape grade certification timelines. Nagoya and Tokyo Bay industrial corridors concentrate hot-stamping die engineering expertise.
China
MIIT fuel-economy norms and GB standards accelerate AHSS penetration in domestic passenger vehicle platforms. POSCO operates dedicated automotive service centers in Jiangsu and Guangdong provinces. Yangtze River Delta stamping clusters supply SAIC and Geely assembly operations.
South Korea
Hyundai and Kia specification of third-generation grades for body-structure light-weighting drives melt-shop investment. POSCO anchors Asia-Pacific availability through Pohang and Gwangyang facilities. Seoul Capital Area engineering centers coordinate grade qualification with global vehicle program development cycles.
Automotive AHSS Market Vendor Landscape
Capacity expansion dominates the current landscape as mills respond to OEM pressure for certified coil supply earlier in vehicle program development. The vendor base concentrates around integrated producers with captive iron ore and dedicated automotive service center networks. Three strategic archetypes emerge: European blast-furnace operators with R&D pipelines, Asian minimill specialists with electric-arc furnace flexibility, and North American integrated producers with Great Lakes logistics advantages. Competitive moves center on geographic joint ventures and carbon-accounting certification to secure EU CBAM compliance.
Among European integrated producers, ArcelorMittal and Thyssenkrupp AG occupy positions defined by melt-shop integration across multiple jurisdictions. POSCO represents the Asian specialist archetype with dedicated automotive service center infrastructure. Nippon Steel Corporation exemplifies the ultra-high-tensile tier where proprietary chemistry specifications create qualification barriers.
| Leading Market Players |
|---|
| ArcelorMittal |
| POSCO |
| Nippon Steel Corporation |
| Thyssenkrupp AG |
| Tata Steel |
| SSAB AB |
| Cleveland-Cliffs Inc. |
| United States Steel Corporation |
| Nucor Corporation |
| Others |
Supply Flow & Price Mechanics
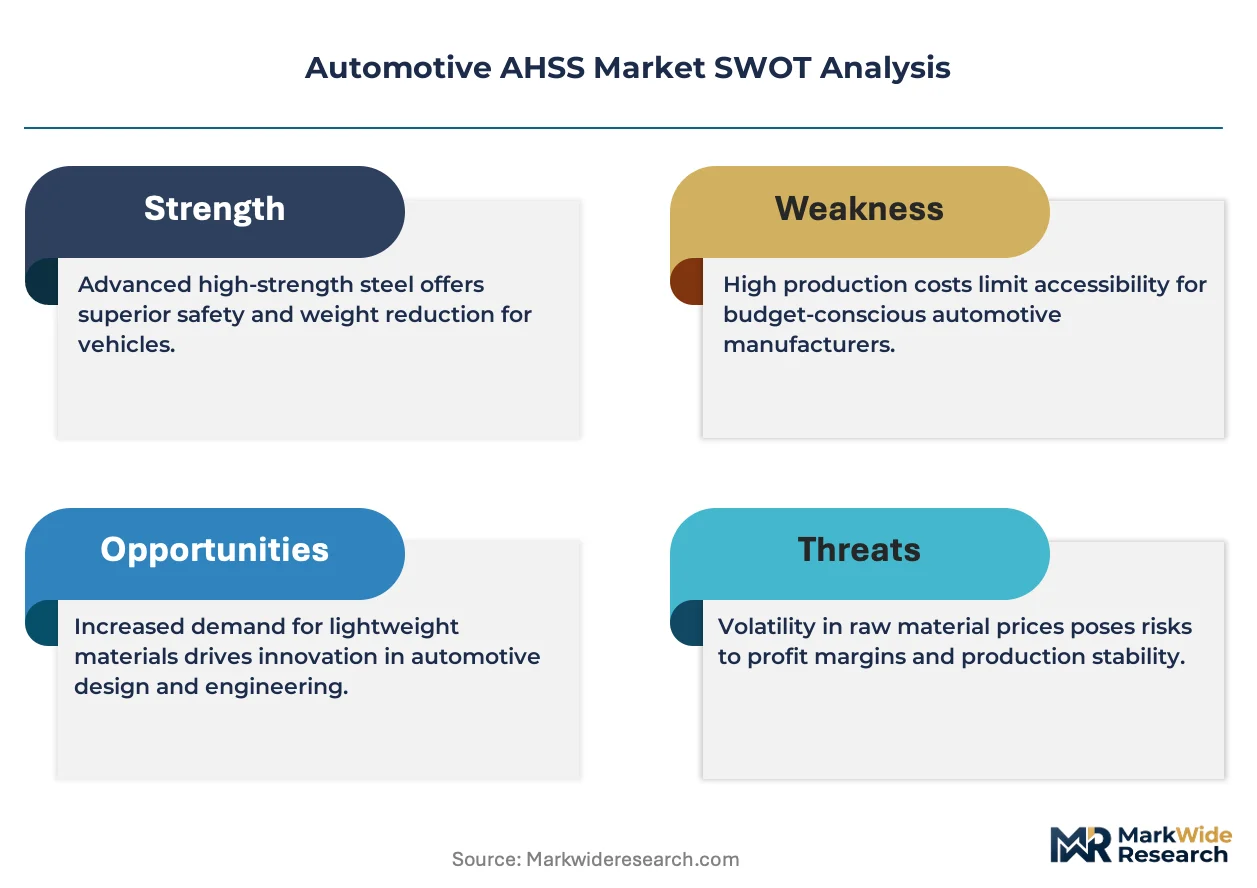
Captive integration of European melt-shop capacity with dedicated automotive service centers anchors both supply security and contract pricing power for ultra-high-tensile grades above 980 MPa. ArcelorMittal and Thyssenkrupp leverage this structure to enforce grade-certified coil premiums while insulating Tier-1 suppliers from nickel and molybdenum surcharge volatility.
Pricing Analysis
Mill-certified coil warranties bundled with thermal-cycle documentation command premiums over unbundled commodity spot purchases. Three-tier pricing structure across automotive-certified, industrial-grade, and spot-market tiers reflects differentiation by tensile certification and REACH coating compliance. Pricing pressure stems from OEM direct-sourcing mandates compressing Tier-1 margins. Aftermarket repair-grade buyers exhibit highest price sensitivity; German OEM procurement teams show lowest sensitivity due to crash-test liability exposure.
Supply Chain Analysis
Nickel and molybdenum supply rests on Indonesian mining concentrate and Chilean byproduct extraction from copper operations. Iron ore draws from Western Australia's Pilbara deposits and Minnesota's Mesabi Range. Blast-furnace coke dependency on Australian coking coal creates tariff-exposure risk. Distribution runs through mill-direct coil stocking arrangements at Munich, Wolfsburg, and Michigan stamping plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-high-tensile capacity concentration above 980 MPa constrains supply elasticity, propping contract pricing for qualified mills. This bottleneck intensifies as Japanese OEMs specify proprietary chemistries with single-source qualification timelines.
For Market Incumbents: Hedge aluminum substitution in hood and door applications by accelerating third-generation AHSS formability R&D. Secure backward integration into nickel concentrate offtake to stabilize alloy surcharge exposure. Prioritize EU CBAM carbon-accounting certification to defend European melt-shop margins against electric-arc furnace competitors.
For New Entrants and Emerging Players: Digital service-center platforms offer route to bypass established mill-direct relationships in India's emerging passenger vehicle market. Target battery enclosure applications for electric vehicle architectures where martensitic grade demand outpaces qualified supply. Pursue joint-venture qualification with German Tier-1 die engineering specialists to compress press-hardening certification timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in electric-arc furnace minimill acquisitions with renewable power purchase agreements. Five-to-ten year viability favors mills with documented embedded-emissions advantages under EU carbon-border adjustments. Watch for EPA CAFE rulemaking acceleration as inflection signal for North American grade-mix shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Ultra-High-Tensile Grades | Thyssenkrupp's Duisburg melt-shop investment addresses BMW and Volkswagen A-pillar demand concentration. |
| Backward Integration into Nickel Concentrate | ArcelorMittal secures Indonesian mining offtake to stabilize alloy surcharge volatility for multi-year programs. |
| EU CBAM Carbon-Accounting Certification | POSCO's European joint ventures document embedded emissions below blast-furnace competitor benchmarks. |
| Long-term Supply Agreement with OEM Direct Sourcing | Cleveland-Cliffs locks Ford truck platform volumes through dedicated Michigan coil stocking arrangements. |
| Joint Venture for Press-Hardening Die Engineering | Tata Steel partners with German Tier-1 specialists to transfer thermal-mechanical simulation expertise. |
Methodological Framework
SEC 10-K filings, EU ETS emissions registries, and IHS Markit vehicle production databases formed the secondary backbone for capacity and procurement pattern analysis. Primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, and automotive service center operations managers validated grade-mix assumptions. Bottom-up coil shipment data triangulated against top-down OEM body-in-white mass-reduction targets across the analysis window.
Historical trendline analysis of AHSS penetration rates by vehicle class established baseline growth coefficients. The modeling framework segmented by processing technology, application integration point, tensile strength tier, and regional production cluster. CAGRs derived from weighted average of OEM program launch volumes and mill capacity expansion announcements. Forecast inputs incorporated EPA CAFE compliance trajectory and EU CBAM implementation pace.
The model holds under steady regulatory enforcement timelines; deviation in EPA rulemaking acceleration or EU carbon-border adjustment scope would shift grade-mix projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
Automotive Screenwash Products Market