
 Autonomous Delivery Robots Market | 2026-2036
Autonomous Delivery Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Delivery Robots Market Intelligence
China is reshaping autonomous delivery robot manufacturing through state-backed pilot corridors and component clustering. Nuro leverages in-house sensor fusion development to sustain technology leadership in suburban parcel transport. Starship Technologies anchors European campus and grocery delivery through dense operational networks across multiple cities. Geek+ dominates Asian warehouse-to-curb logistics with scalable ground-robot architectures.
Autonomous delivery robots are self-navigating vehicles combining lidar, cameras, and GPS with edge-computing processors to execute goods transport without human drivers, typically operating at speeds below 25 km/hour across structured environments. Ground robots occupy the largest deployment base due to lower regulatory barriers and payload adaptability for food and parcel categories, while aerial drones command premium positioning in medical supply chains where speed overrides unit economics. E-commerce platforms represent the deepest end-user margin pool as they integrate captive fleets into fulfillment networks rather than outsourcing to third-party logistics providers.
The US DOT and FAA jointly govern roadway and airspace access for delivery robots, with sidewalk permissions varying across municipal jurisdictions and creating fragmented go-to-market requirements. China's MIIT and SAMR coordinate national standards for autonomous vehicle testing and commercial deployment, accelerating fleet scaling through centralized regulatory pathways. Stakeholders must monitor evolving liability frameworks as operators shift from supervised to fully unmanned service models across multiple geographies.
Market Dynamics
Last-mile labor shortages are compressing fulfillment economics across e-commerce networks, forcing retailers to automate sidewalk and curbside delivery corridors that previously relied on gig-economy drivers.
Growth Catalysts
- Lidar cost deflation:Solid-state sensor architectures are collapsing per-unit navigation costs below the threshold for fleet-scale deployment in food and grocery segments.
- China's MIIT national standards:Centralized testing protocols for autonomous ground vehicles are compressing commercialization timelines across Shenzhen, Beijing, and Shanghai pilot zones.
- Suburban parcel density:Single-family residential patterns with predictable sidewalk infrastructure are creating economically viable robot deployment corridors in US and European markets.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing remains concentrated among East Asian cell manufacturers, exposing fleet operators to input cost volatility and supply allocation constraints.
- FAA Part 135 certification barriers:Aerial drone delivery faces extended airworthiness approval timelines that ground-based competitors bypass through municipal sidewalk permits.
- GPS-denied navigation gaps:Urban canyon environments with signal multipath remain technically challenging for pure satellite-dependent localization systems.
Strategic Opportunities
- Medical supply chain integration:Hospital-to-pharmacy autonomous corridors for temperature-sensitive biologics represent an underpenetrated application with premium unit economics.
- EU AI Act compliance pathways:Proactive alignment with high-risk AI system documentation requirements is creating first-mover positioning for European market access.
- Edge-computing and 5G convergence:Low-latency vehicle-to-infrastructure communication is enabling lighter onboard processing and reduced sensor payload costs.
Industry Challenges
- Autonomous systems engineering talent:The intersection of robotics software, sensor fusion, and safety-critical validation requires specialized skill sets in short supply across labor markets.
- Municipal permitting fragmentation:Sidewalk robot operators face inconsistent local ordinances across US cities, requiring jurisdiction-by-jurisdiction compliance engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Delivery Robots Market |
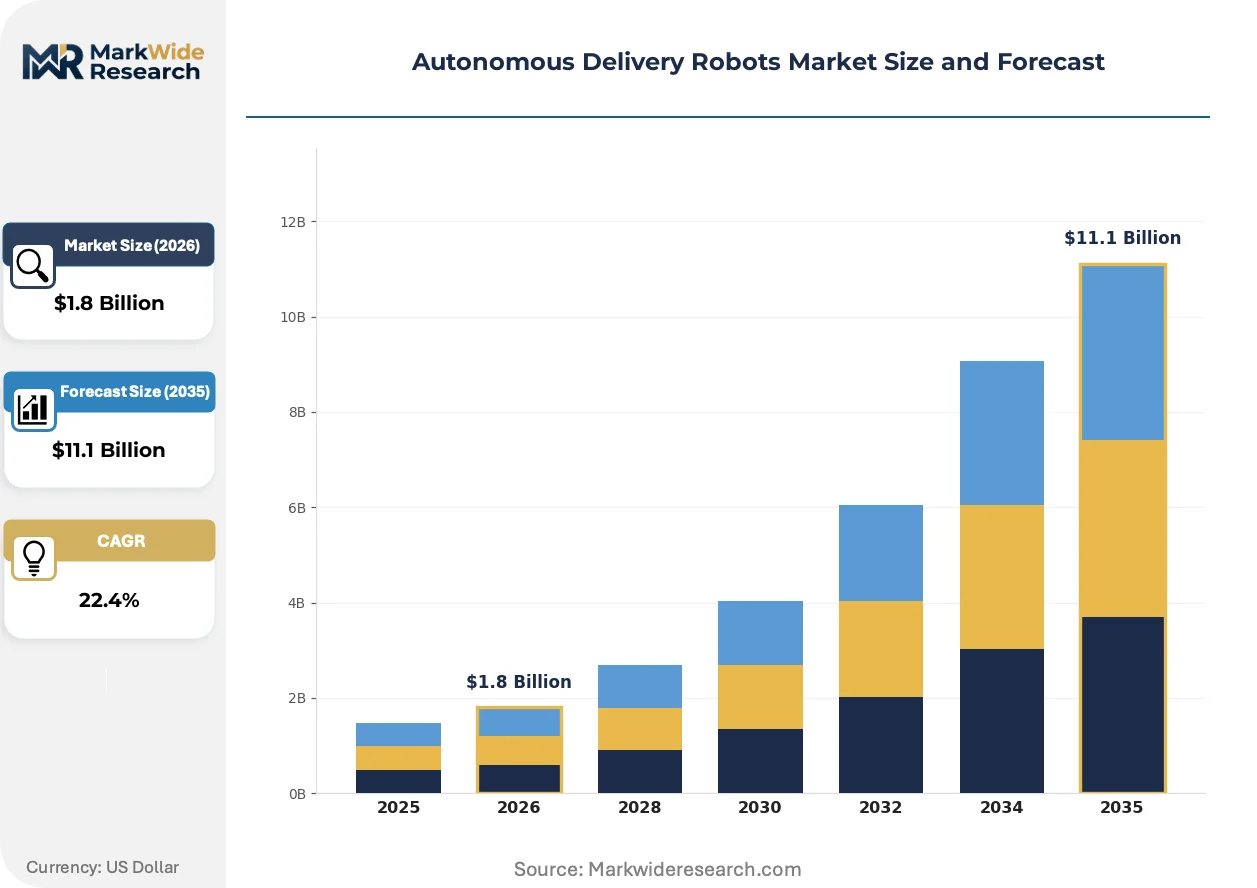
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Ground Robots, Aerial Drones, Underwater Robots, Hybrid Models Deployment Environment: Urban Areas, Suburban Zones, Industrial Complexes, Academic Campuses Application: Food Delivery, Parcel Transport, Medical Supplies, Retail Goods End User: Logistics Providers, E-commerce Platforms, Healthcare Facilities, Hospitality Services |
| Companies Covered | Amazon Scout, Agility Robotics, Starship Technologies, Locus Robotics, Geek+, Nuro, Serve Robotics, Mobile Industrial Robots, Coco Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Delivery Robots Market Strategic Shifts & Innovations
Sensor fusion architectures and regulatory harmonization efforts are converging to expand operational domains beyond controlled campus environments into contested urban traffic and mixed pedestrian corridors.
V4D (4D imaging) radar is rendering obsolete the lidar-dominant sensor stacks that defined first-generation delivery robots. E-commerce fulfillment networks are piloting solid-state radar-camera fusion at scale in Asian and North American corridors. The shift is compressing bill-of-materials costs while extending operational availability through precipitation and dust conditions that degrade optical systems.
China's SAMR commercial deployment guidelines are establishing liability frameworks that shift from supervised to fully unmanned operations. The standards create centralized certification pathways absent in fragmented US municipal governance. Ground-robot manufacturers with MIIT testing credentials are securing preferential access to dense urban pilot zones in Shenzhen and Beijing.
Retailers are consolidating vendor relationships around fleet-management platforms that integrate autonomous delivery into existing order-management systems. Third-party logistics providers are losing share to captive e-commerce fleets as procurement prioritizes control over last-mile data and customer touchpoints. The consolidation is most visible in Chinese and US markets where platform economics favor vertical integration of fulfillment infrastructure.
Autonomous Delivery Robots Market Segmentation
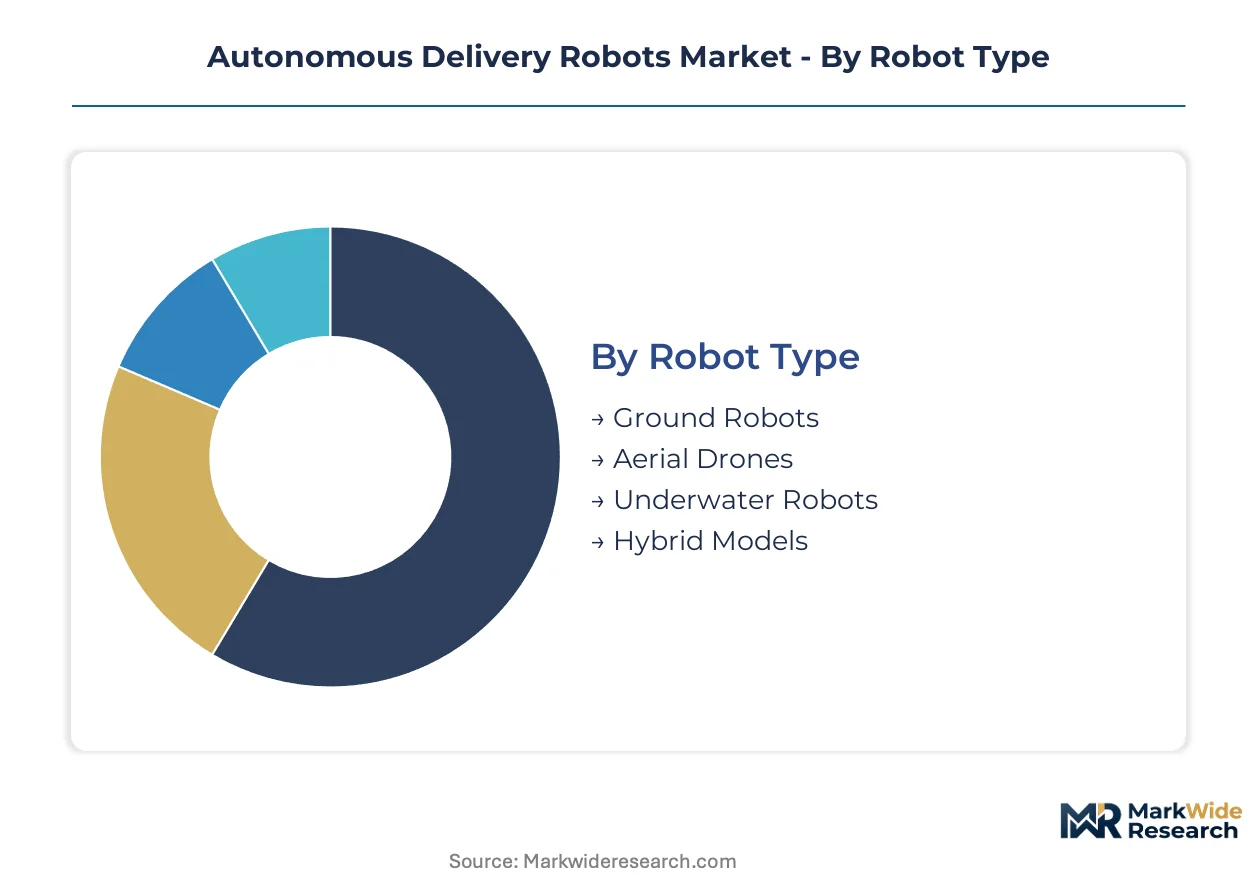
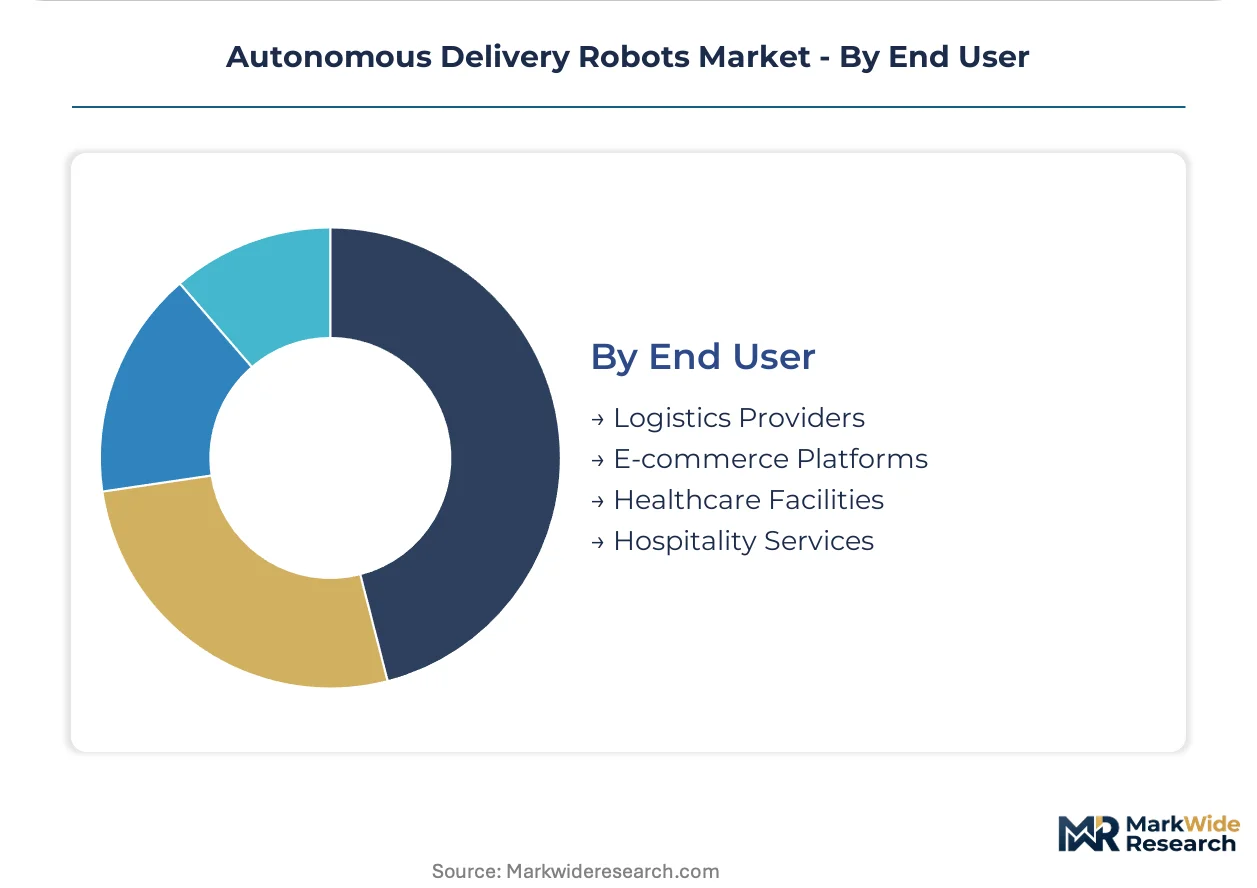
Segmentation in autonomous delivery robots reveals how hardware design, operational terrain, and customer economics interact. Each dimension shapes procurement decisions, regulatory pathways, and fleet deployment economics differently.
Robot Type:
Cost tier separates the four robot architectures, with sensor payload and powertrain complexity driving unit economics across fleet procurement decisions.
- Ground Robots:Wheeled platforms integrate lidar-camera fusion with electric drivetrains rated for 20-25 km/h operation on sidewalks and bike lanes. Demand concentrates in Chinese pilot zones where MIIT certification pathways enable scaled municipal deployment without airspace coordination.
- Aerial Drones:Multirotor systems carry 2-5 kg payloads via GPS-waypoint navigation with BVLOS (beyond visual line of sight) capabilities. FAA Part 135 certification barriers constrain US commercial scaling while medical supply chains in Switzerland and Australia advance through regulator-specific exemptions.
- Underwater Robots:Tethered and autonomous underwater vehicles serve port logistics and marine research with pressure-rated hulls. Coastal infrastructure inspection in Norway and Japan drives niche procurement.
- Hybrid Models:Transforming platforms switch between ground transit and limited aerial hop modes for obstacle traversal. Experimental deployments in Dubai and Singapore test multi-modal corridor integration.
Ground robots hold installed capacity. Aerial drones are rotating up the share rankings.
Deployment Environment:
Application context determines sensor redundancy requirements and regulatory jurisdiction, with pedestrian density and infrastructure predictability shaping go-to-market complexity.
- Urban Areas:High-rise canyons and mixed traffic demand 360-degree perception stacks with V2I communication integration. GPS-denied navigation gaps in downtown Shenzhen and Manhattan limit pure satellite-dependent systems.
- Suburban Zones:Single-family residential patterns with dedicated sidewalks and lower pedestrian density enable lighter sensor configurations. US and European markets concentrate procurement here due to predictable right-of-way access.
- Industrial Complexes:Controlled private environments with standardized loading docks allow reduced safety margins and higher payload-to-weight ratios. Warehouse-to-curb logistics in Chinese manufacturing parks anchor demand.
- Academic Campuses:Closed-loop road networks with centralized facilities management simplify permitting and liability frameworks. Starship Technologies anchors European operations across university corridors in Estonia, UK, and Germany.
Suburban zones capture procurement volume. Industrial complexes are climbing the fastest.
Application:
Margin structure varies sharply across payload categories, with temperature sensitivity and delivery urgency determining pricing power and fleet utilization economics.
- Food Delivery:Insulated compartments with 30-45 minute thermal retention target quick-service restaurant chains. E-commerce platforms in China and South Korea integrate captive fleets to avoid third-party logistics fees.
- Parcel Transport:Standardized container interfaces accommodate variable box dimensions across e-commerce fulfillment networks. US suburban density patterns create economically viable deployment corridors for major retailers.
- Medical Supplies:Cold-chain validation and chain-of-custody documentation serve hospital-to-pharmacy biologics transport. Swissmedic and TGA pathways in Switzerland and Australia enable premium positioning.
- Retail Goods:Same-day grocery and convenience store replenishment competes with gig-economy driver economics. Dense urban pilot zones in Beijing and Shenzhen test scaled deployment.
Parcel transport holds installed capacity. Medical supplies are gaining share fastest.
End User:
Customer type determines fleet ownership models, with vertical integration preferences shaping vendor selection and data control priorities.
- Logistics Providers:Third-party operators face margin compression as e-commerce platforms bring delivery in-house. DHL and FedEx test robot integration in German and US corridors respectively.
- E-commerce Platforms:Captive fleet deployment prioritizes last-mile data ownership and customer touchpoint control. Alibaba and JD.com anchor Chinese procurement with MIIT-certified ground robot networks.
- Healthcare Facilities:Hospital systems demand ISO 13485-adjacent quality systems for specimen and pharmacy logistics. Temperature-sensitive corridors in Switzerland and UAE drive specialized procurement.
- Hospitality Services:Hotels and resorts deploy robots for amenity delivery and guest services in controlled property environments. Dubai and Singapore lead experimental deployment.
E-commerce platforms hold installed capacity. Healthcare facilities are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT and SAMR anchor China's centralized regulatory framework, accelerating fleet deployment through national testing corridors that bypass the municipal fragmentation constraining US operators.
United States
Suburban parcel density and gig-economy labor shortages drive retailer procurement of sidewalk robots. The FAA and DOT jointly govern airspace and roadway access, while municipal permitting varies block-by-block. Amazon Scout and Nuro test in Arizona, California, and Texas corridors with favorable local ordinances.
China
E-commerce platform vertical integration and state-backed pilot zones concentrate demand in ground-robot fleets. MIIT national standards compress commercialization timelines through centralized certification. Shenzhen and Beijing municipal governments deploy dense urban pilot corridors with preferential access for certified manufacturers.
Germany
Campus logistics and industrial warehouse-to-curb applications anchor European demand. KBA and municipal transport authorities coordinate sidewalk robot permits with EU AI Act compliance requirements. Starship Technologies operates across university corridors in Estonia, UK, and Germany with standardized facilities management frameworks.
Switzerland
Medical supply chain integration for temperature-sensitive biologics creates premium positioning opportunities. Swissmedic pathways enable hospital-to-pharmacy autonomous corridors with chain-of-custody documentation. Zurich and Geneva anchor specialized procurement for cold-chain validated transport systems.
Australia
Suburban residential patterns and regulatory openness to aerial drone exemptions attract pilot programs. TGA pathways advance medical supply delivery while municipal councils test ground-robot integration. Sydney and Melbourne concentrate logistics provider experimentation with autonomous last-mile solutions.
Autonomous Delivery Robots Market Key Industry Players
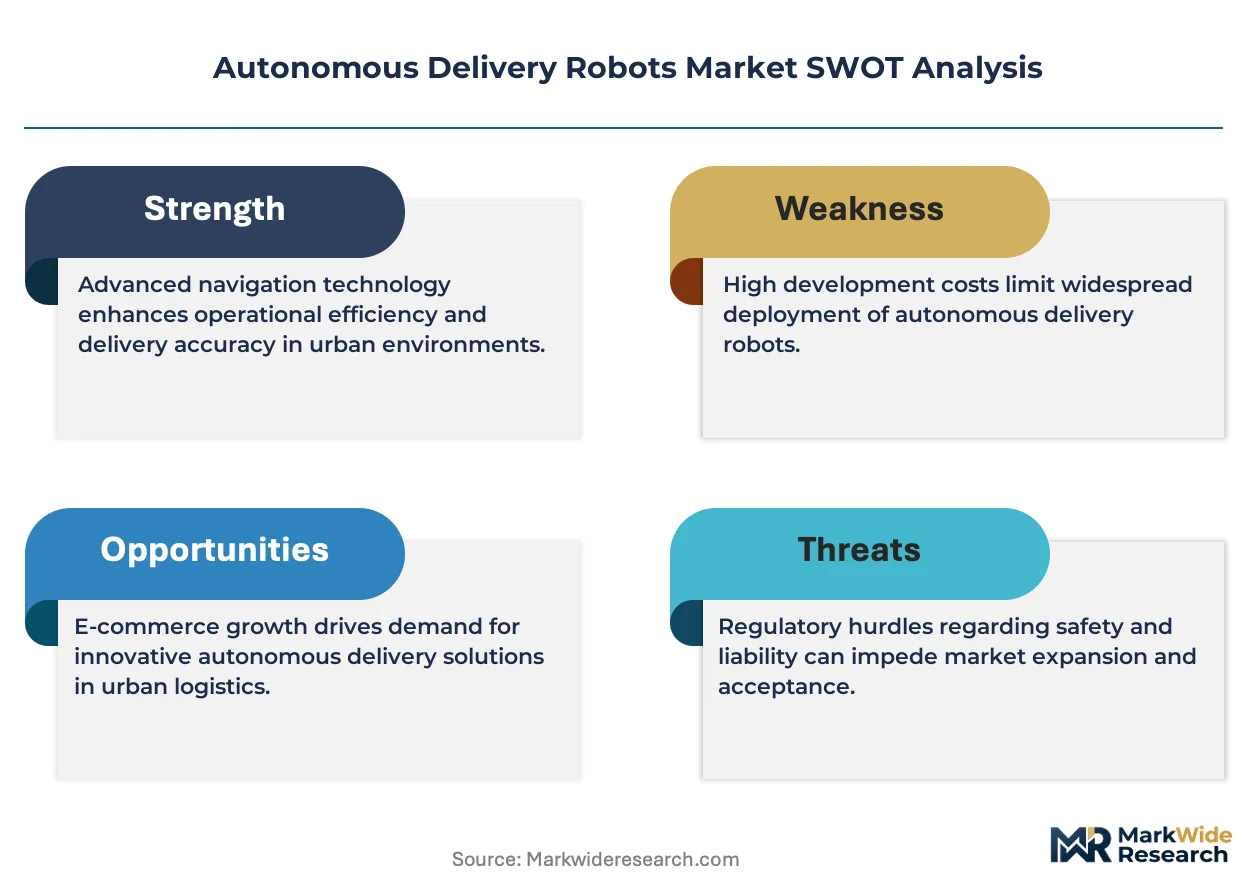
Platform-integrated operators and independent fleet specialists split the market between captive e-commerce networks and third-party logistics contracts. The vendor base organizes around three archetypes: technology developers with in-house sensor fusion, fleet operators with dense municipal permits, and warehouse automation specialists extending into curbside delivery. Consolidation pressures favor vertical integration of fulfillment infrastructure over outsourcing relationships. Geographic permit accumulation and MIIT certification credentials represent the dominant competitive moves.
Within the platform-integrated tier, Amazon Scout exemplifies captive fleet deployment tied to e-commerce fulfillment networks. Starship Technologies anchors European campus and grocery delivery through accumulated municipal permits across multiple jurisdictions. Nuro occupies a position representing suburban parcel specialization with in-house navigation development for structured residential environments.
| Leading Market Players |
|---|
| Amazon Scout |
| Agility Robotics |
| Starship Technologies |
| Locus Robotics |
| Geek+ |
| Nuro |
| Serve Robotics |
| Mobile Industrial Robots |
| Coco Robotics |
| Others |
Cost & Logistics Intelligence
Shenzhen's sensor manufacturing cluster anchors global lidar and solid-state radar supply, concentrating component pricing power among certified MIIT suppliers while compressing margins for non-integrated assemblers in Europe and North America.
Pricing Analysis
Chinese-certified ground robots command 15-25% premiums over uncertified competitors in European procurement. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-validated fleets from municipal-permit-only operators from campus-limited units. Cost compression in the economy tier is intensifying because lithium-ion cell allocation constraints favor volume buyers. Third-party logistics providers exhibit highest price sensitivity; e-commerce platforms with captive fleets show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for ground-robot assemblers. Component sourcing draws from China for lidar and edge processors, South Korea for battery cells, and Taiwan for semiconductor substrates. Single-source vulnerability concentrates in solid-state sensor fabs. Distribution runs through OEM direct sales to e-commerce platforms, with third-party logistics providers losing share to vertical integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal permitting fragmentation creates white-space opportunities for operators with jurisdiction-specific regulatory expertise, as demand shifts from supervised to fully unmanned service models.
For Market Incumbents: Insulate market position by accumulating municipal permits across fragmented US jurisdictions before competitors replicate Starship Technologies' European campus density. Prioritize MIIT certification investment to secure preferential access to Shenzhen and Beijing pilot corridors. Counter emerging sensor fusion specialists through backward integration into solid-state radar development. For New Entrants and Emerging Players: Medical supply chain corridors in Switzerland and Australia represent the most penetrable entry point, bypassing FAA Part 135 barriers that constrain aerial competitors. Target suburban parcel density in US Sun Belt municipalities with permissive sidewalk ordinances. Pursue hospital system partnerships as the primary go-to-market angle for cold-chain validated transport. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because MIIT-certified manufacturers with accumulated municipal permits will consolidate fragmented vendor relationships. Acquisition target archetype: fleet operators with 10+ city permits and in-house sensor fusion capability. Watch FAA BVLOS rulemaking as the signal for aerial drone inflection.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Investment | Unlocks preferential access to Shenzhen and Beijing municipal pilot corridors. |
| Municipal Permit Accumulation | Creates defensible geographic moats against fragmented regulatory competitors. |
| Solid-State Radar Integration | Displaces lidar-dominant stacks while extending operational availability in precipitation. |
| Hospital System Partnership | Secures premium positioning for temperature-sensitive biologics transport corridors. |
| Captive Fleet Deployment | Preserves last-mile data ownership against third-party logistics margin compression. |
Research Approach
Initial hypotheses were tested against primary input from autonomous systems engineers, municipal permitting officers, e-commerce logistics directors, and healthcare supply chain managers and refined through secondary validation against FAA dockets, MIIT testing protocols, EU AI Act documentation, and customs trade data. Bottom-up fleet deployment estimates triangulated with top-down e-commerce fulfillment network analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include robot type, deployment environment, application category, and end-user ownership structure. CAGRs derived from unit economics modeling of lidar cost deflation curves and regulatory commercialization timelines. Industry-specific inputs incorporated MIIT certification pipeline data and municipal permit issuance rates.
Stress conditions across lithium-ion cell supply allocation, FAA BVLOS rulemaking delays, and GPS-denied navigation performance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization progress and sensor cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Autonomous Taxi Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Asia-Pacific Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Europe IoT Connected Cars Market