
 China Autonomous Navigation Market | 2026-2036
China Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
China Autonomous Navigation Market Insights
LiDAR perception engineering talent scarcity is reorganizing competitive dynamics across the China Autonomous Navigation Market. Baidu leverages its Apollo platform to anchor autonomous taxi operations in multiple Chinese cities. Hesai Technology specializes in solid-state LiDAR manufacturing to sustain hardware cost reductions for domestic automakers.
Autonomous navigation encompasses real-time positioning, path planning, and obstacle avoidance systems that fuse sensor inputs at sub-50-millisecond latency to enable unmanned vehicle operation in dynamic environments. The technology serves commercial transport, precision agriculture, and last-mile logistics by replacing human situational judgment with machine perception. Lidar and computer vision segments lead hardware procurement as automakers pursue multi-sensor redundancy for highway pilot systems. Cloud-based deployment architectures are expanding fastest among logistics providers managing centralized fleet coordination across hub-and-spoke distribution networks.
MIIT's intelligent connected vehicle technical standards, NMPA's conditional autonomous driving vehicle type-approval rules, and GB national standards for functional safety collectively shape product certification requirements and market access timelines. SAMR's oversight of mapping data security adds compliance layers for navigation software providers handling geospatial information. Stakeholders must monitor regulatory clarity on cross-provincial operation permits and data localization mandates to align commercial rollout strategies with enforcement trajectories.
Market Dynamics
MIIT's intelligent connected vehicle standards are compressing commercialization timelines by mandating unified technical specifications across domestic automakers and navigation software providers.
Growth Catalysts
- GB Standards Harmonization:National functional safety standards reduce certification friction for multi-provincial fleet operators seeking rapid deployment approvals.
- Guangdong Logistics Clusters:Dense port-to-warehouse corridors in Shenzhen and Guangzhou generate concentrated demand for autonomous yard tractors and container handlers.
- 5G-V2X Infrastructure Rollout:Cellular vehicle-to-everything networks enable sub-20-millisecond latency for cooperative perception between autonomous trucks and traffic infrastructure.
Market Restraints
- LiDAR Supply Concentration:Domestic solid-state sensor production remains concentrated among three specialized manufacturers, creating input bottlenecks for tier-one system integrators.
- Mapping Data Localization:SAMR's geospatial security requirements impose data residency costs on navigation software providers handling real-time road geometry updates.
- High-Definition Map Refresh Costs:Centimeter-accurate road databases require quarterly survey vehicle passes, elevating operating expenditures for highway pilot systems.
Strategic Opportunities
- Jiangsu Manufacturing Corridors:Suzhou and Wuxi industrial zones present untapped demand for autonomous material transport between semiconductor fabrication facilities.
- Dual Carbon Policy Alignment:MEE emissions reduction mandates create regulatory tailwinds for electric autonomous fleets replacing diesel yard equipment.
- AI-Edge Convergence:On-vehicle neural network inference chips combined with cloud-based fleet optimization enable predictive maintenance and dynamic route adjustment.
Industry Challenges
- Perception Engineering Talent Scarcity:Domestic universities produce insufficient LiDAR fusion specialists, forcing system integrators to poach from competing autonomous driving programs.
- Cross-Provincial Permit Fragmentation:Municipal traffic authorities maintain non-uniform testing and operation licensing requirements, complicating nationwide fleet scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Autonomous Navigation Market |
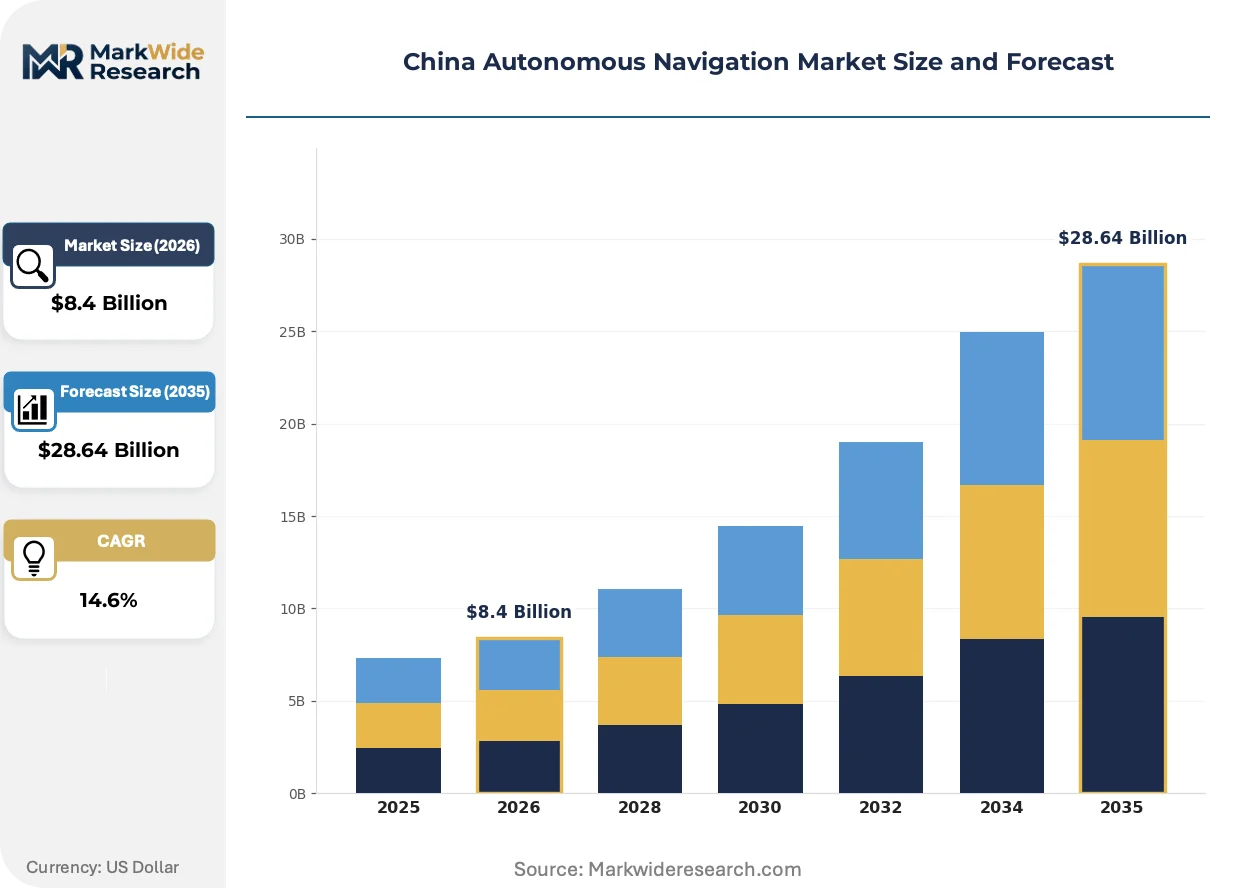
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lidar, Radar, Computer Vision, GNSS End User: Automakers, Logistics Providers, Research Institutions, Public Transport Application: Passenger Vehicles, Delivery Drones, Robotic Cleaners, Agricultural Machinery Deployment: Edge Computing, Cloud-based Systems, On-Premises Solutions, Hybrid Models |
| Companies Covered | Baidu, Pony.ai, AutoNavi, Hesai Technology, Huawei Technologies, XPeng, WeRide, Haomo.ai, NavInfo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Autonomous Navigation Market Trends and Innovations
Hardware-software decoupling is reshaping supplier relationships as automakers seek modular navigation stacks that accommodate multiple sensor configurations without proprietary lock-in.
Solid-state LiDAR is decomposing the traditional mechanical scanning architecture by replacing rotating assemblies with semiconductor-based beam steering. Domestic automakers in the premium electric segment are adopting these sensors for highway pilot systems at accelerating procurement volumes. This technology is decomposing cost structures by eliminating precision motor assemblies and enabling chip-scale manufacturing economics.
NMPA's conditional autonomous driving vehicle type-approval rules establish a structured pathway from closed-course testing to supervised public road operation. The framework mandates documented safety validation across defined operational design domains before commercial deployment authorization. Jiangsu and Guangdong provincial regulators are advancing pilot zone expansions in response, accelerating fleet operator licensing timelines.
Fleet procurement committees are consolidating vendor relationships around integrated perception-navigation platforms rather than discrete sensor purchases. Logistics providers managing hub-and-spoke networks in the Yangtze River Delta are demanding unified hardware-software stacks with guaranteed interoperability. This consolidation is most visible among port operators in Ningbo-Zhoushan seeking single-source accountability for autonomous container handling performance.
China Autonomous Navigation Market Segmentation
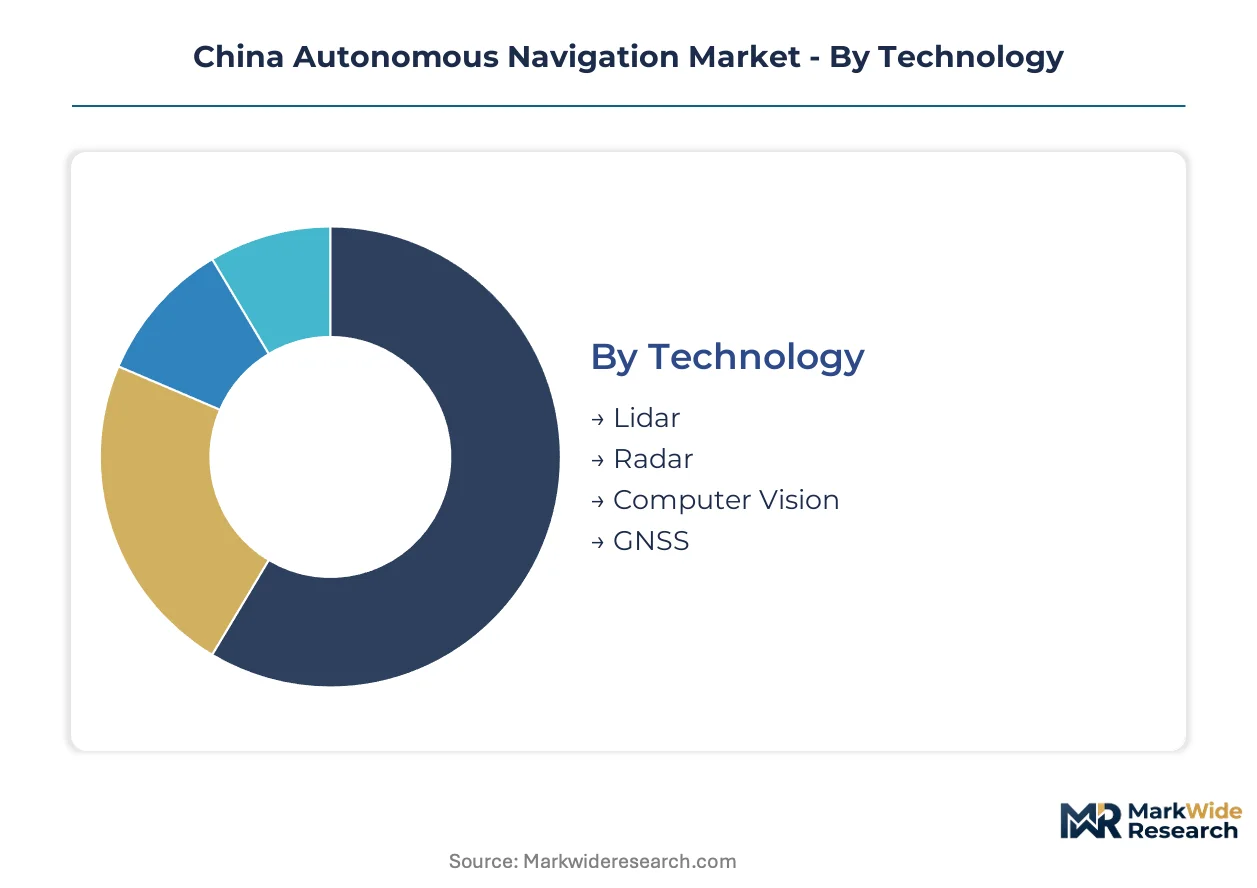
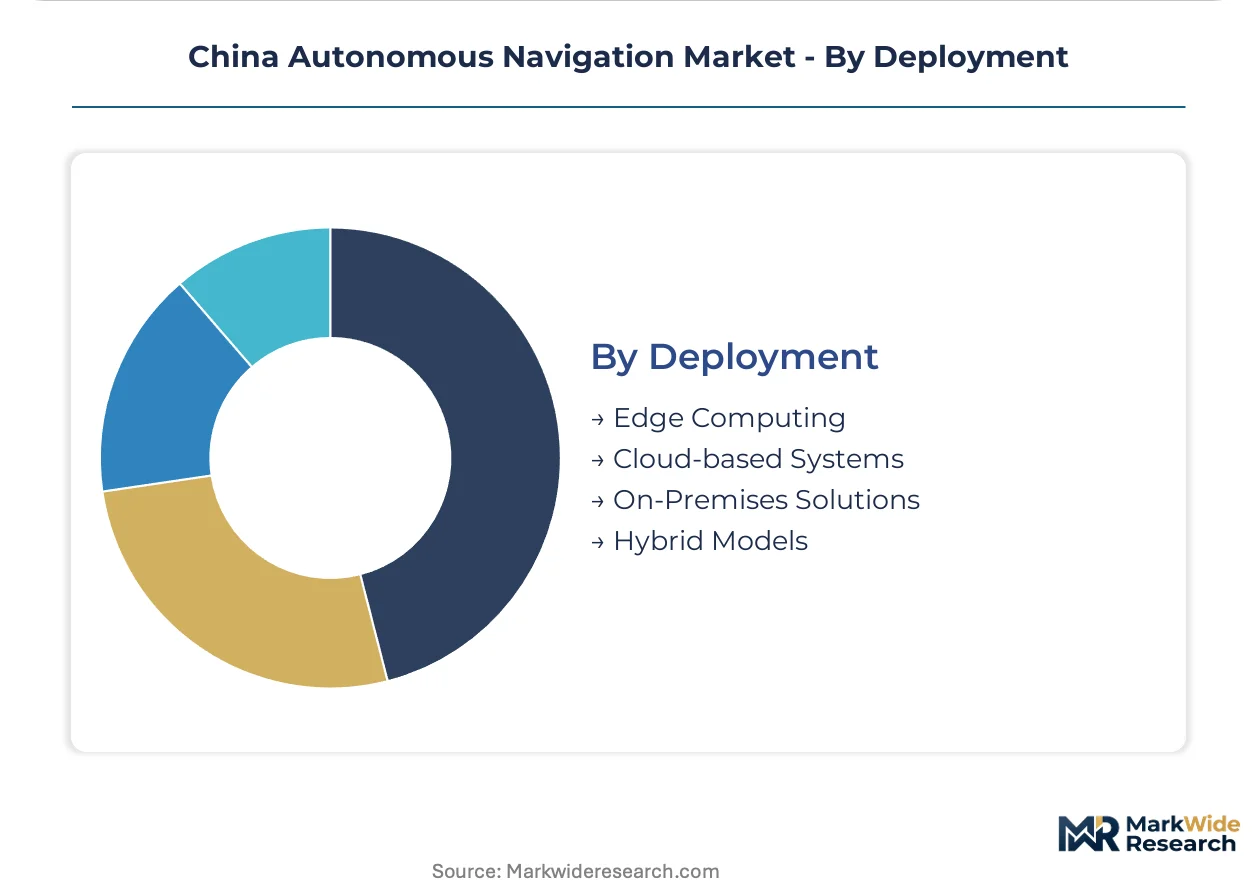
Technology and deployment configurations in the China Autonomous Navigation Market determine regulatory compliance pathways and hardware procurement priorities. MIIT's intelligent connected vehicle standards create divergent certification requirements across sensor modalities and computing architectures, forcing stakeholders to align segment strategies with specific approval timelines.
Technology:
GB national standards for functional safety impose differentiated testing protocols on each sensor modality, with LiDAR and computer vision facing distinct electromagnetic compatibility and environmental durability requirements.
- Lidar:Solid-state semiconductor beam steering replaces mechanical rotating assemblies, enabling chip-scale manufacturing economics. Guangdong logistics clusters in Shenzhen and Guangzhou drive concentrated procurement for autonomous yard tractors requiring centimeter-accurate obstacle detection. Established volume favors LiDAR; emerging adoption favors GNSS.
- Computer Vision:Neural network inference on embedded GPUs processes camera feeds for lane recognition and traffic sign interpretation. Domestic automakers integrate these systems for highway pilot functions in premium electric vehicles, constrained by SAMR's mapping data localization requirements for real-time road geometry updates.
- Radar:77GHz and 79GHz frequency modulated continuous wave sensors provide velocity measurement and all-weather penetration for adaptive cruise control systems.
- GNSS:Multi-constellation receivers combining BeiDou, GPS, and GLONASS signals deliver decimeter-level positioning for open-road autonomous trucking corridors.
Cost tiering separates high-precision LiDAR arrays from commoditized radar modules in commercial vehicle specifications.
End User:
Customer procurement authority determines integration complexity, with automakers demanding full-stack control while logistics providers accept vendor-managed perception platforms.
- Automakers:Vertical integration into sensor fusion software and domain controller hardware preserves proprietary differentiation in highway pilot systems. NMPA's conditional autonomous driving type-approval rules mandate documented safety validation across defined operational design domains before commercial deployment authorization.
- Logistics Providers:Hub-and-spoke network operators in the Yangtze River Delta consolidate vendor relationships around unified hardware-software stacks with guaranteed interoperability. Ningbo-Zhoushan port operators seek single-source accountability for autonomous container handling performance.
- Research Institutions:University and national laboratory programs advance algorithmic perception frontiers through closed-course testing exemptions.
- Public Transport:Municipal bus operators pilot fixed-route autonomous shuttles under localized traffic authority permits in Jiangsu and Guangdong pilot zones.
Procurement concentration clusters with logistics providers; technology validation concentrates with automakers.
Application:
Operating environment severity dictates sensor redundancy requirements, with highway passenger vehicles facing the most stringent functional safety mandates.
- Passenger Vehicles:Multi-sensor fusion architectures combining LiDAR, radar, and computer vision enable highway pilot systems in premium electric segments. Domestic automakers pursue sub-50-millisecond latency for unmanned operation in dynamic traffic environments.
- Delivery Drones:Low-altitude urban air mobility platforms navigate via GNSS-waypoint guidance with optical flow backup for GPS-denied environments.
- Robotic Cleaners:Structured indoor navigation relies on 2D LiDAR and ultrasonic arrays for corridor mapping in commercial facilities.
- Agricultural Machinery:RTK-GNSS guidance systems enable centimeter-accurate planting and spraying across standardized field geometries.
Application maturity favors passenger vehicles; steepest expansion trajectory favors delivery drones.
Deployment:
Computing architecture selection determines latency-performance tradeoffs and data sovereignty compliance costs for navigation software providers.
- Edge Computing:On-vehicle neural network inference chips enable sub-20-millisecond perception-to-actuation loops for safety-critical obstacle avoidance. Suzhou and Wuxi industrial zones present untapped demand for autonomous material transport between semiconductor fabrication facilities.
- Cloud-based Systems:Centralized fleet coordination platforms manage dynamic route optimization across distributed logistics networks. SAMR's geospatial security requirements impose data residency costs on providers handling real-time road geometry updates.
- On-Premises Solutions:Dedicated server installations within enterprise facilities satisfy air-gapped security requirements for defense and critical infrastructure applications.
- Hybrid Models:Partitioned architectures process time-critical functions locally while offloading fleet optimization to cloud resources.
Latency-sensitive applications anchor on edge deployments; fleet-scale coordination drives cloud adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong and Jiangsu provinces consume autonomous navigation technologies through port logistics and warehouse automation, while Beijing-Tianjin-Hebei prioritizes passenger vehicle highway pilot systems. This consumption-mix differential shapes deployment priorities across China's regional markets.
Guangdong Province
Shenzhen and Guangzhou port operators deploy autonomous yard tractors and container handlers at accelerating procurement volumes. MIIT's intelligent connected vehicle standards compress certification timelines for logistics fleet operators seeking multi-provincial deployment approvals. The Shenzhen-Guangzhou corridor generates concentrated demand for centimeter-accurate obstacle detection systems in dense port-to-warehouse environments.
Jiangsu Province
Suzhou and Wuxi industrial zones present untapped demand for autonomous material transport between semiconductor fabrication facilities. NMPA's conditional autonomous driving type-approval rules mandate documented safety validation across defined operational design domains before commercial authorization. The Yangtze River Delta logistics clusters consolidate vendor relationships around unified hardware-software stacks with guaranteed interoperability.
Beijing Municipality
Autonomous taxi operations anchor demand through Baidu's Apollo platform deployments across multiple urban districts. SAMR's mapping data localization requirements impose data residency costs on navigation software providers handling real-time road geometry updates. The Beijing-Tianjin-Hebei corridor prioritizes passenger vehicle highway pilot systems with sub-50-millisecond latency requirements for dynamic traffic environments.
Shanghai Municipality
Ningbo-Zhoushan port operators seek single-source accountability for autonomous container handling performance across hub-and-spoke networks. GB national standards for functional safety impose differentiated testing protocols on sensor modalities with distinct electromagnetic compatibility requirements. The Yangtze River Delta manufacturing base drives cloud-based fleet coordination platform adoption for distributed logistics network management.
Sichuan-Chongqing Region
Western China logistics corridors generate emerging demand for autonomous trucking across challenging terrain configurations. MEE emissions reduction mandates create regulatory tailwinds for electric autonomous fleets replacing diesel yard equipment in industrial zones. The Chengdu-Chongqing economic circle pilots fixed-route autonomous shuttles under localized traffic authority permits advancing fleet operator licensing timelines.
China Autonomous Navigation Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in China's autonomous navigation market structure. Tier-one system integrators compete through proprietary sensor fusion software and domain controller hardware preserving differentiation in highway pilot systems. Three archetypes dominate: full-stack platform providers, solid-state LiDAR specialists, and precision mapping data services. Competitive moves concentrate on strategic partnerships for 5G-V2X infrastructure integration and backward integration into perception chip design.
Within the full-stack platform tier, Baidu anchors autonomous taxi operations through its Apollo deployment across multiple Chinese cities. Hesai Technology occupies a position exemplifying solid-state LiDAR manufacturing specialization for domestic automaker procurement. Pony.ai represents the emerging tier of autonomous ride-hail operators advancing from closed-course testing to supervised public road operation under NMPA's structured approval pathway.
| Leading Market Players |
|---|
| Baidu |
| Pony.ai |
| AutoNavi |
| Hesai Technology |
| Huawei Technologies |
| XPeng |
| WeRide |
| Haomo.ai |
| NavInfo |
| Others |
Pricing and Supply Chain Analysis
MIIT's intelligent connected vehicle standards gate both supplier qualification and price differentiation simultaneously, compressing certification timelines for qualified vendors while imposing compliance costs that stratify hardware-software bundles across premium and standard tiers. NMPA's conditional autonomous driving approval pathways add parallel validation requirements that concentrate pricing power among integrated platform providers capable of absorbing multi-stage testing expenditures.
Pricing Analysis
Long-term offtake contracts dominate procurement between logistics fleet operators and LiDAR manufacturers, locking in volume commitments against price stability guarantees. Three-tier pricing structure across premium, standard, and economy levels separates highway pilot-grade sensor fusion stacks from port automation hardware and indoor robotic navigation modules. Cost compression in solid-state LiDAR arrays is intensifying because domestic semiconductor packaging capacity is scaling faster than mechanical rotating assembly supply. Logistics providers in Guangdong and Jiangsu exhibit highest price sensitivity due to thin yard automation margins, while premium electric automakers absorb certification-premium pricing for NMPA type-approved highway systems.
Supply Chain Analysis
China and Taiwan anchor semiconductor wafer fabrication and MEMS chip packaging for solid-state LiDAR beam steering components. The supply chain draws from rare earth magnet deposits for precision motor assemblies in legacy mechanical scanners, and from German and Japanese specialty glass suppliers for optical substrate fabrication. Single-source vulnerability concentrates in indium phosphide laser diode production, where two specialized foundries control global output. Distribution runs through tier-one system integrators who consolidate discrete sensor procurement into unified perception platforms for downstream automakers and logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's autonomous navigation market sits in early-cycle expansion, with NMPA's structured approval pathway accelerating commercial deployment timelines beyond comparable regulatory regimes. MIIT's harmonized technical standards are compressing fragmentation that historically delayed fleet-scale rollouts.
For Market Incumbents: Fortify backward integration into perception chip design to defend margin position against emerging fabless AI accelerator entrants. Secure exclusive 5G-V2X infrastructure partnerships in Jiangsu and Guangdong pilot zones to lock out competing platform providers. Capacity addition in Suzhou semiconductor packaging corridors preserves supply assurance as LiDAR demand inflects.
For New Entrants and Emerging Players: Lead with autonomous material transport solutions targeting Suzhou and Wuxi semiconductor fabrication facilities, the most penetrable segment given minimal incumbent saturation. Deploy edge-computing-native navigation stacks that bypass cloud data localization compliance costs burdening established cloud-dependent platforms. Direct sales to industrial zone operators bypass automaker certification queues.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across solid-state LiDAR manufacturing as chip-scale economics displace mechanical assembly precision requirements. Long-term viability favors vertically integrated perception platform providers with captive sensor supply and NMPA approval track records. Monitor MIIT's cross-provincial operation permit harmonization as the signal indicating nationwide fleet scaling feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| 5G-V2X Infrastructure Partnership | Sub-20-millisecond cooperative perception unlocks highway platooning authorization under MIIT standards. |
| Solid-State LiDAR Manufacturing Scale-Up | Chip-scale beam steering eliminates precision motor dependencies and enables automotive-grade cost targets. |
| NMPA Conditional Approval Pathway Navigation | Documented ODD validation accelerates commercial deployment authorization timelines for fleet operators. |
| Backward Integration into Edge AI Chips | On-vehicle neural network inference reduces cloud data residency compliance costs under SAMR mandates. |
| Dual Carbon Fleet Electrification Alignment | MEE emissions mandates create regulatory tailwinds for battery-electric autonomous yard equipment procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MIIT policy circulars, NMPA approval filings, and GB standards documentation. Primary interviews engaged autonomous vehicle platform engineers, LiDAR manufacturing procurement leads, logistics fleet operations directors, and SAMR compliance officers across Guangdong, Jiangsu, and Beijing. Secondary validation incorporated customs trade data for sensor component imports, provincial pilot zone licensing records, and automaker SEC disclosures for intelligent connected vehicle capex. Bottom-up demand modeling from fleet operator procurement plans triangulates against top-down market sizing from hardware shipment aggregations.
Segmentation dimensions modeled span sensor modality, deployment architecture, end-user category, and application environment across the analysis window. Technology segments capture LiDAR, computer vision, radar, and GNSS with differentiated electromagnetic compatibility testing protocols. Deployment splits across edge computing, cloud-based systems, on-premises solutions, and hybrid architectures. CAGRs derive from weighted average of technology adoption curves, regulatory approval velocity, and fleet replacement cycle timing. Industry-specific inputs include 5G-V2X infrastructure rollout schedules and NMPA type-approval queue lengths.
Forecasts assume regulatory continuity in MIIT standards enforcement and NMPA approval pathway structure; material policy shifts would require re-modeling. Specific risks include SAMR mapping data localization mandate expansion, cross-provincial permit fragmentation persistence, and LiDAR supply concentration disruption. Recalibration cycles align with material shifts in NMPA approval velocity and provincial pilot zone expansion decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Asia-Pacific Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
North America ADAS Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
Europe IoT Connected Cars Market