
 Autonomous Vehicle ECU Market | 2026-2036
Autonomous Vehicle ECU Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Vehicle ECU Market Outlook
ASIL-D safety certification is reorganizing supplier hierarchies in the autonomous vehicle ECU landscape. NXP Semiconductors leverages its domain expertise in automotive-grade microcontrollers to anchor high-integrity compute platforms. Bosch competes through in-house production of sensor fusion modules and power distribution systems. Continental AG differentiates via integrated software-hardware stacks spanning perception to actuation.
An autonomous vehicle ECU constitutes a ruggedized embedded controller combining multi-core processors, deterministic real-time operating systems, and ISO 26262-compliant fault management to execute perception, planning, and control algorithms for self-driving operation. The component dimension shows central processing units capturing the dominant margin pool due to silicon complexity and thermal design requirements, while communication interfaces represent the fastest-expanding category as V2X deployment accelerates. Sensor fusion technology leads the technology segmentation in current revenue contribution, though artificial intelligence integration is reshaping architectural roadmaps across OEM and Tier-1 supplier end-user channels.
UNECE WP.29, the EU AI Act, and FDA-equivalent national automotive regulators in target deployment countries are mandating traceable validation documentation and cybersecurity management systems as preconditions for type approval. These frameworks compress development timelines and elevate barriers for ECU suppliers lacking established regulatory affairs capabilities. Stakeholders must monitor evolving liability allocation rules between hardware suppliers, software integrators, and fleet operators as automation levels advance.
Market Dynamics
ASIL-D certification mandates from UNECE WP.29 are compressing supplier timelines and forcing redundant compute architectures across the autonomous vehicle ECU supply base. This regulatory pressure is restructuring competitive hierarchies around fault-tolerant hardware and traceable software validation.
Growth Catalysts
- UNECE WP.29 Type Approval:Harmonized validation frameworks accelerate cross-border deployment for Level 3 and Level 4 systems, reducing redundant testing costs for suppliers serving multiple national markets.
- Fleet operator consolidation:Logistics and ride-hailing buyers aggregate procurement volumes, creating dedicated supply agreements that amortize ECU development costs across thousand-unit deployments.
- Silicon photonics integration:Optical interconnects within sensor fusion modules reduce electromagnetic interference and enable deterministic latency for real-time perception pipelines.
Market Restraints
- Automotive-grade silicon scarcity:Foundry capacity constraints for 7nm and 5nm process nodes limit ECU production scaling and extend lead times for high-compute platforms.
- LiDAR cost structure:Solid-state and mechanical LiDAR units constitute 30-40% of perception subsystem BOM, constraining cost-down trajectories for mass-market vehicle programs.
- Cybersecurity certification friction:ISO/SAE 21434 compliance timelines add 12-18 months to product development cycles, delaying revenue recognition for new platform launches.
Strategic Opportunities
- Edge AI inference acceleration:Dedicated neural processing units enable on-device perception without cloud dependency, opening military and remote mining applications previously blocked by connectivity constraints.
- India PLI scheme for automotive electronics:Production-linked incentives attract ECU assembly and testing investments, creating export capacity for Southeast Asian and Middle Eastern vehicle markets.
- V2X infrastructure mandates:DSRC and C-V2X roadside unit deployments in Germany, Japan, and China create aftermarket retrofit demand for communication-enabled ECU variants.
Industry Challenges
- Functional safety engineering talent:ISO 26262-certified hardware and software architects command premium compensation, constraining Tier-1 supplier hiring pipelines.
- Legacy vehicle platform integration:Retrofitting Level 2+ automation into existing electrical architectures requires gateway ECU redesigns and power distribution upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Vehicle ECU Market |
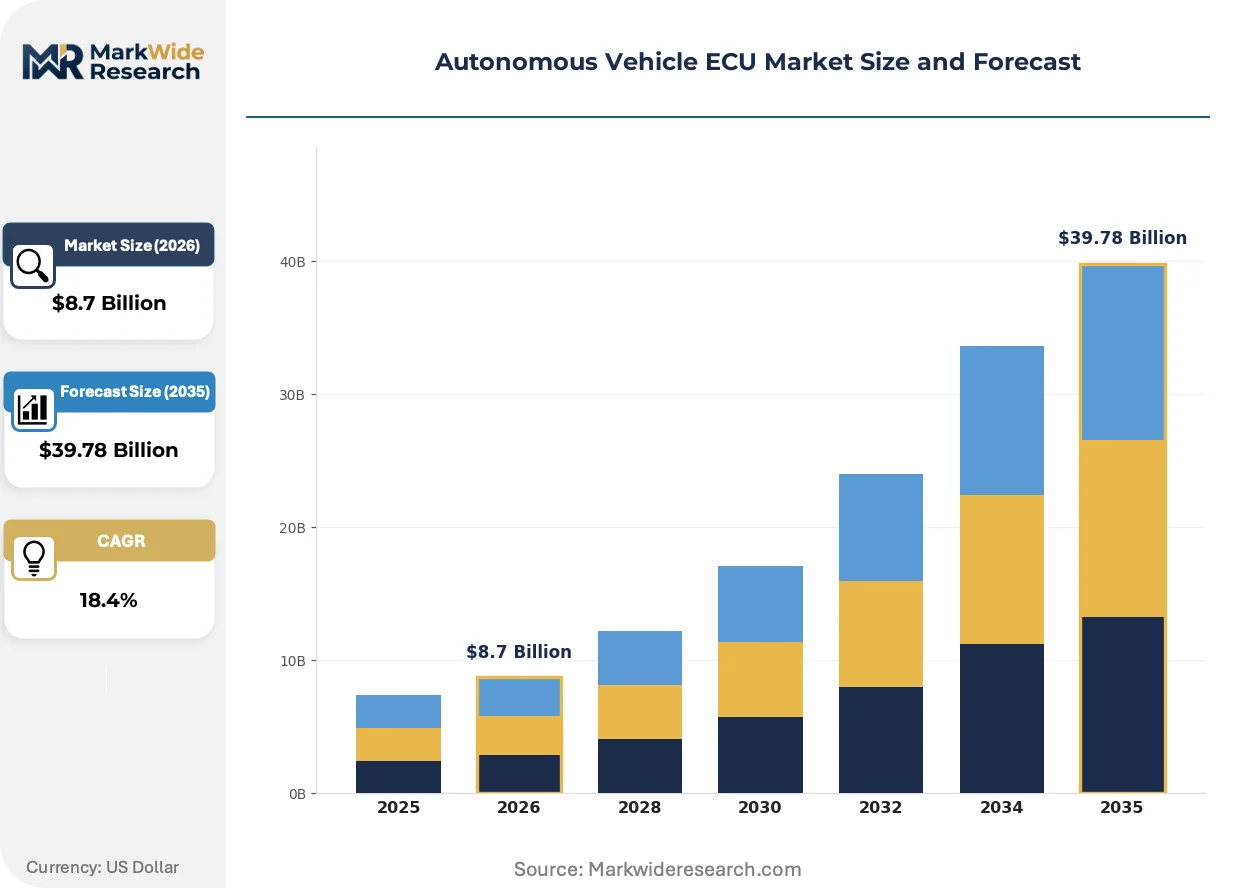
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Central Processing Unit, Sensor Module, Power Distribution Unit, Communication Interface Technology: Artificial Intelligence, Machine Learning, Sensor Fusion, V2X Communication End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, R&D Institutions Application: Autonomous Driving, Driver Assistance, Fleet Management, Urban Mobility |
| Companies Covered | NXP Semiconductors, Hitachi, Continental AG, Nvidia Corporation, Intel Corporation, Bosch, Infineon Technologies AG, Renesas Electronics Corporation, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Vehicle ECU Market Strategic Shifts
Centralized zonal architectures are collapsing distributed ECU topologies into domain controllers, consolidating compute resources and simplifying wiring harness complexity. This structural shift is redrawing supplier boundaries between silicon vendors, Tier-1 integrators, and OEM software divisions.
Domain controller consolidation is supplanting the traditional distributed ECU model where 70-100 separate controllers managed individual vehicle functions. BMW and Mercedes-Benz production programs now deploy central compute platforms handling perception, planning, and body control from unified silicon. This compression eliminates redundant power management and communication hardware, reducing harness mass and assembly labor while concentrating margin pools with semiconductor suppliers capable of delivering ASIL-D capable system-on-chip designs.
The EU AI Act's risk classification framework for autonomous driving systems mandates algorithmic transparency and human oversight mechanisms as preconditions for market access. Suppliers must maintain version-controlled training datasets and model lineage documentation spanning development through deployment. German and French regulators are enforcing these requirements most stringently, pushing ECU manufacturers to embed hardware-based logging and cryptographic attestation directly into compute platforms.
Fleet procurement teams now specify total cost of ownership metrics encompassing hardware, software licensing, and over-the-air update infrastructure rather than unit-based ECU pricing. Logistics operators in California and Texas negotiate outcome-based contracts tying supplier payments to uptime and collision avoidance performance. This reconfiguration shifts commercial risk toward ECU vendors and accelerates demand for predictive maintenance analytics embedded at the edge.
Autonomous Vehicle ECU Market Segmentation
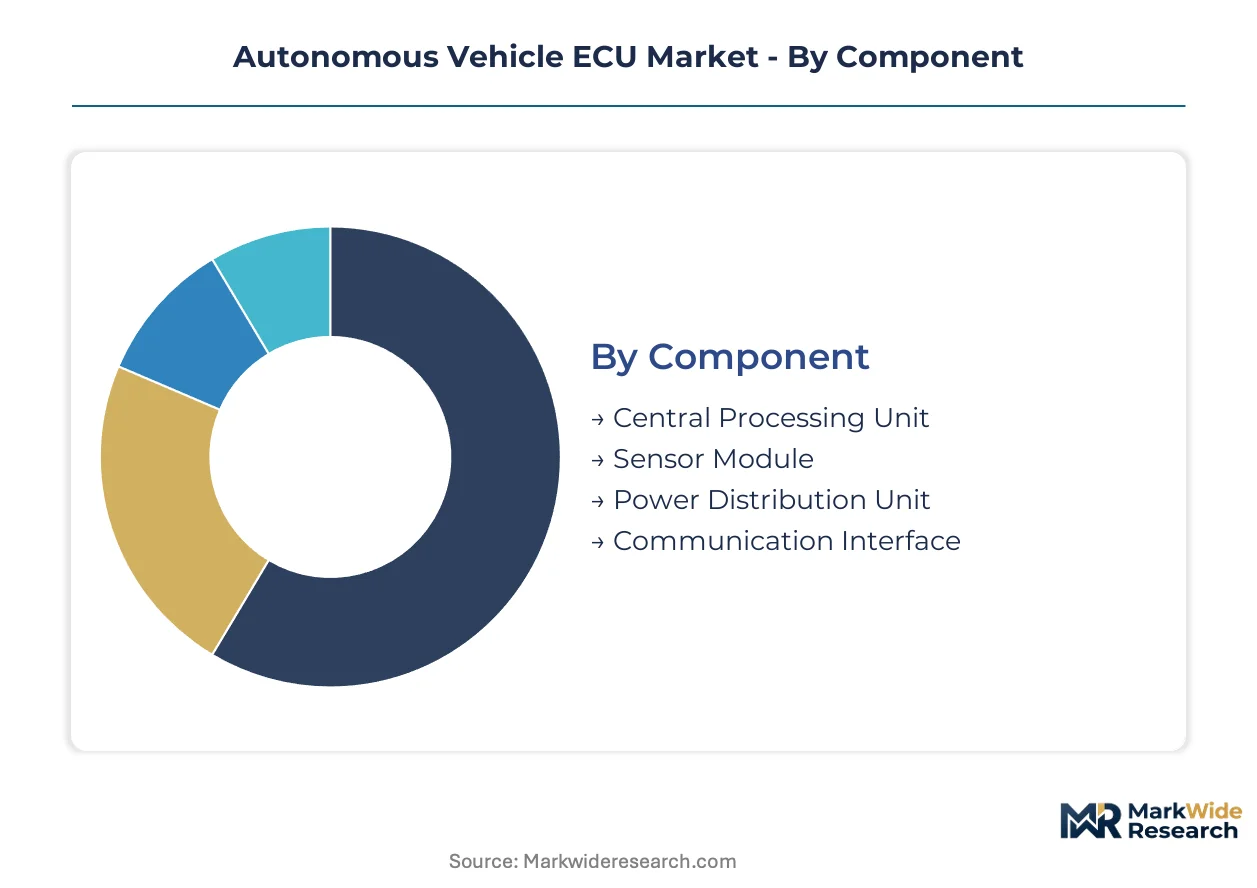
Segmentation in autonomous vehicle ECUs reveals how architectural consolidation and regulatory tiering create divergent margin pools. Suppliers must align component portfolios with specific automation levels and validation requirements rather than pursuing horizontal coverage.
Component:
Central processing units face the most acute substitution pressure from domain controller consolidation, while communication interfaces benefit from V2X infrastructure mandates that lock in dedicated hardware requirements.
- Central Processing Unit:Multi-core system-on-chip designs integrating ASIL-D safety islands and neural processing units for deterministic perception pipelines. BMW and Mercedes-Benz production programs concentrate procurement here for unified compute platforms handling perception through actuation.
- Sensor Module:Integrated LiDAR, radar, and camera preprocessing units with embedded sensor fusion algorithms reducing raw data bandwidth to central compute. Solid-state LiDAR cost trajectories determine adoption velocity in mass-market vehicle programs.
- Power Distribution Unit:Redundant power management with fault-tolerant switching architectures isolating critical safety functions.
- Communication Interface:DSRC and C-V2X transceiver modules enabling vehicle-to-infrastructure coordination.
Central processing units retain volume leadership; communication interfaces hold the steepest expansion curve.
Technology:
Technology segmentation reflects cost tier differentiation between proven deterministic systems and probabilistic AI approaches requiring extensive validation documentation.
- Artificial Intelligence:Deep learning inference engines for object detection and trajectory prediction operating on quantized neural networks. EU AI Act algorithmic transparency requirements concentrate demand in Germany and France for hardware-based logging capabilities.
- Sensor Fusion:Kalman filter and particle filter implementations combining heterogeneous sensor streams into unified environmental models. This technology anchors current production deployments with established ISO 26262 validation pathways.
- Machine Learning:Supervised learning pipelines for behavioral prediction and anomaly detection in traffic scenarios.
- V2X Communication:Low-latency messaging protocols for cooperative perception and intersection coordination.
Sensor fusion retains volume leadership; artificial intelligence holds the steepest expansion curve.
End User:
Customer type segmentation tracks procurement consolidation among fleet operators versus fragmented OEM development programs.
- OEMs:Vehicle manufacturers specifying integrated software-hardware stacks with captive validation resources. Volkswagen, BMW, and Mercedes-Benz maintain concentrated R&D spending on SAE Level 3 production programs driving ECU specification authority.
- Tier-1 Suppliers:Bosch and Continental AG aggregating multi-OEM volumes through modular platform designs amortizing development across customer programs.
- Aftermarket Providers:Retrofit system integrators serving commercial vehicle fleet upgrades.
- R&D Institutions:University and government research programs validating novel algorithms.
Tier-1 suppliers retain volume leadership; OEMs hold the steepest expansion curve.
Application:
Application segmentation aligns with automation level validation requirements and operational design domain constraints.
- Autonomous Driving:Level 3 and Level 4 systems executing full self-driving within mapped operational design domains. Logistics and ride-hailing fleet operators in California and Texas aggregate procurement volumes through outcome-based contracting structures.
- Driver Assistance:Level 2 and Level 2+ systems combining adaptive cruise control with lane-keeping assistance. This application dominates current production volumes with established regulatory approval pathways.
- Fleet Management:Centralized monitoring and predictive maintenance for commercial vehicle deployments.
- Urban Mobility:Low-speed autonomous shuttles and last-mile delivery pods operating in geofenced environments.
Driver assistance retains volume leadership; autonomous driving holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for automotive-grade silicon concentrates in Taiwan and South Korea, while ECU integration and validation clusters dominate Germany, the United States, and Japan. Demand formation tracks divergent regulatory timelines across national markets.
Germany
BMW, Mercedes-Benz, and Volkswagen operate concentrated Level 3 production programs in Bavaria and Baden-Württemberg. KBA enforces UNECE WP.29 type approval with stringent documentation requirements for algorithmic traceability. Stuttgart anchors sensor fusion R&D clusters where Bosch and Continental AG validate integrated software-hardware stacks.
United States
California and Texas host logistics and ride-hailing fleet operators negotiating outcome-based ECU procurement contracts. NHTSA maintains voluntary guidance frameworks while California DMV operates permit-based testing regimes for autonomous deployment. Silicon Valley concentrates AI inference chip design activity for neural processing units.
China
Domestic OEMs accelerate Level 4 pilot programs in Beijing and Shanghai with MIIT-mandated data localization for connected vehicle systems. SAMR oversees cybersecurity certification under GB standards. Yangtze River Delta manufacturing bases scale domain controller assembly for export to Southeast Asian markets.
Japan
Toyota and Honda maintain captive ECU development in Aichi Prefecture with METI-sponsored V2X infrastructure deployment timelines. JIS standards govern functional safety documentation for domestic type approval. Nagoya-Tokyo corridor hosts Renesas Electronics production facilities for automotive microcontrollers.
South Korea
Hyundai Motor Group consolidates autonomous driving R&D in Seoul Capital Area with government-mandated C-V2X spectrum allocation. MFDS-equivalent automotive regulators coordinate with MIIT on cross-border validation recognition. Busan-Ulsan industrial complex supplies memory and logic semiconductors for ECU subsystems.
Autonomous Vehicle ECU Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the autonomous vehicle ECU landscape. The market structure consolidates around semiconductor vendors with ASIL-D silicon expertise and Tier-1 integrators with multi-OEM platform scale. Three archetypes dominate: automotive-grade chip designers, domain controller integrators, and sensor fusion specialists. Competitive dynamics center on strategic partnerships for software stack integration and foundry capacity reservations for advanced process nodes.
Within the semiconductor archetype, NXP Semiconductors, Nvidia Corporation, and Infineon Technologies AG occupy positions anchoring high-integrity compute platforms. NXP represents European automotive microcontroller heritage, Nvidia exemplifies AI inference acceleration for autonomous perception pipelines, and Infineon anchors German power semiconductor and safety controller expertise. These companies sit within a tier where silicon complexity and thermal design capabilities determine procurement access to Level 3 and Level 4 vehicle programs.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Hitachi |
| Continental AG |
| Nvidia Corporation |
| Intel Corporation |
| Bosch |
| Infineon Technologies AG |
| Renesas Electronics Corporation |
| ZF Friedrichshafen AG |
| Others |
Value Chain & Pricing Dynamics
Silicon photonics substitution for copper interconnects in sensor fusion modules is redrawing foundry geography toward Taiwan and South Korea while compressing pricing premiums for electromagnetic-interference-resistant designs. This materials transition simultaneously elevates ASIL-D certification costs and concentrates procurement leverage with semiconductor vendors holding advanced packaging capabilities.
Pricing Analysis
UNECE WP.29 dictates the pricing tier structure across autonomous vehicle ECU procurement, separating ASIL-D validated platforms from lower-integrity alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and thermal design complexity. Cost compression in standard-tier domain controllers is intensifying because foundry capacity constraints for 5nm nodes extend lead times. Fleet operators exhibit highest price sensitivity due to thousand-unit deployment scales, while OEM captive programs show lowest sensitivity given R&D amortization across vehicle lifecycles.
Supply Chain Analysis
Strategic stockpiling of automotive-grade silicon has displaced just-in-time preferences as Tier-1 suppliers buffer against Taiwan and South Korea foundry allocation volatility. Raw material dependencies center on 300mm silicon wafers, ABF substrate laminates, and rare-earth magnet components for LiDAR actuators. Single-source vulnerability in EUV lithography equipment creates systemic exposure for advanced node production. Distribution runs through direct OEM-Tier-1 contracts with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as domain controller consolidation splinters legacy supplier relationships and creates entry points for specialized AI inference chip designers. Fleet procurement centralization around outcome-based contracting fragments volume concentration previously held by captive OEM programs.
For Market Incumbents: Secure redundant foundry capacity reservations across Taiwan and South Korea to buffer against automotive-grade silicon scarcity threatening production scaling. Defend margin position through backward integration into power distribution unit manufacturing, insulating against commodity volatility in MOSFET and IGBT components. Prioritize ISO/SAE 21434 cybersecurity certification investment to compress 12-18 month compliance timelines blocking competitor platform launches. For New Entrants and Emerging Players: Anchor in edge AI inference acceleration for military and remote mining applications where cloud connectivity constraints previously blocked autonomous deployment. Target India PLI scheme incentives for automotive electronics assembly, leveraging production-linked benefits to undercut established European and Japanese cost structures. Pursue DSRC and C-V2X communication module specialization as German, Japanese, and Chinese infrastructure mandates create aftermarket retrofit demand. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sensor fusion specialists holding established Kalman filter validation pathways but lacking neural processing unit integration capabilities. Five-to-ten year viability hinges on successful architectural transition from deterministic to probabilistic perception pipelines. Watch for inflection when fleet operator outcome-based contracts exceed fifty percent of Tier-1 supplier revenue mix, signaling irreversible commercial risk transfer to hardware vendors.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Safety Certification Investment | UNECE WP.29 compliance timelines compress competitive access for uncertified suppliers. |
| Foundry Capacity Reservation | Taiwan and South Korea node allocation secures production scaling for Level 4 programs. |
| Edge AI Inference Chip Development | Neural processing units unlock military and mining applications blocked by connectivity gaps. |
| India Manufacturing Footprint Expansion | PLI scheme incentives create export capacity for Southeast Asian vehicle markets. |
| V2X Communication Module Specialization | DSRC and C-V2X mandates in Germany, Japan, and China generate aftermarket retrofit demand. |
Study Parameters
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement data anchors the qualitative findings across the autonomous vehicle ECU landscape. Primary interviews with ECU system architects, functional safety validation leads, semiconductor foundry account managers, and fleet operator procurement directors combined with secondary validation from UNECE WP.29 regulatory filings, KBA type approval databases, and IHS Markit vehicle production data. Bottom-up unit economics triangulated against top-down market sizing from semiconductor vendor revenue disclosures.
Sensitivity analysis across automation level adoption curves and foundry capacity expansion scenarios shapes the analytical framework. Segmentation dimensions modeled include component type, technology tier, end-user channel, and application automation level across the projection horizon. CAGRs derive from regression against historical semiconductor content per vehicle trajectories and regulatory approval velocity for Level 3 and Level 4 systems. Industry-specific forecast inputs incorporate LiDAR cost-down curves and V2X infrastructure deployment timelines.
Underlying assumptions cover sustained fleet operator consolidation and stable UNECE WP.29 regulatory frameworks, with deviation risk concentrated in automotive-grade silicon allocation shocks and EU AI Act algorithmic transparency enforcement intensity. Revision becomes warranted when foundry utilization rates for automotive-qualified nodes cross thresholds triggering allocation rationing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Automotive Adaptive Cruise Control Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) System Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Autonomous Taxi Market
Autonomous Vehicles
Europe Autonomous Navigation Market