
 Asia-Pacific Automotive Advanced Driver Assistance Systems Market | 2026-2036
Asia-Pacific Automotive Advanced Driver Assistance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Advanced Driver Assistance Systems Market Outlook
Embedded software engineering talent scarcity across Japan, South Korea, and China is unwinding traditional supplier hierarchies as automakers accelerate in-house algorithm development. Continental AG anchors its regional position through deep radar manufacturing partnerships with domestic OEMs. Robert Bosch GmbH dominates camera-based perception stacks through localized R&D centers in Bangalore and Shanghai. Hyundai Mobis Co Ltd leverages its captive relationship with Hyundai Motor Group to sustain integrated ADAS module shipments across ASEAN assembly plants.
Asia-Pacific automotive advanced driver assistance systems encompass sensor fusion platforms, electronic control units, and actuation hardware that process real-time environmental data to execute semi-autonomous vehicle functions such as adaptive speed regulation and trajectory correction, typically operating on 77 GHz radar frequencies or solid-state lidar arrays with sub-10 centimeter ranging precision. Camera technology leads installed volumes due to cost scalability and computer vision maturity, while lidar adoption concentrates in premium electric vehicle programs where OEMs absorb higher bill-of-materials thresholds. Collision avoidance systems command the largest current revenue pool, though park assist modules face margin compression as ultrasonic sensor commoditization spreads across Chinese tier-2 suppliers.
Japan's METI safety roadmaps, South Korea's KNCAP rating incentives, and China's GB/T standards for advanced driver assistance are collectively mandating baseline autonomous emergency braking across new vehicle categories, forcing component suppliers to certify platforms against divergent test protocols. India's Automotive Industry Standard AIS-145 for electronic stability control and Thailand's impending NCAP alignment with ASEAN harmonized rules are extending compliance obligations into emerging production bases. Stakeholders must monitor regulatory divergence between national type-approval systems when allocating sensor platform development budgets across the region.
Market Dynamics
China's MIIT mandates for automatic emergency braking are compressing deployment timelines and forcing collision avoidance suites into mass-market vehicle segments ahead of supplier readiness cycles.
Growth Catalysts
- Japan's METI safety roadmaps:Mandatory autonomous emergency braking timelines for kei cars and light commercial vehicles are pulling forward sensor procurement schedules across domestic OEMs.
- 77 GHz radar frequency allocation:Harmonized spectrum access across South Korea, Japan, and China enables single-platform sensor designs that slash regional certification costs.
- Passenger fleet renewal:Replacement demand in eastern China's tier-1 cities is concentrating ADAS penetration in vehicles priced below prior premium thresholds.
Market Restraints
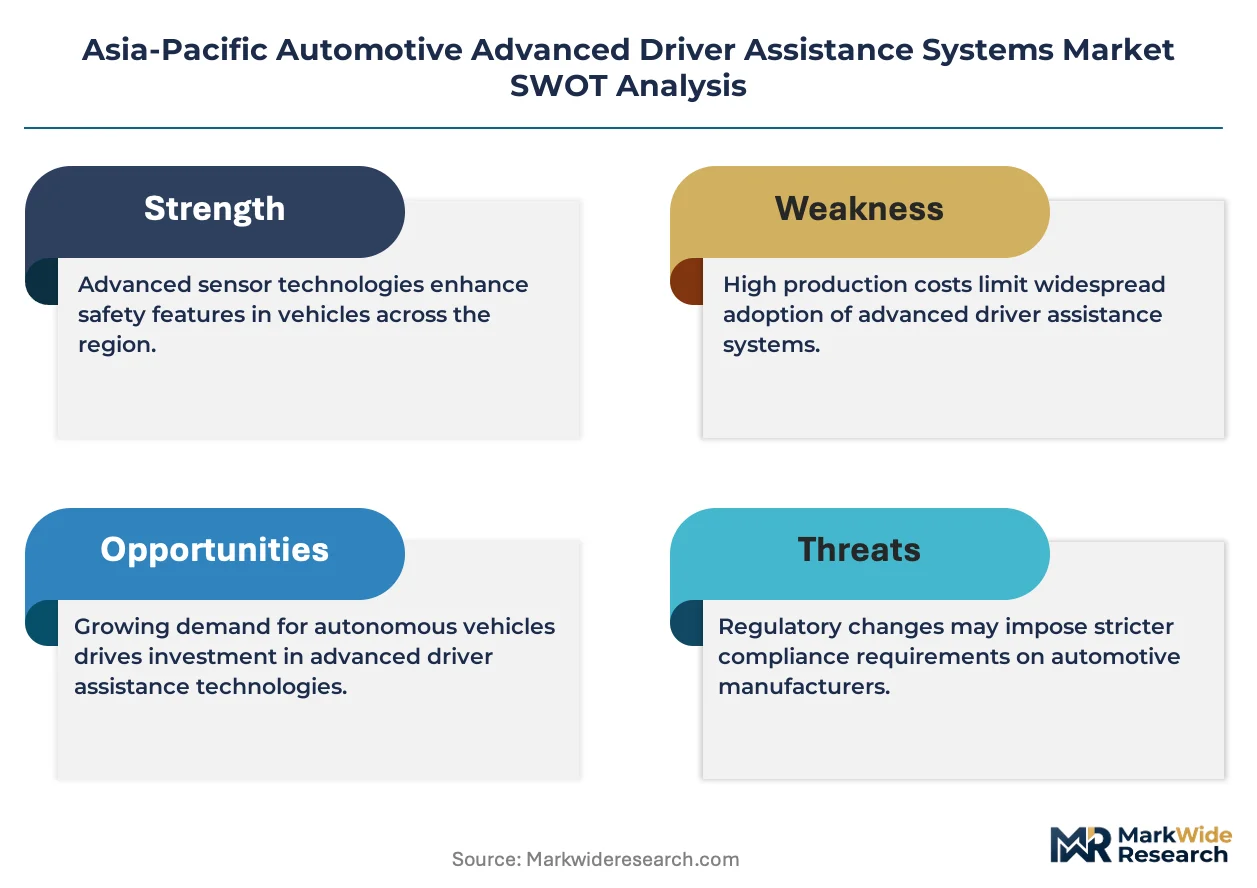
- Semiconductor input volatility:Advanced CMOS image sensor and radar MMIC supply concentrates in Taiwanese foundry capacity, exposing tier-1 suppliers to allocation risk.
- Technical limitation in monocular depth estimation:Camera-only perception stacks fail in low-illumination scenarios, forcing redundant lidar integration that elevates bill-of-materials.
- Regulatory friction from divergent test protocols:China's GB/T standards, Japan's JNCAP, and South Korea's KNCAP employ non-overlapping collision scenarios, multiplying platform validation cycles.
Strategic Opportunities
- India's AIS-145 electronic stability control mandate:Phased implementation through 2025 creates first-mover positioning for sensor suppliers establishing local assembly partnerships.
- Thailand NCAP alignment with ASEAN harmonized rules:Regulatory convergence opens consolidated platform sourcing across emerging ASEAN production bases.
- Camera-lidar fusion convergence:Solid-state lidar cost curves intersecting with neural perception maturity enables mid-tier EV programs to adopt previously premium-only architectures.
Industry Challenges
- Embedded perception engineering scarcity:Algorithm development talent concentrates in Shenzhen, Bangalore, and Seoul, forcing suppliers into compensation wars that compress R&D margins.
- Functional safety certification timelines:ISO 26262 ASIL-D validation for sensor fusion ECUs extends 18-24 months, misaligning with compressed OEM model cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Advanced Driver Assistance Systems Market |
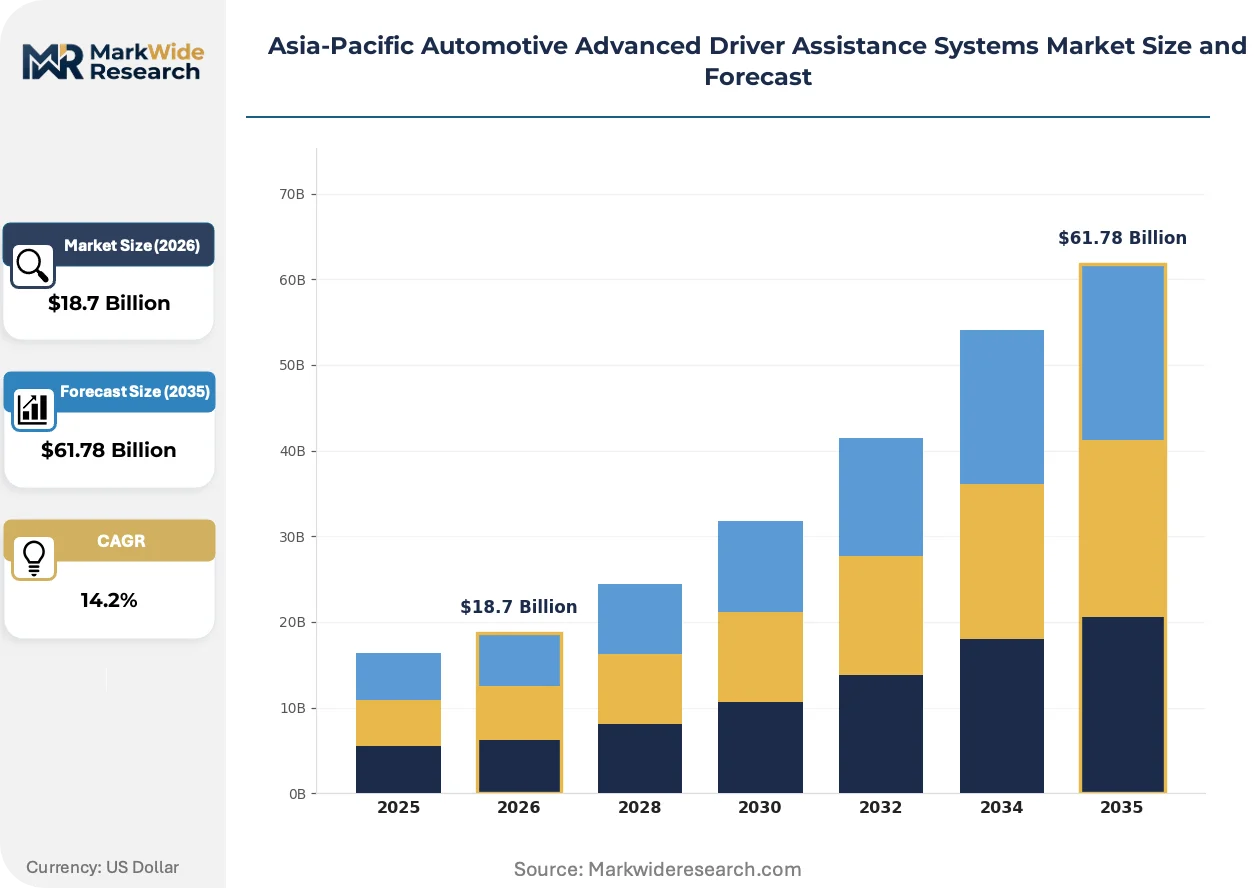
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Lidar, Camera, Ultrasonic System Type: Adaptive Cruise Control, Lane Departure Warning, Park Assist, Collision Avoidance Vehicle Type: Sedan, SUV, Truck, Electric Vehicle End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | DENSO Corporation, Continental AG, Aptiv PLC, Robert Bosch GmbH, ZF Friedrichshafen AG, Hyundai Mobis Co Ltd, Aisin Seiki Co Ltd, Valeo SA, Autoliv Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Advanced Driver Assistance Systems Market Strategic Shifts
Sensor fusion architectures are undergoing rapid recalibration as solid-state lidar cost trajectories intersect with neural network inference efficiency gains on edge compute platforms.
Solid-state lidar is fragmenting traditional mechanical scanning architectures by eliminating moving parts and enabling automotive-grade reliability at sub-premium price points. Chinese EV OEMs in the Yangtze River Delta are integrating these units into volume production programs scheduled for 2025-2026 launch windows. The technology is fragmenting established supplier hierarchies by allowing tier-2 component houses to bypass incumbent mechanical lidar specialists.
China's GB/T standards for advanced driver assistance are mandating baseline autonomous emergency braking across passenger and commercial vehicle categories with phased enforcement beginning 2024. This regulatory compression is forcing foreign suppliers to establish localized testing facilities in Shanghai and Tianjin to achieve type-approval parity with domestic competitors. Premium EV programs are absorbing compliance costs while mass-market ICE platforms face margin compression from mandatory sensor inclusion.
Fleet procurement of integrated ADAS modules is consolidating around captive tier-1 relationships as OEMs prioritize single-source accountability for functional safety liability. Japanese and South Korean automakers are favoring module suppliers with in-house algorithm stacks over discrete component vendors, compressing opportunities for pure-play sensor manufacturers. This pattern concentrates most visibly in Thailand's eastern seaboard assembly corridor where Hyundai and Toyota operate integrated supplier parks.
Asia-Pacific Automotive Advanced Driver Assistance Systems Market Segmentation
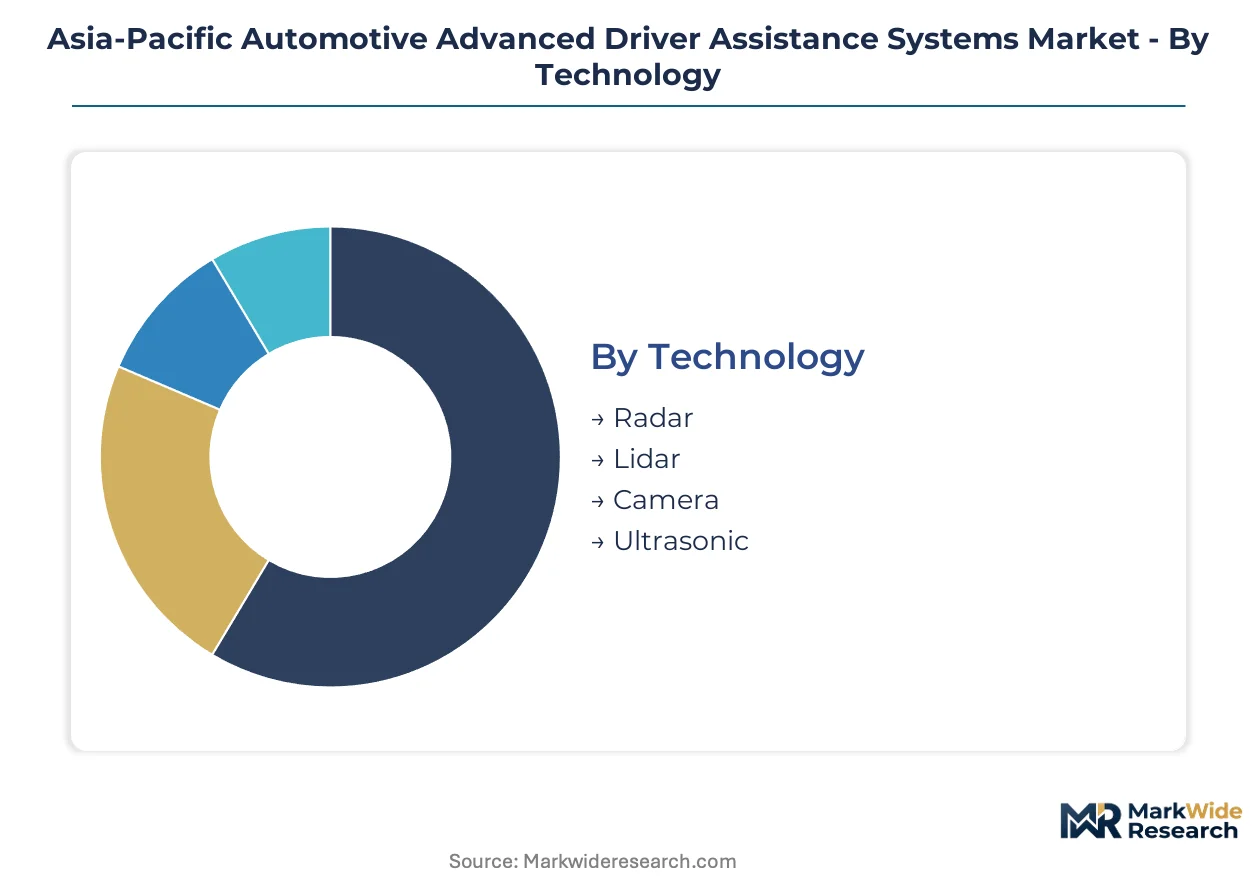
Technology choices in Asia-Pacific ADAS deployment carry irreversible cost commitments. Sensor platform decisions made at vehicle architecture stage lock suppliers into decade-long procurement relationships.
Technology:
Camera modules face substitution pressure from solid-state lidar as neural perception efficiency closes the cost-performance gap.
- Radar:77 GHz frequency architectures dominate highway-speed adaptive cruise applications. Procurement concentrates among South Korean and Japanese OEMs seeking single-platform regional certification against METI and KNCAP protocols.
- Lidar:Solid-state arrays eliminate mechanical scanning components for automotive-grade reliability. Yangtze River Delta EV programs absorb these units as Chinese OEMs pursue premium perception differentiation.
- Camera:CMOS image sensors deliver cost-scalable computer vision for lane-keeping and traffic sign recognition.
- Ultrasonic:Parking proximity detection relies on commodity sensor arrays with compressed margins across Chinese tier-2 suppliers.
Camera retains volume leadership; lidar holds the steepest expansion curve.
System Type:
Cost tier separation determines which suites penetrate mass-market segments versus remaining captive to premium vehicle lines.
- Adaptive Cruise Control:Radar-camera fusion platforms regulate longitudinal speed relative to forward traffic. Demand clusters in Japan's expressway-dense vehicle fleet where METI mandates accelerate deployment.
- Collision Avoidance:Automatic emergency braking suites integrate multi-sensor fusion for pedestrian and vehicle detection. China's MIIT mandates compress deployment timelines across domestic and foreign supplier bases.
- Lane Departure Warning:Camera-based edge detection triggers haptic steering feedback.
- Park Assist:Ultrasonic and camera fusion enables automated maneuvering in constrained spaces.
Collision avoidance commands current revenue concentration; adaptive cruise control scales most rapidly across mid-tier vehicle programs.
Vehicle Type:
Application intensity varies sharply across powertrain architectures and body styles.
- Electric Vehicle:Battery-electric platforms integrate ADAS as standard equipment to justify premium positioning. Eastern China tier-1 city replacement demand concentrates penetration in vehicles below prior luxury price thresholds.
- SUV:Higher ride heights and family-oriented positioning drive sensor suite penetration for highway safety. South Korean OEMs prioritize these segments for export competitiveness against European rivals.
- Sedan:Traditional three-box configurations retain volume production in ASEAN assembly corridors.
- Truck:Commercial fleet operators specify collision avoidance for liability reduction and driver retention.
SUV maintains installed base dominance; electric vehicle gains share fastest as platform architectures converge.
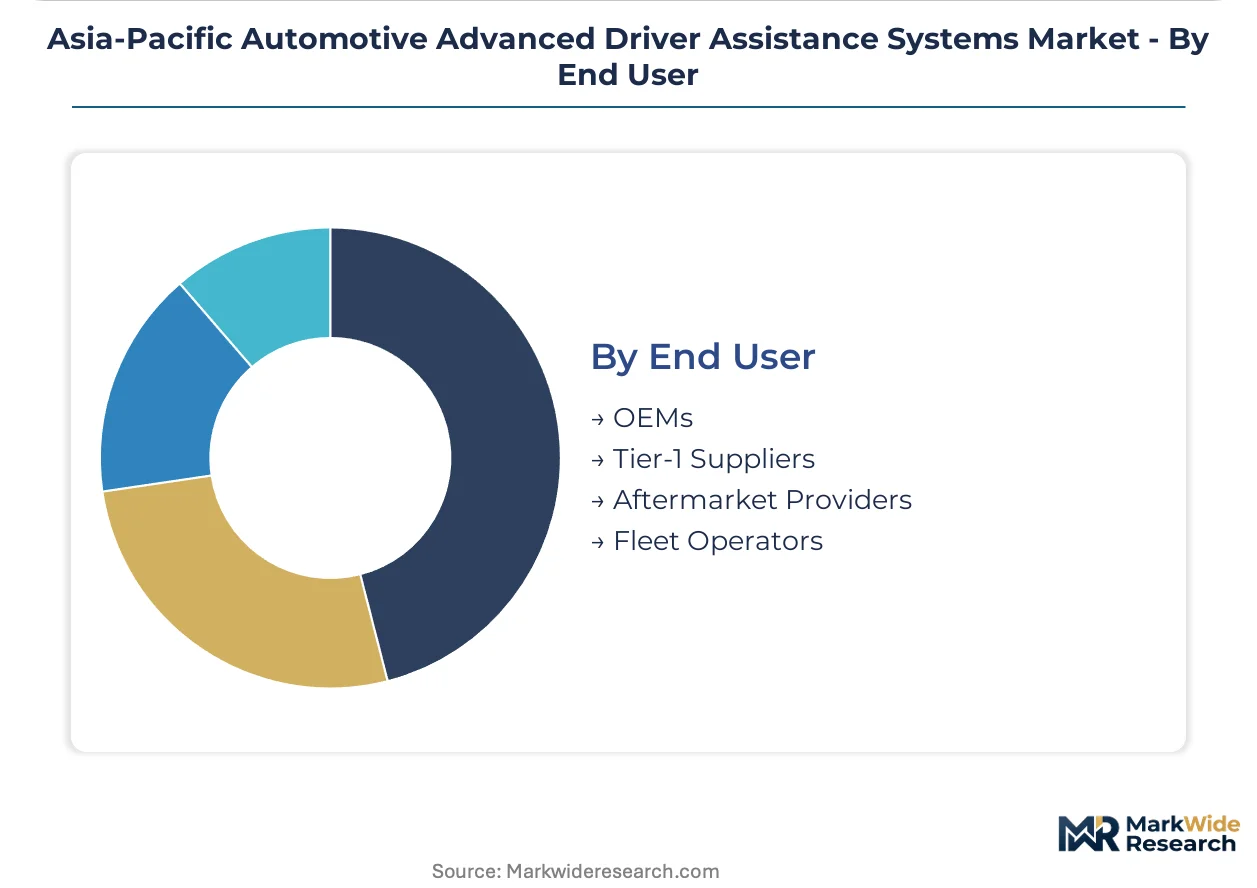
End User:
Customer type dictates liability structures and procurement accountability requirements.
- OEMs:Vehicle manufacturers source integrated modules with single-source functional safety accountability. Japanese and South Korean automakers favor suppliers with captive algorithm stacks over discrete component vendors.
- Tier-1 Suppliers:System integrators consolidate sensor fusion and ECU production for OEM direct supply. Thailand's eastern seaboard assembly corridor concentrates these relationships in integrated supplier parks.
- Fleet Operators:Commercial vehicle buyers specify ADAS for insurance premium reduction and regulatory compliance.
- Aftermarket Providers:Retrofit installation serves vehicle parc extension in price-sensitive segments.
OEMs retain procurement volume leadership; tier-1 suppliers capture the steepest margin expansion as module integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Japan and South Korea exceeds that in Southeast Asian assembly corridors by substantial margins, reflecting tier-1 supplier concentration and captive OEM relationships versus emerging market cost competition.
China
Eastern China tier-1 cities generate replacement demand for vehicles below prior luxury price thresholds. MIIT mandates for automatic emergency braking compress deployment timelines across domestic and foreign supplier bases. Shanghai and Tianjin host localized testing facilities where foreign suppliers achieve type-approval parity with domestic competitors.
Japan
METI safety roadmaps mandate autonomous emergency braking timelines for kei cars and light commercial vehicles. JNCAP test protocols diverge from regional standards, multiplying platform validation cycles for suppliers. Kanto region OEMs accelerate sensor procurement schedules through deep radar manufacturing partnerships.
South Korea
KNCAP rating incentives pull forward sensor procurement schedules across domestic OEMs. 77 GHz radar frequency allocation harmonizes with Japan and China, enabling single-platform sensor designs. Seoul Capital Area suppliers dominate camera-based perception stacks through localized R&D centers.
India
Automotive Industry Standard AIS-145 for electronic stability control creates first-mover positioning for sensor suppliers. Phased implementation through 2025 forces establishment of local assembly partnerships. Maharashtra and Gujarat assembly corridors concentrate procurement from tier-1 suppliers seeking cost-competitive module sourcing.
Thailand
Impending NCAP alignment with ASEAN harmonized rules extends compliance obligations into emerging production bases. Eastern seaboard assembly corridor concentrates integrated supplier parks where Hyundai and Toyota operate. Bangkok-based procurement offices consolidate module sourcing across ASEAN vehicle export hubs.
Asia-Pacific Automotive Advanced Driver Assistance Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium perception stacks coexist with mass-market sensor commoditization. The market consolidates around captive tier-1 relationships as OEMs prioritize single-source accountability for functional safety liability. Three archetypes dominate: integrated module suppliers with in-house algorithm stacks, discrete component vendors facing margin compression, and emerging solid-state lidar specialists disrupting mechanical scanning incumbents. Strategic moves center on backward integration into semiconductor supply and geographic expansion through localized testing facilities.
Among Japanese and German integrated module suppliers, DENSO Corporation and Continental AG exemplify the captive tier-1 archetype through deep OEM relationships. Robert Bosch GmbH occupies a position representing the algorithm-integrated perception stack specialist, anchoring regional R&D investment patterns.
| Leading Market Players |
|---|
| DENSO Corporation |
| Continental AG |
| Aptiv PLC |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Hyundai Mobis Co Ltd |
| Aisin Seiki Co Ltd |
| Valeo SA |
| Autoliv Inc |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month ISO 26262 ASIL-D certification cycles compress supplier pricing power while concentrating procurement leverage among Japanese and South Korean OEMs with captive tier-1 relationships. This lead-time rigidity forces component vendors to absorb upfront validation costs, widening spreads between integrated module suppliers and discrete sensor vendors across the Asia-Pacific procurement landscape.
Pricing Analysis
Price spreads between Japan's Kanto region supplier parks and Thailand's eastern seaboard assembly corridors exceed factor-of-two differentials for equivalent radar-camera fusion modules. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified platforms from KNCAP-validated mid-tier systems and commodity ultrasonic park-assist arrays. Pricing pressure stems from Chinese tier-2 suppliers flooding ultrasonic sensor markets with undifferentiated hardware. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership procurement models, while premium EV programs absorb certification premiums for perception differentiation.
Supply Chain Analysis
Inventory buffers for 77 GHz radar MMICs and advanced CMOS image sensors stretch to six-month coverage as Taiwanese foundry allocation constraints persist. Semiconductor feedstock draws from Taiwan, South Korea, and Japan, while solid-state lidar final assembly concentrates in China's Yangtze River Delta. Single-source vulnerability around radar MMIC supply exposes tier-1 suppliers to foundry allocation risk during demand surges. Distribution runs through integrated supplier parks in Thailand and eastern China where Hyundai and Toyota consolidate module sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific ADAS market is recovering from semiconductor allocation troughs as passenger fleet renewal accelerates across eastern China's tier-1 cities. OEM procurement intensity is rebounding with MIIT mandate compliance deadlines compressing order cycles.
For Market Incumbents: Compound defensive positioning through backward integration into radar MMIC supply and captive algorithm stack development. Solid-state lidar specialists threaten mechanical scanning incumbents with sub-premium price points. Priority lever rests on accelerating ISO 26262 certification pipelines to match compressed OEM model cycles. For New Entrants and Emerging Players: China's GB/T type-approval fast-track offers entry pathway for foreign suppliers establishing Shanghai testing facilities. Mass-market ICE platforms present most penetrable segment as mandatory sensor inclusion forces margin compression among established vendors. Go-to-market angle centers on localized validation partnerships with domestic OEMs seeking AEB compliance ahead of enforcement windows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state lidar sub-segments as Chinese EV programs scale volume procurement. Five-to-ten year viability favors suppliers with dual capability in perception software and automotive-grade hardware manufacturing. Acquisition target archetype combines neural perception IP with established tier-1 OEM relationships. Signal to watch is divergence between KNCAP and JNCAP test protocol alignment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | 77 GHz radar designs harmonized across METI and KNCAP protocols slash regional certification costs for South Korean suppliers. |
| Software-Defined Vehicle Investment | Neural perception efficiency gains on edge compute platforms enable camera-lidar fusion in mid-tier EV programs. |
| Geographic Manufacturing Footprint | Thailand's eastern seaboard supplier parks consolidate ASEAN sourcing for Hyundai and Toyota module procurement. |
| Backward Integration | Captive radar MMIC production insulates tier-1 suppliers from Taiwanese foundry allocation volatility. |
| Regulatory Compliance Fast-Track | Localized GB/T testing facilities in Shanghai achieve type-approval parity for foreign collision avoidance suite vendors. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with tier-1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; and secondary validation against vehicle production databases, IHS Markit registration data, MIIT type-approval filings, and KNCAP test protocol documentation. Bottom-up sensor shipment estimates triangulated against top-down OEM ADAS penetration assumptions across the analysis window.
Across the modeling period, forecasts segmented by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from regression against historical ADAS penetration curves and regulatory mandate enforcement schedules. Industry-specific inputs included 77 GHz radar frequency allocation harmonization status and solid-state lidar cost trajectory assumptions.
Decision-makers should treat outputs as directional under stable semiconductor foundry allocation and regulatory timeline assumptions; material deviation would warrant model refresh. Specific risks include JNCAP-KNCAP protocol divergence prolonging validation cycles and Chinese tier-2 supplier price erosion in ultrasonic segments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Automotive Adaptive Cruise Control Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Autonomous Taxi Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market