
 Europe IoT Connected Cars Market | 2026-2036
Europe IoT Connected Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IoT Connected Cars Market Intelligence
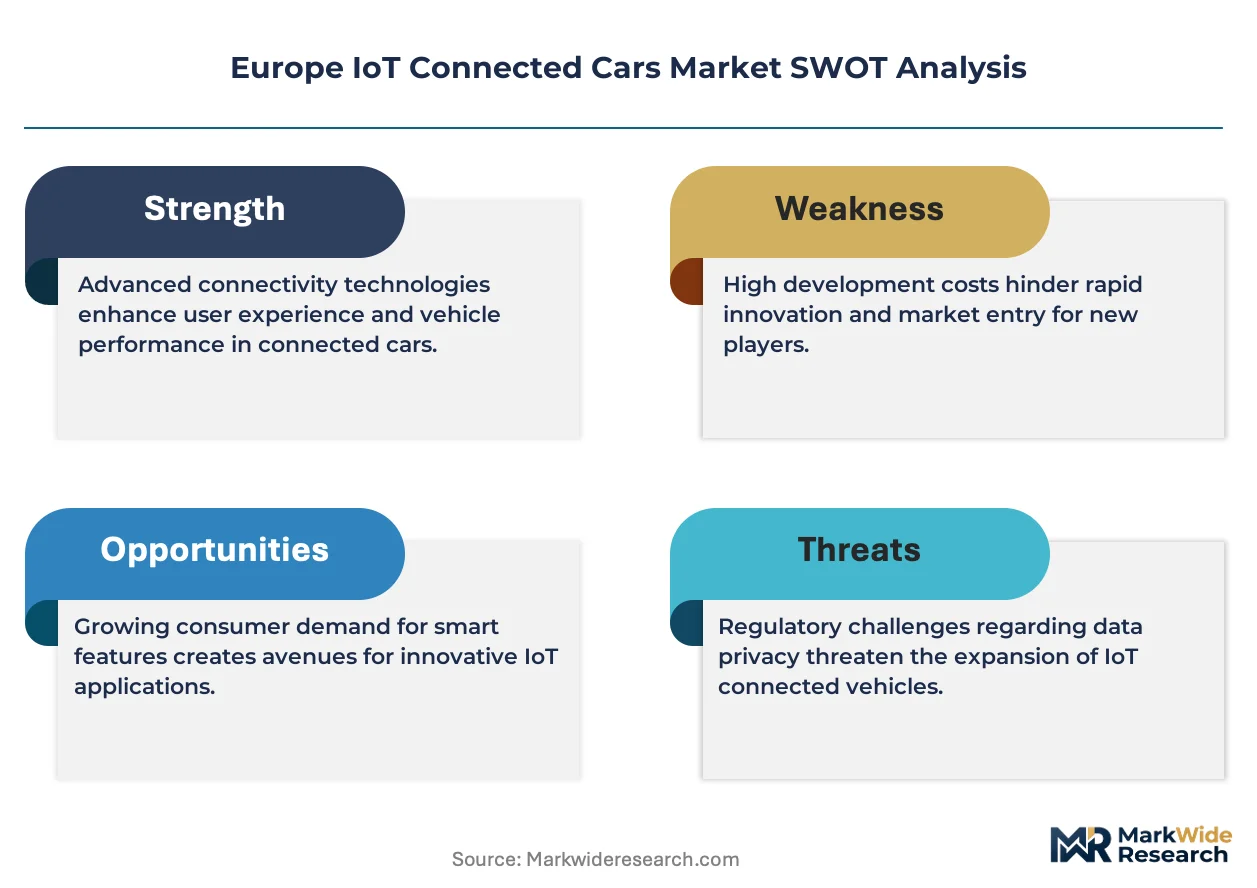
The EU Cyber Resilience Act is restructuring the cost-of-entry calculus for connected car platforms by mandating continuous security updates and vulnerability disclosure across the vehicle lifecycle. Continental AG leverages its integrated hardware-software stack to sustain compliance without fragmenting its supply chain. Robert Bosch GmbH anchors its position through deep manufacturing scale in powertrain and chassis electronics that feed directly into IoT-enabled architectures. NXP Semiconductors specializes in secure element and V2X chipset design, giving it narrow but defensible control over authentication layers.
Europe IoT Connected Cars encompass vehicles equipped with embedded sensors, telematics control units, and wireless transceivers operating across cellular, Wi-Fi, and Dedicated Short Range Communications protocols to enable real-time data exchange with infrastructure, other vehicles, and cloud platforms. These systems primarily serve commercial purposes including fleet optimization, predictive maintenance scheduling, and traffic flow coordination. Cellular connectivity currently dominates installed base economics due to mature carrier infrastructure across the continent, while Dedicated Short Range Communications is gaining regulatory traction for low-latency safety applications. Fleet Management applications capture the deepest margin pools among end-use segments because recurring SaaS revenue attaches to hardware sales.
EMA, ECHA, and the EU AI Act collectively shape product standards by requiring algorithmic transparency in automated driving functions and restricting hazardous substances in onboard electronics. REACH compliance adds material traceability costs that filter down to module suppliers and semiconductor fabricators. Stakeholders must decide whether to build in-house over-the-air update infrastructure or outsource to telecommunication companies before regulatory deadlines harden competitive gaps.
Market Dynamics
The EU Cyber Resilience Act is forcing fleet operators and OEMs to re-architect their software supply chains around continuous security validation, compressing development timelines while expanding compliance budgets across the vehicle lifecycle.
Growth Catalysts
- Fleet optimization demand:Commercial operators in Germany and France are deploying telematics at scale to reduce fuel consumption and unplanned downtime, creating recurring SaaS revenue pools that subsidize hardware costs.
- EU AI Act algorithmic transparency mandates:Automated driving function disclosures are accelerating investment in explainable AI frameworks, pulling Tier-1 suppliers into closer co-development with OEMs.
- V2X infrastructure rollout:Dedicated Short Range Communications deployment across Dutch and Belgian highway corridors is enabling low-latency safety applications that cellular networks cannot match.
Market Restraints
- Semiconductor supply concentration:Secure element and V2X chipset fabrication remains concentrated in a limited number of Asian foundries, exposing European module suppliers to geopolitical disruption risk.
- REACH material traceability costs:Hazardous substance restrictions in onboard electronics are filtering compliance burdens down to semiconductor fabricators, raising bill-of-materials costs for telematics control units.
- Cybersecurity certification timeline friction:The EU Cyber Resilience Act's vulnerability disclosure requirements are extending product validation cycles before market entry, delaying revenue recognition for platform developers.
Strategic Opportunities
- Polish and Romanian fleet underpenetration:Eastern European commercial vehicle operators lag Western counterparts in telematics adoption, presenting first-mover expansion potential for hardware-software bundle providers.
- Over-the-air update infrastructure outsourcing:Telecommunication carriers are positioning to capture recurring revenue streams from OEMs electing not to build in-house OTA capabilities before regulatory deadlines harden.
- Cellular-V2X convergence:Hybrid connectivity architectures blending 5G latency improvements with DSRC reliability are opening new application categories in cooperative intelligent transport systems.
Industry Challenges
- Embedded systems cybersecurity talent scarcity:The intersection of automotive engineering and cryptographic protocol design remains sparsely populated, forcing OEMs to compete for limited specialists against fintech and defense sectors.
- Legacy fleet integration complexity:Retrofitting connected capabilities onto existing commercial vehicle populations requires bridging incompatible electrical architectures without full platform replacement.
- Cross-border data sovereignty fragmentation:Divergent national implementations of GDPR vehicle data provisions are complicating centralized fleet management platform deployment across multi-country operator networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IoT Connected Cars Market |
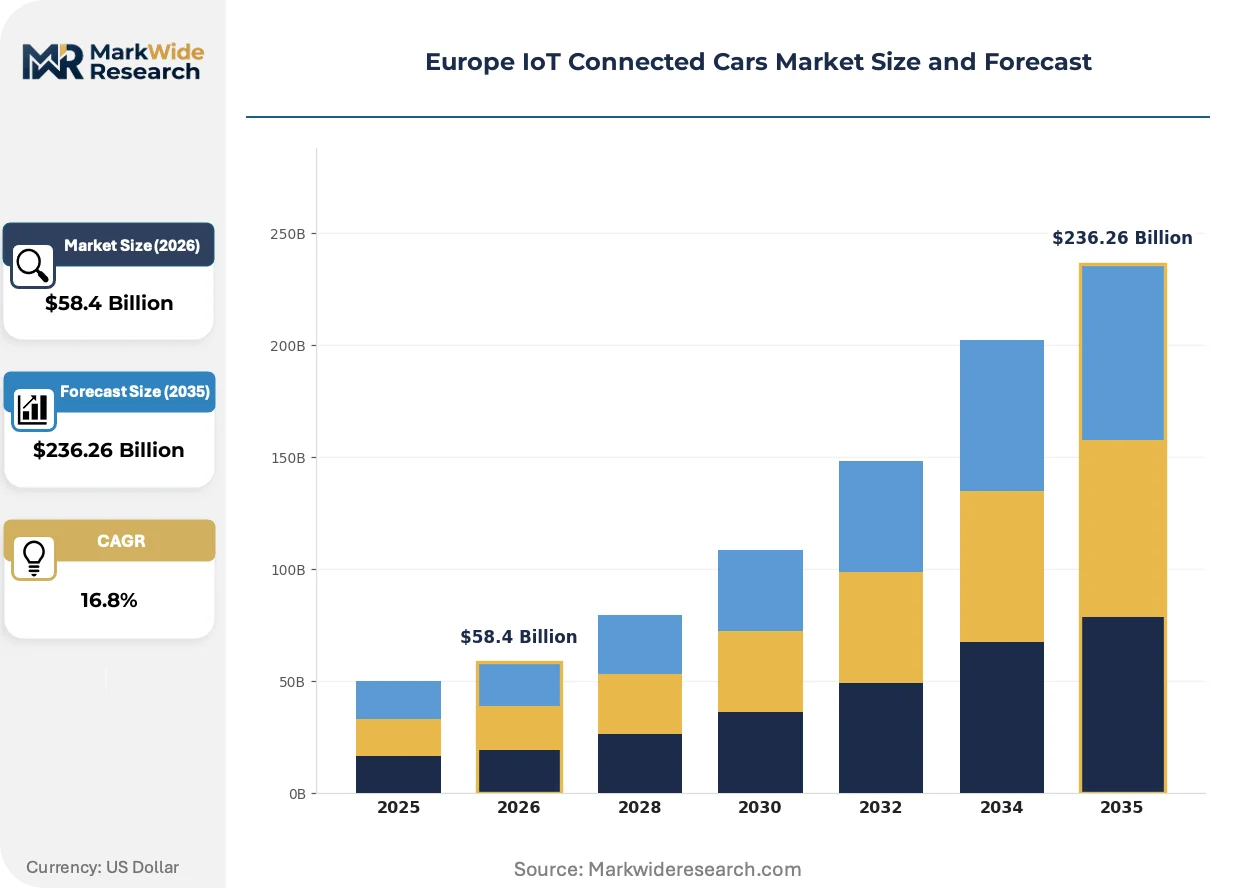
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $236.26 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connectivity Technology: Cellular, Wi-Fi, Dedicated Short Range Communications, Satellite, Bluetooth, Zigbee Application: Fleet Management, Predictive Maintenance, Vehicle Tracking, Infotainment Services, Remote Diagnostics, Traffic Management Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles, Autonomous Vehicles End User: OEMs, Insurance Providers, Government Agencies, Telecommunication Companies, Ride-Hailing Firms |
| Companies Covered | Continental AG, Robert Bosch GmbH, Harman International, Denso Corporation, NXP Semiconductors, Qualcomm Technologies, TomTom N.V., Volkswagen Group, Infineon Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IoT Connected Cars Market Strategic Shifts & Innovations
Edge computing migration is redistributing computational load from centralized cloud platforms toward vehicle-mounted processors, altering hardware specifications and supplier power dynamics simultaneously.
Software-defined vehicle architectures are automating the decoupling of hardware refresh cycles from feature upgrade timelines. German OEMs are adopting zonal electronic control unit designs that enable functional updates without physical module replacement. This shift is automating the compression of traditional Tier-1 supplier value capture, as OEMs assume direct control over middleware and application layers previously outsourced.
The EU Cyber Resilience Act's vulnerability disclosure mandates are restructuring procurement specifications for in-vehicle systems. Fleet operators now require documented secure development lifecycle evidence before contract award, disqualifying suppliers without established incident response protocols. Commercial vehicle segments in France and the Netherlands are responding fastest, embedding these requirements into multi-year service agreements.
Outcome-based fleet management contracts are displacing traditional hardware-plus-subscription pricing in European commercial vehicle markets. Logistics operators in the Rhine-Ruhr corridor are contracting for guaranteed uptime percentages rather than purchasing telematics units outright, transferring operational risk to platform providers. This model concentrates most visibly among temperature-controlled freight operators where cargo integrity failures carry severe liability exposure.
Europe IoT Connected Cars Market Segmentation
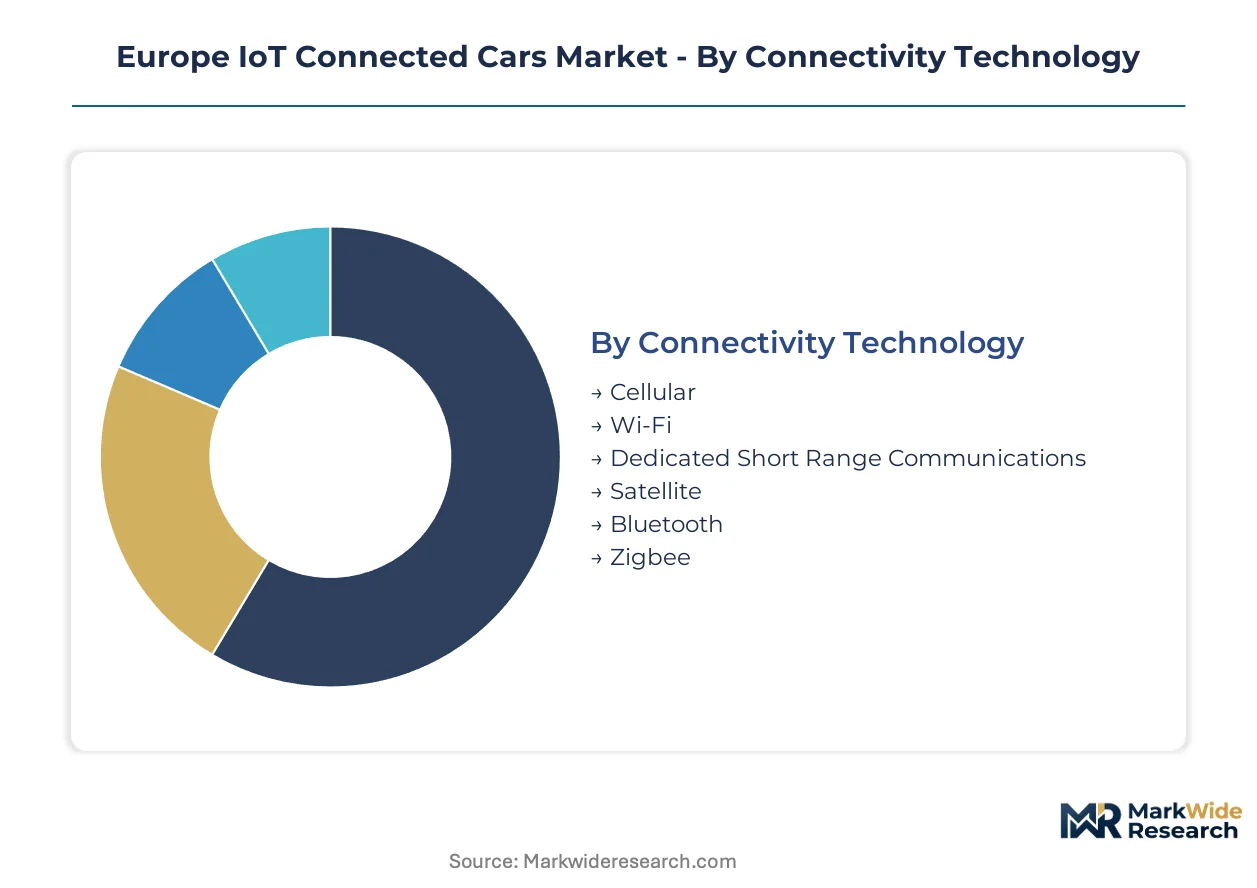
Segmentation in Europe IoT Connected Cars reveals how procurement priorities diverge across fleet operators, OEMs, and infrastructure planners. Connectivity choices determine regulatory compliance pathways, while application focus shapes whether vendors capture hardware margins or recurring SaaS revenue.
Connectivity Technology:
Fleet procurement teams weigh latency requirements against carrier infrastructure maturity when selecting communication protocols.
- Cellular:Mature 4G and expanding 5G networks across Germany, France, and the Netherlands deliver reliable wide-area coverage for telematics and over-the-air updates. German logistics corridors running Cologne-Düsseldorf-Dortmund deploy cellular-connected fleets at scale, prioritizing predictable data costs over millisecond latency.
- Dedicated Short Range Communications:Low-latency direct vehicle-to-vehicle and vehicle-to-infrastructure communication enables cooperative collision avoidance without network dependency. Dutch and Belgian highway authorities are prioritizing DSRC deployment along Antwerp-Rotterdam freight routes where cellular handoff gaps create safety risks.
- Wi-Fi:Short-range high-bandwidth protocol serving infotainment content offload and depot-based fleet diagnostics.
- Satellite:Backhaul connectivity for remote rural corridors and cross-border Alpine transit where terrestrial coverage fails.
- Bluetooth:Smartphone pairing and proximity-based vehicle access control in consumer-facing applications.
- Zigbee:Low-power mesh networking for in-vehicle sensor clusters and tire pressure monitoring systems.
Volume sits with Cellular; growth tilts toward Dedicated Short Range Communications.
Application:
Commercial vehicle operators segment their spending between operational efficiency tools and liability-reduction systems.
- Fleet Management:Real-time vehicle location, driver behavior scoring, and fuel consumption analytics delivered through telematics control units. French and German temperature-controlled freight operators in the Rhine corridor are contracting for guaranteed uptime percentages, transferring operational risk to platform providers.
- Predictive Maintenance:Sensor-driven component health monitoring that schedules service before failures strand vehicles. Commercial fleets operating across Poland and Romania are adopting predictive systems fastest where roadside assistance infrastructure remains sparse.
- Vehicle Tracking:Asset recovery and route verification for high-value cargo and leased equipment.
- Infotainment Services:Streaming content, navigation, and concierge functions targeting premium passenger segments.
- Remote Diagnostics:Over-the-air fault code reading and parameter adjustment reducing workshop visits.
- Traffic Management:Cooperative intelligent transport systems feeding anonymized flow data to municipal authorities.
Revenue concentrates in Fleet Management; Predictive Maintenance is gaining share fastest.
Vehicle Type:
Electrification mandates and automation roadmaps are restructuring which vehicle categories justify connected system investment.
- Passenger Cars:High-volume segment where connectivity packages differentiate trim levels and enable subscription revenue. German OEMs are embedding cellular modules as standard equipment to satisfy EU Cyber Resilience Act update requirements.
- Electric Vehicles:Battery state-of-health monitoring and charging station coordination create mandatory connectivity for range assurance. Dutch fleet operators deploying EVs across the Randstad urban corridor require real-time charge point availability data.
- Commercial Vehicles:Heavy-duty trucks and vans where downtime costs dominate procurement calculations.
- Luxury Vehicles:Premium positioning justifies higher sensor counts and concierge service integration.
- Autonomous Vehicles:Development fleets requiring redundant connectivity for remote monitoring and regulatory data logging.
Passenger Cars dominate installed base; Electric Vehicles show the steepest expansion trajectory.
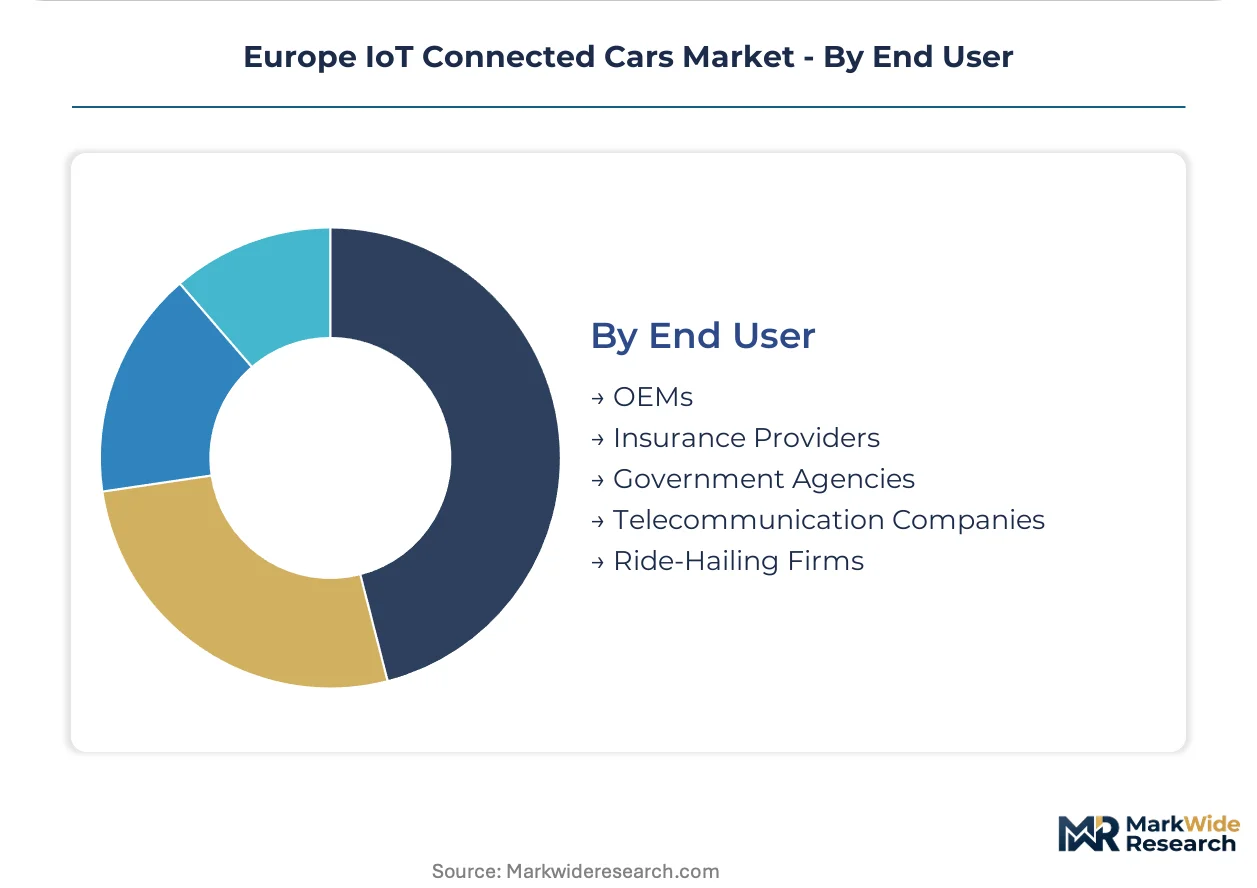
End User:
Buyer sophistication varies sharply between automotive incumbents and adjacent sector entrants.
- OEMs:Integrated vehicle manufacturers designing zonal electronic architectures that internalize middleware control. German OEMs are assuming direct software stack ownership previously outsourced to Tier-1 suppliers.
- Telecommunication Companies:Carriers positioning to capture recurring revenue from OEMs outsourcing over-the-air update infrastructure before EU Cyber Resilience Act deadlines harden.
- Insurance Providers:Usage-based policy pricing requiring granular driving behavior data streams.
- Government Agencies:Traffic authorities and regulatory bodies mandating V2X deployment for safety-critical corridors.
- Ride-Hailing Firms:Mobility platforms optimizing asset utilization through real-time demand matching and predictive repositioning.
Procurement volume rests with OEMs; Telecommunication Companies are capturing the fastest-growing revenue pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across Germany's automotive corridor concentrate connected vehicle development, with tax incentives and co-location benefits drawing Tier-1 suppliers alongside OEM engineering centers.
Germany
Fleet operators in the Rhine-Ruhr corridor contract for guaranteed uptime percentages, transferring operational risk to platform providers. The EU Cyber Resilience Act mandates continuous security updates across the vehicle lifecycle, compressing development timelines for domestic module suppliers. Stuttgart anchors powertrain electronics manufacturing, where Bosch and Continental co-locate production with zonal architecture engineering teams.
France
Temperature-controlled freight operators in the Île-de-France region embed cybersecurity requirements directly into multi-year service agreements. ANSM and CNIL guidance on vehicle data processing shapes procurement specifications for telematics platforms. The Lyon-Saint-Étienne corridor hosts specialized predictive maintenance software clusters serving cross-border logistics networks.
Netherlands
Dutch fleet operators deploying electric vehicles across the Randstad urban corridor require real-time charge point availability data integration. Dedicated Short Range Communications deployment along Antwerp-Rotterdam freight routes enables cooperative collision avoidance where cellular handoff gaps create safety risks. Eindhoven's semiconductor ecosystem feeds secure element design into V2X chipset development.
Poland
Eastern European commercial vehicle operators lag Western counterparts in telematics adoption, presenting first-mover expansion potential for hardware-software bundle providers. REACH compliance adds material traceability costs that filter down to module suppliers assembling in Silesian industrial zones. The Warsaw-Łódź corridor attracts logistics operators retrofitting connected capabilities onto legacy fleet populations.
Belgium
Cross-border freight operators face data sovereignty fragmentation as divergent national GDPR implementations complicate centralized fleet management. Belgian highway authorities prioritize DSRC deployment along freight corridors connecting Dutch ports to German manufacturing centers. Antwerp's port logistics ecosystem drives demand for asset recovery and route verification systems in high-value cargo segments.
Europe IoT Connected Cars Market Key Industry Players
German producers anchor one tier through integrated hardware-software stacks and deep manufacturing scale; Dutch and Belgian specialists hold positions in secure element design and V2X chipset architecture. The vendor base clusters around three strategic archetypes: full-stack platform providers, semiconductor authentication specialists, and telematics service aggregators. Dominant competitive moves include strategic partnerships between OEMs and telecommunications carriers for over-the-air infrastructure, plus portfolio diversification into predictive maintenance software.
Within the integrated platform tier, Continental AG and Robert Bosch GmbH exemplify German engineering conglomerates with captive electronics manufacturing. NXP Semiconductors occupies a specialized position in secure authentication layers, representing the narrow-but-defensible archetype in V2X chipset supply. These three anchors illustrate how compliance with the EU Cyber Resilience Act is restructuring procurement specifications, with documented secure development lifecycle evidence now required before contract award.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Harman International |
| Denso Corporation |
| NXP Semiconductors |
| Qualcomm Technologies |
| TomTom N.V. |
| Volkswagen Group |
| Infineon Technologies |
| Others |
Cost & Logistics Intelligence
Silicon wafer spot prices cascade through European telematics module production, compressing margins for Tier-2 suppliers while OEMs with captive semiconductor sourcing maintain pricing power across subscription tiers.
Pricing Analysis
Lead-time premiums separate urgent procurement from scheduled volume commitments in connected car platform contracting. Three-tier pricing structure across premium, standard, and economy levels stratifies by cybersecurity certification grade and OTA infrastructure bundling. Cost compression in economy telematics units intensifies because REACH material traceability burdens filter to module assemblers. Fleet operators in Poland and Romania exhibit highest price sensitivity; German temperature-controlled freight carriers prioritize guaranteed uptime over per-unit hardware costs.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for V2X chipset and secure element delivery across the continent. Secure element fabrication concentrates in Taiwan, South Korea, and the Netherlands; telematics control unit assembly clusters in Germany, Poland, and Romania. The supply chain draws from silicon wafers, automotive-grade memory modules, and ceramic substrate materials. Single-source vulnerability in secure element foundry capacity exposes European module suppliers to geopolitical disruption. Distribution runs through Tier-1 supplier consolidation points before final OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secure element foundry capacity constraints prop pricing power for semiconductor authentication specialists, sustaining margin pools even as telematics hardware commoditizes.
For Market Incumbents: Anticipate margin compression in standardized telematics hardware as Polish and Romanian fleet operators drive volume procurement. Defensive consolidation through backward integration into secure element sourcing reduces exposure to Asian foundry concentration. Prioritize certification investment in EU Cyber Resilience Act compliance documentation to disqualify emerging competitors lacking established incident response protocols. For New Entrants and Emerging Players: Telecommunication carriers offer the most accessible channel partnership for OTA infrastructure outsourcing, bypassing OEM direct sales complexity. White-space targets concentrate in predictive maintenance software for Eastern European commercial fleets and DSRC-enabled safety systems for Dutch-Belgian freight corridors. A hardware-software bundle go-to-market angle penetrates underpenetrated Polish and Romanian operator segments faster than pure platform plays. For Investors and Strategic Acquirers: Distressed-cycle entries favor narrow-but-defensible semiconductor authentication specialists in the Netherlands with established V2X chipset roadmaps. Long-term viability across the analysis window hinges on regulatory compliance capability rather than scale alone. Watch DSRC infrastructure deployment acceleration along Antwerp-Rotterdam corridors as the inflection signal for cooperative intelligent transport system adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Zonal ECU architectures enable German OEMs to internalize middleware control previously outsourced. |
| Battery Supply Agreement | Electric vehicle fleet operators in the Randstad corridor require guaranteed charge point data integration. |
| Platform Standardization | Cellular-V2X convergence architectures reduce supplier fragmentation across cooperative safety applications. |
| Geographic Manufacturing Footprint | Silesian industrial zones in Poland attract module assembly investment serving Eastern European fleet expansion. |
| Charging Infrastructure Partnership | Dutch fleet electrification depends on real-time charge point availability data bundled with telematics subscriptions. |
Research Approach
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, telecommunication carrier IoT strategists, and fleet operations managers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from vehicle production databases, EU regulatory filings, customs trade records, and semiconductor supply chain disclosures establishes segment boundaries. Bottom-up unit economics triangulate against top-down market sizing across connectivity technology, application, and vehicle type dimensions.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the projection horizon. Segmentation modeling spans connectivity protocol, application purpose, vehicle propulsion architecture, and end-user buyer archetype. CAGRs derive from fitted growth curves calibrated to fleet penetration rates, regulatory compliance deadlines, and infrastructure deployment schedules. Forecast inputs incorporate DSRC corridor activation timelines and EU Cyber Resilience Act implementation phases.
Caveats apply where semiconductor supply disruption, abrupt regulatory enforcement acceleration, or cross-border data sovereignty rulings could materially shift the outlook. Forecasts reflect documented assumptions about fleet replacement cycles and electrification mandates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Global Driverless Car Market