
 Greece Autonomous Navigation Market | 2026-2036
Greece Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Greece Autonomous Navigation Market Insights
Defense procurement channels in Greece are reconfiguring around NATO-aligned autonomous systems requirements. Thales Group leverages its established Hellenic naval electronics footprint to anchor long-term service contracts. Raytheon Technologies competes through integrated command-and-control architectures tailored for Aegean maritime patrol. Safran sustains positioning in avionics-guided navigation for Hellenic Air Force modernization programs.
Autonomous navigation encompasses self-directed positioning and routing systems that fuse sensor arrays, inertial measurement units, and real-time kinematic corrections to achieve sub-meter accuracy without continuous human intervention. The technology serves commercial shipping, defense platforms, and unmanned aerial systems by reducing crew dependency while enhancing route efficiency in GPS-denied environments. Hardware segments dominate installed value, though software layers capturing machine learning-based path optimization command expanding margin pools. Maritime applications within the end-user matrix lead absolute spending, reflecting Greece's archipelagic geography and the operational urgency of automated ferry services across island chains.
Hellenic regulatory alignment with EASA drone frameworks and the EU MDR for marine equipment certification shapes product entry requirements for both domestic and foreign suppliers. The country's central bank and transport ministry coordinate on liability protocols for autonomous vessel operations in congested commercial waterways. Stakeholders must monitor how forthcoming IMO safety standards for remote-operated shipping redefine insurability and operator accountability across Greek territorial waters.
Market Dynamics
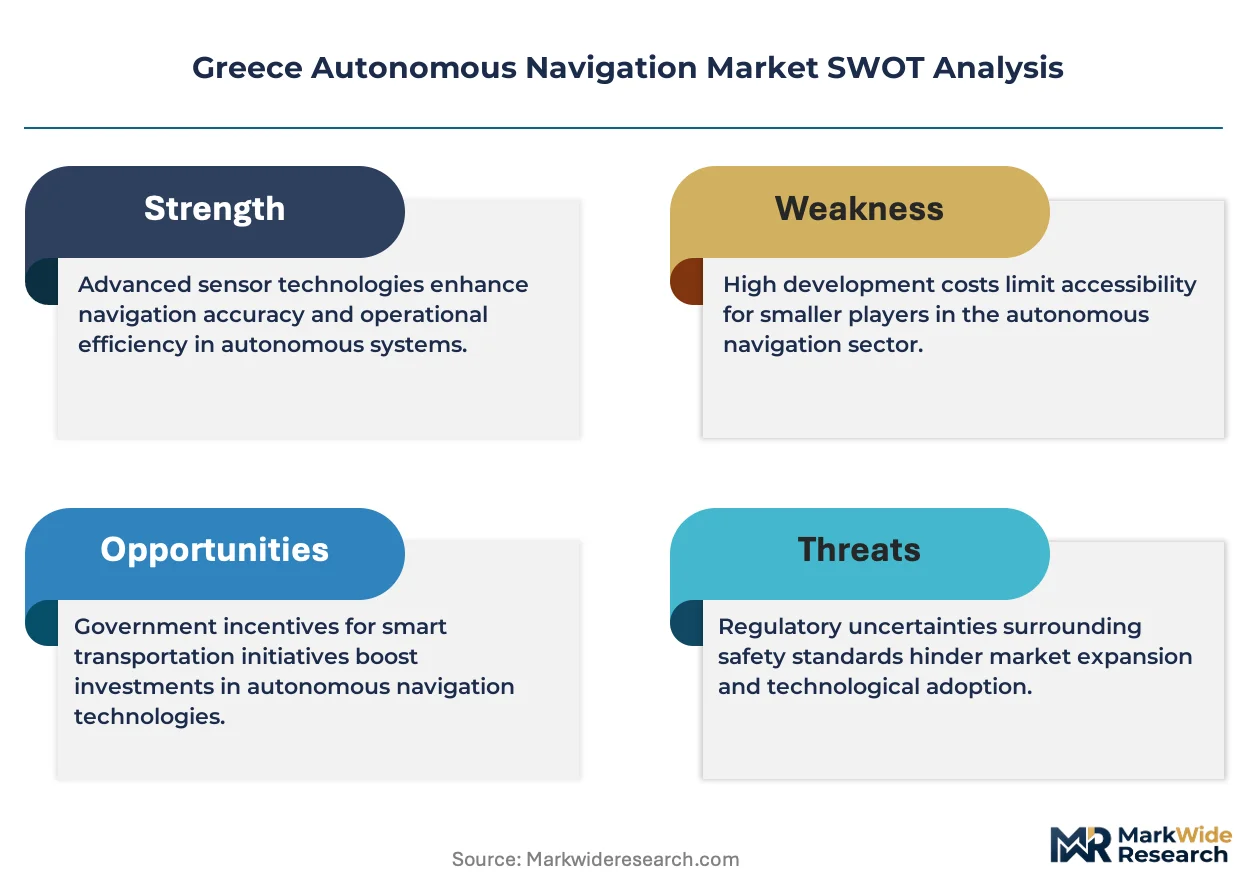
The Aegean maritime corridor is driving procurement concentration as ferry operators and island connectivity services demand collision-avoidance autonomy and remote monitoring capabilities for congested island-hopping routes.
Growth Catalysts
- EU AI Act compliance mandates:Certification requirements for autonomous vessel systems are accelerating domestic supplier capability upgrades across Piraeus and Thessaloniki port authorities.
- Island ferry route optimization:Automated scheduling and dynamic routing systems reduce fuel consumption and crew rotation costs for archipelagic connectivity services.
- IMO Maritime Autonomous Surface Ships code adoption:International safety standards are harmonizing Greek regulatory frameworks with NATO-aligned defense procurement channels.
Market Restraints
- Sensor hardware import dependency:Lidar and marine-grade inertial measurement units concentrate supply from German and Japanese manufacturers, exposing Greek integrators to currency volatility.
- Technical limitation in GPS-denied environments:Aegean terrain shadowing and jamming vulnerabilities constrain pure-satellite navigation reliability for military patrol applications.
- Regulatory friction from EASA drone framework misalignment:Divergent certification timelines between aerial and maritime autonomous systems delay dual-use product launches.
Strategic Opportunities
- Crete and Dodecanese underpenetration:Southern island chains lack integrated autonomous port infrastructure, creating first-mover advantage for terminal automation providers.
- Technology convergence of AI path optimization and edge computing:Real-time decision-making without cloud dependency suits Greece's intermittent connectivity across scattered islands.
- Hellenic Navy modernization programs:NATO interoperability requirements for autonomous mine countermeasures and patrol craft are opening long-term service contract windows.
Industry Challenges
- Marine autonomy software engineering talent scarcity:Domestic universities produce insufficient specialists in sensor fusion and maritime machine learning, forcing reliance on foreign contracting.
- Dual certification burden:Products must simultaneously satisfy EU MDR for marine equipment and national transport ministry liability protocols, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece Autonomous Navigation Market |
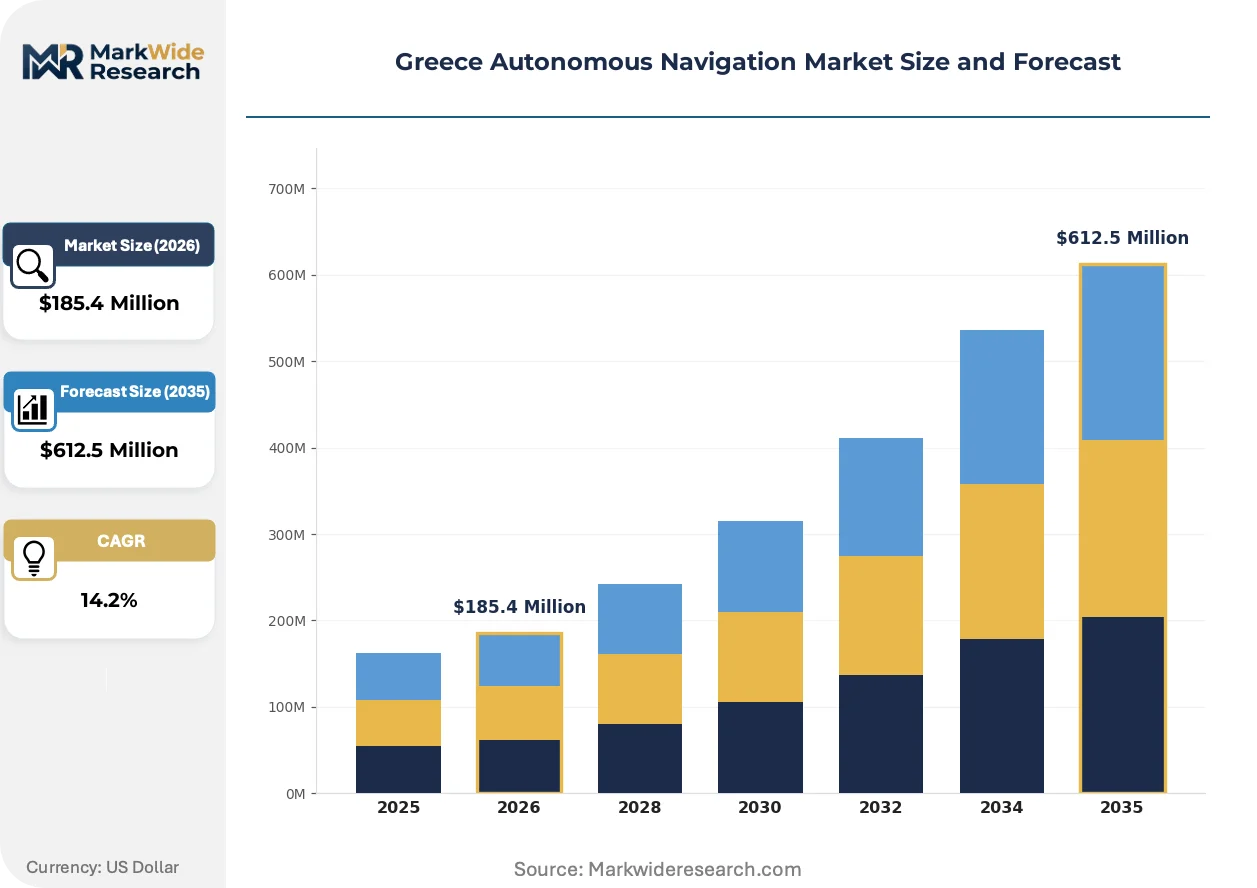
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $612.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, GPS Systems, Sensors End User: Aerospace, Maritime, Automotive, Research Institutions Application: Self-Driving Cars, Drones, Navigation Systems, Autonomous Vessels Technology: Computer Vision, Lidar, Machine Learning, Robotics |
| Companies Covered | Thales Group, Raytheon Technologies, Safran, ABB, Northrop Grumman Corporation, Honeywell International, L3Harris Technologies, Kongsberg Gruppen, General Dynamics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece Autonomous Navigation Market Trends and Innovations
Sensor fusion architectures are displacing single-modality navigation systems as Greek operators prioritize redundancy for safety-critical archipelagic operations. Machine learning inference is moving toward vessel-edge processors.
Multi-sensor fusion stacks combining radar, camera, and lidar arrays are migrating from research vessels to commercial ferry fleets. Attica Group and Blue Star Ferries are piloting integrated perception systems for automated docking at Piraeus. This technology compression is eliminating standalone pilotage service contracts and consolidating navigation system procurement under single-vendor agreements.
EASA drone framework amendments and EU AI Act risk-classification rules are tightening algorithmic transparency requirements for autonomous navigation software. Greek suppliers must now document decision-path logging for maritime AI systems. The commercial shipping segment is responding by segregating domestic product lines from export variants to manage compliance cost divergence.
Buyer concentration among Attica Group, ANEK Lines, and Hellenic Seaways is consolidating procurement leverage for ferry fleet modernization. These operators are unbundling hardware acquisition from software maintenance, forcing navigation vendors into subscription-based service models. This contractual restructuring is most visible in the Saronic Gulf routes where rapid vessel turnaround demands predictive maintenance guarantees.
Greece Autonomous Navigation Market Segmentation
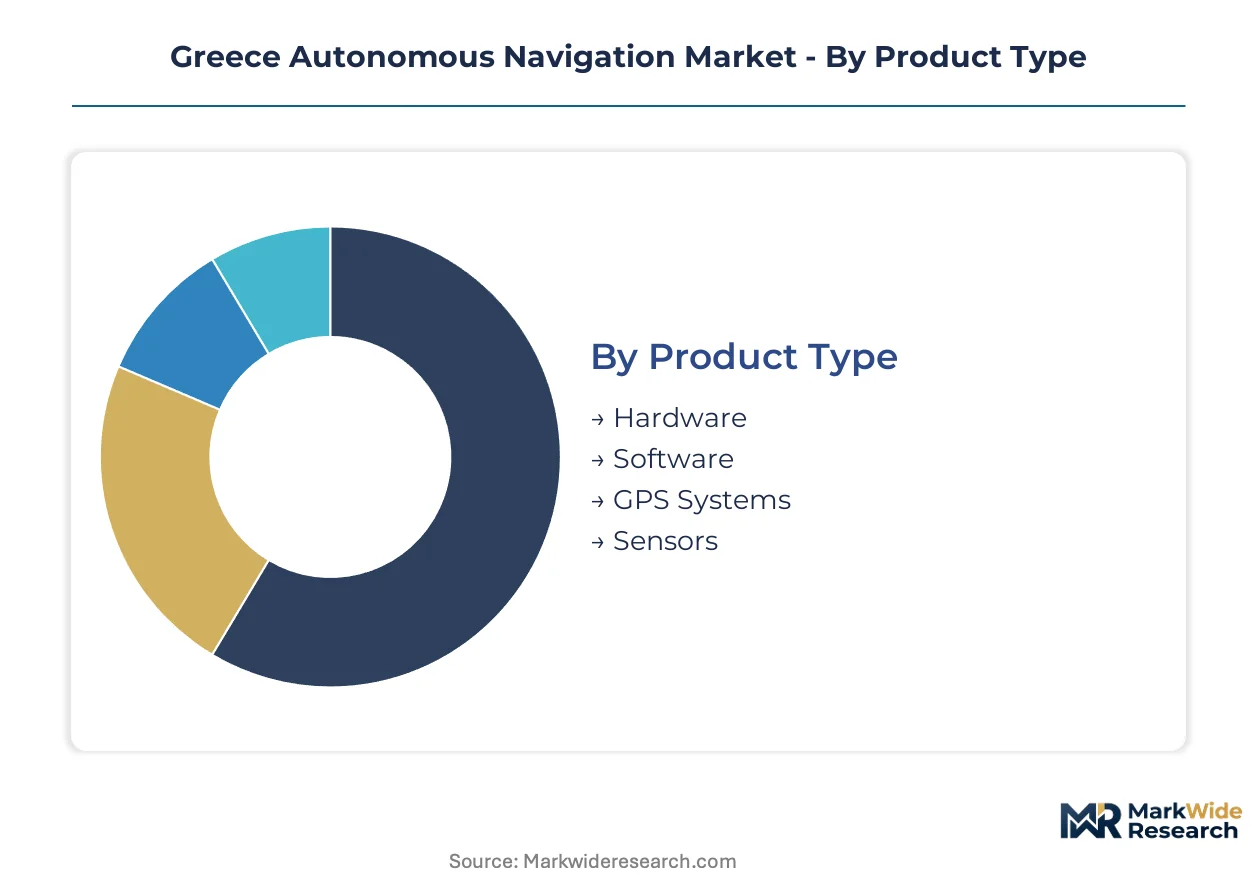
Greek procurement patterns diverge sharply across product maturity levels, with maritime operators favoring proven hardware stacks while defense channels incubate emerging software architectures. Segment boundaries blur as ferry fleet modernization demands integrated sensor-software bundles rather than standalone components.
Product Type:
Mature hardware categories dominate installed value, yet emerging software layers capture expanding margin pools through subscription service models.
- Hardware:Marine-grade inertial measurement units, edge processors, and ruggedized compute enclosures constitute the foundational layer for Aegean ferry autonomy. Piraeus port authorities prioritize redundant hardware stacks for collision-avoidance systems in congested commercial waterways.
- Software:Path optimization algorithms and predictive maintenance platforms operate on vessel-edge infrastructure, reducing cloud dependency across Greece's intermittently connected island chains. Machine learning inference engines for dynamic routing command premium pricing from Attica Group and Blue Star Ferries procurement teams.
- GPS Systems:Real-time kinematic correction services and multi-constellation receivers anchor navigation reliability for Saronic Gulf operations.
- Sensors:Lidar arrays, marine radar, and camera fusion modules enable automated docking pilotage at Thessaloniki terminal facilities.
Hardware retains volume leadership; software holds the steepest expansion curve.
End User:
Cost-tier segmentation separates capital-intensive maritime fleet operators from research institutions operating on grant-funded procurement cycles.
- Maritime:Ferry operators and cargo shippers across the Aegean corridor drive absolute spending, with Attica Group unbundling hardware acquisition from software maintenance contracts. Island connectivity mandates accelerate collision-avoidance system deployment on inter-island routes.
- Aerospace:Hellenic Air Force modernization programs and commercial drone service providers demand avionics-guided navigation with NATO interoperability certification. EASA drone framework compliance shapes algorithmic transparency requirements for domestic suppliers.
- Automotive:Limited domestic vehicle manufacturing constrains adoption, though Athens metropolitan mobility pilots test autonomous shuttle connectivity.
- Research Institutions:University of Athens and Hellenic Centre for Marine Research procure sensor fusion platforms for Aegean seabed mapping and environmental monitoring applications.
Maritime commands procurement volume; aerospace exhibits the most aggressive capability upgrade cycles.
Application:
Geography-driven demand concentration elevates archipelagic vessel autonomy above terrestrial alternatives.
- Autonomous Vessels:IMO Maritime Autonomous Surface Ships code alignment positions Greek ferry operators for early remote-operated shipping certification. Automated scheduling systems reduce crew rotation costs across the Dodecanese island chain.
- Drones:Aegean maritime patrol and island logistics services deploy beyond-visual-line-of-sight platforms under EASA framework amendments. Hellenic Navy mine countermeasure programs incubate dual-use navigation architectures.
- Self-Driving Cars:Athens congestion management pilots and Thessaloniki port logistics zones test limited autonomous mobility corridors.
- Navigation Systems:Integrated bridge systems for commercial shipping consolidate radar, GPS, and inertial inputs for sub-meter positioning accuracy.
Autonomous vessels anchor current spending; drone applications are climbing the fastest.
Technology:
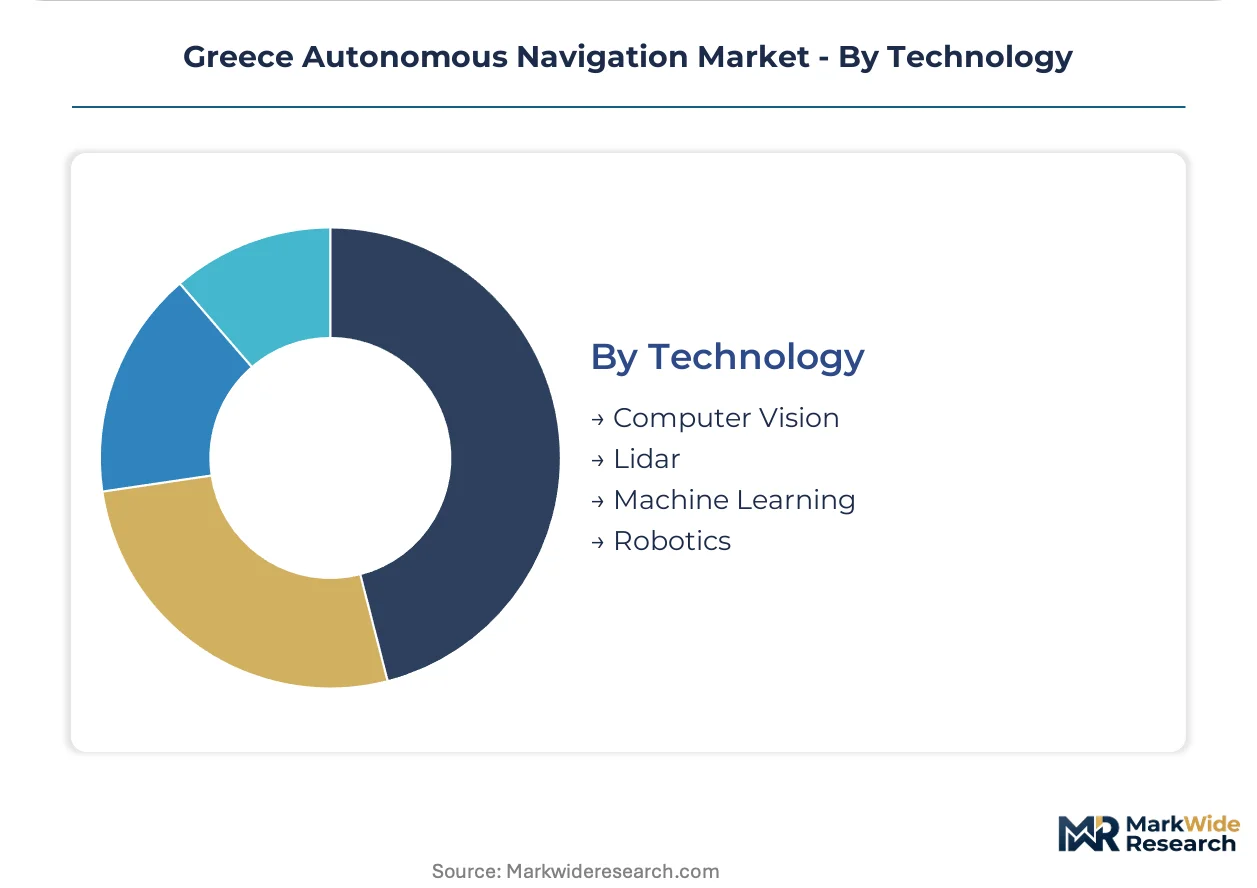
Supply concentration in sensor hardware shapes competitive positioning, while machine learning differentiation emerges in software procurement.
- Lidar:Marine-grade scanning arrays from German and Japanese manufacturers dominate Aegean ferry perception stacks. Import dependency exposes Greek integrators to currency volatility and extended lead times.
- Computer Vision:Camera-based object recognition systems enable automated docking at Piraeus and Thessaloniki terminals. Multi-sensor fusion architectures displace single-modality systems for safety-critical operations.
- Machine Learning:Edge-deployed inference engines process routing decisions without continuous connectivity, addressing Greece's scattered island infrastructure constraints.
- Robotics:Autonomous manipulation systems for vessel maintenance and subsea inspection remain nascent, concentrated in Hellenic Navy and research institution procurement.
Lidar retains installed base dominance; machine learning represents the steepest capability expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Piraeus container terminal and Thessaloniki port complex anchor Greece's maritime autonomy infrastructure, underwriting Aegean corridor connectivity and NATO-aligned defense procurement channels across southeastern Europe.
Attica Region
Piraeus port authorities accelerate collision-avoidance system deployment for congested commercial waterways. EU AI Act certification mandates reshape procurement specifications for domestic integrators. Attica Group ferry operations at Piraeus pilot automated docking systems, consolidating navigation vendor relationships under single-source agreements.
Central Macedonia
Thessaloniki terminal facilities drive sensor fusion platform demand for cargo handling optimization. Greece's transport ministry coordinates liability protocols with the central bank for autonomous vessel operations. Hellenic Navy patrol craft modernization programs concentrate procurement leverage in the Thermaic Gulf maritime cluster.
South Aegean
Dodecanese island chains generate underpenetrated demand for integrated autonomous port infrastructure. EASA drone framework amendments tighten algorithmic transparency requirements for beyond-visual-line-of-sight logistics services. Blue Star Ferries routes connecting Rhodes and Kos test dynamic routing systems for fuel consumption reduction.
Crete
Heraklion and Chania harbors lack terminal automation coverage relative to northern counterparts. IMO Maritime Autonomous Surface Ships code alignment positions Cretan operators for remote-operated shipping certification. Hellenic Centre for Marine Research deploys sensor fusion platforms for seabed mapping across the Libyan Sea.
Greece Autonomous Navigation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying marine-grade inertial measurement units and edge processors. The vendor base concentrates around defense-electronics conglomerates with established Hellenic naval footprints, supplemented by industrial automation multinationals serving commercial shipping channels. Three archetypes dominate: NATO-aligned defense contractors anchoring long-term service agreements, European industrial integrators leveraging port modernization programs, and sensor hardware specialists exposed to currency volatility from German and Japanese supply concentration. Competitive moves center on unbundling hardware acquisition from software maintenance contracts and consolidating navigation system procurement under single-vendor agreements for ferry fleet operators.
Within the defense-contractor archetype, Thales Group and Raytheon Technologies occupy positions reflecting established Hellenic naval electronics footprints, while Kongsberg Gruppen exemplifies the industrial-integrator tier serving commercial maritime automation requirements. These three entities represent distinct competitive vectors: Thales anchors NATO-aligned command-and-control architectures, Raytheon exemplifies integrated maritime patrol system positioning, and Kongsberg sits within the commercial vessel autonomy segment addressing Aegean ferry operator procurement.
| Leading Market Players |
|---|
| Thales Group |
| Raytheon Technologies |
| Safran |
| ABB |
| Northrop Grumman Corporation |
| Honeywell International |
| L3Harris Technologies |
| Kongsberg Gruppen |
| General Dynamics |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Japanese lidar manufacturers exposes Greek integrators to currency volatility and determines both pricing tier spreads and supply chain shape. Hardware acquisition costs compress margins for domestic system integrators while subscription-based software maintenance contracts capture expanding margin pools from ferry fleet operators.
Pricing Analysis
Volume-discount tiering structures separate Attica Group and Blue Star Ferries procurement teams from smaller island operators through multi-vessel bundling agreements. Price differentiation rests on EU MDR certification grade and NATO interoperability compliance for defense channels. Cost compression in entry-level sensor hardware is intensifying because Piraeus port authorities prioritize redundant stacks. Smaller ferry operators exhibit the highest price sensitivity, while Hellenic Navy modernization programs demonstrate minimal elasticity.
Supply Chain Analysis
Export-control regimes limiting marine-grade inertial measurement unit flows from Germany and Japan constrain Greek integrator access to critical components. Hardware sourcing draws from German precision optics manufacturers, Japanese sensor specialists, and Taiwanese edge processor fabricators. Lidar array and ruggedized compute enclosure dependencies create single-source vulnerability for collision-avoidance system deployments. Distribution runs through Piraeus and Thessaloniki port authority procurement channels, with defense contracts flowing via NATO-aligned procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greek autonomous navigation incumbents face substitution defense imperatives as Chinese industrial automation suppliers enter Aegean maritime corridors with lower-cost perception stacks. Incumbents must navigate this threat through capability deepening and contractual restructuring.
For Market Incumbents: Pre-empt Chinese sensor hardware entrants by anchoring long-term service contracts with Attica Group and Blue Star Ferries through predictive maintenance guarantees. Deepen vertical integration into edge processor assembly to reduce exposure to Taiwanese supply volatility. Certification investment in EU AI Act algorithmic transparency documentation creates switching costs that lock ferry operators into incumbent software stacks.
For New Entrants and Emerging Players: Mid-market Crete and Dodecanese island chains lacking integrated autonomous port infrastructure represent the most penetrable entry point for terminal automation specialists. Research institution procurement cycles at the Hellenic Centre for Marine Research offer grant-funded pilot opportunities with lower competitive intensity. A go-to-market angle targeting seabed mapping sensor fusion platforms bypasses direct confrontation with established defense-electronics conglomerates.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with NATO-aligned service contract backlogs. Long-term viability over the next decade hinges on exposure to Hellenic Navy modernization programs and Aegean ferry fleet replacement cycles. Acquisition targets should display dual-use navigation architectures spanning commercial maritime and defense applications. The signal to watch is IMO Maritime Autonomous Surface Ships code ratification timing, which would accelerate remote-operated shipping certification and expand addressable market scope.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Algorithmic transparency documentation satisfies EASA drone framework amendments for Attica Group procurement. |
| Edge Processor Backward Integration | In-house assembly of vessel-edge compute enclosures reduces Taiwanese supply chain exposure for Piraeus integrators. |
| Predictive Maintenance Service Contracts | Subscription-based software maintenance locks Blue Star Ferries into multi-year navigation system relationships. |
| Crete Terminal Automation Deployment | First-mover positioning in Heraklion and Chania harbors captures underpenetrated southern island chain demand. |
| NATO Interoperability Alignment | Hellenic Navy mine countermeasure program qualification opens long-term defense service contract windows. |
Research Methodology
A spread of perspectives from ferry fleet operations directors, Hellenic Navy procurement officers, port authority technical managers, and marine equipment certification specialists converged on the working assumptions. Primary fieldwork combined structured interviews with Attica Group and Blue Star Ferries navigation system procurement teams alongside regulatory affairs leads at the transport ministry. Secondary validation drew from EU MDR marine equipment certification databases, EASA drone framework amendment filings, and IMO Maritime Autonomous Surface Ships code development records. Bottom-up vessel deployment counts triangulated against top-down Aegean maritime corridor spending estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type maturity tiers, end-user procurement cycle characteristics, application geography constraints, and technology capability trajectories. CAGRs were derived through regression analysis of historical ferry fleet modernization spending patterns and defense procurement pipeline visibility. Industry-specific forecast inputs incorporated EU AI Act implementation timelines and IMO remote-operated shipping standard ratification scenarios.
Stress conditions across euro-yen currency volatility bands, German export license approval delays, and Aegean ferry passenger volume recovery trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NATO defense spending commitments and EU Green Deal maritime decarbonization enforcement. Material shifts in IMO safety standard ratification schedules or Hellenic Navy procurement acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
Automotive Adaptive Cruise Control Market
Autonomous Vehicles
Autonomous Navigation Sensing System Market
Autonomous Vehicles
Asia-Pacific Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market