
 Automotive Battery Testing Market | 2026-2036
Automotive Battery Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Testing Market Insights
Electric vehicle OEMs is repositioning the demand center of automotive battery testing away from traditional internal combustion starter battery validation. DEKRA leverages its European laboratory network to dominate homologation testing for imported EV platforms. Chroma ATE specializes in high-throughput charge-discharge cycle equipment for gigafactory quality gates. SGS SA extends its environmental stress-testing portfolio to cover solid-state cell prototypes.
Automotive battery testing encompasses electrical, thermal, mechanical, and lifecycle validation protocols applied to traction and auxiliary power cells before vehicle integration. Test regimes typically subject cells to nail penetration, thermal runaway propagation, and thousand-cycle degradation profiling to verify safety margins and warranty durability. Impedance testing and capacity testing are commanding premium pricing as next-generation lithium-ion and solid-state chemistries require more granular state-of-health characterization. Automated testing systems are displacing manual benches across OEM and battery manufacturer facilities as throughput requirements scale with production volume.
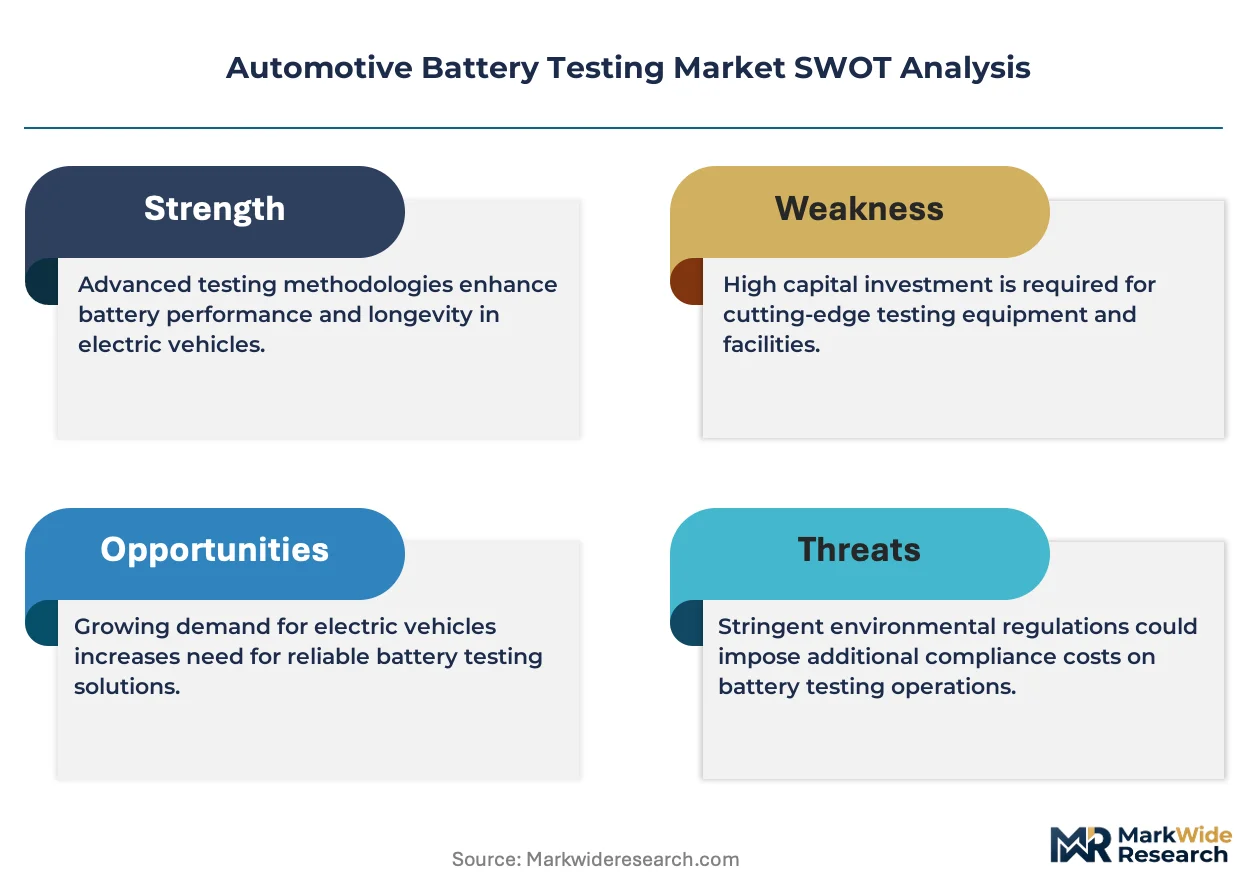
FDA, EPA, and NHTSA frameworks in the United States govern transportation and stationary storage safety thresholds, while ECHA's REACH restrictions and the EU Green Deal's battery passport requirements in Europe mandate chemical disclosure and recyclability verification. These regulations shape demand by forcing test scope expansion into supply chain traceability and end-of-life material recovery. Stakeholders must monitor how divergent regional certification timelines affect platform development costs and laboratory capacity allocation.
Market Dynamics
Cell chemistry diversification is fragmenting validation protocols as solid-state and sodium-ion platforms demand entirely new test matrices alongside incumbent lithium-ion regimes.
Growth Catalysts
- EU Green Deal battery passport mandates:Chemical disclosure requirements are expanding test scope into supply chain traceability and recyclability verification across European EV supply chains.
- Gigafactory quality gate scaling:Automated charge-discharge cycle equipment is displacing manual benches as production volumes at battery manufacturing facilities multiply throughput requirements.
- China NMPA cell safety certification:Thermal runaway propagation testing is now compulsory for all traction battery platforms entering the Chinese passenger vehicle market.
Market Restraints
- Lithium price volatility:Input cost swings for cathode active materials are compressing R&D budgets available for extended validation cycles at mid-tier battery manufacturers.
- Equipment supplier concentration:German and Japanese precision instrumentation vendors control critical subsystems for high-throughput impedance spectroscopy, creating procurement bottlenecks.
- Solid-state interface characterization limits:Existing electrochemical impedance protocols cannot adequately model ceramic-electrolyte delamination failure modes.
Strategic Opportunities
- India PLI scheme localization:Domestic cell manufacturing incentives are creating demand for indigenous validation laboratories as OEMs establish regional supply chains.
- Second-life stationary storage:State-of-health assessment protocols developed for automotive retirement are transferring to grid-scale battery repurposing applications.
- AI-driven predictive degradation modeling:Machine learning convergence with electrochemical simulation is enabling virtual test cycle compression before physical validation.
Industry Challenges
- Multiphysics simulation talent scarcity:Battery-specific electrochemical-thermal-mechanical modeling expertise remains concentrated among a limited pool of specialized engineers.
- Homologation timeline divergence:Misaligned certification schedules between NHTSA, ECHA, and NMPA are forcing parallel test track development and redundant laboratory investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Testing Market |
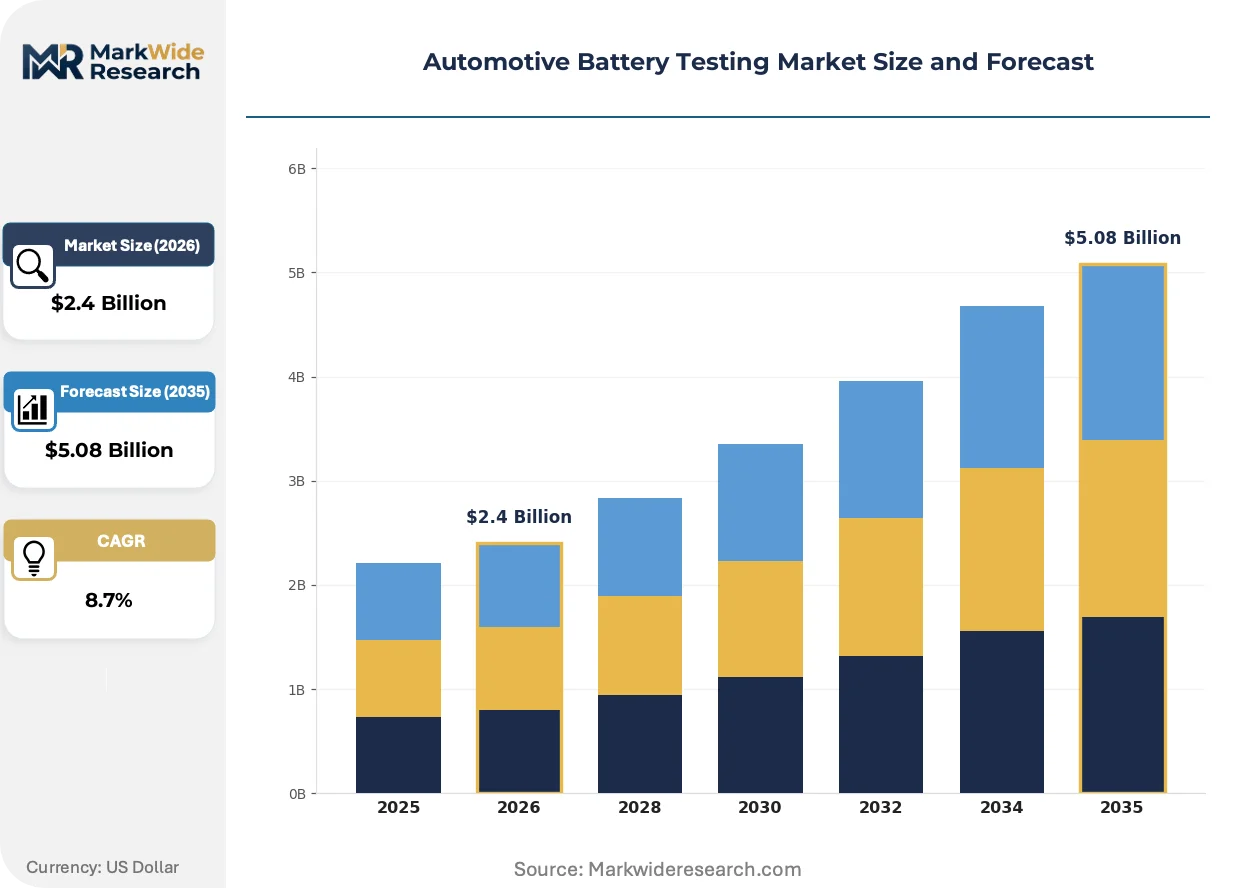
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Solid State Testing Method: Charge Discharge Cycle, Capacity Testing, Load Testing, Impedance Testing End User: OEMs, Aftermarket Repair Shops, Battery Manufacturers, Research Institutions Technology: Automated Testing, Manual Testing, Digital Testing, Hybrid Testing |
| Companies Covered | TÜV SÜD, Chroma ATE, UL LLC, Arbin Instruments, Keysight Technologies, SGS SA, DEKRA, Rohde & Schwarz, Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Testing Market Trends and Innovations
Digital twin integration is compressing development cycles while regulatory fragmentation forces multi-jurisdictional protocol engineering. Test equipment vendors are repositioning around data analytics layers.
In-situ electrochemical acoustic sensing is overtaking traditional voltage-current measurement as the primary state-of-health diagnostic for next-generation cells. Premium EV OEMs in Germany and South Korea are adopting this modality for warranty-grade degradation profiling. The technology is overtaking incumbent impedance methods by enabling non-destructive internal structural monitoring across thousand-cycle test regimes.
REACH substance restriction updates are forcing reformulation of electrolyte solvents and separator coatings used in European-market batteries. Industrial consequence includes expanded toxicological screening budgets and supply chain requalification delays. Cell suppliers serving German automotive OEMs are responding by consolidating testing partnerships with laboratories holding dual chemical and electrical certification scope.
Buyer concentration among top-tier EV OEMs is consolidating vendor qualification lists and compressing commercial terms for testing service providers. Tier-2 battery manufacturers are losing direct OEM relationships as procurement authority centralizes at platform engineering hubs. South Korean and Chinese cell producers are most affected, responding through captive laboratory buildouts to retain specification influence.
Automotive Battery Testing Market Segmentation
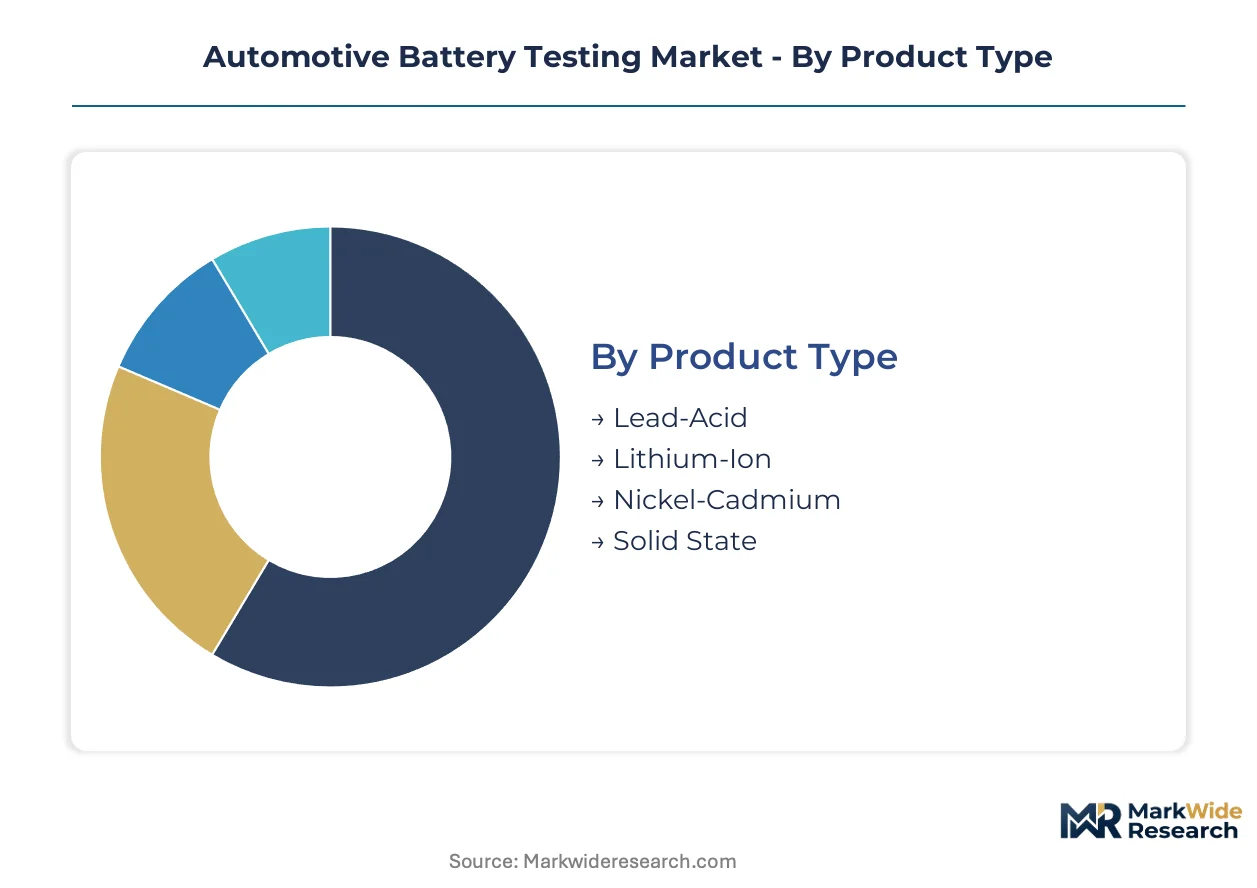
Automotive battery testing segments fracture along chemistry complexity and regulatory stringency. Divergent validation requirements across traction versus starter battery applications create distinct procurement patterns for test equipment and laboratory services.
Product Type:
Volume concentration sits with incumbent chemistries serving ICE starter applications. Premium expansion concentrates in next-generation platforms demanding extended safety and lifecycle protocols.
- Lithium-Ion:Dominant chemistry for electric vehicle traction batteries requiring thermal runaway propagation, nail penetration, and thousand-cycle degradation profiling. German and South Korean OEMs are mandating in-situ electrochemical acoustic sensing for warranty-grade state-of-health characterization.
- Solid State:Ceramic-electrolyte architectures demand entirely new test matrices including interface delamination modeling and dendrite suppression validation. Prototype testing is concentrating at captive laboratories of premium EV manufacturers in Japan and Germany.
- Lead-Acid:Mature starter battery validation with standardized load and capacity protocols serving aftermarket replacement cycles.
- Nickel-Cadmium:Niche aviation and industrial applications with declining automotive relevance due to REACH substance restrictions.
Mature deployment sits with Lead-Acid. Newer deployment is concentrated in Solid State.
Testing Method:
Throughput economics favor automated modalities at gigafactory quality gates. Precision diagnostics command premium pricing in R&D and warranty validation contexts.
- Impedance Testing:Electrochemical impedance spectroscopy enables non-destructive internal structural monitoring and state-of-health quantification. Next-generation lithium-ion and solid-state chemistries are driving demand granularity beyond traditional voltage-current measurements.
- Charge Discharge Cycle:High-throughput automated equipment displaces manual benches as production volumes multiply at battery manufacturing facilities. Chinese and European gigafactories are scaling thousand-cycle validation for warranty durability verification.
- Capacity Testing:Fundamental energy throughput measurement for cell grading and pack balancing.
- Load Testing:Starter battery cranking performance validation for aftermarket and ICE vehicle applications.
Throughput scaling is fastest in Charge Discharge Cycle. Diagnostic precision premiums are expanding in Impedance Testing.
End User:
Procurement authority centralizes at platform engineering hubs. Direct OEM relationships are consolidating while tier-2 manufacturers retreat to captive validation.
- OEMs:Electric vehicle platform engineering hubs in Germany and South Korea are consolidating vendor qualification lists and compressing commercial terms. Cell chemistry diversification is fragmenting validation protocols and extending homologation timelines.
- Battery Manufacturers:Gigafactory quality gates demand automated testing systems with data analytics integration. Chinese and South Korean cell producers are building captive laboratories to retain specification influence amid procurement centralization.
- Aftermarket Repair Shops:Standardized starter battery load and capacity testing for replacement market diagnostics.
- Research Institutions:Solid-state and sodium-ion prototype characterization for next-generation chemistry development.
Platform authority concentrates with OEMs. Capacity investment is accelerating at Battery Manufacturers.
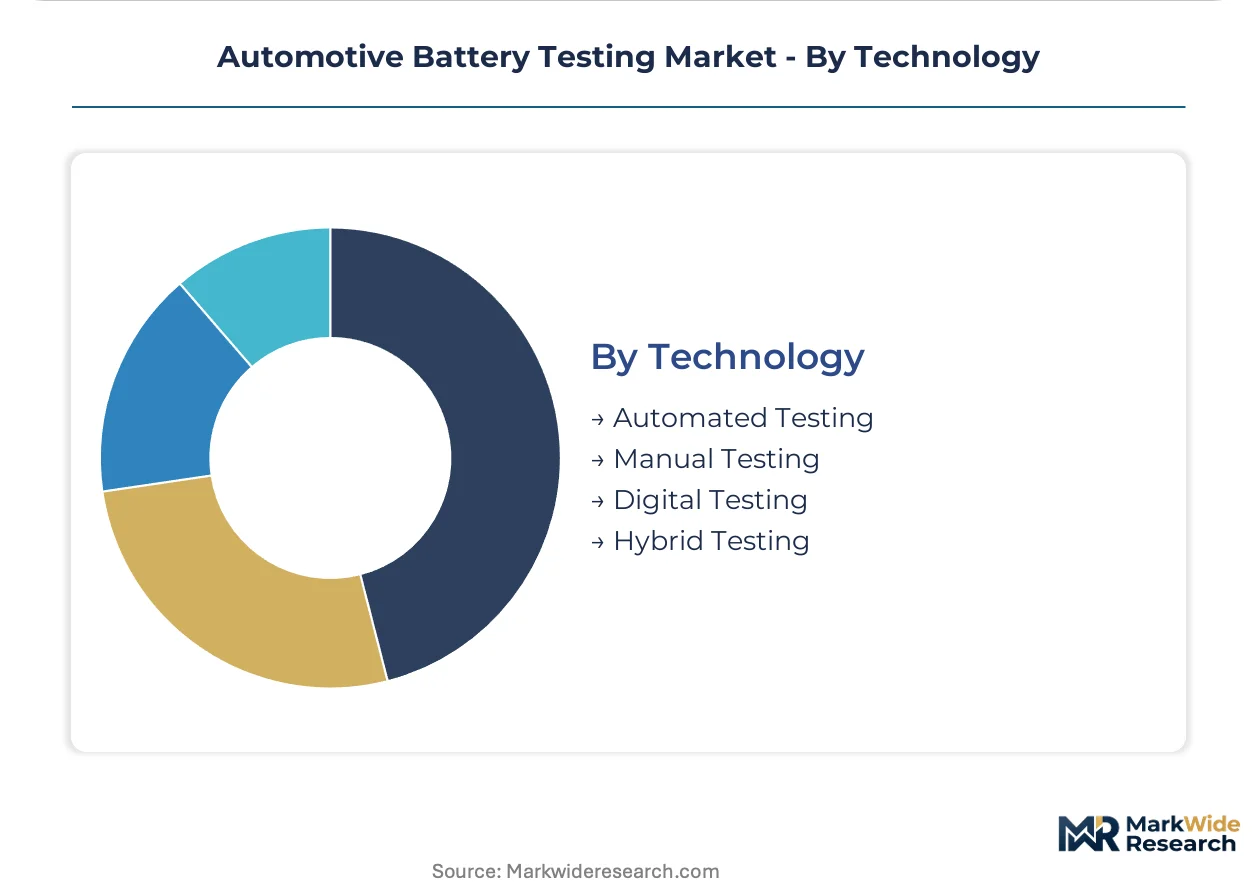
Technology:
Automation displacement proceeds fastest at volume manufacturing facilities. Hybrid architectures bridge legacy equipment and digital analytics layers.
- Automated Testing:Robotic sample handling and continuous charge-discharge cycling enable 24/7 throughput at gigafactory scale. Equipment vendors are repositioning around data analytics and predictive degradation modeling software layers.
- Digital Testing:AI-driven virtual test cycle compression converges with electrochemical simulation before physical validation. Machine learning is reducing redundant laboratory investment across multiphysics simulation workflows.
- Manual Testing:Remaining relevance in prototype and failure analysis contexts requiring engineer intervention.
- Hybrid Testing:Transitional architectures combining automated hardware with digital twin integration for development cycle compression.
Displacement from Manual Testing is complete at volume facilities. Digital Testing represents the steepest expansion trajectory for R&D cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive engineering corridor around Stuttgart and Munich functions as Europe's dominant battery validation cluster, with tax-advantaged industrial zones concentrating laboratory infrastructure and engineering talent.
China
CATL and BYD procurement is scaling validation demand for sodium-ion and lithium-iron-phosphate chemistries. NMPA thermal runaway propagation mandates now apply to all passenger EV platforms entering commercial service. Shanghai and Shenzhen host the densest concentrations of captive gigafactory laboratories serving domestic OEM export programs.
Germany
Volkswagen Group and BMW platform engineering hubs are consolidating vendor qualification lists for EU Green Deal battery passport compliance. ECHA REACH restrictions on electrolyte solvents are forcing expanded toxicological screening budgets. Stuttgart and Munich anchor the European laboratory network where DEKRA and SGS SA dominate homologation testing workflows.
South Korea
LG Energy Solution and Samsung SDI are mandating in-situ electrochemical acoustic sensing for warranty-grade state-of-health characterization. MFDS chemical disclosure frameworks align with EU battery passport requirements for export-bound production. Seoul Capital Area laboratories are building captive capacity to retain specification influence amid procurement centralization at OEM platform hubs.
United States
GM and Ford EV platform development is driving demand for NHTSA-aligned safety validation and EPA stationary storage thresholds. IRA domestic content incentives are reshaping laboratory location decisions for cell qualification. Michigan and California engineering centers concentrate multiphysics simulation talent for solid-state interface characterization.
India
Reliance Industries and Ola Electric are establishing regional supply chains under PLI scheme cell manufacturing incentives. BIS safety standards are converging with UN 38.3 transportation testing protocols for indigenous validation laboratory buildouts. Gujarat and Tamil Nadu industrial corridors are attracting testing equipment vendors for gigafactory quality gate deployment.
Automotive Battery Testing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with European homologation laboratories commanding premium pricing for regulatory certification while Asian equipment vendors capture volume manufacturing accounts. Market structure tilts toward consolidation at the top tier, where three to four full-service validation networks control cross-border OEM relationships. Strategic archetypes separate into homologation specialists, high-throughput equipment fabricators, and captive laboratory operators. Dominant competitive moves include laboratory network expansion into battery manufacturing clusters and portfolio diversification from electrical safety into environmental stress-testing.
Within the homologation specialist tier, DEKRA and SGS SA occupy positions anchored by European regulatory accreditation depth. Chroma ATE exemplifies the high-throughput equipment archetype, with its geographic origin signaling Taiwanese manufacturing scale advantages. These three entities represent the competitive spectrum from regulatory certification services through automated testing hardware, illustrating how market position depends on proximity to either OEM platform engineering hubs or gigafactory production lines.
| Leading Market Players |
|---|
| TÜV SÜD |
| Chroma ATE |
| UL LLC |
| Arbin Instruments |
| Keysight Technologies |
| SGS SA |
| DEKRA |
| Rohde & Schwarz |
| Intertek Group plc |
| Others |
Pricing and Supply Chain Analysis
Top-tier EV OEM platform engineering hubs in Germany and South Korea concentrate procurement authority, compressing commercial terms for testing service providers into volume-scaled contract structures with tiered certification-grade pricing.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations as NMPA and ECHA certification deadlines compress validation windows. Three-tier pricing structure across premium, standard, and economy levels separates EU battery passport-compliant laboratories from regional-only certifiers and uncertified equipment vendors. Price differentiation centers on dual chemical-electrical certification scope and automated throughput capacity. Cost compression in mid-tier services is intensifying because Chinese and South Korean cell producers are building captive laboratories to bypass external procurement.
Supply Chain Analysis
Workforce availability for electrochemical-thermal-mechanical modeling engineers concentrates in Germany, South Korea, and the United States, anchoring high-value validation services in these geographies. Equipment subsystems for high-throughput impedance spectroscopy draw from Japanese and German precision instrumentation vendors. Critical dependencies include ceramic electrolyte materials for solid-state protocols and lithium-iron-phosphate reference cells. Single-source vulnerability runs through German-Japanese equipment supplier concentration. Distribution runs through direct OEM platform engineering relationships and gigafactory quality gate partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive battery testing market sits in a technology-transition phase as in-situ electrochemical acoustic sensing displaces traditional impedance methods for warranty-grade degradation profiling.
For Market Incumbents: Lock in captive relationships with CATL and LG Energy Solution through dedicated laboratory capacity in Shenzhen and Seoul. DEKRA and SGS SA should expand dual chemical-electrical certification scope ahead of REACH substance restriction updates. Vertical integration threat from Chinese cell producers building in-house validation capabilities demands preemptive capacity commitments at platform engineering hubs. For New Entrants and Emerging Players: Gigafactory laboratories in India present the most penetrable white-space as Reliance Industries and Ola Electric establish regional supply chains under PLI scheme incentives. Second-life stationary storage assessment protocols offer adjacent entry into grid-scale battery repurposing. Go-to-market through BIS certification partnerships with Gujarat and Tamil Nadu industrial corridor developers bypasses entrenched OEM vendor lists. For Investors and Strategic Acquirers: The window for entry favors specialized electrochemical simulation software providers ahead of AI-driven predictive degradation modeling consolidation. Long-term viability hinges on laboratories capturing solid-state and sodium-ion protocol development before chemistry standardization. Watch for NHTSA-ECHA-NMPA certification timeline convergence as inflection indicator for redundant laboratory asset rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Testing Equipment Deployment | Chroma ATE scales robotic charge-discharge cycling for 24/7 gigafactory throughput in China and Europe. |
| Dual Certification Scope Expansion | DEKRA integrates ECHA REACH toxicological screening with electrical safety validation for German OEM compliance. |
| Digital Twin Platform Integration | Keysight Technologies converges electrochemical simulation with physical validation to compress development cycles. |
| Captive Laboratory Buildout | LG Energy Solution and Samsung SDI retain specification influence through Seoul Capital Area capacity investment. |
| Second-Life Protocol Transfer | SGS SA extends automotive state-of-health assessment to grid-scale stationary storage repurposing applications. |
Research Methodology
Document review covered NMPA cell safety certification filings, ECHA REACH substance restriction updates, and EU Green Deal battery passport implementation guidance, complemented by interviews with OEM platform engineers, Tier 1 battery manufacturer procurement leads, and testing laboratory technical directors. Secondary validation drew from vehicle production databases, gigafactory capacity announcements, and regulatory agency technical standards. Bottom-up segment sizing triangulated against top-down market aggregation across chemistry type, testing method, and end-user category.
Historical capacity deployment patterns cross-referenced against panel input from equipment vendors and service providers shaped the analytical framework. Segmentation dimensions modeled include cell chemistry complexity, regulatory stringency tier, automation level, and regional certification cluster. CAGRs were derived from elasticity-adjusted demand projections tied to EV platform rollout schedules and gigafactory quality gate scaling trajectories. Solid-state interface characterization limits and multiphysics simulation talent scarcity were incorporated as supply-side constraints.
Several conditions sit outside the modeled scope, including abrupt lithium price collapse or surge, unilateral regulatory timeline acceleration by any single agency, and breakthrough solid-state commercialization ahead of projected windows. Forecasts reflect documented assumptions about chemistry transition pacing and laboratory capacity expansion schedules. Material deviation in NMPA-ECHA-NHTSA alignment, equipment supplier consolidation, or AI-driven virtual test cycle adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Torque Testers Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market