
 Luxury Autonomous Vehicle Market | 2026-2036
Luxury Autonomous Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Autonomous Vehicle Market Analysis
A shortage of systems engineers trained in functional safety for SAE Level 4 architectures is redrawing competitive boundaries across the sector. Tesla leverages its captive data infrastructure from millions of shadow-mode miles to sustain iterative software improvements. BMW Group anchors European development through its dedicated autonomous driving campus near Munich. Lucid Motors differentiates via integrated LiDAR-sensor fusion packaged within streamlined exterior designs.
Luxury autonomous vehicles combine premium cabin appointments with redundant perception stacks capable of unsupervised operation in designated operational design domains. These vehicles typically integrate solid-state LiDAR arrays, 360-degree radar coverage, and centralized compute platforms exceeding 500 TOPS to enable real-time path planning without human intervention. Sedan configurations currently lead procurement volumes among fleet operators seeking optimized aerodynamics for extended electric range. SUV variants are capturing growing interest from private owners prioritizing cabin spaciousness and all-weather sensor mounting positions. AI-driven decision engines represent the fastest-expanding technology segment as manufacturers shift from rules-based to neural network architectures for edge-case handling.
NHTSA in the United States, the EU AI Act framework in Europe, and China's MIIT GB standards collectively shape homologation pathways and cross-border deployment permissions. Regulatory divergence in data localization requirements and crash liability assignment directly influences platform architecture investments and geographic rollout sequencing. Stakeholders must monitor pending rulemakings on remote operation protocols and cybersecurity certification to anticipate which operational design domains will unlock first across competing jurisdictions.
Market Dynamics
The transition from rules-based to neural network decision architectures is fragmenting established engineering workflows and forcing wholesale reorganization of vehicle development programs across the sector.
Growth Catalysts
- Federal Motor Vehicle Safety Standards modernization:NHTSA's 2024 automated driving system amendments eliminated testing barriers that previously blocked commercial deployment of unsupervised operation.
- Fleet operator procurement acceleration:Urban mobility contract expansions across California's Bay Area corridor are concentrating demand for Level 4-capable sedan configurations.
- Shadow-mode data accumulation:Captive telematics infrastructure from consumer vehicle fleets enables iterative software validation without regulatory exposure.
Market Restraints
- Functional safety engineer scarcity:SAE Level 4 architecture expertise concentrates among a limited cohort of specialists, inflating compensation costs and extending program timelines.
- LiDAR sensor supply concentration:Solid-state array production remains dependent on Asian component fabricators, creating geographic vulnerability in perception stack procurement.
- Operational design domain fragmentation:Jurisdictional divergence in remote operation protocols forces redundant platform certifications for cross-border deployment.
Strategic Opportunities
- EU AI Act compliance pathway:Early alignment with European artificial intelligence risk classification frameworks positions manufacturers for streamlined CE marking of automated driving systems.
- SUV configuration white space:Private owner segments prioritizing cabin spaciousness remain underpenetrated relative to fleet-focused sedan procurement volumes.
- Edge-case neural network convergence:Integration of generative simulation with physical test fleets compresses validation cycles for rare traffic scenarios.
Industry Challenges
- Compute platform thermal management:Centralized processing architectures exceeding 500 TOPS demand novel cooling solutions that extend development cycles.
- Cross-jurisdictional liability assignment:Unclear crash responsibility frameworks between vehicle manufacturers, fleet operators, and software providers complicate insurance structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Autonomous Vehicle Market |
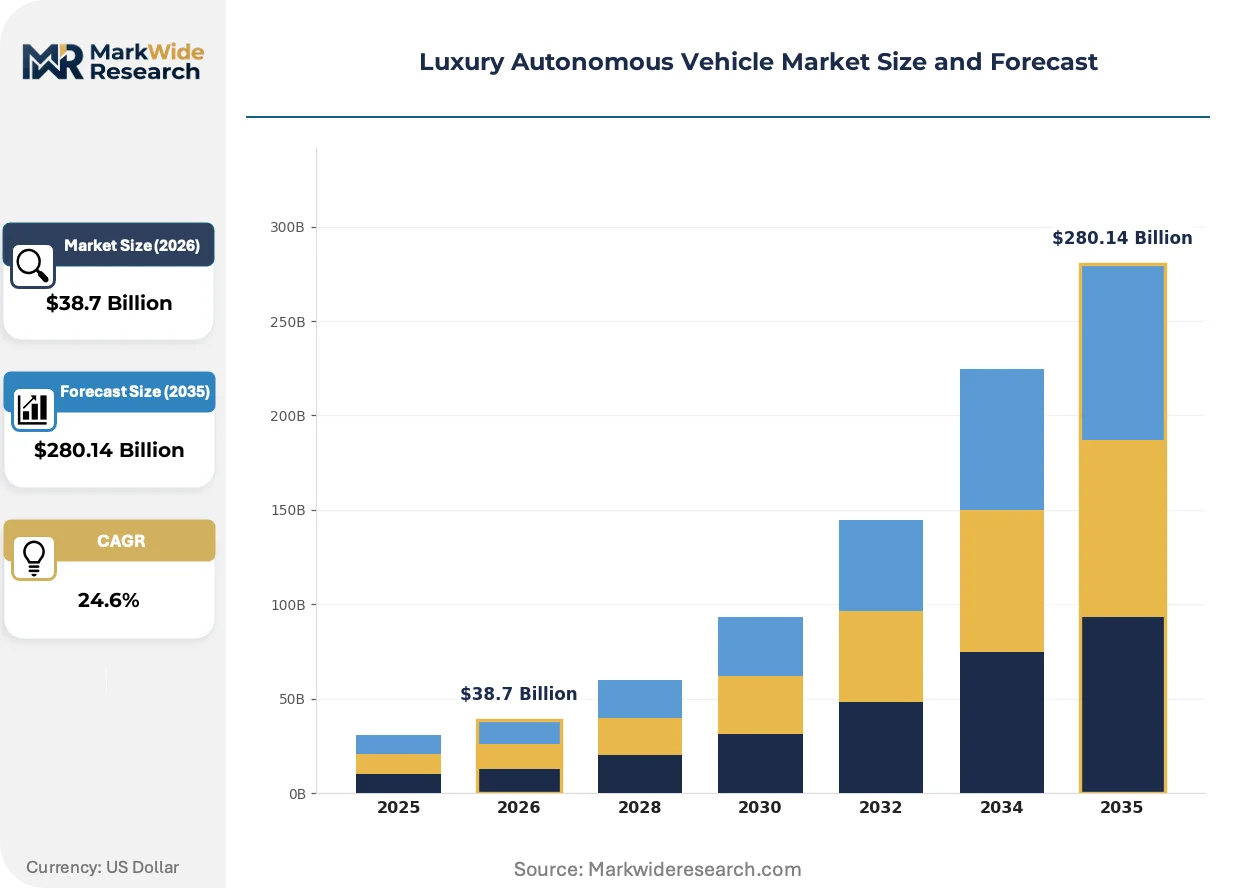
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Coupe, Crossover Technology: LiDAR, Radar, Computer Vision, AI End User: Fleet Operators, Private Owners, Corporate Clients, Luxury Rentals Distribution Channel: Direct Sales, Online Platforms, Dealerships, Showrooms |
| Companies Covered | Mercedes-Benz Group AG, Tesla Inc., BMW Group, Audi AG, General Motors Company, Lucid Motors, Hyundai Motor Company, Volvo Car Corporation, Porsche AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Autonomous Vehicle Market Emerging Trajectories
Neural network architectures are displacing deterministic control systems across perception and planning functions, while regulatory frameworks race to codify safety assurance methodologies for machine-learned behaviors.
Sensor fusion architectures are fragmenting as manufacturers debate the optimal balance between camera-dominant and LiDAR-inclusive perception stacks. Fleet operators in California's Bay Area corridor are accelerating procurement of redundant 360-degree radar configurations to mitigate weather-related operational design domain restrictions. This technical divergence is compressing interoperability standards development and forcing tier-one suppliers to maintain parallel validation programs.
The EU AI Act risk-based classification framework is reshaping homologation pathways for automated driving systems deployed within European member states. Manufacturers must now document training data provenance and algorithmic explainability prior to CE marking authorization. Sedan configurations targeting cross-border fleet services face the most complex compliance burden, as operational design domains frequently span multiple regulatory jurisdictions.
Urban mobility contracts are consolidating procurement authority among a narrowing set of fleet operators with dedicated autonomous vehicle infrastructure. Technology companies co-located in California's Bay Area corridor are displacing traditional rental and limousine services through integrated app-based hailing platforms. This channel concentration is most visible in designated geofenced zones where municipalities have pre-approved unsupervised operation.
Luxury Autonomous Vehicle Market Segmentation
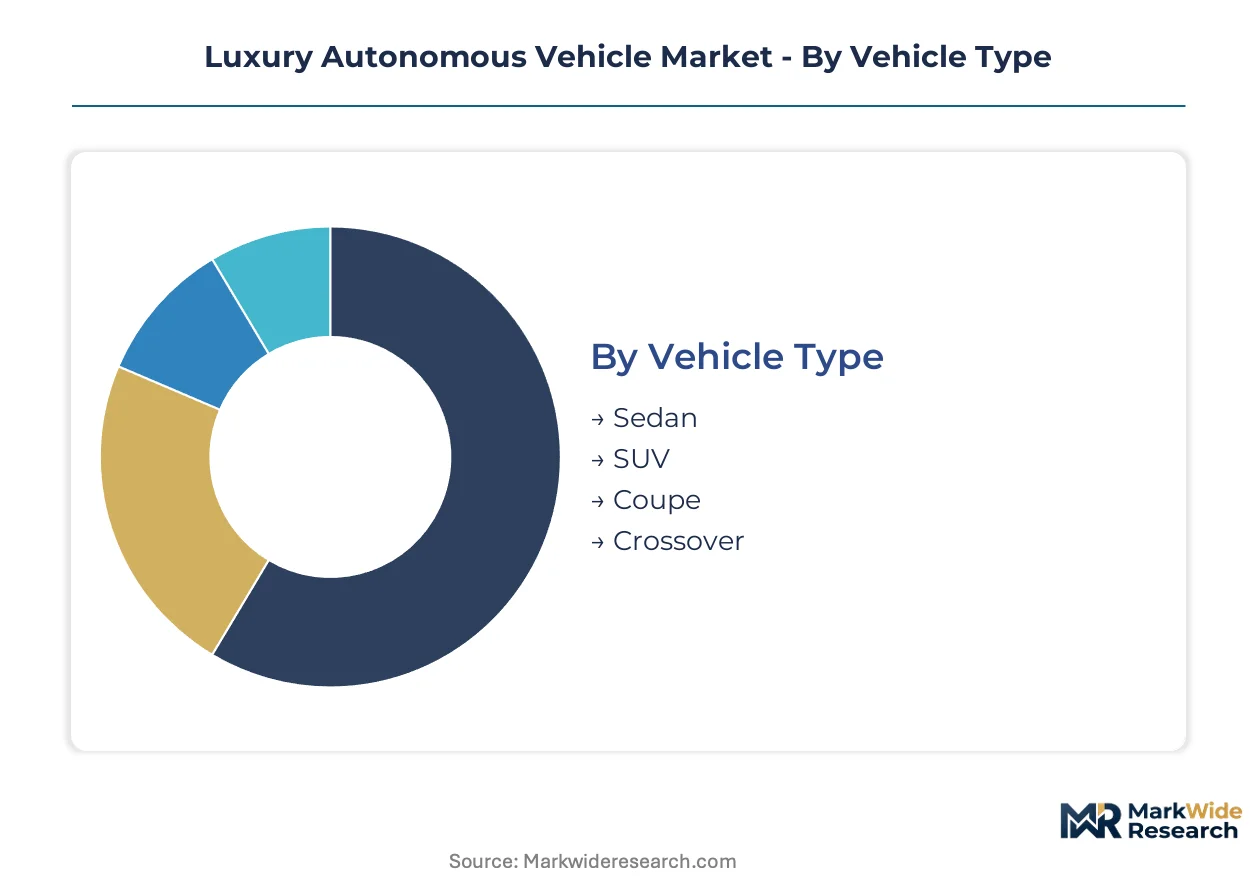
Segmentation reveals how procurement authority concentrates among fleet operators while private ownership patterns diverge on cabin configuration preferences. Technology choices fragment across regional regulatory tolerances for unsupervised operation.
Vehicle Type:
Geographic demand splits between fleet-dense urban corridors and suburban private ownership zones, with aerodynamic efficiency driving sedan procurement in California's Bay Area while cabin volume commands premium in Sun Belt states.
- Sedan:Optimized drag coefficients extend electric range for high-utilization fleet duty cycles. Procurement concentrates among California-based mobility services seeking maximum operational efficiency within geofenced urban domains.
- SUV:Elevated sensor mounting positions and spacious cabins attract private owners prioritizing all-weather operational design domain flexibility. Demand clusters in Texas and Florida where suburban density favors larger vehicle footprints.
- Coupe:Two-door configurations with reduced rear accessibility limit fleet applicability. Niche positioning targets individual enthusiasts in premium coastal markets.
- Crossover:Blended ride height and cargo flexibility appeals to corporate shuttle services. Moderate penetration reflects positioning between sedan efficiency and SUV utility.
Sedan configurations command the established base. The steepest expansion runs through SUV variants.
Technology:
Cost tiers separate perception architectures by computational intensity, with LiDAR-inclusive stacks commanding premium pricing against camera-dominant alternatives.
- LiDAR:Solid-state arrays deliver centimeter-range precision for dense urban obstacle detection. Deployment concentrates where NHTSA guidelines mandate redundant depth sensing for unsupervised operation.
- Radar:360-degree coverage penetrates precipitation that degrades optical systems. Fleet operators specify redundant radar configurations to minimize weather-related operational design domain restrictions.
- Computer Vision:Camera-dominant perception reduces hardware cost but demands extensive training data validation. Regulatory scrutiny of edge-case performance limits deployment scope.
- AI:Neural network decision engines displace rules-based control for complex scenario handling. Algorithmic explainability requirements under EU AI Act frameworks constrain European rollout timelines.
LiDAR-inclusive stacks anchor premium pricing. AI decision engines are climbing the fastest as manufacturers retrain architectures on accumulated fleet data.
End User:
Customer type determines contract structure, with fleet operators negotiating volume commitments against individual purchasers selecting on configuration preferences.
- Fleet Operators:Urban mobility contracts consolidate procurement authority among technology-integrated platforms. California municipalities pre-approve unsupervised operation in designated geofenced zones.
- Private Owners:Individual purchasers prioritize cabin appointments and discretionary control override capabilities. Suburban garages in Arizona and Nevada support home charging infrastructure for extended-range configurations.
- Corporate Clients:Executive shuttle services demand consistent arrival times without driver availability constraints. Campus-based deployment in Texas technology corridors leverages private road networks.
- Luxury Rentals:Short-term access models require simplified user interfaces for unfamiliar operators. Airport-adjacent facilities in Florida and California concentrate vehicle staging.
Fleet operators command the established base. Corporate client adoption is expanding most quickly as campus networks expand autonomous shuttle coverage.
Distribution Channel:
Volume concentration favors direct manufacturer relationships for fleet procurement, while experience-driven channels serve individual ownership segments.
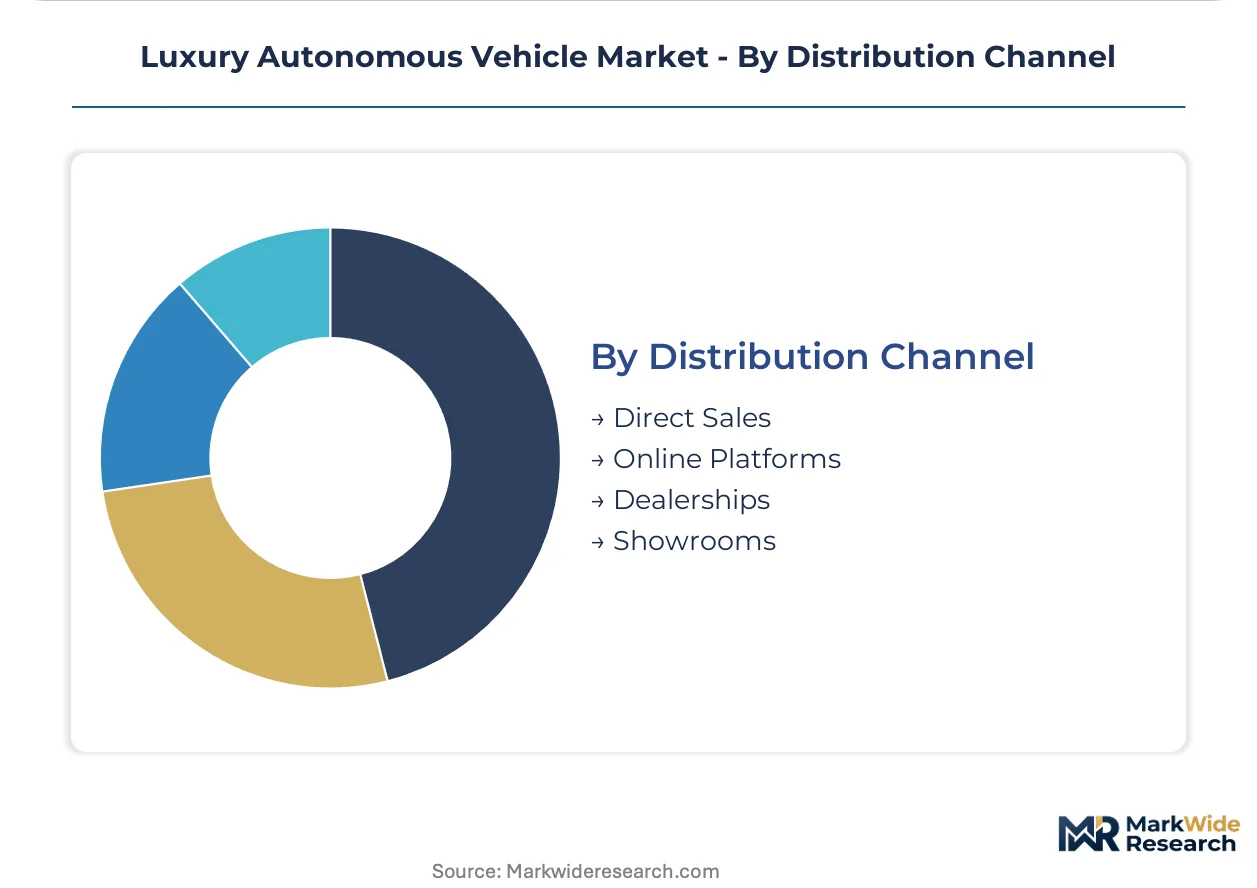
- Direct Sales:Manufacturer-controlled transactions enable customized service agreements and telemetry integration. Fleet operators negotiate directly for volume pricing and dedicated maintenance protocols.
- Online Platforms:Digital configuration tools support remote specification of cabin appointments and technology packages. Private owners in tech-adjacent demographics favor streamlined purchasing workflows.
- Dealerships:Traditional retail networks provide physical inspection and test ride opportunities. Geographic coverage concentrates in metropolitan statistical areas with established luxury vehicle infrastructure.
- Showrooms:Experience-focused facilities demonstrate unsupervised operation capabilities in controlled environments. Urban flagship locations in California and New York serve as technology demonstration anchors.
Direct sales command the established base. Online platforms are gaining share fastest as digital-native fleet operators streamline procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA's 2024 Federal Motor Vehicle Safety Standards modernization anchors North American deployment timelines, while the EU AI Act and China's MIIT GB standards create divergent homologation pathways across major automotive markets.
United States
Fleet operators in California's Bay Area corridor are accelerating Level 4 sedan procurement under expanded urban mobility contracts. NHTSA's automated driving system amendments eliminated prior testing barriers that delayed commercial unsupervised operation. Arizona and Nevada suburban zones support private ownership growth through home charging infrastructure for extended-range configurations.
Germany
BMW Group anchors European development through its dedicated autonomous driving campus near Munich, concentrating systems engineering talent for SAE Level 4 architectures. The EU AI Act risk-based classification framework mandates documented training data provenance and algorithmic explainability prior to CE marking authorization. Baden-Württemberg's automotive supplier density supports redundant perception stack integration for cross-border fleet services.
China
MIIT GB standards govern homologation pathways for automated driving systems, with data localization requirements directly influencing platform architecture investments. Domestic technology companies co-locate with luxury fleet services in Shenzhen and Shanghai technology corridors. Solid-state LiDAR array procurement concentrates among Asian component fabricators serving both domestic and export markets.
Japan
METI industrial policy frameworks support neural network decision engine development through collaborative research consortia. Toyota and Honda anchor domestic autonomous vehicle programs with integrated sensor fusion approaches. Kanto region technology clusters concentrate AI training infrastructure for edge-case scenario validation.
United Kingdom
The national automated vehicle regulatory framework permits supervised trial deployments while finalizing liability assignment protocols for unsupervised operation. London-based mobility platforms pilot geofenced autonomous shuttle services in designated urban zones. Midlands automotive engineering centers supply functional safety expertise for SAE Level 4 software validation programs.
Luxury Autonomous Vehicle Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive data infrastructure and in-house perception stack development distinguishing the upper tier from component-dependent assemblers. The middle tier fragments across LiDAR-inclusive and camera-dominant technology bets, each requiring parallel validation programs for diverging regulatory tolerances. Three archetypes dominate: vertically integrated technology platforms, luxury automotive incumbents with dedicated autonomous campuses, and electric vehicle specialists with streamlined sensor fusion designs. Competitive moves concentrate on strategic partnerships for compute platform access and geographic expansion through fleet operator consortia.
Within the integrated technology platform tier, Tesla Inc. exemplifies captive telematics infrastructure deployment, while Mercedes-Benz Group AG occupies a position representing luxury incumbent autonomous development scale. BMW Group anchors the dedicated campus archetype with European engineering concentration. These three companies sit within distinct strategic vectors—shadow-mode data accumulation, premium brand fleet penetration, and regional regulatory compliance leadership—rather than competing directly on identical capability matrices.
| Leading Market Players |
|---|
| Mercedes-Benz Group AG |
| Tesla Inc. |
| BMW Group |
| Audi AG |
| General Motors Company |
| Lucid Motors |
| Hyundai Motor Company |
| Volvo Car Corporation |
| Porsche AG |
| Others |
Supply Flow & Price Mechanics
Solid-state LiDAR arrays replacing mechanical spinning units simultaneously redraws component sourcing maps from Asian fabricators to emerging domestic packaging facilities and collapses perception-stack cost curves for fleet-scale procurement. This substitution dynamic concentrates pricing power among integrated manufacturers with captive sensor development while fragmenting margins for tier-one assemblers dependent on external supply.
Pricing Analysis
Geographic price spreads between California fleet contracts and Texas private-owner transactions reflect divergent operational design domain requirements and after-sales service bundling intensity. Three-tier pricing structure across premium LiDAR-inclusive, standard radar-fusion, and economy camera-dominant configurations anchors the market. Pricing pressure stems from functional safety engineer scarcity inflating development overhead. Fleet operators exhibit highest price sensitivity due to volume commitment leverage, while luxury rental channels absorb premium tiers with minimal negotiation.
Supply Chain Analysis
Port congestion along the Shanghai-Los Angeles trade lane elevates inbound logistics costs for solid-state LiDAR substrates and centralized compute substrates exceeding 500 TOPS. Component fabrication concentrates in China, South Korea, and Taiwan for sensor arrays and semiconductor packaging. Raw material dependencies span gallium nitride wafers, rare-earth magnet assemblies, and high-grade copper busbars. Single-source vulnerability in solid-state emitter arrays threatens production continuity. Distribution runs through direct manufacturer channels for fleet procurement and flagship showrooms for private demonstration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
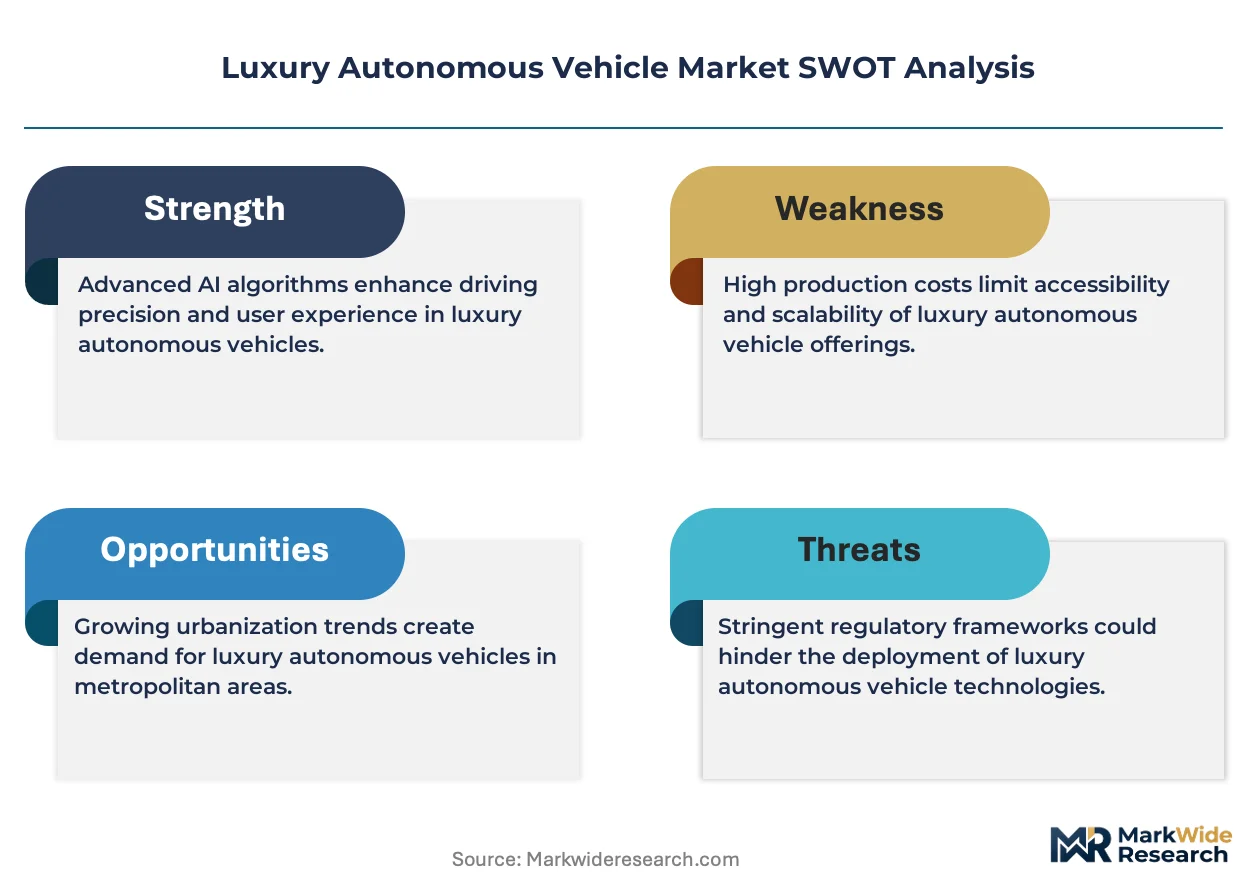
Human-supervised mobility services represent a substitution threat that autonomous vehicle incumbents must neutralize through demonstrated unsupervised operational reliability and accelerated regulatory clearance.
For Market Incumbents: Secure functional safety engineering talent through dedicated campus investments near Munich and Bay Area corridors to compress Level 4 validation timelines. Lock in multi-year solid-state LiDAR offtake agreements with Asian fabricators to hedge against emitter array supply disruption. These defensive moves counter emerging electric vehicle specialists with streamlined sensor fusion designs. For New Entrants and Emerging Players: Lead with SUV configurations targeting Texas and Florida private ownership zones where suburban density favors larger footprints and fleet penetration remains shallow. Exploit underpenetrated corporate shuttle segments in Arizona and Nevada campus networks. A direct-to-fleet digital procurement platform bypasses established dealership infrastructure. For Investors and Strategic Acquirers: NHTSA's 2024 Federal Motor Vehicle Safety Standards modernization reshapes the acquisition landscape by removing deployment barriers and validating commercial viability for unsupervised operation. Target vertically integrated technology platforms with captive telematics infrastructure and shadow-mode data accumulation capabilities for five-to-ten-year holding periods. Monitor EU AI Act CE marking authorization timelines as the critical inflection signal for European market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Shadow-Mode Data Infrastructure Expansion | Tesla's captive telematics deployment validates iterative software improvement without regulatory exposure. |
| EU AI Act Compliance Pre-Positioning | BMW's Munich campus concentrates algorithmic explainability documentation for streamlined CE marking. |
| LiDAR-Sensor Fusion Integration | Lucid's streamlined exterior packaging demonstrates premium differentiation through embedded perception stacks. |
| Fleet Operator Consortium Formation | California Bay Area mobility contracts consolidate procurement authority among technology-integrated platforms. |
| Functional Safety Campus Investment | BMW's dedicated autonomous driving campus anchors European systems engineering talent concentration. |
Methodological Framework
A spread of perspectives from autonomous vehicle platform engineers, fleet procurement directors, NHTSA regulatory affairs specialists, and tier-one supplier program managers converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against NHTSA rulemaking dockets, EU AI Act implementation guidance, and vehicle production registration databases. Bottom-up triangulation across segment-level procurement volumes and top-down cross-checks against mobility contract expansion announcements anchored the analytical framework.
Segmentation dimensions modeled span vehicle configuration class, perception architecture technology tier, end-user procurement authority structure, and regional regulatory framework cluster across the projection horizon. CAGRs were derived from logistic diffusion curves fitted to fleet operator adoption patterns and private ownership penetration thresholds. Industry-specific forecast inputs incorporated operational design domain expansion timelines and solid-state LiDAR cost-down trajectories.
Forecasts assume regulatory continuity in NHTSA automated driving system guidelines and EU AI Act risk classification frameworks; material policy shifts on remote operation protocols or cybersecurity certification would require re-modeling. Practitioners should keep alternative scenarios live as cross-jurisdictional liability assignment negotiations and data localization requirement evolutions unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Fully Autonomous Driving Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
India Autonomous Navigation Market
Autonomous Vehicles
Blind Spot Detection Market