
 Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market | 2026-2036
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market Outlook
Aftermarket service revenue for sensor recalibration and software updates is fragmenting as vehicle electronics architectures consolidate toward centralized compute platforms. Robert Bosch GmbH leverages its tier-1 supplier relationships to sustain long-term service contracts across European OEM programs. Continental AG anchors its position through in-house production of radar modules and control units for mass-market vehicle lines. Mobileye Global Inc. differentiates via vision-processing chipsets that power camera-based BSD systems for multiple automakers.
Adaptive Cruise Control and Blind Spot Detection constitute active driver-assistance systems that use radar, lidar, camera, or ultrasonic sensors to maintain following distances and monitor adjacent lanes, typically operating at frequencies between 24 GHz and 77 GHz for radar-based implementations with detection ranges up to 250 meters. Their primary commercial purpose is to reduce rear-end and sideswipe collisions while enabling partial automation in highway driving scenarios. Camera technology leads volume deployment in passenger vehicles due to lower unit costs, while lidar-based configurations represent the fastest-growing technology segment for autonomous vehicle applications where redundant sensing is mandatory. Sensor systems capture the dominant share of component value, though software margins are expanding as over-the-air feature updates become standard.
The U.S. NHTSA mandates automatic emergency braking on new light vehicles, while Euro NCAP's safety ratings reward vehicles equipped with ACC and BSD, effectively conditioning market access across European Union member states. Japan's Ministry of Land, Infrastructure, Transport and Tourism (MLIT) has advanced similar crash-avoidance requirements, creating parallel compliance obligations for suppliers serving Japanese OEM export programs. Stakeholders must monitor divergence between regional sensor performance standards and the pace at which China's SAMR aligns GB standards with UN ECE regulations.
Market Dynamics
Centralized vehicle compute architectures are collapsing discrete ECU silos into domain controllers, forcing Tier-1 suppliers to recalibrate sensor fusion software stacks and service revenue models around over-the-air update cycles rather than hardware replacement.
Growth Catalysts
- NHTSA Automatic Emergency Braking Mandate:US crash-avoidance requirements for light vehicles create baseline demand for integrated ACC and BSD sensor suites across all passenger segments.
- Electric Vehicle Platform Standardization:Battery-electric architectures from Germany, Japan, and US OEMs embed ACC and BSD as default features, normalizing active safety across price tiers.
- 77 GHz Radar Module Cost Curves:Semiconductor process improvements for millimeter-wave components reduce per-unit sensor costs, expanding addressable volume in mass-market vehicle lines.
Market Restraints
- LiDAR Raw Material Concentration:Rare earth element processing for laser emitter substrates concentrates in limited geographic corridors, creating supply vulnerability for redundant sensing tiers.
- Sensor Recalibration Labor Intensity:Camera and radar alignment following windshield replacement or collision repair requires specialized equipment and technician certification, inflating total cost of ownership.
- Euro NCAP Rating Threshold Escalation:Safety score inflation progressively tightens performance requirements, compressing margins for suppliers serving budget vehicle programs.
Strategic Opportunities
- India Automotive Safety Regulation Alignment:Bureau of Indian Standards trajectory toward UN ECE harmonization creates pre-compliance positioning window for ACC and BSD module suppliers.
- Camera-LiDAR Sensor Fusion:Convergence of vision-processing chipsets with solid-state laser scanning enables software-defined perception stacks upgradable via firmware.
- Direct-to-Consumer Aftermarket Channels:Mobile installation networks for retrofit BSD systems bypass traditional dealer service departments in price-sensitive vehicle pools.
Industry Challenges
- Functional Safety Engineer Scarcity:ISO 26262 certification expertise for automotive software development outpaces vocational pipeline output, constraining supplier R&D velocity.
- Legacy CAN Bus Integration Friction:Newer ACC control units face protocol translation complexity when interfacing with older vehicle network architectures still prevalent in commercial fleets.
- Homologation Timeline Compression:Divergent regional electromagnetic compatibility test regimes force parallel validation tracks, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market |
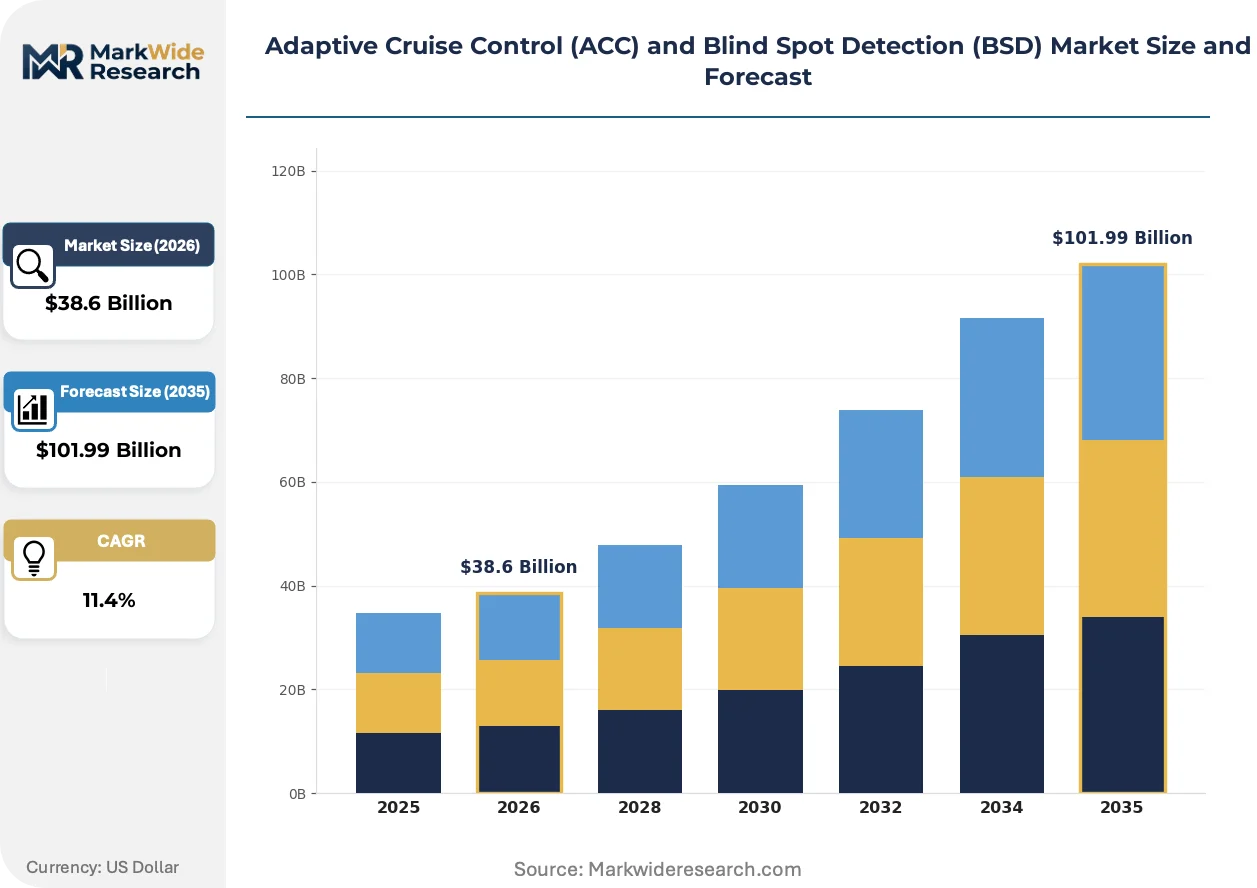
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Lidar, Camera, Ultrasonic Component: Sensor Systems, Control Units, Displays, Software End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Autonomous Vehicles |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, ZF Friedrichshafen AG, Autoliv Inc., Aptiv PLC, Valeo SA, Magna International Inc., Mobileye Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market Strategic Shifts
Sensor modality convergence and regulatory score inflation are compressing development cycles while expanding the performance envelope expected of production ACC and BSD systems. Tier-1 engineering resources are reallocating toward software-centric architectures.
Radar-camerasensor fusion is hybridizing perception architectures across premium electric vehicle platforms. Mercedes-Benz and BMW production lines now deploy unified sensor pods combining 77 GHz radar with 8-megapixel cameras behind common apertures. This integration reduces wiring harness complexity and enables single-point calibration, though it compresses supplier differentiation opportunities in discrete component markets.
Euro NCAP's 2026 protocol updates will penalize vehicles lacking active lane-keeping integration with ACC and BSD functions. European OEM engineering teams are accelerating control algorithm development to maintain five-star eligibility. The regulatory pressure most acutely affects mid-size sedan programs where cost engineering previously deferred full sensor fusion.
Fleet procurement specifications for rental and lease vehicles now mandate ACC and BSD as residual value protection measures. Hertz and Enterprise volume agreements with OEMs specify minimum active safety content, displacing previous discretionary option selection. This contractual standardization concentrates demand timing around model-year changeovers in North American and Western European markets.
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market Segmentation
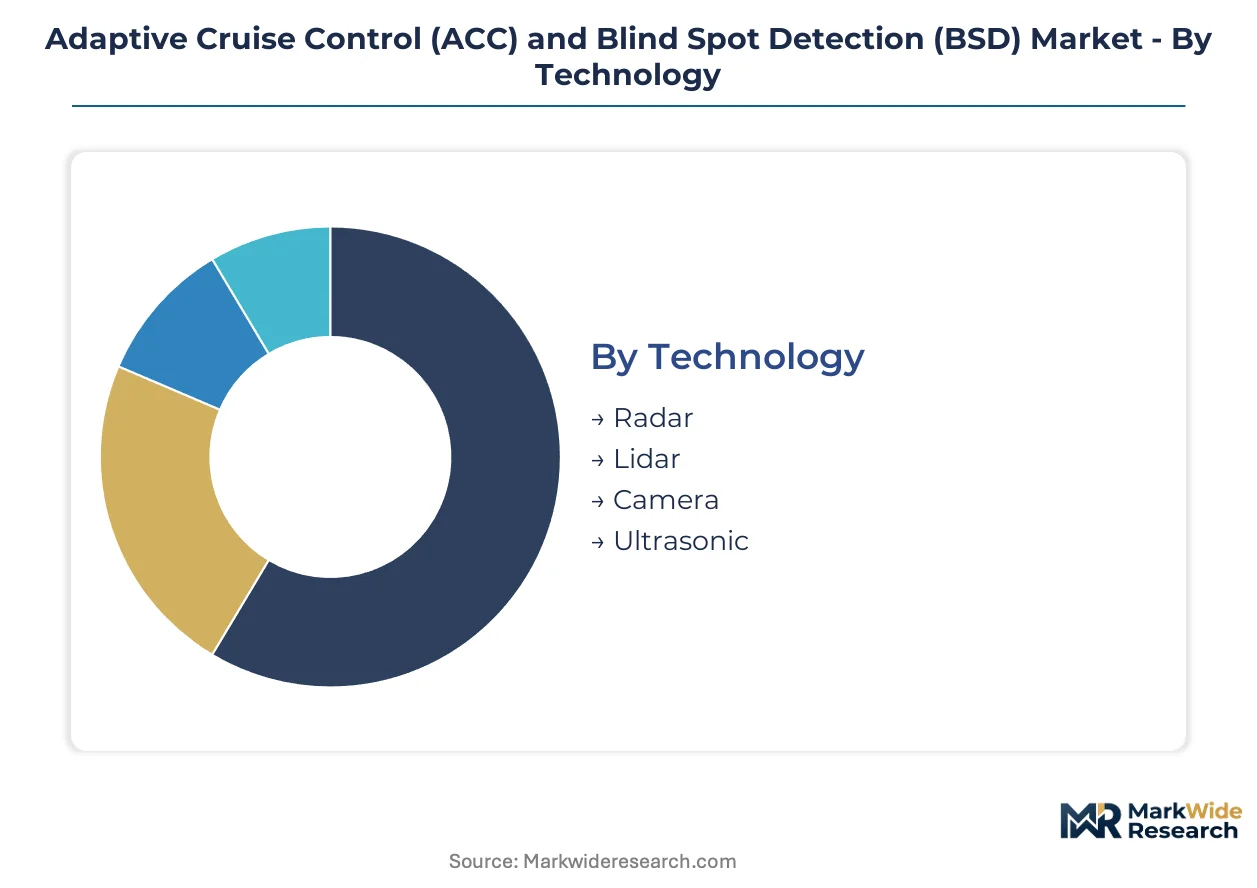
Technology modality and component architecture determine pricing tiers and integration complexity for ACC and BSD deployments. Electric vehicle platforms and regulatory mandates are compressing segmentation boundaries as sensor fusion becomes standard across application categories.
Technology:
Radar and camera implementations dominate mature production lines, while lidar and ultrasonic configurations occupy emerging autonomy tiers with distinct cost-performance profiles.
- Radar:Millimeter-wave systems operating at 24 GHz and 77 GHz frequencies provide all-weather detection ranges up to 250 meters. German and Japanese OEMs specify radar-first architectures for highway-speed ACC, leveraging established semiconductor supply chains for cost predictability.
- Camera:Vision-processing chipsets from Mobileye and competitors enable lane-keeping integration with BSD at lower unit costs than radar alternatives. Passenger vehicle volume concentrates here, though performance degrades in low-visibility conditions.
- Lidar:Solid-state laser scanning delivers redundant perception for autonomous vehicle redundancy requirements.
- Ultrasonic:Short-range proximity detection supports low-speed parking assistance and BSD gap-filling.
Camera retains volume leadership; lidar holds the steepest expansion curve.
Component:
Hardware-software value distribution is shifting as over-the-air updates enable recurring revenue from perception algorithms.
- Sensor Systems:Radar modules, camera pods, and lidar units capture dominant component value through specialized manufacturing processes. Tier-1 suppliers anchor market position through in-house production of these elements for mass-market vehicle lines.
- Software:Sensor fusion algorithms and machine learning models for object classification generate expanding margins via firmware updates. Control algorithm development accelerates as Euro NCAP tightens integration requirements.
- Control Units:Domain controllers consolidate ECU functions into centralized compute platforms.
- Displays:HMI elements for driver alerts and system status indication complete the stack.
Sensor systems retain volume leadership; software holds the steepest expansion curve.
End User:
Supply chain position determines technical specification authority and long-term service revenue access.
- OEMs:Vehicle manufacturers specify integrated ACC and BSD as platform-standard features, particularly for electric vehicle architectures. NHTSA mandates and Euro NCAP scoring directly shape their procurement priorities across German, Japanese, and US engineering centers.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG translate OEM requirements into production systems, sustaining relationships through long-term service contracts.
- Aftermarket Providers:Retrofit specialists target price-sensitive vehicle pools outside dealer networks.
- Vehicle Assemblers:Contract manufacturers execute build-to-print programs for regional markets.
OEMs retain volume leadership; aftermarket providers hold the steepest expansion curve.
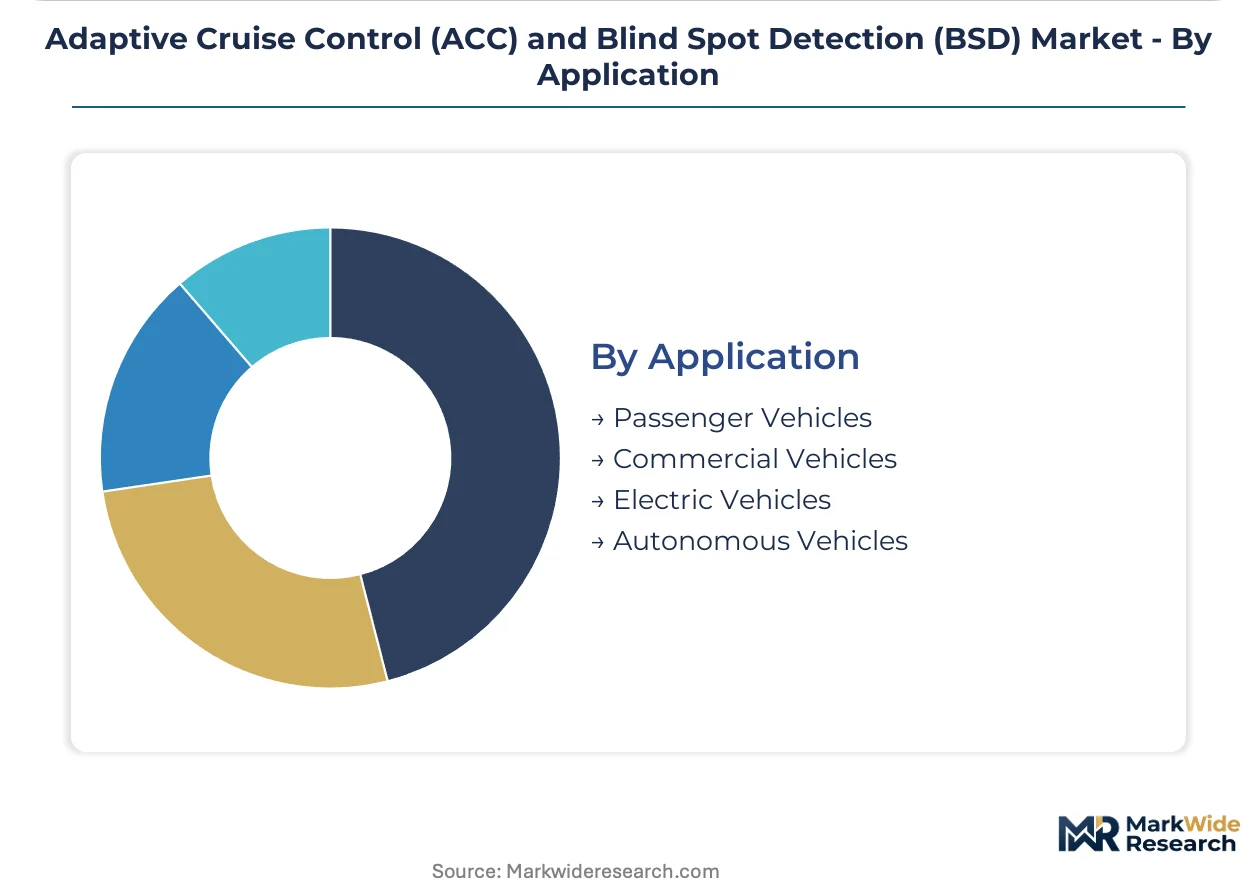
Application:
Platform electrification and automation level differentiate performance requirements and sensor modality selection.
- Passenger Vehicles:Camera-radar fusion dominates mass-market deployments where Euro NCAP five-star eligibility drives specification. Mid-size sedan programs face acute pressure to integrate active lane-keeping with ACC and BSD.
- Electric Vehicles:Battery-electric architectures normalize ACC and BSD as default features across price tiers, with sensor pods integrated into clean-sheet designs. Mercedes-Benz and BMW production lines deploy unified perception hardware behind common apertures.
- Commercial Vehicles:Fleet procurement specifications from Hertz and Enterprise mandate active safety content as residual value protection.
- Autonomous Vehicles:Redundant sensing tiers require lidar-camera-radar convergence for unsupervised operation.
Passenger vehicles retain volume leadership; electric vehicles hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German and Japanese buyers accept premium sensor fusion suites as standard equipment. Indian and Brazilian fleets remain price-sensitive, deferring full ACC-BSD integration until regulatory deadlines force compliance.
United States
Fleet procurement from Hertz and Enterprise mandates ACC-BSD content as residual value protection. NHTSA automatic emergency braking rules create baseline demand across all light vehicle segments. Detroit-area engineering centers coordinate tier-1 supplier integration for domestic OEM platforms.
Germany
Premium electric vehicle lines from Mercedes-Benz and BMW normalize unified sensor pods as default features. KBA type-approval requirements align with Euro NCAP scoring protocols. Stuttgart and Munich engineering clusters drive radar-camera fusion development for mass-market deployment.
Japan
MLIT crash-avoidance mandates parallel Euro NCAP trajectory, conditioning export program compliance. Toyota and Honda engineering specifications favor radar-first architectures for highway-speed reliability. Nagoya-area supplier networks anchor millimeter-wave semiconductor sourcing.
China
Domestic EV platforms from BYD and NIO embed active safety as competitive differentiation against legacy joint ventures. SAMR GB standard alignment with UN ECE regulations proceeds incrementally. Yangtze River Delta manufacturing clusters concentrate solid-state lidar module production.
India
Bureau of Indian Standards trajectory toward UN ECE harmonization creates pre-compliance positioning for module suppliers. Maruti Suzuki and Hyundai Motor India face cost engineering pressure on budget vehicle programs. Tamil Nadu and Gujarat automotive corridors attract tier-1 sensor assembly investments.
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market Competitive Environment
Capability concentration sits with semiconductor and software specialists; scale advantage sits with diversified tier-1 conglomerates. The vendor base stratifies across three archetypes: integrated automotive suppliers with captive sensor production, vision-processing chipset specialists, and domain-controller platform architects. Consolidation pressure intensifies as centralized compute architectures collapse discrete ECU procurement. Dominant competitive moves include strategic partnerships for sensor fusion software stacks and backward integration into radar module fabrication.
Within the integrated supplier tier, Robert Bosch GmbH and Continental AG exemplify scale-driven positioning through long-term OEM service contracts. Mobileye Global Inc. occupies the vision-processing specialist archetype, anchoring camera-based BSD deployments across multiple automaker programs. These three entities represent distinct competitive vectors: hardware-integrated scale, software-centric differentiation, and sensor-modality convergence.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| ZF Friedrichshafen AG |
| Autoliv Inc. |
| Aptiv PLC |
| Valeo SA |
| Magna International Inc. |
| Mobileye Global Inc. |
| Others |
Value Chain & Pricing Dynamics
Rare earth element processing concentration for laser emitter substrates determines both tiered pricing spreads and supply chain vulnerability in ACC and BSD sensor production. This single-source dependency for lidar-grade substrates widens cost differentials between camera-radar fusion tiers and full redundancy configurations while forcing OEMs into long-term offtake commitments.
Pricing Analysis
Aftermarket sensor recalibration and software update contracts drive lifetime value capture for tier-1 suppliers serving European OEM programs. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 functional safety certification level and volume scale commitments. Cost compression in mass-market radar modules intensifies as 77 GHz semiconductor process improvements mature. Fleet procurement managers at Hertz and Enterprise exhibit lowest price sensitivity due to residual value protection mandates, while budget vehicle programs in India face acute margin pressure.
Supply Chain Analysis
Export-control restrictions on millimeter-wave semiconductor fabrication equipment limit capacity expansion outside established corridors. Supply concentrates in Germany, Japan, and Taiwan for radar module production, with Yangtze River Delta clusters dominating solid-state lidar assembly. Gallium nitride substrates, indium phosphide wafers, and specialized optical coatings constitute critical input dependencies. Single-source vulnerability in rare earth element processing for laser emitters creates tariff exposure. Distribution runs through tier-1 supplier direct OEM contracts with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ACC and BSD market expansion sits in early-cycle penetration acceleration. NHTSA automatic emergency braking mandates and Euro NCAP score inflation create irreversible adoption tailwinds across passenger and commercial vehicle segments.
For Market Incumbents: Harden defensive positioning through backward integration into 77 GHz radar module fabrication and captive sensor pod production. Centralized compute architectures threaten discrete ECU revenue streams; incumbents must secure long-term service contracts for over-the-air update cycles. Certification investment in ISO 26262 functional safety expertise constrains R&D velocity for competitors.
For New Entrants and Emerging Players: Direct-to-consumer aftermarket channels for retrofit BSD systems in price-sensitive vehicle pools outside dealer networks represent the most penetrable entry point. India's pre-compliance window ahead of Bureau of Indian Standards UN ECE harmonization offers geographic white-space. Mobile installation networks bypassing traditional service departments provide the critical go-to-market angle.
For Investors and Strategic Acquirers: Euro NCAP's 2026 protocol updates reshaping the acquisition landscape toward sensor fusion software specialists. Long-term viability centers on domain-controller platform architects with recurring firmware revenue models. Watch for divergence between China's SAMR GB standard alignment pace and UN ECE regulations as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Mercedes-Benz and BMW unified sensor pods reduce wiring complexity and enable single-point calibration protocols. |
| Software-Defined Vehicle Investment | Over-the-air perception algorithm updates transform hardware margins into recurring service revenue streams. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat corridors attract tier-1 sensor assembly investments ahead of Indian regulatory alignment. |
| Battery Supply Agreement | Electric vehicle platform standardization embeds ACC and BSD as default features across all price tiers. |
| Charging Infrastructure Partnership | Fleet procurement specifications from rental operators mandate active safety content as residual value protection. |
Study Parameters
Desk research of vehicle production databases, regulatory filing repositories, and tier-1 supplier financial disclosures preceded structured interviews with OEM platform engineers, tier-1 procurement directors, aftermarket distributors, and functional safety certification specialists. Secondary validation drew from NHTSA rulemaking dockets, Euro NCAP test protocols, and MLIT technical standards. Bottom-up sensor shipment estimates and top-down automotive electronics spend analysis were triangulated against production volume forecasts.
Assumptions held fixed included NHTSA mandate implementation timelines, Euro NCAP scoring weightings, and semiconductor process cost curves; variables stress-tested encompassed rare earth supply disruptions, regional regulatory divergence, and EV platform adoption rates. The analytical framework modeled technology modality, component architecture, end-user supply chain position, and application electrification level across the projection horizon. CAGRs were derived from segment-level volume trajectories and content-per-vehicle escalation curves, with 77 GHz radar cost reduction and lidar module yield improvement as key forecast inputs.
Stress conditions across rare earth element availability, electromagnetic compatibility test regime divergence, and functional safety engineer pipeline output were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and boundary conditions. Material shifts in China's SAMR GB standard harmonization pace or UN ECE regulatory alignment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Africa Autonomous Navigation Market