
 Autonomous Delivery Vehicle Market | 2026-2036
Autonomous Delivery Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Delivery Vehicle Market Intelligence
Food delivery is hardening as the dominant end-use vertical, displacing early pilot deployments in campus mail services. Nuro sustains a narrow product focus on neighborhood grocery and pharmacy routes with its custom-built zero-occupant vehicles. Starship Technologies dominates sidewalk robot density across European and North American university towns. Amazon extends its logistics footprint through autonomous middle-mile trucking trials between fulfillment nodes.
Autonomous delivery vehicles are self-guiding transport systems that combine lidar arrays, stereo cameras, and differential GPS to navigate pre-mapped corridors without human steering input, purpose-built to move goods from distribution nodes to end consumers at speeds below 50 km/h. Ground robots occupy the most mature segment with proven unit economics in controlled environments, while drone platforms represent the fastest-growing category as battery energy density improves and beyond-visual-line-of-sight frameworks expand. Machine learning models trained on pedestrian behavior patterns differentiate operational reliability across competing technology stacks.
The US DOT and FAA jointly govern street and airspace access, with the FAA's Part 135 drone certification creating a regulated on-ramp for aerial delivery operators. The EU AI Act and CE marking requirements impose algorithmic transparency standards on autonomous navigation systems entering European cities. Stakeholders must monitor how municipal permitting fragmentation across jurisdictions shapes scalable deployment economics.
Market Dynamics
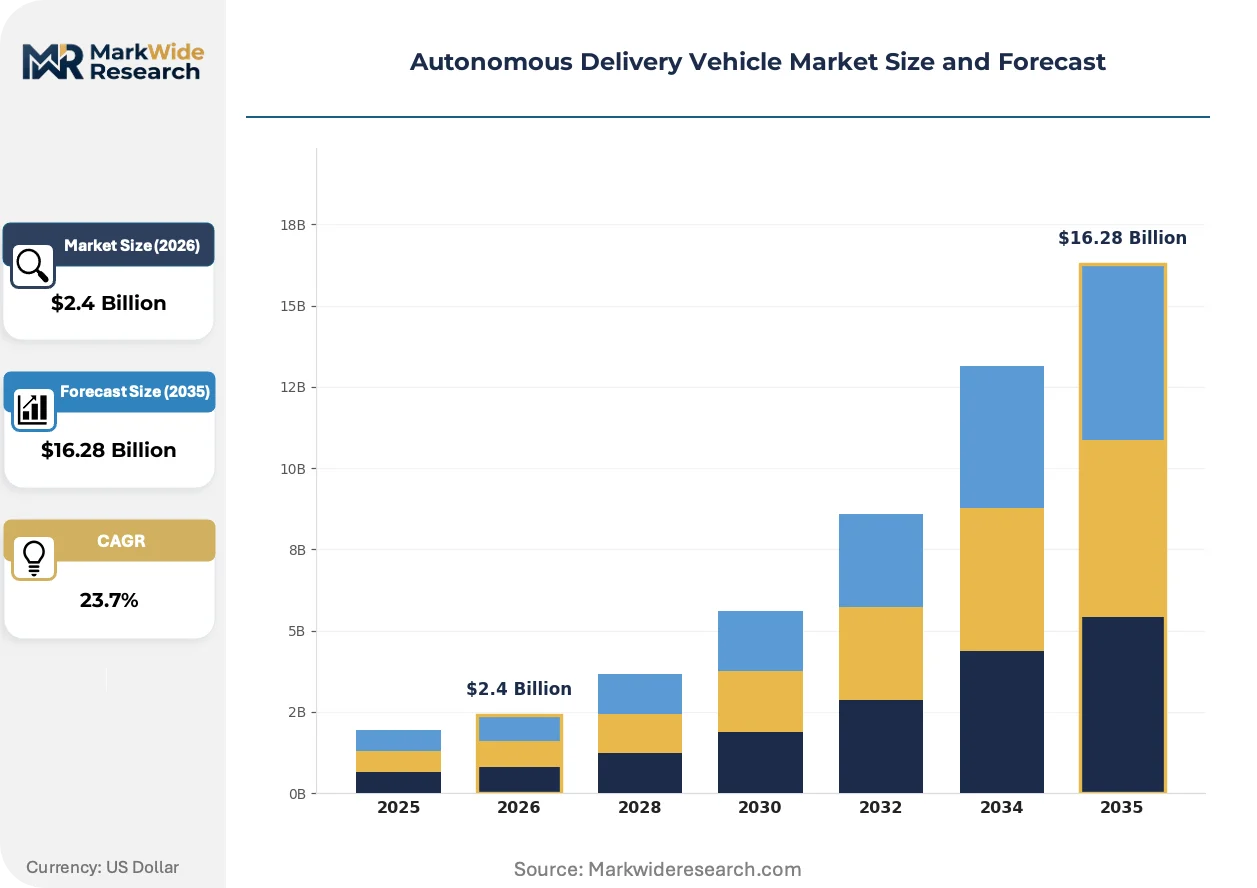
Last-mile labor inflation is compressing unit economics across parcel networks, forcing operators toward autonomous alternatives as wage floors rise faster than delivery pricing power. The shift from pilot programs to fleet-scale deployment hinges on municipal permitting velocity and insurance framework clarity.
Growth Catalysts
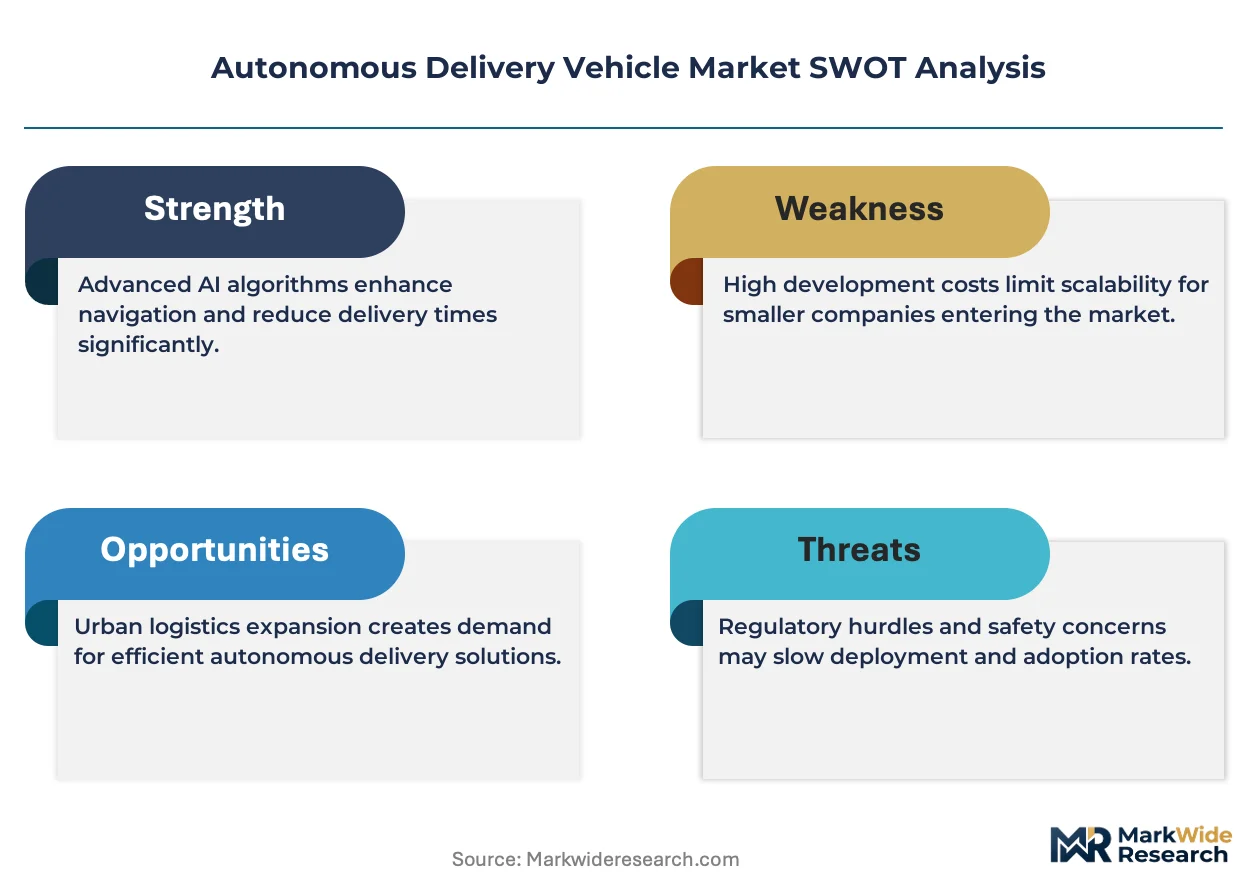
- US DOT AV Guidance:Streamlined street-deployment permits for small ground robots reduce regulatory friction in dense urban corridors. Local authorities in California, Texas, and Arizona issue experimental licenses with reduced compliance overhead.
- Battery Energy Density Gains:Solid-state cell chemistry advances extend aerial drone range thresholds, unlocking suburban delivery loops previously uneconomical for rotorcraft platforms.
- Food Service Labor Shortages:Quick-service restaurant chains and ghost kitchen operators deploy sidewalk robots to offset kitchen-to-curb staffing gaps during peak demand windows.
Market Restraints
- Lidar Sensor Supply Concentration:Production of 1550nm wavelength units clusters among Asian optical component foundries, creating single-source vulnerability for perception stack manufacturers.
- Municipal Permitting Fragmentation:No federal preemption exists for sidewalk robot operation; operators face 50-state patchwork of local ordinances, insurance mandates, and speed-limit variations.
- Weather-Induced Downtime:Snow accumulation and ice formation disable camera-based navigation systems, forcing fleet idling in northern climates during winter quarters.
Strategic Opportunities
- India Dense Urban Corridors:Narrow street geometry and two-wheeler traffic patterns favor small-form ground robots over van-based delivery in Mumbai, Bangalore, and Delhi metropolitan zones.
- EU AI Act Algorithmic Transparency:CE marking requirements for autonomous navigation systems create compliance-as-a-service revenue streams for certification consultancies and testing laboratories.
- Pharmaceutical Cold Chain Convergence:Integration of refrigerated compartments with autonomous chassis addresses temperature-sensitive prescription delivery in retirement community clusters.
Industry Challenges
- Edge Case Annotation Bottleneck:Training datasets for pedestrian collision avoidance require millions of labeled scenarios; annotation labor costs constrain model iteration velocity for mid-tier developers.
- FAA Part 135 Certification Timeline:Drone operators face 18-24 month approval windows for beyond-visual-line-of-sight operations, delaying revenue generation after prototype validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Delivery Vehicle Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $16.28 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Robots, Drones, Autonomous Trucks, Delivery Pods Technology: GPS Navigation, Computer Vision, Lidar, Machine Learning End User: E-commerce, Food Delivery, Retail, Logistics Deployment Model: On-demand, Scheduled, Hybrid, Fixed-route |
| Companies Covered | Starship Technologies, Nuro, Amazon, JD.com, Udelv, Marble Robot, Kiwibot, Flytrex, Drone Delivery Canada, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Delivery Vehicle Market Strategic Shifts & Innovations
Perception hardware commoditization is flattening technology moats, shifting competitive advantage toward fleet management software and regulatory navigation capabilities. Operators now differentiate through operational density rather than sensor sophistication alone.
Solid-state lidar arrays are electrifying cost structures for autonomous navigation stacks. Unit prices for automotive-grade sensors dropped below five hundred dollars in volume procurement contracts during 2024. Tier-2 logistics providers in Germany and Japan now specify these components for middle-mile trucking retrofits. The technology is electrifying entry barriers, enabling capital-constrained regional carriers to field autonomous capabilities without proprietary hardware development.
The EU AI Act's risk-classification framework for autonomous systems imposes algorithmic audit requirements on navigation software deployed in European cities. CE marking now demands documented training data provenance and bias testing protocols. Ground robot manufacturers targeting Paris, Berlin, and Amsterdam municipal contracts must embed compliance documentation into product development cycles, extending time-to-market by six to nine months relative to US deployments.
Restaurant chains are consolidating delivery procurement around autonomous fleet operators with guaranteed uptime service-level agreements. Traditional per-dispatch gig economy models face displacement as enterprise buyers prioritize reliability metrics over marginal cost savings. This concentration is most visible in South Korean dense districts, where franchise operators negotiate exclusive autonomous delivery partnerships covering multiple brand portfolios within single geographic zones.
Autonomous Delivery Vehicle Market Segmentation
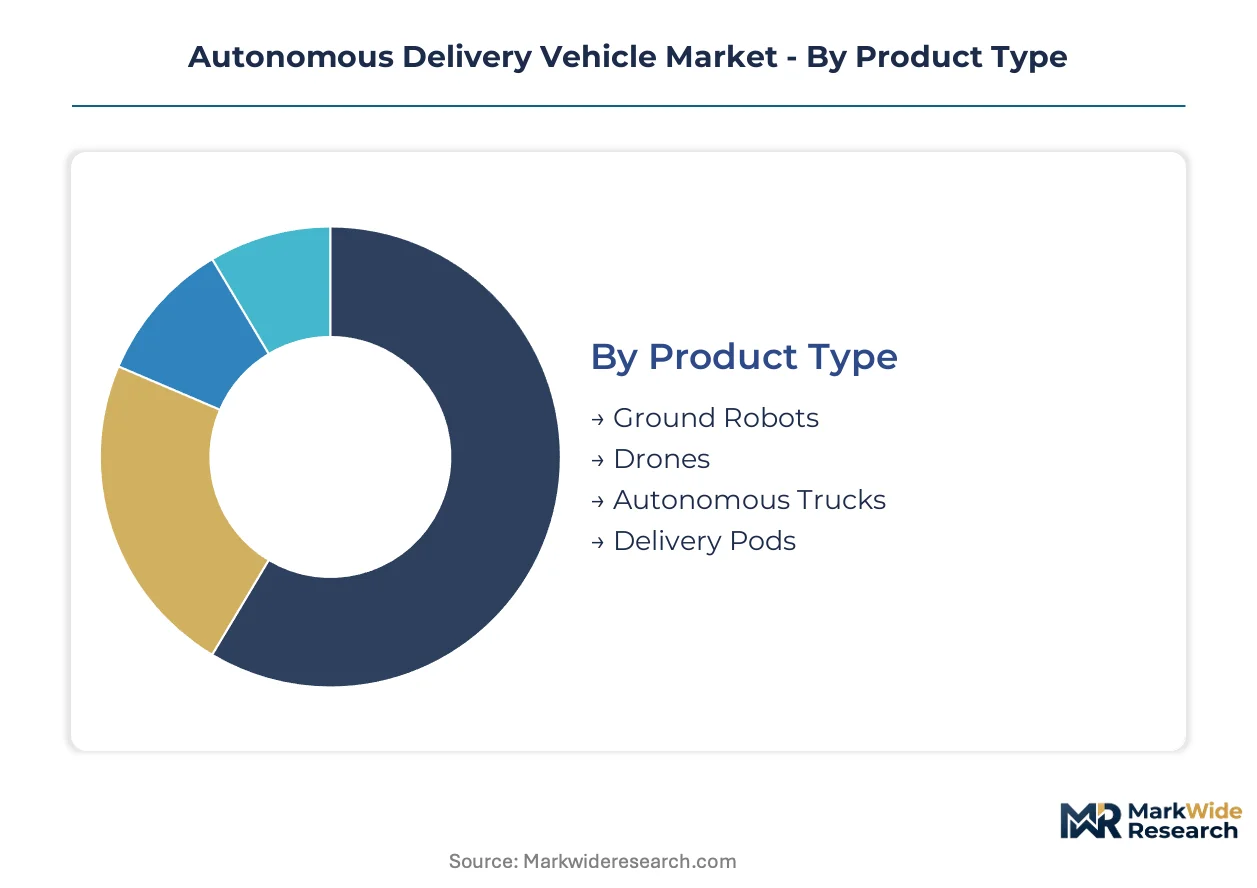
Segmentation in autonomous delivery vehicles reveals divergent technology maturity curves and regulatory exposure profiles. Ground robots and drones operate under fundamentally different airspace versus sidewalk governance regimes. Understanding these fault lines shapes capital allocation across hardware platforms and operational models.
Product Type:
Volume economics favor sidewalk robots while premium capabilities concentrate in aerial platforms. The cost-per-mile spread between these modalities exceeds an order of magnitude, driving divergent deployment strategies.
- Ground Robots:Low-speed electric chassis with differential GPS and ultrasonic obstacle detection navigate pedestrian corridors at under 6 km/h. JD.com deploys thousands across Chinese urban districts where sidewalk width accommodates two-meter form factors. Labor arbitrage in dense metropolitan zones accelerates fleet scaling.
- Drones:Multi-rotor and fixed-wing platforms carry sub-5kg payloads via beyond-visual-line-of-sight corridors. Battery chemistry improvements extend suburban delivery radii beyond previous rotorcraft limitations. FAA Part 135 certification timelines constrain near-term revenue recognition for US operators.
- Autonomous Trucks:Middle-mile chassis with SAE Level 4 highway automation connect distribution nodes on fixed interstate corridors. Tier-1 automotive suppliers integrate redundant steering and braking for 80,000-pound gross vehicle weight ratings.
- Delivery Pods:Enclosed cargo compartments mounted on autonomous chassis protect pharmaceuticals and prepared meals from environmental exposure. Refrigeration integration targets healthcare and food service procurement specifications.
Today's leader: Ground Robots. Tomorrow's challenger: Drones.
Technology:
Perception stack costs now stratify entry barriers more than software differentiation. Sensor commoditization shifts competitive advantage toward fleet management and regulatory navigation capabilities.
- GPS Navigation:Differential correction services achieve sub-10cm accuracy in open-sky environments. Urban canyon multipath errors persist in Manhattan and Hong Kong high-rise districts, requiring sensor fusion with visual odometry.
- Computer Vision:Stereo camera arrays process pedestrian intent recognition at 30 frames per second. Annotation bottlenecks for edge case training data constrain mid-tier developer iteration velocity.
- Lidar:Solid-state 1550nm wavelength units from Asian optical foundries enable 200-meter range detection in adverse weather. Supply concentration creates single-source vulnerability for perception stack manufacturers.
- Machine Learning:Behavioral prediction models trained on millions of labeled pedestrian trajectories differentiate collision avoidance reliability. EU AI Act algorithmic audit requirements extend European deployment timelines.
Cost leadership: GPS Navigation. Capability frontier: Machine Learning.
End User:
Procurement concentration around enterprise fleet operators displaces gig-economy dispatch models. Guaranteed uptime service-level agreements now outweigh marginal per-delivery cost savings in vendor selection.
- E-commerce:Fulfillment center operators deploy autonomous middle-mile trucking between sortation nodes. Amazon's pilot programs connect regional distribution centers on scheduled corridors.
- Food Delivery:Quick-service restaurant chains and ghost kitchen operators deploy sidewalk robots for kitchen-to-curb handoffs. South Korean franchise operators negotiate exclusive autonomous partnerships covering multiple brand portfolios within single geographic zones.
- Retail:Grocery and pharmacy chains specify refrigerated compartments for temperature-sensitive prescription delivery. Nuro's zero-occupant vehicles target neighborhood grocery routes with custom-built chassis.
- Logistics:Parcel networks integrate autonomous first-mile and last-mile segments with conventional hub-and-spoke infrastructure. Labor inflation compresses unit economics, forcing automation adoption.
Current procurement concentration: Food Delivery. Expanding fastest: E-commerce.
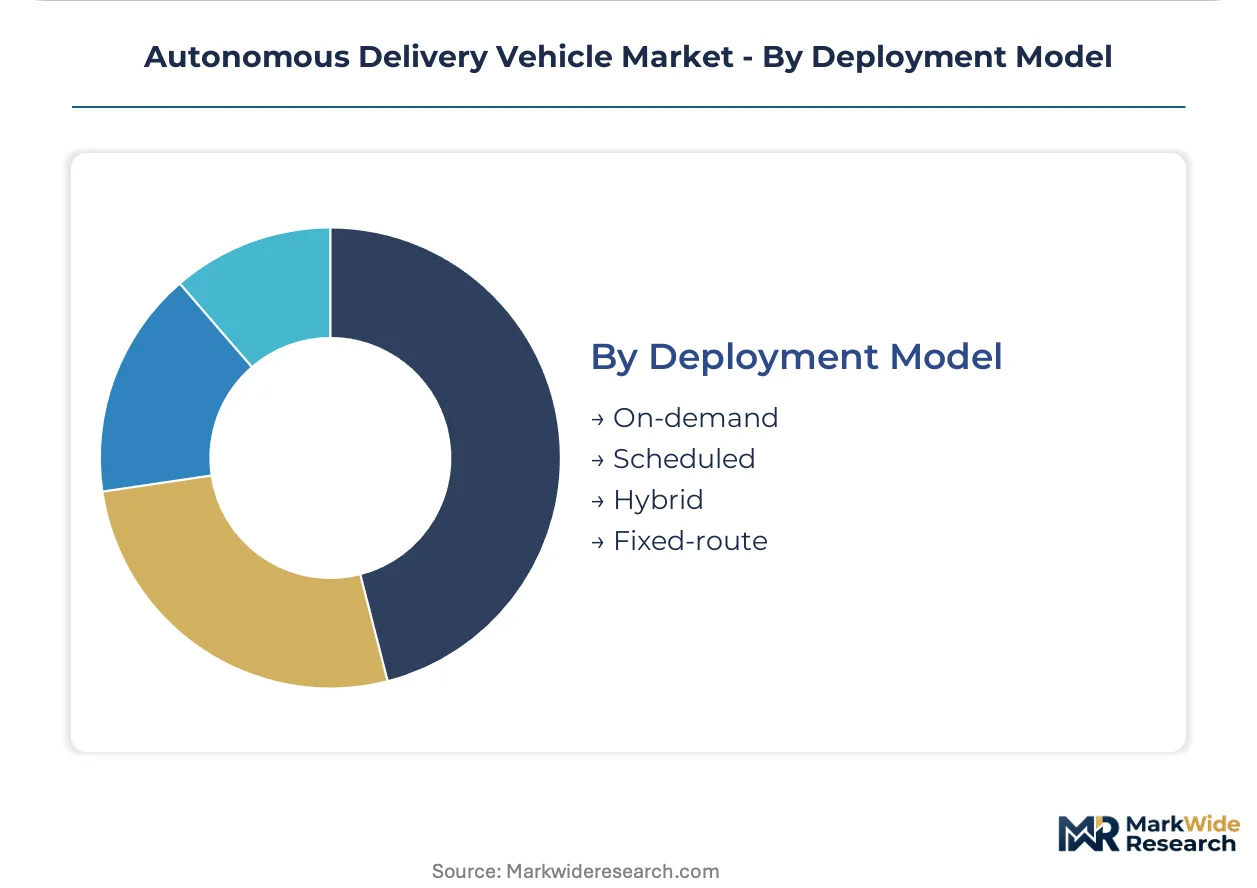
Deployment Model:
Operational predictability versus demand responsiveness defines the strategic trade-off. Fixed-route models amortize capital costs through utilization density; on-demand captures variable demand spikes.
- On-demand:Dynamic routing algorithms dispatch nearest-available units in response to real-time order flow. Starship Technologies dominates university town density with this model across European and North American campuses.
- Scheduled:Pre-planned circuits between distribution nodes and delivery zones optimize fleet utilization during known demand windows. Pharmaceutical distributors favor this model for retirement community clusters.
- Hybrid:Fixed-route backbone with on-demand last-mile flexibility balances utilization and responsiveness. Municipal permitting fragmentation complicates scalable deployment across jurisdiction boundaries.
- Fixed-route:Dedicated corridors with pre-mapped waypoints minimize real-time computational load. Campus mail services and industrial park logistics favor this constrained operational envelope.
Scale economics favor: Scheduled. Flexibility premium: On-demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
JD.com operates thousands of ground robots across China's dense urban corridors, establishing the world's largest deployed fleet and defining the benchmark for sidewalk robot density in metropolitan delivery networks.
United States
Food service labor shortages and rising wage floors drive quick-service restaurant chains toward autonomous kitchen-to-curb solutions. The FAA's Part 135 certification framework governs beyond-visual-line-of-sight drone operations, creating 18-24 month approval timelines. California, Texas, and Arizona municipal authorities issue experimental street-deployment licenses with reduced compliance overhead for small ground robots.
China
E-commerce fulfillment center expansion and last-mile labor cost inflation compress parcel network economics toward automation. The Ministry of Industry and Information Technology (MIIT) oversees autonomous vehicle testing permits and GB standard compliance for navigation systems. JD.com concentrates fleet operations in Beijing, Shanghai, and Shenzhen metropolitan zones where sidewalk width accommodates two-meter robot form factors.
Germany
Tier-2 logistics providers specify solid-state lidar components for middle-mile trucking retrofits as sensor costs drop below volume procurement thresholds. The KBA (Kraftfahrt-Bundesamt) regulates autonomous vehicle type approval under EU framework harmonization. Industrial automation clusters in Bavaria and Baden-Württemberg host testing corridors for SAE Level 4 highway automation between distribution nodes.
South Korea
Franchise operators negotiate exclusive autonomous delivery partnerships covering multiple quick-service brand portfolios within single geographic zones. The Ministry of Food and Drug Safety (MFDS) and municipal authorities coordinate permitting for food-service robot deployment. Seoul Capital Area dense districts concentrate procurement concentration around guaranteed uptime service-level agreements displacing gig-economy dispatch models.
United Kingdom
University towns across England and Scotland host high sidewalk robot density deployments targeting campus mail services and student residential corridors. The Department for Transport issues code of practice guidance for automated vehicle trials while local highway authorities retain permitting authority. Cambridge and Oxford technology clusters anchor perception software development and pedestrian behavior model training operations.
Autonomous Delivery Vehicle Market Key Industry Players
Strategic partnerships dominate the current landscape as operators seek municipal permitting velocity and insurance framework clarity to bridge pilot-to-fleet scaling gaps. The vendor base stratifies across three tiers: technology-integrated automotive suppliers, pure-play autonomous chassis developers, and fleet management software platforms. Two archetypes define positioning: hardware-agnostic operators leveraging commoditized sensor stacks, and vertically integrated developers controlling proprietary perception systems. Technology licensing agreements and geographic expansion into regulatory-friendly jurisdictions constitute the dominant competitive moves.
Among North American pure-play developers, Nuro and Starship Technologies occupy distinct archetype positions. Nuro represents the zero-occupant custom chassis approach with neighborhood grocery and pharmacy route specialization. Starship Technologies exemplifies high-density sidewalk robot deployment across European and North American controlled environments. JD.com anchors the integrated e-commerce operator model, leveraging captive logistics demand to scale fleet economics in Chinese urban corridors.
| Leading Market Players |
|---|
| Starship Technologies |
| Nuro |
| Amazon |
| JD.com |
| Udelv |
| Marble Robot |
| Kiwibot |
| Flytrex |
| Drone Delivery Canada |
| Others |
Cost & Logistics Intelligence
Solid-state lidar cost electrification simultaneously compresses perception stack economics and redistributes supply power toward Asian optical foundries, collapsing hardware moats while concentrating component sourcing risk in fewer production nodes.
Pricing Analysis
Input-cost pass-through from 1550nm wavelength sensor procurement dominates ground robot unit economics, with volume tiering separating fleet-scale operators from pilot-stage developers. Price differentiation rests on CE marking compliance depth and guaranteed uptime service-level agreements, with municipal permitting velocity as a secondary tier. Pricing pressure stems from solid-state lidar commoditization below five hundred dollar thresholds in automotive-grade contracts. Quick-service restaurant chains exhibit highest price sensitivity due to kitchen-to-curb margin compression, while pharmaceutical distributors accept premium positioning for refrigerated compartment integration.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese and Chinese optical component foundries producing solid-state lidar arrays at volume scale. The autonomous delivery vehicle supply chain draws from South Korean battery cell manufacturers, German automotive-grade braking systems, and Japanese precision motor suppliers. Tariff exposure on perception hardware imports creates margin volatility for North American chassis assemblers lacking captive Asian sourcing. Distribution runs through Tier-1 automotive suppliers retrofitting middle-mile trucking fleets, with direct OEM relationships dominating last-mile ground robot deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous delivery vehicle market compounds steadily as last-mile labor inflation forces parcel networks toward automation across successive wage cycles.
For Market Incumbents: Deepen fleet management software differentiation as perception hardware commoditization erodes sensor-based moats. Secure exclusive municipal permitting partnerships in California, Texas, and Arizona corridors before regulatory velocity slows. Invest in CE marking compliance documentation to compress European deployment timelines against EU AI Act audit requirements.
For New Entrants and Emerging Players: Enter via pharmaceutical cold chain convergence in retirement community clusters, where refrigerated autonomous chassis face limited incumbent penetration. Target Indian dense urban corridors in Mumbai and Bangalore, where narrow street geometry favors small-form ground robots over van-based delivery. Pursue compliance-as-a-service positioning for algorithmic transparency consulting under EU AI Act frameworks.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play fleet management software platforms lacking captive hardware development overhead. Five-to-ten year viability favors operators with demonstrated municipal permitting velocity and insurance framework clarity bridging pilot-to-fleet scaling gaps. Monitor FAA Part 135 certification timeline compression as inflection signal for aerial drone revenue recognition acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Municipal Permitting Partnership | California and Arizona authorities issue experimental licenses with reduced compliance overhead for sidewalk robot deployment. |
| CE Marking Compliance Investment | EU AI Act algorithmic audit requirements extend European time-to-market by six to nine months relative to US deployments. |
| Refrigerated Compartment Integration | Pharmaceutical distributors specify temperature-controlled chassis for prescription delivery in retirement community clusters. |
| Solid-State Lidar Volume Procurement | Tier-2 logistics providers in Germany and Japan specify automotive-grade sensors below five hundred dollar thresholds. |
| Beyond-Visual-Line-of-Sight Certification | FAA Part 135 approval timelines constrain near-term revenue recognition for US aerial drone operators. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with autonomous vehicle fleet operators, municipal permitting officers, quick-service restaurant procurement leads, and pharmaceutical distribution logistics directors with secondary validation against SEC filings, FAA Part 135 certification databases, EU AI Act implementation guidance, and customs trade data on optical component imports. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates across ground robot, drone, and autonomous truck segments.
Historical deployment data anchored projection parameters across the analysis window, with segmentation dimensions spanning product type, navigation technology stack, end-use vertical, and deployment model. CAGRs derived from logistic diffusion curves fitted to fleet scaling patterns in Chinese, US, and European corridors. Forecast inputs incorporated battery energy density improvement trajectories and municipal permitting velocity assumptions by regulatory jurisdiction cluster.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time fleet utilization metrics from private operators introduce uncertainty bands around revenue recognition timing. Forecasts reflect documented assumptions on certification timeline compression and labor cost inflation persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Africa Autonomous Navigation Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Europe IoT Connected Cars Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Driverless Cab Service Market