
 Autonomous Electric Bus Market | 2026-2036
Autonomous Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Electric Bus Market Insights
China is fragmenting as domestic manufacturers scale battery-electric output for autonomous platforms. Yutong Bus anchors the Asia-Pacific supply base through integrated chassis-electronics production. BYD Co. Ltd. leverages its cell-to-pack battery architecture to sustain cost advantages in long-range configurations. AB Volvo competes on safety-system redundancy for European municipal tenders.
An autonomous electric bus integrates electric drivetrains with automated driving systems to eliminate onboard operators while maintaining scheduled service. These platforms typically deploy lidar arrays, solid-state batteries, and redundant steering actuators to achieve operational design domain compliance for fixed-route deployment. Battery Electric Bus configurations dominate current procurement volumes, while Level 4 Automation systems capture the dominant share of embedded technology value. V2X Communication infrastructure represents the fastest-growing technology segment as cities prioritize intersection coordination over full cabin-empty operation.
EU Green Deal emissions targets and EMA urban air quality directives are accelerating fleet replacement timelines across European municipalities. NHTSA automated vehicle guidance and EPA zero-emission transit mandates shape product certification requirements for manufacturers targeting North American deployment. Stakeholders must weigh sensor hardware costs against operational labor savings when structuring procurement models for mixed-automation fleets.
Market Dynamics
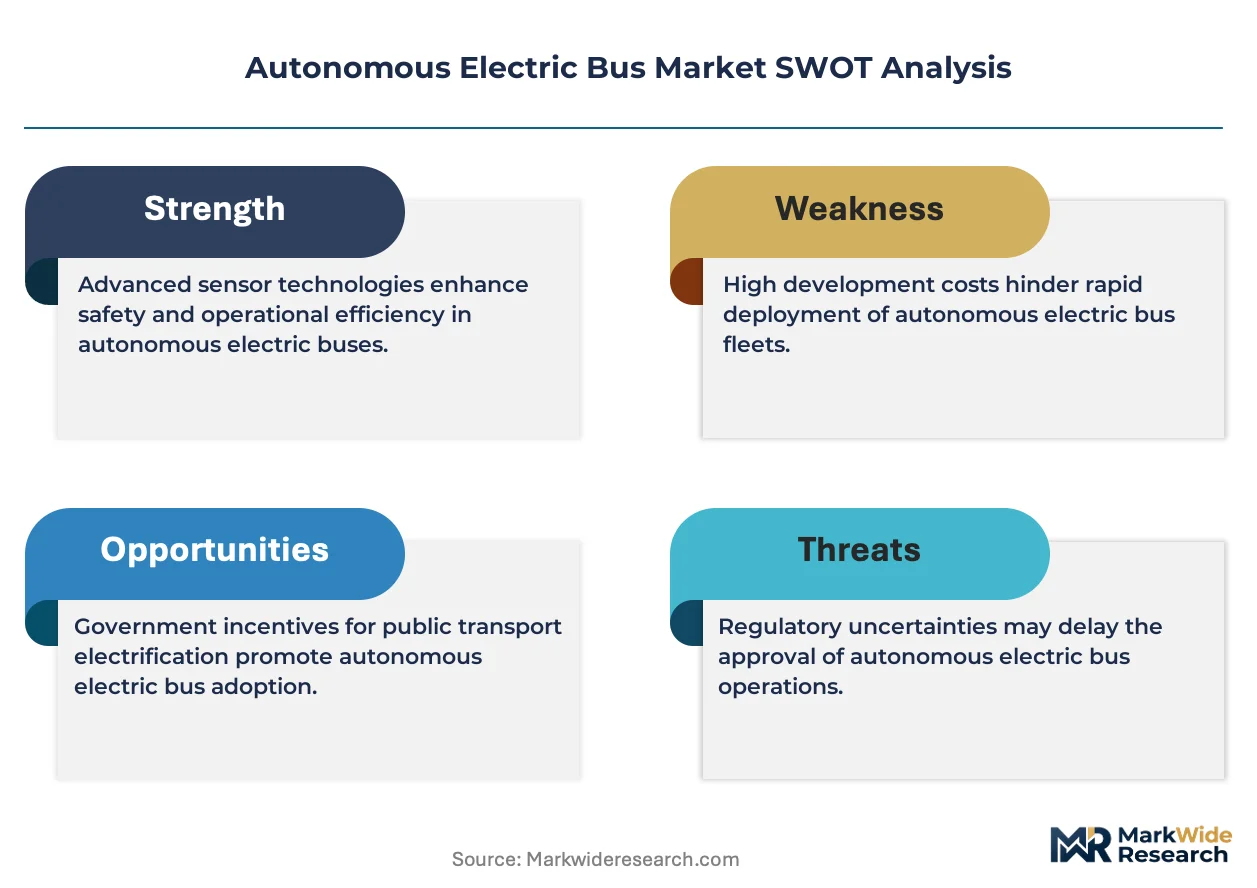
Level 4 automation software is concentrating procurement decisions among municipal transit agencies that demand fixed-route operational design domain compliance without onboard operators.
Growth Catalysts
- EU Green Deal mandates:German municipal transit agencies are expanding pilot fleets to meet binding emissions targets and urban air quality directives.
- Solid-state battery chemistries:Cell-to-pack architectures are extending operational range for fixed-route configurations while reducing thermal management overhead.
- V2X Communication infrastructure:Cities in Singapore are prioritizing intersection coordination systems that enable mixed-traffic deployment ahead of full cabin-empty operation.
Market Restraints
- Lidar sensor cost structure:Solid-state lidar arrays remain the dominant hardware expense in Level 4 automation stacks, compressing margin structures for fleet-scale deployments.
- Redundant actuator supply concentration:Steering and braking actuator manufacturing clusters in Germany and Japan create single-source vulnerability for safety-system procurement.
- Operational design domain limitation:Current automation software cannot handle unmapped construction zones or severe weather without human intervention, restricting deployable routes.
Strategic Opportunities
- EMA urban air quality directives:Fleet replacement timelines across French and Italian municipalities are accelerating tender volumes for zero-emission autonomous platforms.
- Convergence of V2X and edge computing:Real-time intersection processing is enabling traffic-signal prioritization that improves schedule adherence without dedicated bus lanes.
- India's PLI scheme for advanced chemistry cells:Domestic cell manufacturing incentives are creating localized battery supply for autonomous electric bus assembly in the Asia-Pacific region.
Industry Challenges
- Functional safety certification timeline:ISO 26262 ASIL-D compliance for autonomous steering systems requires 18-24 month validation cycles that delay fleet revenue recognition.
- Legacy transit management system integration:Proprietary fleet dispatch protocols from incumbent suppliers create API friction that complicates automation software deployment.
- Autonomous systems engineering talent scarcity:Competition with passenger vehicle automation programs is constraining availability of perception-stack specialists for commercial vehicle applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Electric Bus Market |
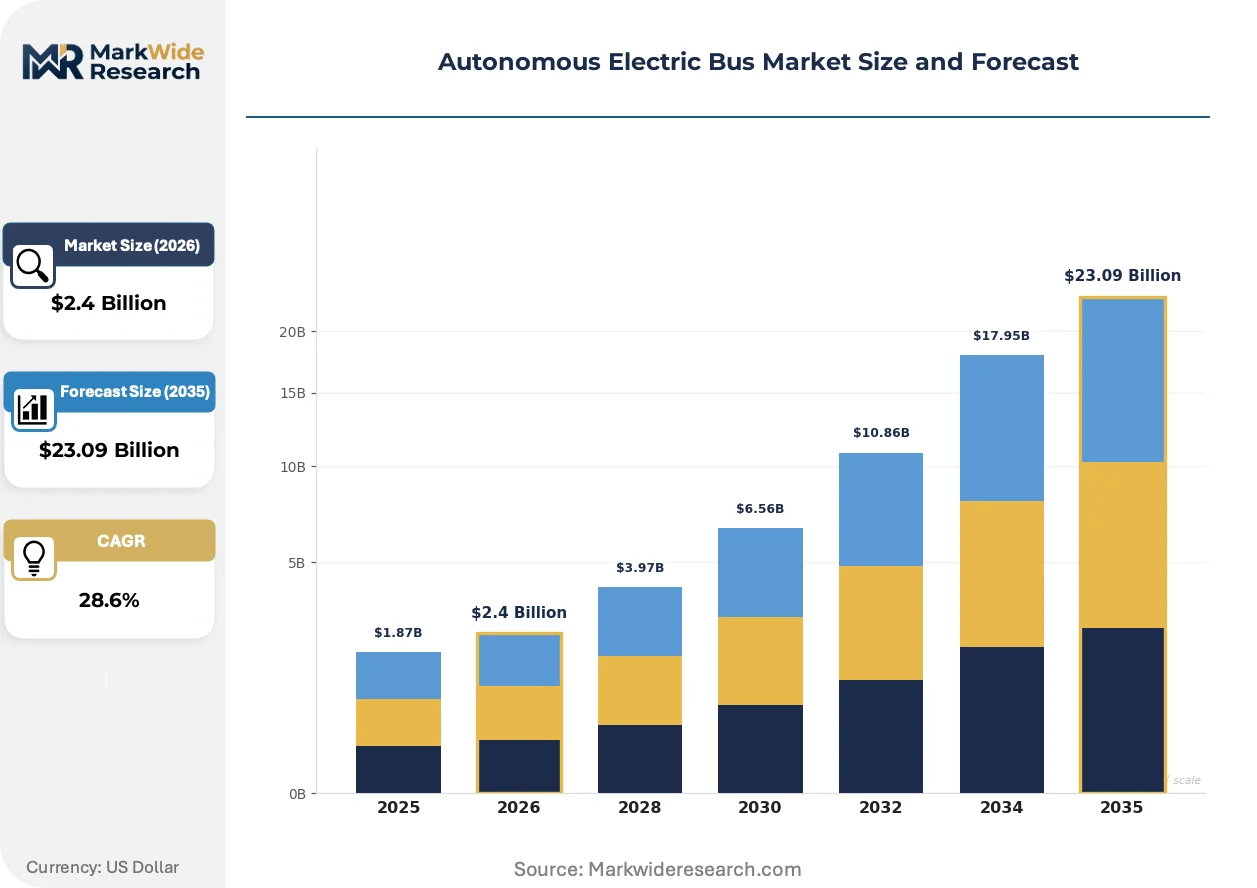
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $23.09 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Bus, Hydrogen Fuel Cell Bus, Plug-in Hybrid Bus, Standard Electric Bus Application: Public Transport, Shuttle Services, School Transportation, Long-Distance Travel Technology: Level 4 Automation, Level 5 Automation, Sensor Fusion, V2X Communication End User: Municipalities, Private Operators, Transportation Authorities, Corporate Fleets |
| Companies Covered | Yutong Bus, BYD Co. Ltd., AB Volvo, EasyMile SAS, Navya, Proterra, MAN Truck & Bus, NFI Group, Daimler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Electric Bus Market Trends and Innovations
Fixed-route automation is hybridizing hardware architectures as transit agencies balance sensor redundancy against capital constraints. Software-defined vehicle platforms are compressing development cycles.
Solid-state lidar is hybridizing with camera-radar fusion stacks to reduce per-unit sensor costs while maintaining safety-system redundancy. Tier 1 suppliers are shipping integrated perception modules to bus manufacturers in Germany and China. The technology is hybridizing procurement criteria toward subsystem-level certification rather than component-by-component validation.
NHTSA automated vehicle guidance is clarifying federal preemption pathways that override fragmented state-level operator requirements. The framework is accelerating product certification timelines for manufacturers targeting North American deployment. California and Arizona are responding with state-level testing permits that exceed federal minimums to attract pilot program investment.
Municipal procurement patterns are rotating toward availability-based service contracts that transfer operational risk to OEMs or mobility operators. Traditional capital purchase models are losing share to performance-guaranteed arrangements in French and Singaporean tenders. This shift is most visible in dense urban corridors where schedule reliability metrics dominate total cost of ownership calculations.
Autonomous Electric Bus Market Segmentation
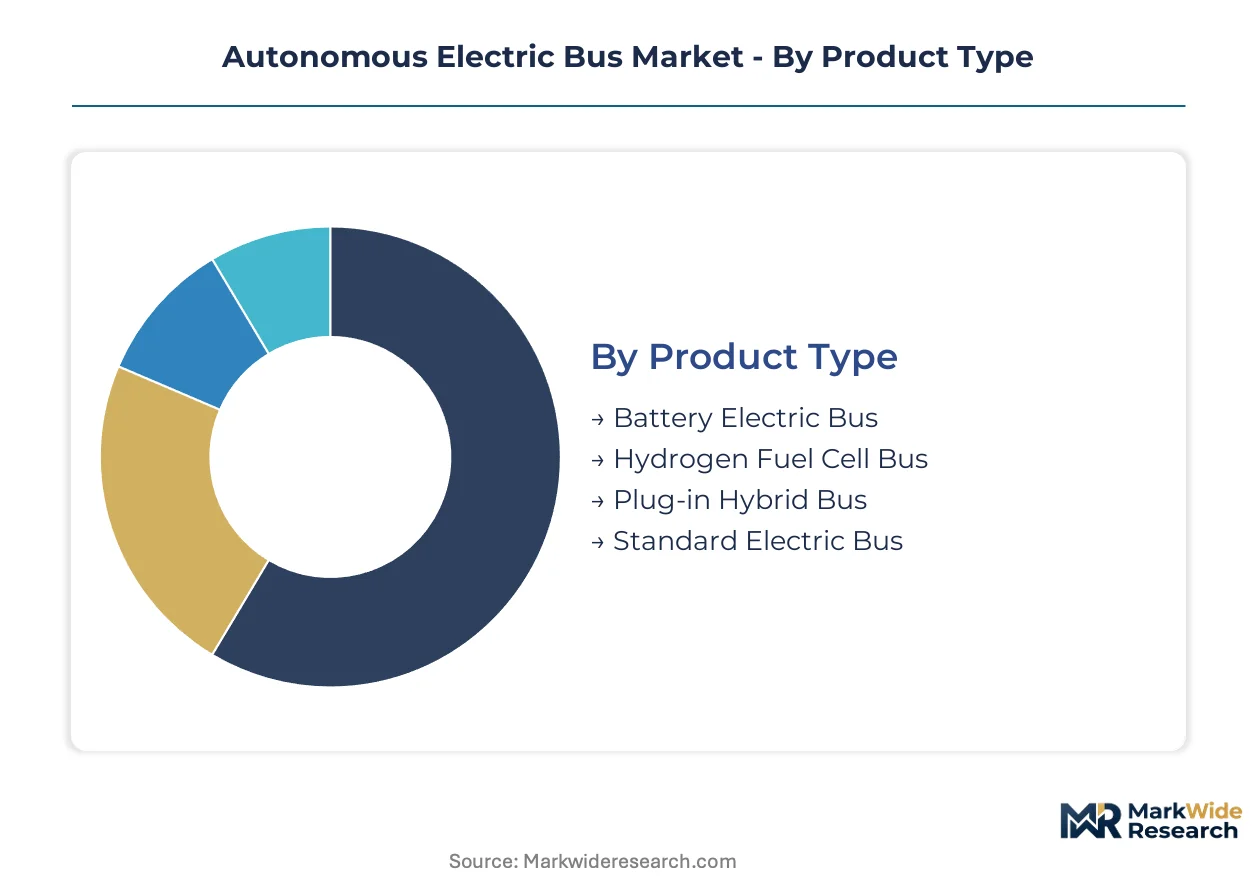
Segmentation in autonomous electric bus markets determines procurement specifications, certification pathways, and after-sales service intensity. Battery chemistry choices and automation tiers create divergent maintenance schedules, while application context dictates sensor redundancy requirements and operational design domain constraints.
Product Type:
After-sales service intensity varies sharply across powertrain architectures, with battery thermal management systems demanding scheduled technician visits that hydrogen fuel cell stacks do not require.
- Battery Electric Bus:Cell-to-pack architectures with liquid-cooled lithium-ion modules dominate current municipal procurement. German transit agencies under EU Green Deal mandates are concentrating demand for 300+ kWh configurations with depot charging infrastructure.
- Hydrogen Fuel Cell Bus:Proton exchange membrane stacks paired with modest battery buffers suit extended-range routes lacking grid capacity. Japanese and South Korean municipalities are piloting these for intercity corridors where charging downtime is operationally prohibitive.
- Plug-in Hybrid Bus:Range-extender configurations retain diesel or CNG generators for emergency fallback.
- Standard Electric Bus:Conventional lead-acid or early lithium-ion platforms without autonomous integration.
By volume, Battery Electric Bus leads. By growth pace, Hydrogen Fuel Cell Bus is ahead.
Application:
Route predictability shapes automation software deployment, with fixed-loop services enabling earlier cabin-empty certification than variable-destination operations.
- Public Transport:Scheduled fixed-route services with dedicated lanes achieve highest automation utilization rates. Singapore's Land Transport Authority is concentrating procurement for trunk-line corridors with signal priority integration.
- Shuttle Services:Closed-campus or airport perimeter loops with geofenced operational design domains reduce sensor complexity. Corporate campuses in California and Arizona are deploying these under state-level testing permits exceeding federal minimums.
- School Transportation:Stop-start patterns with child-safety protocols require enhanced pedestrian detection.
- Long-Distance Travel:Highway-speed automation with platooning capability remains pre-commercial.
Public Transport commands installed base. Shuttle Services are expanding most quickly.
Technology:
Embedded software value concentrates in perception stacks, where sensor fusion algorithms and V2X edge processing determine competitive differentiation.
- Level 4 Automation:Fixed-route operation without onboard drivers within defined operational design domains. EasyMile SAS and Navya are anchoring procurement decisions in France and Singapore with certified platforms.
- Sensor Fusion:Lidar-camera-radar integration with redundant perception pathways. Tier 1 suppliers in Germany are shipping pre-validated modules that compress OEM development cycles.
- Level 5 Automation:Unrestricted cabin-empty operation across all road conditions remains developmental.
- V2X Communication:DSRC and C-V2X protocols for intersection coordination and signal priority.
Level 4 Automation holds revenue concentration. V2X Communication is gaining share fastest.
End User:
Procurement authority structures determine contract duration and risk allocation, with municipal tenders favoring availability-based service models over capital purchase.
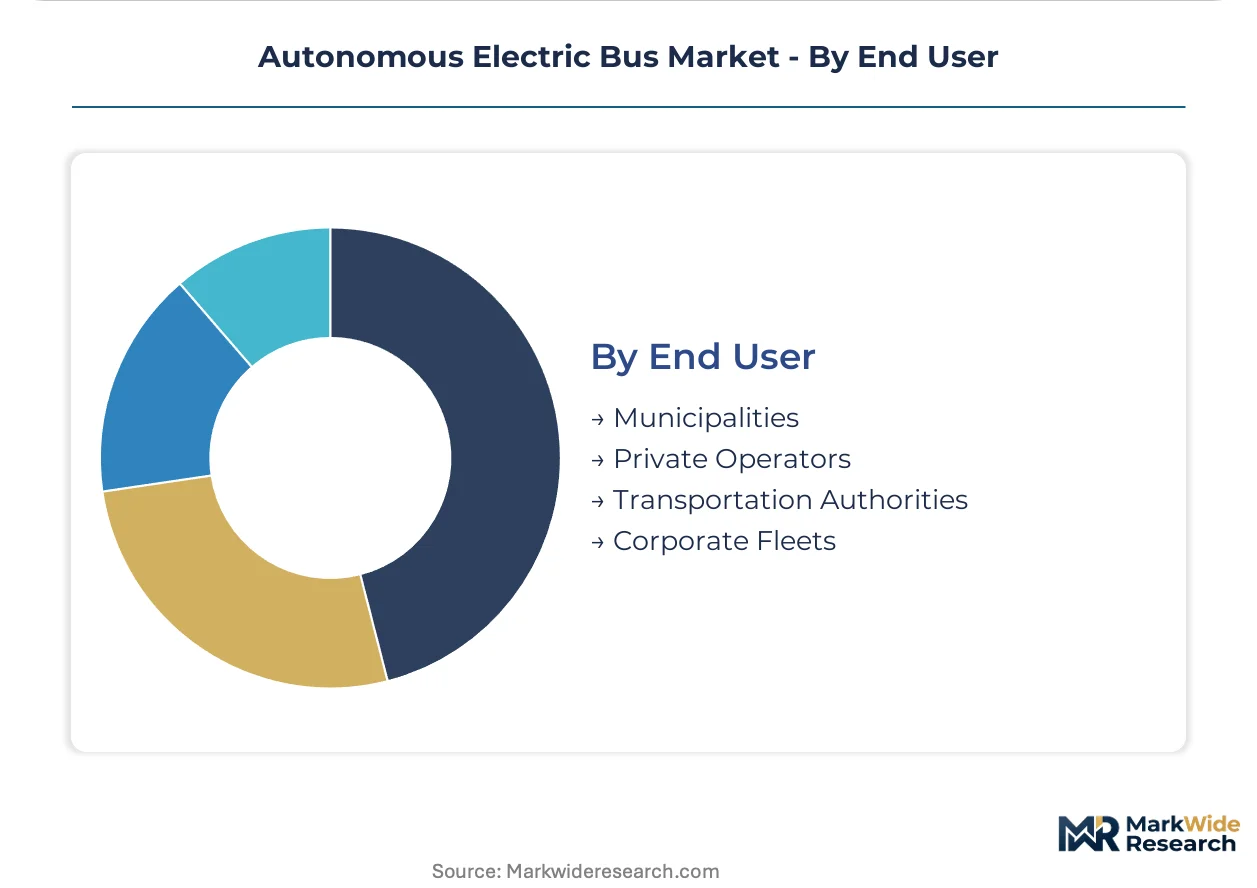
- Municipalities:City-owned transit agencies with EU Green Deal compliance obligations and EMA urban air quality directives. French and Italian municipalities are accelerating tender volumes for zero-emission autonomous platforms.
- Private Operators:Mobility-as-a-service providers accepting operational risk through performance-guaranteed contracts. These entities are displacing traditional capital purchase models in dense urban corridors.
- Transportation Authorities:Regional or state-level bodies coordinating multi-operator fleets.
- Corporate Fleets:Campus and employee shuttle services with dedicated infrastructure control.
Municipalities dominate tender volume. Private Operators are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chassis-electronics integration concentrates in Chinese manufacturing clusters, while European automation software development anchors procurement decisions for municipal transit agencies. German and French regulatory frameworks are compressing deployment timelines through binding emissions mandates.
Germany
Municipal transit agencies in Berlin and Hamburg are expanding pilot fleets to meet EU Green Deal emissions targets. KBA certification requirements for Level 4 automation systems are shaping product development cycles for domestic manufacturers. The Baden-Württemberg industrial corridor hosts steering and braking actuator manufacturing clusters that supply safety-system components across European tenders.
China
Domestic manufacturers are scaling battery-electric output for autonomous platforms through integrated chassis-electronics production. MIIT vehicle-type approval regulations govern automated driving system certification for commercial deployment. The Zhengzhou manufacturing base anchors Asia-Pacific supply chains through cell-to-pack battery architecture production.
France
EMA urban air quality directives are accelerating fleet replacement timelines across Paris and Lyon municipal networks. ANSM and CNIL oversight extends to data governance for connected vehicle platforms in automated transit systems. The Lyon-Grenoble corridor concentrates Level 4 automation software development from EasyMile SAS and Navya.
Singapore
The Land Transport Authority is concentrating procurement for trunk-line corridors with signal priority integration. National regulations on automated vehicle testing exceed federal minimums established in other jurisdictions to attract pilot program investment. The Jurong Innovation District hosts V2X communication infrastructure deployment for intersection coordination systems.
United States
Corporate campuses in California and Arizona are deploying shuttle services under state-level testing permits. NHTSA automated vehicle guidance is clarifying federal preemption pathways that override fragmented state-level operator requirements. The San Francisco Bay Area and Phoenix metropolitan clusters anchor closed-campus automation deployment with geofenced operational design domains.
Autonomous Electric Bus Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor and actuator supply. The vendor base organizes around three strategic archetypes: full-stack bus manufacturers with captive automation development, pure-play autonomy software providers licensing perception stacks, and Tier 1 subsystem suppliers shipping pre-validated modules. Consolidation pressure is concentrating around vertical integration into battery cell production and strategic partnerships for V2X infrastructure deployment.
Among Chinese full-stack manufacturers, Yutong Bus and BYD Co. Ltd. represent the integrated chassis-electronics archetype. AB Volvo occupies a position within European safety-system redundancy development. EasyMile SAS and Navya exemplify the pure-play automation software tier anchoring procurement in France and Singapore. These five entities collectively illustrate the geographic bifurcation between Asian manufacturing scale and European software certification leadership.
| Leading Market Players |
|---|
| Yutong Bus |
| BYD Co. Ltd. |
| AB Volvo |
| EasyMile SAS |
| Navya |
| Proterra |
| MAN Truck & Bus |
| NFI Group |
| Daimler AG |
| Others |
Pricing and Supply Chain Analysis
Steering and braking actuator manufacturing clusters in Germany and Japan concentrate safety-system supply for European and Asian procurement, anchoring margin pools in Tier 1 subsystem suppliers rather than bus OEMs or municipal operators. This upstream concentration forces downstream pricing negotiations around availability-based service contracts that transfer operational risk.
Pricing Analysis
EU Green Deal mandates dictate the pricing tier structure across municipal tenders, with EMA urban air quality directives compressing fleet replacement timelines and intensifying price competition for zero-emission autonomous platforms. Pricing stratifies across premium certified-automation, standard sensor-fusion, and economy pilot-program tiers, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in standard-tier configurations is intensifying because solid-state lidar arrays remain the dominant hardware expense. Municipal transit agencies exhibit highest price sensitivity, while private mobility operators under performance-guaranteed contracts demonstrate lowest sensitivity due to risk-transfer structures.
Supply Chain Analysis
Extended payment terms from Tier 1 subsystem suppliers to German and Japanese actuator manufacturers are compressing working capital cycles across the safety-system tier. Geographic supply concentrates in China for cell-to-pack battery architectures, Germany for steering and braking actuators, and Singapore for V2X communication infrastructure. Raw material dependencies draw from lithium carbonate for solid-state batteries, rare earth elements for electric motors, and silicon carbide for power electronics. Single-source vulnerability in German and Japanese actuator manufacturing creates structural supply chain risk. Distribution runs through municipal tender processes and availability-based service contracts with private operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous electric bus markets are approaching a platform-economics inflection where V2X communication interoperability determines ecosystem control. Software-defined vehicle architectures are displacing component-by-component procurement criteria.
For Market Incumbents: Insulate automation software margins through captive perception-stack development and ISO 26262 ASIL-D certification investment ahead of functional safety timeline compression. Secure redundant actuator supply agreements with Baden-Württemberg and Japanese manufacturing clusters to mitigate single-source vulnerability from emerging Tier 1 competitors. For New Entrants and Emerging Players: Shuttle services in Arizona and California corporate campuses represent the most penetrable entry point given state-level testing permits exceeding federal minimums and geofenced operational design domains reducing sensor complexity. India's PLI scheme for advanced chemistry cells offers localized battery supply for Asia-Pacific assembly partnerships as a go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play automation software providers licensing perception stacks to bus manufacturers. Long-term viability hinges on convergence of V2X and edge computing capabilities across the analysis window. Monitor municipal procurement rotation toward availability-based service contracts as the inflection signal for platform-economics value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell-to-pack architectures from BYD and Yutong anchor cost positions in long-range configurations. |
| Software-Defined Vehicle Investment | EasyMile SAS and Navya compress development cycles through integrated chassis-electronics platforms. |
| V2X Infrastructure Partnership | Singapore's Land Transport Authority prioritizes intersection coordination ahead of cabin-empty operation. |
| Geographic Manufacturing Footprint | Zhengzhou and Baden-Württemberg clusters concentrate safety-system and battery supply for regional tenders. |
| Platform Standardization | Subsystem-level certification from Tier 1 suppliers displaces component-by-component validation in German procurement. |
Research Methodology
A spread of perspectives from municipal transit procurement officers, Tier 1 subsystem supplier executives, automation software engineering leads, and V2X infrastructure planners converged on the working assumptions. Primary interviews combined with secondary validation from MIIT vehicle-type approval regulations, KBA certification documentation, NHTSA automated vehicle guidance filings, and EU Green Deal mandate tracking. Customs data on lithium-ion battery trade flows and municipal tender databases provided volume anchors. Bottom-up fleet deployment projections triangulated against top-down emissions target compliance modeling.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include powertrain architecture, automation tier, application context, and regional regulatory cluster. CAGRs derived from logistic adoption curves for Level 4 automation software penetration and linear replacement schedules for EU Green Deal fleet turnover. Industry-specific forecast inputs incorporated solid-state battery chemistry maturation timelines and V2X communication infrastructure deployment rates.
Practitioners should monitor NHTSA federal preemption pathway clarifications and EMA urban air quality directive enforcement intensity for early signals. Forecasts reflect assumptions on automation software certification timelines and battery cost trajectories. Macroeconomic deviation in municipal transit budgets, regulatory restriction on lidar sensor deployment, or technological breakthrough in Level 5 automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Autonomous Navigation Sensing System Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Fully Autonomous Driving Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Connected Vehicle Technology Market