
 Spain Autonomous Navigation Market | 2026-2036
Spain Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Autonomous Navigation Market Insights
Spain's Basque Country is reshaping autonomous navigation manufacturing through its established maritime and aerospace supplier ecosystem. Thales Group leverages its Seville-based defense electronics footprint to anchor military autonomous systems development. Safran sustains R&D intensity in inertial navigation units from its Spanish engineering centers. BAE Systems competes through its Madrid operations focused on naval platform autonomy.
Autonomous navigation encompasses self-directed positioning and path-planning systems that fuse multi-sensor inputs—LiDAR point clouds, GNSS corrections, and inertial measurement unit drift compensation—to achieve sub-meter accuracy without human intervention. These systems enable vessels, vehicles, and aerial platforms to execute missions in GPS-denied or communications-constrained environments where manual control proves impractical. Vision-based systems lead commercial adoption in Spanish logistics hubs due to lower hardware costs and faster calibration cycles, while LiDAR dominates marine applications where centimeter-level berth precision prevents collision damage. Edge computing deployment is expanding fastest among industrial robots in Catalonia's automotive plants, though cloud-based architectures still capture the largest margin pools through recurring software licensing.
Spain's national cybersecurity regulator and the Spanish Maritime Safety Agency enforce autonomous system certification under EU MDR and the F-Gas Regulation for sensor cooling gases. The Directorate General of Traffic coordinates with EASA frameworks to define liability boundaries for self-driving car trials on public roads. Stakeholders must monitor how Madrid transposes the EU AI Act's risk-classification rules into national enforcement protocols affecting navigation algorithm approvals.
Market Dynamics
EU Green Deal corridor mandates are forcing Spanish logistics operators to retrofit fleets with autonomous positioning systems ahead of 2030 decarbonization deadlines, compressing technology procurement cycles across Catalonia and Valencia.
Growth Catalysts
- EU AI Act Risk Classification:Madrid's transposition of algorithmic approval protocols creates regulatory clarity for navigation software vendors seeking national certification.
- Port Automation Mandates:Barcelona and Valencia terminal operators face berth congestion penalties that accelerate autonomous vessel docking system procurement.
- Andalusia Defense Cluster:Spanish Ministry of Defence procurement concentrates R&D investment around Seville aerospace suppliers developing military-grade autonomous platforms.
Market Restraints
- LiDAR Sensor Cost Volatility:Rare earth element supply concentration in Chinese processing facilities inflates hardware input costs for Spanish marine autonomy integrators.
- F-Gas Regulation Compliance:EU cooling gas restrictions for sensor thermal management add certification friction and extend product development timelines.
- GNSS Signal Vulnerability:Jamming incidents in Mediterranean shipping lanes expose technical limitations of satellite-dependent navigation architectures.
Strategic Opportunities
- Basque Maritime Supplier Ecosystem:Bilbao and San Sebastián engineering centers offer underpenetrated manufacturing partnerships for sensor fusion module production.
- Smart Logistics Corridors:Madrid-Valencia freight automation incentives under EU Green Deal implementation create regulatory tailwinds for truck platooning pilots.
- Edge-Cloud Convergence:Hybrid computing architectures combining Catalonia automotive plant edge deployments with cloud-based fleet analytics open new service revenue streams.
Industry Challenges
- Sensor Fusion Engineering Talent:Spanish universities produce insufficient specialists in LiDAR-GNSS-IMU integration, forcing Basque Country firms to recruit from French aerospace programs.
- MDR Certification Timelines:EU Medical Device Regulation parallel requirements for autonomous surgical navigation systems create bottlenecks at notified bodies.
- Legacy Fleet Retrofit Complexity:Madrid trucking operators face integration friction when grafting autonomous positioning onto diesel platforms nearing end-of-life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Autonomous Navigation Market |
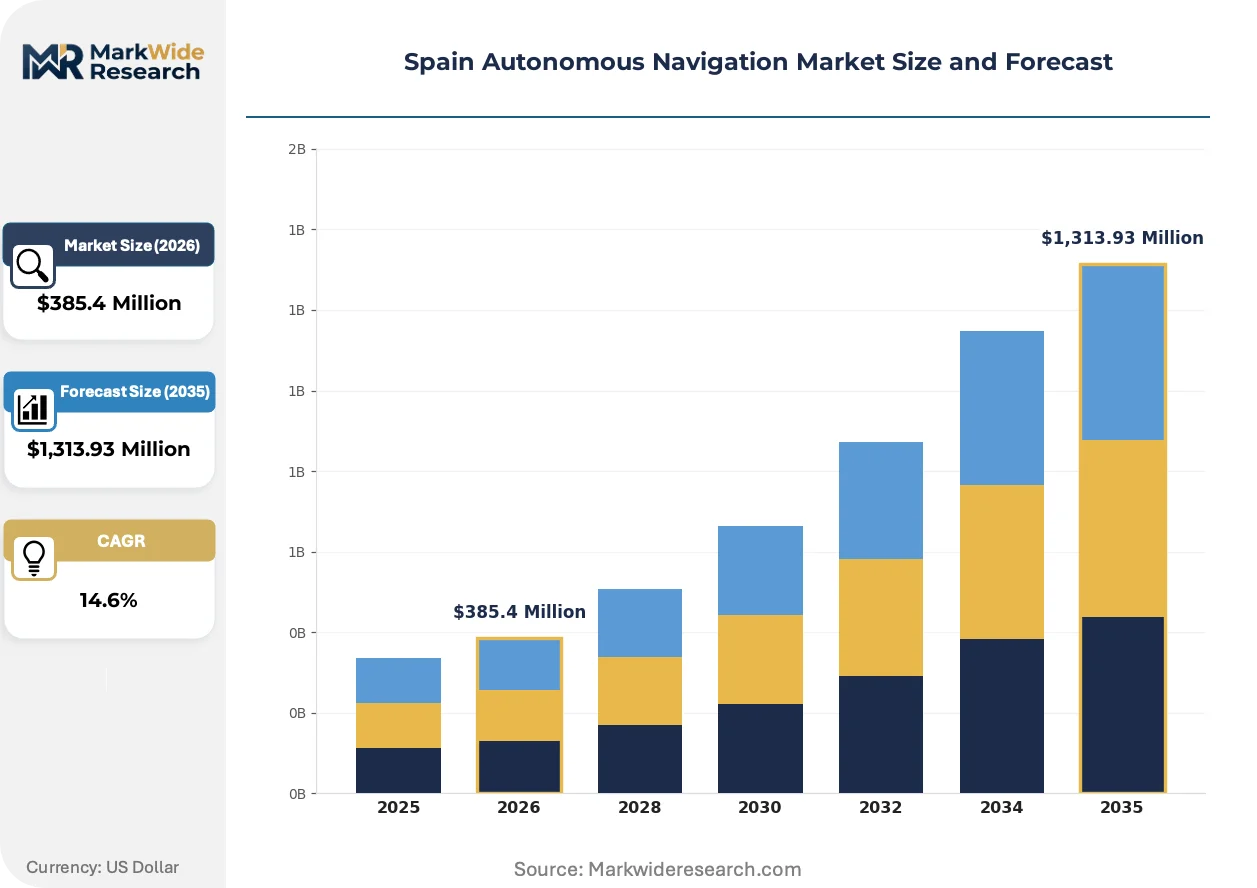
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,313.93 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, GPS, Vision-Based Systems, Inertial Navigation Application: Self-Driving Cars, Drones, Marine Vessels, Industrial Robots End User: Logistics, Defense, Agriculture, Transportation Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Thales Group, Safran, ABB, BAE Systems, Elbit Systems, Lockheed Martin, Northrop Grumman, L3Harris Technologies, Honeywell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Autonomous Navigation Market Trends and Innovations
Vision-based positioning architectures are compressing hardware cost structures in Spanish logistics while maritime applications demand sensor redundancy that elevates system integration complexity.
Solid-state LiDAR arrays with MEMS beam steering are rendering obsolete mechanically scanned units in Valencia port automation projects. Terminal operators at MSC and APM Terminals facilities adopt solid-state platforms for centimeter-level berth precision. The shift collapses maintenance schedules and eliminates rotating component failure modes that plagued earlier marine deployments.
EU F-Gas Regulation phase-down schedules are accelerating thermal management redesigns for Spanish sensor manufacturers. Cooling system constraints force engineering teams toward thermoelectric alternatives or passive architectures. Marine navigation hardware faces the steepest compliance burden due to sealed housing requirements that trap operational heat.
Spanish fleet operators now unbundle autonomous navigation software licenses from hardware procurement, shifting toward subscription-based fleet analytics. Logistics providers in Catalonia's automotive supply chain lead this transition, replacing capital-intensive sensor purchases with per-kilometer positioning service fees. The model spreads fastest among mid-sized carriers lacking internal calibration expertise.
Spain Autonomous Navigation Market Segmentation
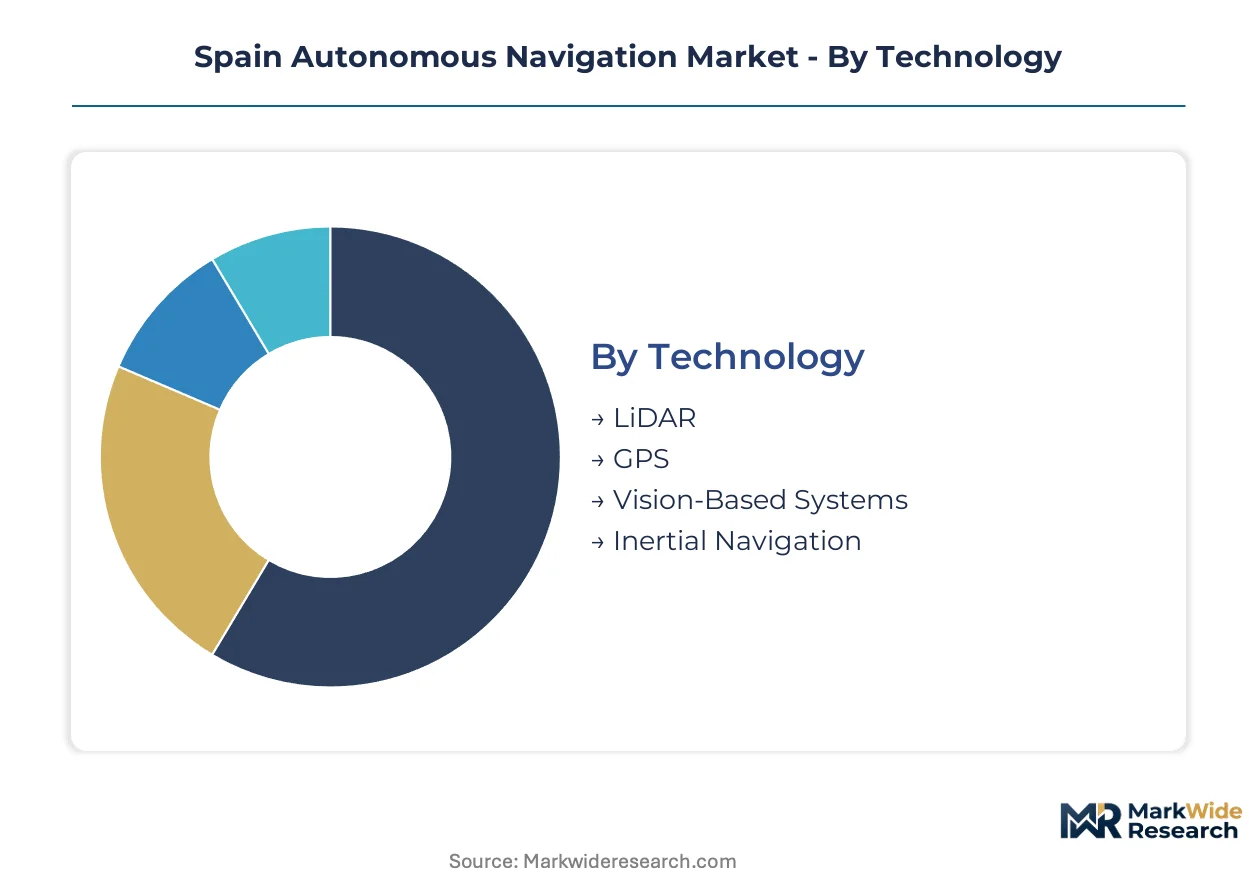
Segmentation in Spain's autonomous navigation market reveals how procurement cycles, certification requirements, and infrastructure readiness vary sharply across technology types and deployment modes. Understanding these fault lines helps vendors align R&D investment with actual revenue velocity rather than headline growth.
Technology:
Cycle times diverge dramatically: vision-based systems refresh every 18-24 months with software updates, while marine LiDAR installations persist for 7-10 years given salt corrosion and sealed-housing replacement costs.
- LiDAR:Solid-state arrays with MEMS beam steering deliver centimeter-level berth precision for Valencia and Barcelona port operators. Marine applications dominate Spanish procurement volumes despite hardware costs running 3-4x above vision alternatives, driven by collision liability exposure in congested Mediterranean shipping lanes.
- Vision-Based Systems:Camera arrays fused with neural network processing enable sub-meter positioning for Catalonia logistics hubs at hardware cost points accessible to mid-sized fleet operators. Calibration cycles measured in days rather than weeks accelerate pilot-to-production transitions for Madrid-Valencia corridor operators.
- GPS:Multi-constellation receivers with RTK correction dominate outdoor robotics in Spanish agriculture, though jamming vulnerabilities in Mediterranean corridors push integrators toward hybrid architectures.
- Inertial Navigation:MEMS-based IMU clusters from Basque Country engineering centers provide dead-reckoning backup for GPS-denied environments, with defense procurement sustaining premium pricing tiers.
LiDAR dominates installed base in Spanish marine autonomy. Vision-based systems are where expansion concentrates fastest among logistics providers.
Application:
Margin structures invert across applications: industrial robots command recurring software licensing premiums, while self-driving car pilots absorb R&D costs without near-term revenue.
- Industrial Robots:Edge-deployed navigation stacks in Catalonia automotive plants achieve 99.97% uptime through sensor fusion architectures. Automotive OEMs in Martorell and Zona Franca drive standardization around proprietary middleware, locking in multi-year service contracts.
- Marine Vessels:Autonomous docking systems at MSC and APM Terminals facilities in Valencia reduce berth turnaround times by eliminating tugboat dependency. Spanish Maritime Safety Agency certification requirements extend sales cycles but protect incumbent integrators from price competition.
- Self-Driving Cars:Madrid metropolitan trials under Directorate General of Traffic permits generate data assets without commercial deployment, with liability frameworks unresolved under EU AI Act transposition.
- Drones:Precision agriculture mapping in Andalusia citrus groves and Ebro Valley vineyards drives demand for lightweight GNSS-vision fusion, though flight altitude restrictions limit addressable use cases.
Industrial robots generate the highest margin per unit deployed. Marine vessels absorb the largest absolute R&D investment.
End User:
Procurement sophistication separates end users: defense buyers specify MIL-STD compliance upfront, while agricultural operators prioritize payback periods under 36 months.
- Logistics:Catalonia automotive supply chain operators and Madrid-Valencia freight corridors lead unbundling of software licenses from hardware, shifting toward per-kilometer positioning subscriptions.
- Defense:Spanish Ministry of Defence procurement through Seville aerospace cluster concentrates demand for military-grade inertial navigation and encrypted data links, with Andalusia suppliers capturing integration value.
- Agriculture:Cooperatives in Valencia citrus regions and La Rioja vineyards adopt drone-based autonomy for variable-rate input application, constrained by seasonal utilization rates.
- Transportation:Urban mobility pilots in Barcelona and Madrid remain pre-revenue, with public operator risk aversion delaying scaled procurement.
Defense commands premium pricing tiers. Logistics is climbing the fastest toward volume deployment.
Deployment:
Architecture choices lock in cost structures: edge deployments eliminate latency for safety-critical loops, while cloud platforms enable fleet-wide model retraining.
- Edge Computing:Local sensor fusion processing in Catalonia automotive plants meets 10-millisecond control loop requirements without connectivity dependency. Hardware costs concentrate at the point of use, avoiding recurring bandwidth charges.
- Cloud-Based:Centralized fleet analytics for Spanish logistics operators enable predictive maintenance across distributed vehicle pools, though GDPR data residency requirements add hosting complexity.
- Hybrid:Split architectures processing time-critical navigation at the edge and strategic optimization in cloud environments dominate marine vessel retrofits, balancing latency against computational scope.
- On-Premises:Air-gapped deployments persist in defense applications around Seville and Madrid, with security clearance requirements limiting vendor pools.
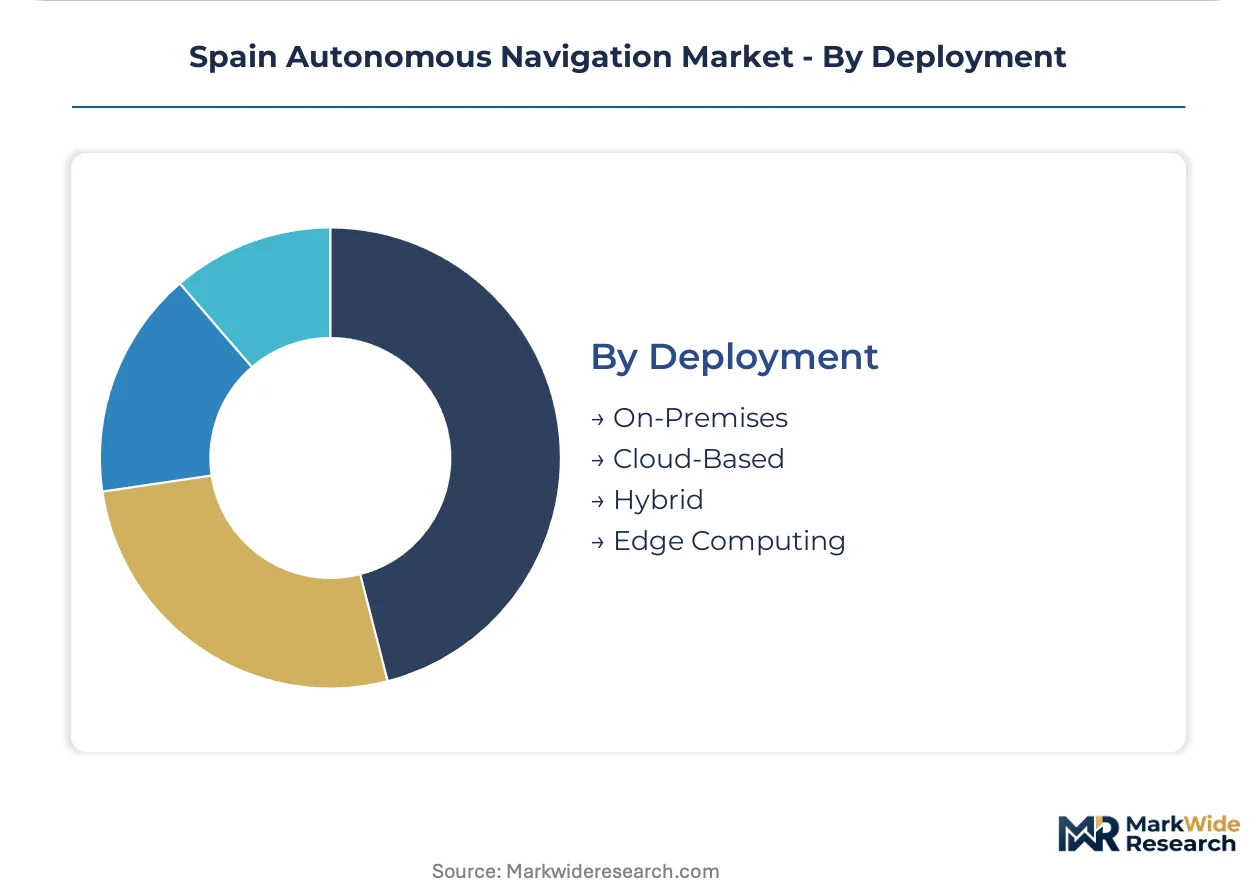
Cloud-based architectures capture the largest recurring revenue streams. Edge computing is expanding most quickly among new industrial installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish autonomous navigation demand concentrates in port automation and defense procurement, diverging from Northern European patterns where automotive pilots dominate investment flows.
Madrid
The capital region absorbs the largest share of smart logistics corridor investment under EU Green Deal implementation. The Directorate General of Traffic coordinates with EASA frameworks to define liability boundaries for self-driving freight trials on the Madrid-Valencia axis. Engineering consultancies cluster in the capital to service national infrastructure digitization mandates.
Catalonia
Barcelona port operators face berth congestion penalties that accelerate autonomous vessel docking procurement. The Spanish Maritime Safety Agency enforces certification requirements that protect incumbent integrators from price competition. Automotive OEMs in Martorell and Zona Franca drive standardization around proprietary middleware for industrial robot navigation.
Basque Country
Bilbao and San Sebastián engineering centers supply sensor fusion modules for marine and aerospace applications. The region's maritime supplier ecosystem offers underpenetrated manufacturing partnerships for LiDAR-GNSS-IMU integration. Basque firms recruit sensor fusion specialists from French aerospace programs to fill talent gaps.
Andalusia
The Seville aerospace cluster concentrates Spanish Ministry of Defence procurement for military-grade autonomous platforms. Thales Group leverages its defense electronics footprint to anchor military systems development. Encrypted data link requirements sustain premium pricing tiers for regional suppliers.
Valencia
Valencia terminal operators at MSC and APM Terminals facilities reduce berth turnaround times through autonomous docking systems. The port authority's automation mandates compress technology procurement cycles ahead of 2030 decarbonization deadlines. Citrus cooperatives in surrounding regions adopt drone-based autonomy for variable-rate input application.
Spain Autonomous Navigation Market Competitive Landscape
Capability concentration sits with defense-electronics specialists; scale advantage sits with diversified industrial conglomerates. The market structure tiers between premium military-grade integrators and commercial marine automation vendors. Three archetypes dominate: European defense primes with established Spanish subsidiaries, sensor-technology specialists with Basque engineering presence, and port-automation integrators serving Mediterranean terminal operators. Competitive moves center on strategic partnerships with Spanish port authorities and backward integration into sensor manufacturing.
Within the defense-prime tier, Thales Group and BAE Systems exemplify capability concentration through their Spanish operational footprints. Thales anchors military autonomous systems development from its Seville-based defense electronics position. BAE Systems occupies a comparable position through Madrid operations focused on naval platform autonomy. Safran represents the sensor-technology specialist archetype, sustaining R&D intensity in inertial navigation units from Spanish engineering centers. These three companies collectively illustrate how European defense procurement patterns shape competitive positioning in Spanish autonomous navigation.
| Leading Market Players |
|---|
| Thales Group |
| Safran |
| ABB |
| BAE Systems |
| Elbit Systems |
| Lockheed Martin |
| Northrop Grumman |
| L3Harris Technologies |
| Honeywell |
| Others |
Pricing and Supply Chain Analysis
Basque Country engineering centers in Bilbao and San Sebastián anchor sensor fusion module production capacity, translating concentrated manufacturing expertise into pricing leverage for LiDAR-GNSS-IMU integrators serving Spanish marine autonomy buyers.
Pricing Analysis
Long-term offtake contracts dominate procurement between Valencia port operators and marine autonomy integrators, insulating vendors from spot-market volatility in rare earth element pricing. Three-tier pricing structure across military-grade, commercial marine, and logistics vision systems separates defense buyers paying MIL-STD compliance premiums from Catalonia fleet operators selecting per-kilometer subscription models. Cost compression in commercial vision systems is intensifying because camera sensor commoditization outpaces software differentiation. Agricultural cooperatives in La Rioja and Valencia citrus regions exhibit highest price sensitivity, while Spanish Ministry of Defence procurement sustains premium tiers.
Supply Chain Analysis
Tariff exposure between Chinese rare earth processing facilities and Spanish LiDAR manufacturers dominates supply chain risk planning for marine navigation hardware. Component sourcing draws from Chinese magnet and laser diode suppliers, German precision optics manufacturers, and French IMU engineering centers. Single-source vulnerability concentrates in solid-state LiDAR MEMS beam steering chips. Distribution runs through Bilbao maritime engineering clusters and Seville aerospace integrators before terminal deployment at MSC and APM Terminals facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
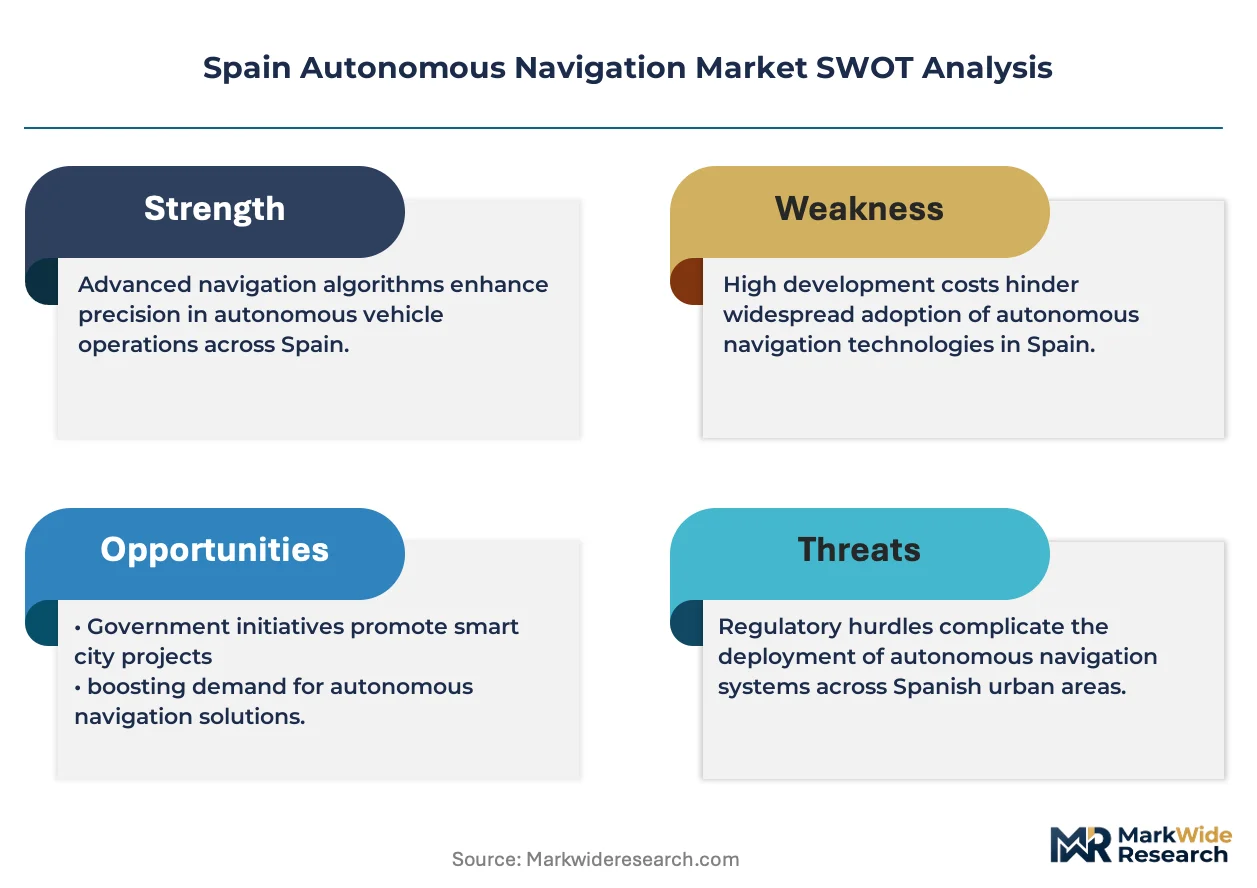
Spain's autonomous navigation market rewards defensive positioning through regulatory entrenchment, where Spanish Maritime Safety Agency certification timelines create switching costs that protect incumbent marine integrators from price competition.
For Market Incumbents: Entrench market position by deepening backward integration into solid-state LiDAR sensor manufacturing at Basque Country engineering centers, reducing exposure to Chinese rare earth price volatility. Pursue EU AI Act algorithmic approval protocols ahead of Madrid's transposition deadlines to lock in regulatory moats against emerging software-centric entrants. Priority lever rests on certification investment rather than capacity expansion. For New Entrants and Emerging Players: Andalusia precision agriculture drone autonomy offers underpenetrated white space, with citrus cooperative demand for variable-rate input application outpacing specialized vendor supply. Target Madrid-Valencia freight corridor truck platooning pilots where EU Green Deal incentives compress procurement cycles for mid-sized carriers lacking internal sensor fusion expertise. Go-to-market angle should emphasize per-kilometer subscription pricing to bypass capital-constrained buyer budgets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-technology specialists with captive IMU engineering capabilities over pure-play software vendors. Long-term viability across the projection horizon hinges on hybrid edge-cloud architecture control. Acquisition target archetype includes Basque Country firms with French aerospace recruitment pipelines and Spanish Maritime Safety Agency certification track records. Signal to watch is EU F-Gas Regulation thermal management redesign completion rates among marine hardware vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solid-State LiDAR | Reduces rare earth exposure for Valencia port automation integrators. |
| EU AI Act Certification Pre-Positioning | Locks algorithmic approval ahead of Madrid enforcement protocol finalization. |
| Per-Kilometer Subscription Model Launch | Captures Catalonia mid-sized fleet operators lacking calibration expertise. |
| Basque Country Manufacturing Partnership | Accesses Bilbao sensor fusion talent pools for marine autonomy production. |
| Hybrid Edge-Cloud Architecture Development | Balances latency requirements against fleet analytics revenue streams. |
Research Methodology
Initial hypotheses were tested against primary input from port operations directors, autonomous systems integration engineers, Spanish Maritime Safety Agency certification officers, and defense procurement specialists at the Seville aerospace cluster, then refined through secondary validation against EU MDR filings, F-Gas Regulation compliance databases, Spanish Directorate General of Traffic trial permits, and EASA framework documentation. Bottom-up segment sizing across technology types and deployment modes was triangulated with top-down macroeconomic indicators.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions spanning sensor technology, application vertical, end-user procurement sophistication, and deployment architecture. CAGRs were derived from installed base growth rates and replacement cycle compression in marine versus logistics applications. Forecast inputs incorporated EU Green Deal corridor mandate timelines and Spanish Ministry of Defence R&D concentration patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese LiDAR manufacturers or accelerated EU AI Act enforcement would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Norway Autonomous Navigation Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Asia-Pacific Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market