
 Shipping Supplies Market | 2026-2036
Shipping Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Shipping Supplies Market Analytics
Skilled machine operator availability for automated corrugated converting lines is collapsing across Midwestern US manufacturing hubs, forcing accelerated capital deployment. International Paper leverages its integrated pulp-to-box infrastructure to sustain delivery reliability amid labor shortfalls. Smurfit Kappa anchors European supply through its recycled fiber network. Sealed Air Corporation differentiates via proprietary inflatable barrier systems for fragile freight.
Shipping supplies encompass protective and containment materials engineered to unitize, cushion, and seal goods during transit, with corrugated board typically specified by Edge Crush Test ratings between 23 ECT and 55 ECT for load-bearing performance. These products serve to prevent damage, enable handling efficiency, and support inventory traceability across multimodal distribution networks. Cardboard-based solutions dominate volume due to cost efficiency and established recycling streams, while plastic films capture premium margin pools in moisture-sensitive pharmaceutical and electronics lanes. The E-commerce end user segment commands the fastest expansion as direct-to-consumer order profiles multiply SKU complexity and drive demand for customized size configurations.
US EPA guidelines on recycled content thresholds and OSHA warehouse safety standards shape material selection and ergonomic design requirements for domestic suppliers. The EU F-Gas Regulation and REACH chemical restrictions constrain foam expansion agent formulations entering European channels. Stakeholders must monitor evolving extended producer responsibility frameworks as jurisdictions shift compliance burdens upstream to manufacturers and distributors.
Market Dynamics
Corrugated fiberboard specifications are tightening across distribution networks as automated sortation systems impose stricter dimensional tolerances on parcel geometry, forcing converters to retool cutting and scoring lines for precision that legacy equipment cannot achieve.
Growth Catalysts
- E-commerce fulfillment density:Direct-to-consumer order profiles are multiplying SKU complexity and driving demand for customized box configurations that minimize dimensional weight charges.
- REACH chemical restrictions:The EU regulation is accelerating substitution of petroleum-based foam cushioning with molded fiber alternatives in electronics and pharmaceutical lanes.
- Recycled fiber network expansion:Investment in de-inking and repulping infrastructure across Germany's industrial logistics corridor is reducing virgin pulp dependency for containerboard production.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with municipal collection program disruptions and export demand from Asian packaging mills.
- Midwestern US labor collapse:Skilled operator availability for automated converting lines has contracted sharply, capping effective capacity at existing facilities.
- Plastic film substitution threat:Stretch wrap and shrink film retain cost advantages in moisture-sensitive bulk freight applications where fiber-based alternatives fail.
Strategic Opportunities
- Right-size packaging automation:On-demand box-making systems integrated into fulfillment workflows eliminate void fill requirements and reduce freight cube.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are creating compliance service revenue streams for suppliers with certified circularity tracking.
- Inflatable barrier convergence:Integration of air cushion systems with robotic pick-and-place equipment is opening pharmaceutical cold chain applications.
Industry Challenges
- Automated line commissioning delays:Converting equipment with precision servo controls requires 18-24 month installation cycles that mismatch e-commerce demand ramps.
- Multi-material recyclability certification:Mixed-fiber plastic hybrid packaging faces fragmented acceptance criteria across municipal recovery facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipping Supplies Market |
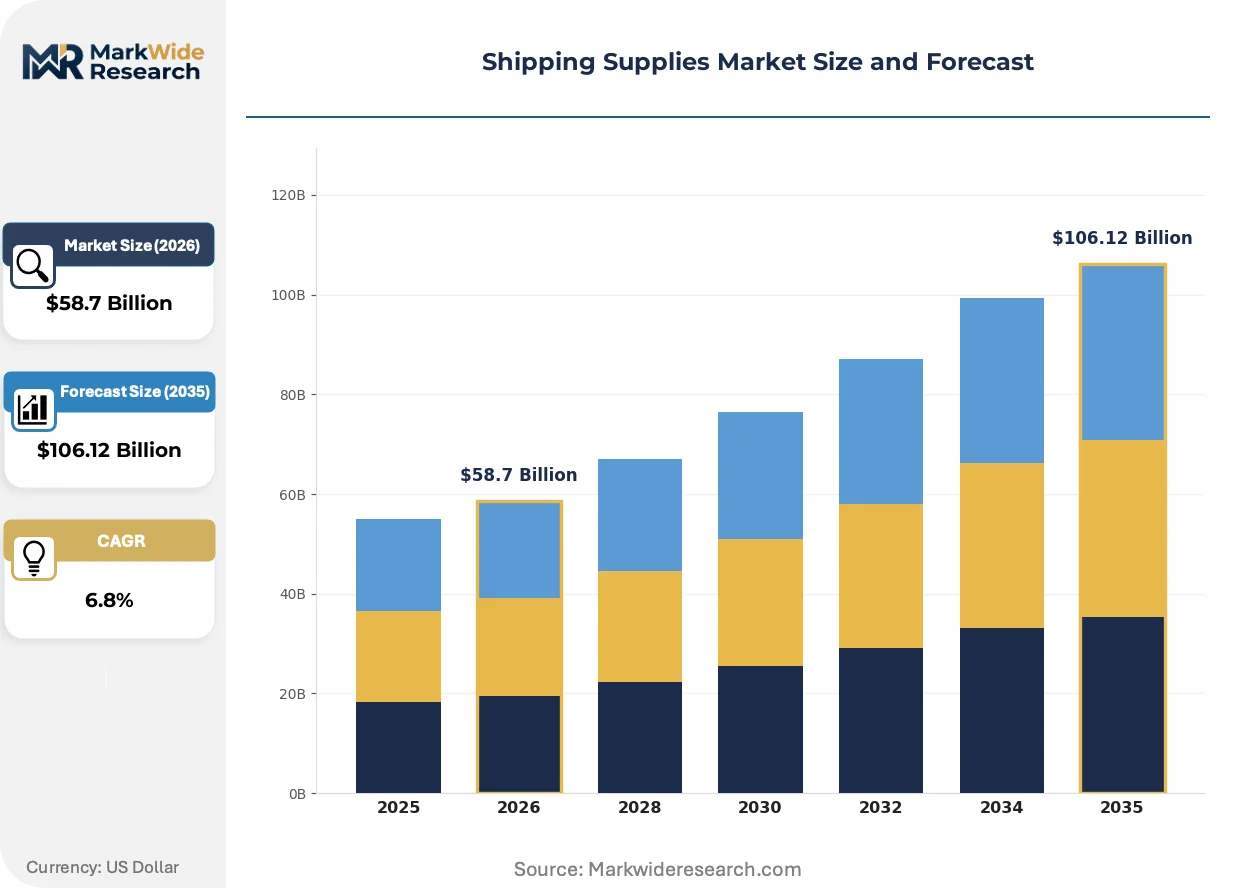
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Envelopes, Bubble Wrap, Tape Material: Cardboard, Plastic, Paper, Foam End User: E-commerce, Retail, Manufacturing, Logistics Size: Small, Medium, Large, Customized |
| Companies Covered | International Paper, WestRock, Smurfit Kappa, DS Smith, Mondi, Sealed Air Corporation, Pregis, Uline, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipping Supplies Market Evolving Landscape
Active transformation in protective packaging centers on dimensional optimization, regulatory chemistry substitution, and fulfillment velocity compression. These shifts are reconfiguring converter capital allocation and buyer procurement criteria simultaneously.
Lightweight honeycomb board construction is miniaturizing protective packaging profiles while maintaining Edge Crush Test performance. Third-party logistics providers serving consumer electronics are specifying 32 ECT-rated honeycomb substitutes for traditional 44 ECT corrugated to reduce freight tonnage. The technology is miniaturizing warehouse storage cube requirements and enabling denser trailer loading without damage rate erosion.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of polyurethane foam expansion agents used in molded cushioning. European appliance manufacturers are qualifying water-blown alternatives that sacrifice minimal compression set performance. German white goods exporters face the steepest compliance timelines as their national chemical regulator enforces transitional quotas most aggressively.
Shippers are consolidating supplier relationships around integrated packaging-plus-fulfillment service contracts that bundle design, production, and inventory management. Mid-market e-commerce retailers are displacing spot purchasing of commodity boxes with multi-year agreements that guarantee capacity allocation. This pattern concentrates most visibly in the Ohio River Valley logistics cluster where warehouse construction has outpaced local converter capacity.
Shipping Supplies Market Segmentation
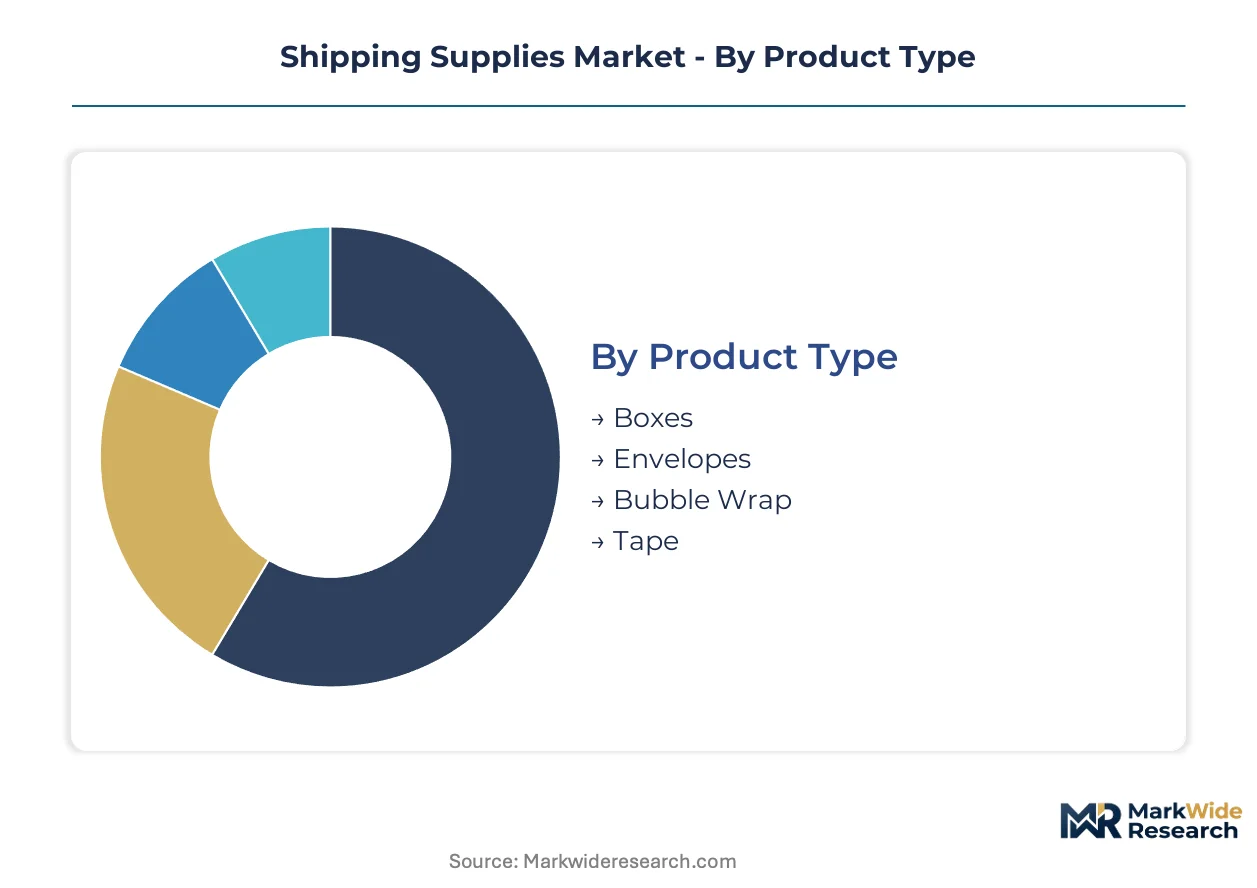
Shipping supplies segmentation reveals how procurement criteria diverge across fulfillment velocity, damage tolerance, and regulatory exposure. Understanding these fracture lines enables suppliers to align capacity investments with buyer decision hierarchies.
Product Type:
REACH chemical restrictions and dimensional weight pricing are fragmenting product specifications across EU and US channels.
- Boxes:Corrugated fiberboard dominates volume, with Edge Crush Test ratings from 23 ECT to 55 ECT specifying load-bearing performance for automated sortation systems. E-commerce fulfillment centers in Germany's industrial logistics corridor are driving demand for customized configurations that minimize dimensional weight charges.
- Envelopes:Padded and rigid mailers capture premium lanes in document and small electronics shipping, with polyethylene bubble-lined variants facing substitution pressure from molded fiber alternatives under EU Packaging and Packaging Waste Regulation mandates.
- Bubble Wrap:Air retention films protect fragile freight, though inflatable barrier systems are displacing traditional rolls in high-velocity operations.
- Tape:Pressure-sensitive adhesives seal containment integrity, with hot-melt and acrylic formulations selected based on temperature exposure and substrate compatibility.
Established volume favors boxes; emerging adoption favors inflatable barrier substitutes.
Material:
Cost tier stratification separates commodity feedstocks from performance-engineered alternatives.
- Cardboard:Recycled containerboard commands the largest share, with Old Corrugated Container feedstock costs swinging on municipal collection disruptions and Asian mill export demand.
- Plastic:Stretch wrap and shrink film retain cost advantages in moisture-sensitive bulk freight where fiber-based alternatives fail, though ECHA restrictions constrain expansion agent chemistries.
- Paper:Kraft wrapping and void fill serve protective functions with established recycling streams, qualifying for EPA recycled content thresholds in US government procurement.
- Foam:Polyurethane and polystyrene cushioning face accelerated substitution as REACH Annex XVII limits persistent organic pollutants in expansion agents.
Cardboard anchors procurement volume; foam substitution is climbing the fastest.
End User:
Application intensity determines performance specifications and contract structures.
- E-commerce:Direct-to-consumer order profiles multiply SKU complexity and drive demand for right-size packaging automation integrated into fulfillment workflows.
- Retail:Store replenishment and ship-from-store operations require standardized box configurations compatible with existing material handling systems.
- Manufacturing:Industrial shippers specify protective packaging for outbound finished goods, with appliance manufacturers qualifying water-blown foam alternatives under aggressive German chemical regulator timelines.
- Logistics:Third-party providers consolidate supplier relationships around integrated packaging-plus-fulfillment service contracts bundling design, production, and inventory management.
E-commerce is gaining share fastest; manufacturing maintains the strictest specification requirements.
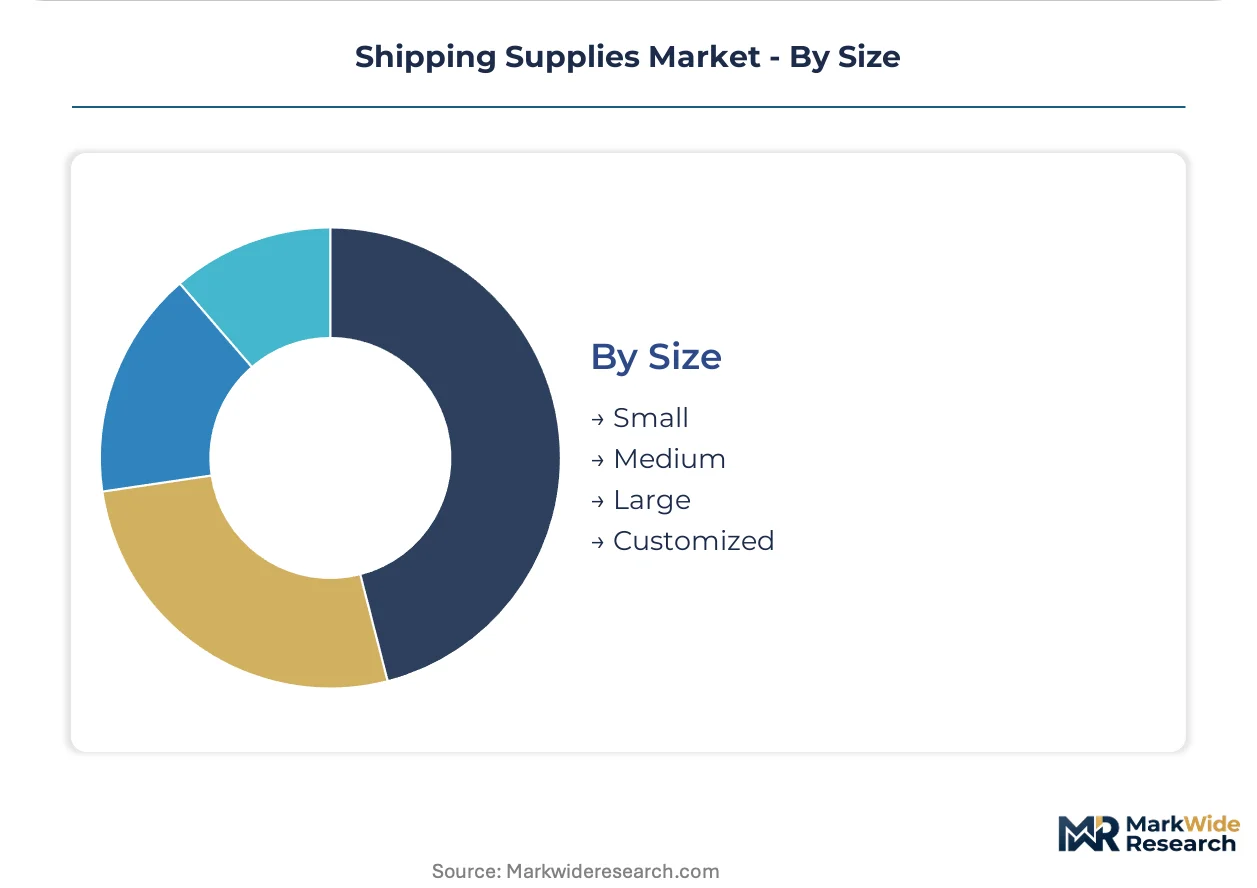
Size:
Customer type and order profile geometry dictate dimensional requirements.
- Small:Compact formats serve individual item shipments in direct-to-consumer channels, with automated sortation systems imposing strict dimensional tolerances.
- Medium:Mid-range configurations balance handling efficiency with freight cube optimization across retail replenishment networks.
- Large:Bulk containment solutions unitize palletized freight for manufacturing and wholesale distribution, requiring 44 ECT and higher ratings.
- Customized:On-demand box-making systems eliminate void fill requirements and reduce freight cube through exact-fit geometries.
Medium sizes dominate transaction volume; customized formats show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies, with Germany prioritizing circularity mandates while the United States optimizes for fulfillment velocity and China scales domestic e-commerce infrastructure.
United States
Midwestern manufacturing hubs face acute skilled operator shortages for automated corrugated converting lines, forcing accelerated capital deployment. OSHA warehouse safety standards shape ergonomic design requirements for domestic suppliers. The Ohio River Valley logistics cluster concentrates demand as warehouse construction outpaces local converter capacity.
Germany
Industrial logistics corridors drive demand for customized box configurations that minimize dimensional weight charges. The EU Packaging and Packaging Waste Regulation tightens recyclability mandates for corrugated materials. German white goods exporters face aggressive compliance timelines as the national chemical regulator enforces REACH transitional quotas.
China
Domestic e-commerce fulfillment centers multiply SKU complexity and drive procurement of right-size packaging automation. The country's national environmental regulator advances dual carbon goals that constrain virgin pulp dependency. Yangtze River Delta manufacturing clusters scale de-inking infrastructure for containerboard production.
Japan
Precision electronics exporters specify protective packaging for fragile freight with strict damage tolerance thresholds. METI industrial standards influence material selection for moisture-sensitive pharmaceutical lanes. Kanto region logistics providers consolidate supplier relationships around integrated packaging-plus-fulfillment service contracts.
India
Direct-to-consumer retail expansion accelerates demand for corrugated fiberboard with established recycling streams. BIS quality standards shape Edge Crush Test rating specifications for load-bearing performance. Maharashtra industrial corridors attract investment in automated sortation-compatible parcel geometry systems.
Shipping Supplies Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pulp-to-box infrastructure owners commanding delivery reliability advantages amid feedstock volatility. The market structure rewards backward integration into recycled fiber networks and captive supply of containerboard. Three archetypes dominate: integrated pulp-to-box conglomerates, specialized protective packaging engineers, and regional fulfillment-focused converters. Competitive moves concentrate on capacity expansion in logistics-adjacent geographies and portfolio diversification into inflatable barrier systems.
Within the integrated tier, International Paper and Smurfit Kappa exemplify scale-driven positioning through captive pulp and recycled fiber infrastructure. Sealed Air Corporation anchors the protective packaging specialist vector. These three occupy positions that span upstream feedstock control through downstream fulfillment integration, representing the vertical range that defines competitive advantage in this market.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Smurfit Kappa |
| DS Smith |
| Mondi |
| Sealed Air Corporation |
| Pregis |
| Uline |
| Packaging Corporation of America |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month commissioning cycles for precision servo-controlled converting equipment concentrate pricing power with integrated pulp-to-box conglomerates that can guarantee capacity allocation, while spot buyers in the Ohio River Valley logistics cluster absorb escalating premiums amid acute skilled operator shortages.
Pricing Analysis
Long-term offtake agreements dominate procurement between mid-market e-commerce retailers and regional converters, displacing spot purchasing as warehouse construction outpaces local capacity. Price differentiation separates certified circularity tracking tiers under EU Packaging and Packaging Waste Regulation mandates from commodity virgin-fiber alternatives. Cost compression in standard-grade corrugated runs through Old Corrugated Container feedstock volatility and export demand from Asian packaging mills. Third-party logistics providers exhibit lowest price sensitivity due to integrated packaging-plus-fulfillment service bundling, while small direct-to-consumer retailers face acute exposure to dimensional weight charge optimization.
Supply Chain Analysis
Port congestion on transpacific trade lanes and container availability constraints amplify inbound logistics costs for virgin pulp imports into Midwestern US manufacturing hubs. Supply concentrates in the United States, Germany, and China, with Germany's industrial logistics corridor anchoring European recycled fiber network expansion. Raw material dependencies rest on Old Corrugated Container feedstock, containerboard rolls, and petroleum-based resin chemistries facing REACH substitution pressure. Single-source vulnerability concentrates in automated converting line equipment suppliers with 18-24 month installation backlogs. Distribution runs through fulfillment-adjacent regional converters integrated into Ohio River Valley and Yangtze River Delta logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in right-size packaging automation as direct-to-consumer order profiles multiply SKU complexity beyond the capacity of legacy spot-purchasing relationships.
For Market Incumbents: Shield market position by accelerating captive recycled fiber network expansion in Germany's industrial logistics corridor to sustain delivery reliability amid OCC price volatility. Deepen backward integration into de-inking infrastructure to offset virgin pulp dependency as China's national environmental regulator advances dual carbon goals. Prioritize certification investment for EU Packaging and Packaging Waste Regulation compliance tracking to capture extended producer responsibility service revenue. For New Entrants and Emerging Players: Lead with on-demand box-making system deployment targeting mid-market e-commerce retailers in the Ohio River Valley logistics cluster where warehouse construction has outpaced converter capacity. Exploit white-space in inflatable barrier convergence with robotic pick-and-place equipment for pharmaceutical cold chain applications. Pursue integrated packaging-plus-fulfillment service contracts as the primary go-to-market angle to displace fragmented spot purchasing. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because integrated pulp-to-box infrastructure owners command delivery reliability advantages that compound amid feedstock volatility and labor shortfalls. Target regional fulfillment-focused converters with automated sortation-compatible parcel geometry capabilities in logistics-adjacent geographies. Watch for inflection in REACH Annex XVII enforcement timelines as German white goods exporters accelerate water-blown foam qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Networks | Captive OCC feedstock supply insulates Smurfit Kappa from export demand swings to Asian mills. |
| Right-Size Packaging Automation Deployment | On-demand box-making systems eliminate void fill requirements for Ohio River Valley fulfillment centers. |
| EU Circularity Certification Investment | Extended producer responsibility tracking opens compliance service revenue under Packaging and Packaging Waste Regulation mandates. |
| Inflatable Barrier System Convergence | Air cushion integration with robotic pick-and-place equipment penetrates pharmaceutical cold chain specifications. |
| Long-Term Capacity Allocation Agreements | Multi-year offtake contracts guarantee converter utilization amid e-commerce demand ramp volatility. |
Research Methodology
A spread of perspectives from corrugated converting plant managers, e-commerce fulfillment procurement leads, third-party logistics channel partners, and EU regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with automated equipment engineers and molded fiber R&D directors combined with secondary validation from SEC 10-K filings of integrated paper and packaging conglomerates, customs trade data on OCC export flows, and EPA recycled content threshold documentation. Bottom-up triangulation across product type, material, end user, and size segmentation dimensions anchored volume estimates against top-down macroeconomic indicators.
Segmentation dimensions modeled encompass product type hierarchy, material feedstock tier, end-use application intensity, and dimensional size category across the projection horizon. CAGRs derive from regression analysis against e-commerce fulfillment density indices, REACH chemical substitution timelines, and automated sortation penetration curves. Industry-specific forecast inputs include Edge Crush Test specification migration patterns and de-inking infrastructure capacity additions in Germany's industrial logistics corridor.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce velocity, stable OCC collection program operations, or unimpaired transpacific container availability would require recalibration. Forecasts reflect documented assumptions on labor availability for automated line commissioning and regulatory enforcement trajectories for extended producer responsibility frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Spain Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Real-Time Inventory-in-Transit Positioning Platforms Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
GCC Trailer Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market