
 Unmanned Traffic Management Market | 2026-2036
Unmanned Traffic Management Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Traffic Management Market Analysis
EU U-space regulation is decoupling legacy air traffic control from drone-specific coordination requirements. Thales Group leverages its ATM heritage to anchor European deployment timelines. L3Harris Technologies competes through military-grade communication links adapted for civilian UTM networks. Lockheed Martin Corporation dominates North American test corridors with integrated radar and AI fusion systems.
Unmanned Traffic Management denotes the integrated hardware, software, and communication infrastructure enabling safe, scalable coordination of autonomous aircraft in shared low-altitude airspace, typically below 400 feet AGL, encompassing detect-and-avoid algorithms, dynamic geofencing, and real-time telemetry exchange. Traffic Monitoring Systems currently occupy the largest system-type allocation due to regulatory mandates for continuous aerial surveillance, while AI-based Analytics within the technology dimension represents the fastest-expanding margin pool as operators demand predictive conflict resolution. Delivery Services applications sustain premium pricing structures where route density justifies dedicated corridor licensing.
The FAA in the United States enforces Remote ID compliance and BVLOS waiver frameworks that directly shape vendor product roadmaps, while EASA's U-space service provider certification in Europe creates a two-tier market between certified and uncertified platform operators. Stakeholders must monitor which regulatory jurisdiction first achieves standardized cross-border UTM interoperability, as this will determine the geographic sequencing of scalable revenue models.
Market Dynamics
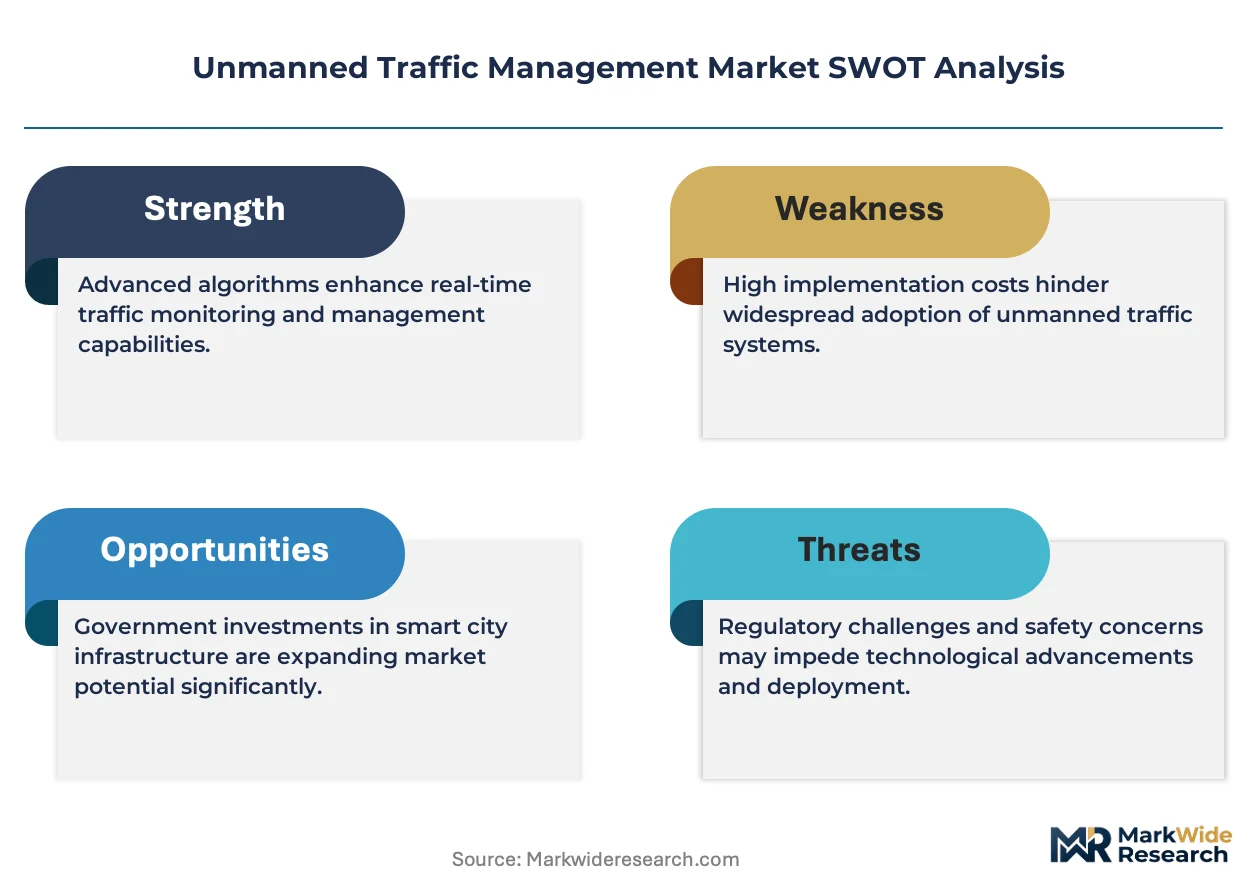
The Unmanned Traffic Management Market is experiencing structural compression as regulatory mandates for Beyond Visual Line of Sight operations force interoperability between legacy radar networks and AI-native detection systems, creating a dual-speed vendor landscape.
Growth Catalysts
- EASA U-space Service Provider Certification:The European framework mandates standardized digital infrastructure, creating immediate procurement pull from fleet operators seeking corridor access in Switzerland and Germany.
- Urban Air Mobility Cargo Deployments:Singapore and Dubai operators are scaling dedicated freight routes, generating demand for dynamic geofencing and real-time telemetry exchange capabilities.
- AI-based Predictive Conflict Resolution:Machine learning algorithms for detect-and-avoid functionality are reducing minimum separation distances, enabling higher-density corridor licensing.
Market Restraints
- Legacy ATM Integration Costs:Harmonization with existing air traffic management systems requires substantial capital outlay, particularly for radar fusion and voice communication handoffs.
- Cross-border Spectrum Allocation Friction:C-band and L-band frequency coordination between adjacent jurisdictions creates deployment delays for communication link providers.
- Cybersecurity Certification Burden:Military-grade encryption standards for civilian networks extend vendor development timelines and inflate hardware costs.
Strategic Opportunities
- Integrated Testing Corridors in Switzerland:Swissmedic and the Federal Office of Civil Aviation have established early-mover regulatory sandboxes attracting platform validation contracts.
- Drone-as-a-Service Business Models:Subscription-based UTM access is displacing perpetual licensing for small logistics operators with variable flight volumes.
- 5G Network Slicing Convergence:Telecommunications infrastructure providers are positioning ultra-reliable low-latency communication as a shared service layer for command-and-control links.
Industry Challenges
- Certified Software Engineer Scarcity:DO-178C and ED-12C qualified developers for safety-critical avionics systems command premium compensation, constraining vendor scaling velocity.
- Multi-jurisdiction Compliance Parallelism:Simultaneous FAA BVLOS waiver pursuit and EASA U-space certification requires duplicate documentation and testing regimes.
- Sensor Fusion Latency Standards:Sub-100 millisecond detect-and-avoid response requirements strain edge computing architectures and thermal management in compact drone payloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Traffic Management Market |
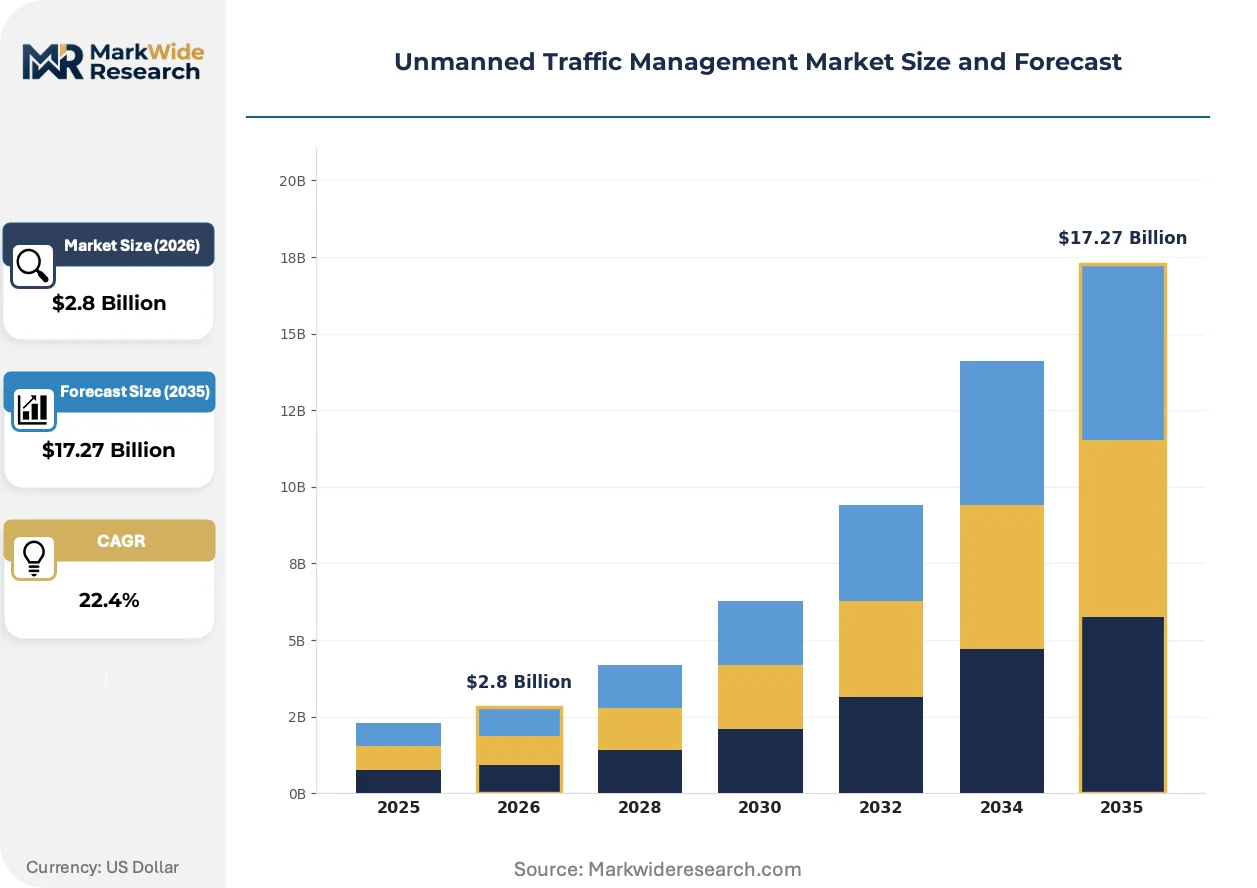
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $17.27 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: UAV Control Systems, Traffic Monitoring Systems, Communication Networks, Data Management Platforms Application: Airspace Management, Infrastructure Inspection, Delivery Services, Emergency Response End User: Government Agencies, Private Enterprises, Logistic Companies, Emergency Services Technology: AI-based Analytics, Cloud Computing, Sensor Technology, Geolocation Services |
| Companies Covered | Thales Group, L3Harris Technologies, Lockheed Martin Corporation, Airbus SE, Altitude Angel, Frequentist, Leonardo S.p.A., Unifly, Nova Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Traffic Management Market Emerging Trajectories
Digital infrastructure for low-altitude coordination is undergoing rapid architectural transformation as predictive analytics supplant reactive surveillance, while procurement models shift toward performance-guaranteed service contracts.
Edge-native AI inference for real-time trajectory deconfliction is overtaking centralized cloud processing architectures. Urban air mobility operators in Dubai and Singapore are deploying onboard neural networks to reduce communication link dependency. This distributed computing shift is compressing vendor margins on ground-based server infrastructure while elevating semiconductor content in aircraft avionics.
REACH-compliant hardware material restrictions are reshaping European supply chain configurations for ground station enclosures and antenna assemblies. The regulation's substance limitations on flame retardants and heavy metals are forcing redesigns of outdoor-rated equipment housings. German and Swiss system integrators are accelerating qualification of aluminum-magnesium alloy alternatives to maintain deployment timelines.
Outcome-based corridor availability guarantees are displacing per-flight transaction pricing among large logistics fleet operators. Amazon Prime Air and Wing Aviation procurement teams are negotiating uptime commitments and latency penalties rather than usage-based fees. This contractual evolution is most visible in the United States, where FAA Remote ID compliance deadlines have concentrated buyer leverage during vendor selection processes.
Unmanned Traffic Management Market Segmentation
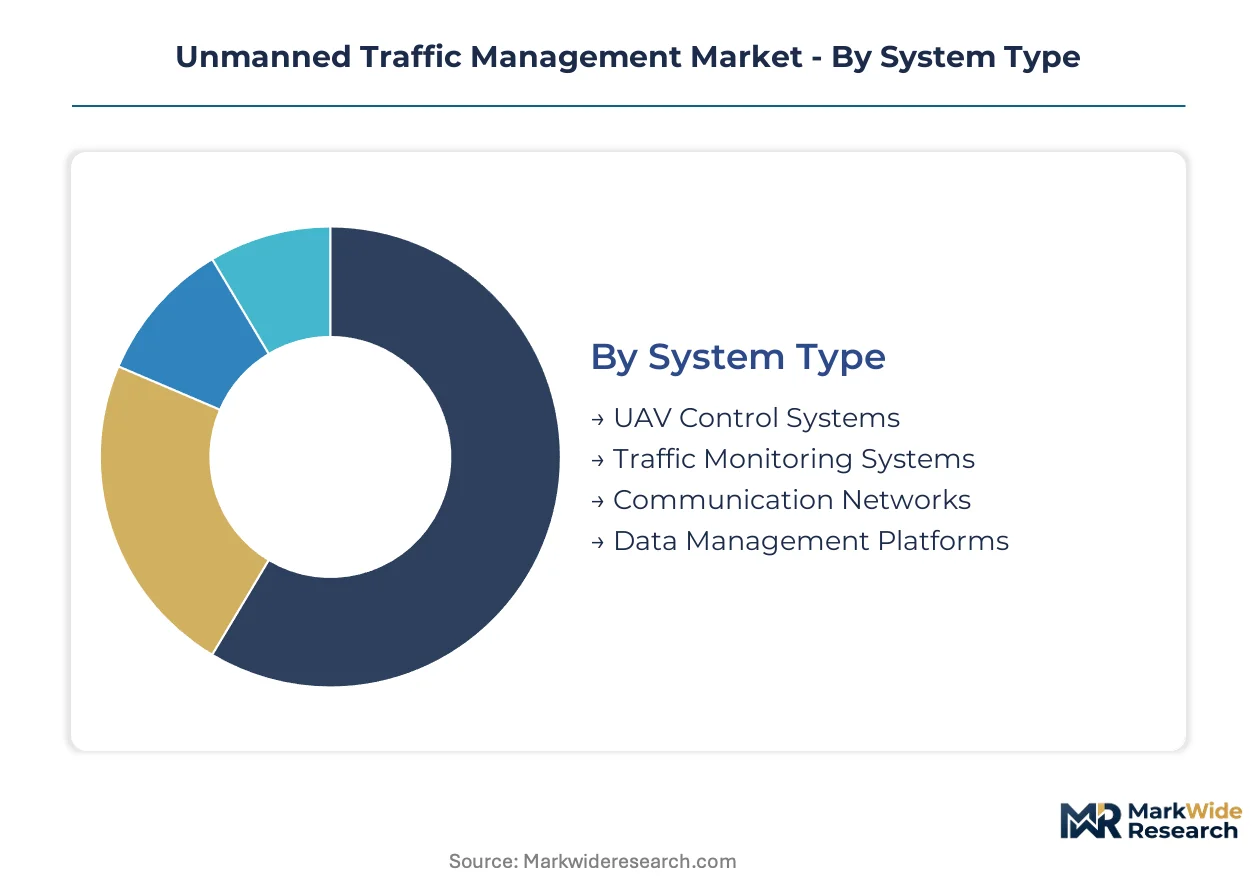
UTM procurement decisions diverge sharply by operational scale and regulatory exposure, with fleet operators prioritizing corridor availability guarantees while government buyers emphasize multi-vendor interoperability mandates. Segmentation reveals where vendor margins concentrate versus where volume transactions commoditize.
System Type:
Buyers differentiate primarily by integration burden with legacy air traffic infrastructure, with certified operators absorbing premium costs for radar harmonization while emerging fleets seek modular, software-native alternatives.
- Traffic Monitoring Systems:Continuous aerial surveillance hardware incorporating ADS-B receivers, radar fusion processors, and multi-sensor correlation engines. Regulatory mandates from the FAA and EASA for persistent low-altitude coverage are concentrating procurement among Swiss and German corridor operators managing dense urban air mobility routes.
- UAV Control Systems:Command-and-control interfaces enabling real-time telemetry exchange, flight plan validation, and dynamic geofencing enforcement. Demand clusters with Singapore and Dubai cargo operators scaling BVLOS operations where sub-100-millisecond latency thresholds determine vendor selection.
- Communication Networks:Dedicated C-band and L-band link infrastructure with military-grade encryption for civilian UTM networks.
- Data Management Platforms:Centralized logging and audit systems supporting regulatory compliance documentation and incident reconstruction.
Volume sits with Traffic Monitoring Systems; growth tilts toward UAV Control Systems.
Application:
Route density economics determine pricing architecture, with high-frequency corridors justifying dedicated infrastructure investment while intermittent use cases favor shared-service models.
- Delivery Services:Last-mile logistics coordination requiring dynamic corridor allocation, real-time weather integration, and predictive conflict resolution for high-density drone fleets. Premium pricing structures prevail where Amazon Prime Air and Wing Aviation operations in the United States negotiate uptime guarantees rather than per-flight fees.
- Emergency Response:Disaster relief and medical supply networks demanding pre-positioned communication infrastructure and priority spectrum access. Swiss and German operators are deploying dedicated UTM nodes along alpine rescue corridors where terrain occlusion challenges standard surveillance coverage.
- Airspace Management:Civil aviation authority systems for low-altitude coordination and regulatory enforcement.
- Infrastructure Inspection:Scheduled and on-demand pipeline, power line, and facility monitoring with variable flight volumes.
Delivery Services commands current revenue concentration; Emergency Response is climbing the fastest as civil defense budgets reallocate toward drone-enabled disaster response.
End User:
Contract structure preferences separate institutional buyers, with government agencies mandating outcome-based availability commitments while private operators negotiate usage-scaled subscription terms.
- Government Agencies:National aviation regulators and defense departments procuring sovereign UTM infrastructure with cybersecurity certification and cross-border interoperability requirements. FAA BVLOS waiver frameworks and EASA U-space service provider mandates are shaping procurement specifications in the United States and Switzerland.
- Logistic Companies:Parcel and freight operators with variable flight volumes seeking elastic infrastructure access without capital-intensive perpetual licensing. Subscription-based UTM-as-a-service models are displacing ownership among mid-tier operators in Singapore and Dubai.
- Private Enterprises:Energy, agriculture, and construction firms with intermittent inspection requirements.
- Emergency Services:Fire departments, medical transport authorities, and search-and-rescue organizations.
Government Agencies anchor procurement value; Logistic Companies are expanding most quickly as fleet-as-a-service business models proliferate.
Technology:
Processing architecture choices divide the vendor landscape between edge-native inference advocates and centralized cloud platform providers, with latency requirements determining technical winners.
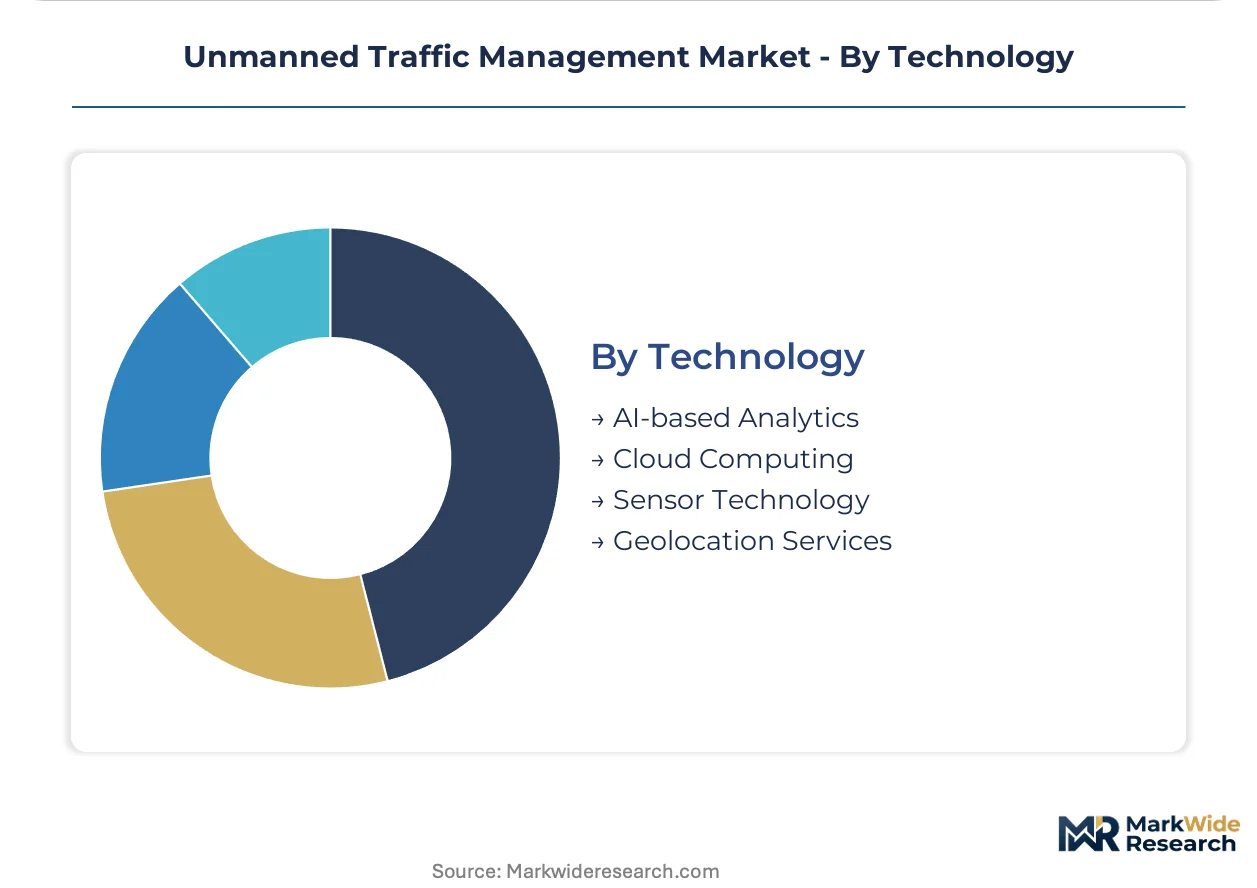
- AI-based Analytics:Machine learning algorithms for predictive conflict resolution, trajectory optimization, and anomaly detection in dense airspace. Onboard neural network deployment by Dubai and Singapore operators is compressing margins on ground-based server infrastructure while elevating semiconductor content in aircraft avionics.
- Sensor Technology:LiDAR, radar, and electro-optical detection systems enabling detect-and-avoid functionality with sub-100-millisecond response standards. Thermal management and edge computing integration challenges are constraining payload miniaturization timelines.
- Cloud Computing:Centralized data processing and storage infrastructure for historical analytics and regulatory reporting.
- Geolocation Services:GNSS augmentation and backup positioning systems for degraded signal environments.
Sensor Technology holds installed base dominance; AI-based Analytics is gaining share fastest as predictive systems displace reactive surveillance architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for unmanned traffic management infrastructure concentrates in jurisdictions with active BVLOS regulatory frameworks and established urban air mobility testbeds. Switzerland, the United States, Singapore, Germany, and the United Arab Emirates anchor procurement volumes through divergent certification pathways and corridor deployment timelines.
Switzerland
Federal Office of Civil Aviation corridor mandates and Swissmedic medical drone integration requirements drive procurement among alpine rescue operators and precision logistics providers. The country's U-space service provider certification framework, operational since 2023, creates immediate demand for detect-and-avoid hardware. Zurich and Geneva urban air mobility clusters are validating multi-sensor fusion systems for high-density low-altitude coordination.
United States
Amazon Prime Air and Wing Aviation fleet expansion programs generate concentrated demand for dynamic geofencing and real-time telemetry exchange capabilities. FAA Remote ID compliance deadlines and BVLOS waiver frameworks shape vendor product specifications and procurement timelines. North Carolina and Virginia test corridors are hosting integrated radar-AI fusion validation programs for commercial drone delivery networks.
Singapore
Urban air mobility cargo operators scaling dedicated freight routes across the city-state require sub-100-millisecond latency communication infrastructure. The Civil Aviation Authority of Singapore's regulatory sandbox for drone deliveries mandates continuous aerial surveillance coverage above designated corridors. One-North and Jurong Innovation District clusters are deploying edge-native AI inference systems for predictive conflict resolution.
Germany
EASA U-space service provider certification requirements and REACH-compliant hardware mandates create dual procurement pressures for ground station and aircraft avionics suppliers. The country's national aviation regulator enforces standardized digital infrastructure for low-altitude coordination across federal states. Bavaria and North Rhine-Westphalia industrial corridors are integrating military-grade encryption standards into civilian UTM network deployments.
United Arab Emirates
Dubai's autonomous aerial vehicle passenger service expansion and Abu Dhabi's logistics drone corridor programs generate demand for AI-based predictive analytics and dynamic corridor allocation systems. The General Civil Aviation Authority's regulatory framework prioritizes sovereign infrastructure control and cross-border interoperability with Saudi Arabian networks. Dubai Silicon Oasis and Masdar City clusters are validating 5G network slicing architectures for command-and-control link redundancy.
Unmanned Traffic Management Market Vendor Landscape
European defense-heritage groups anchor one tier; North American aerospace conglomerates and specialized UTM software vendors hold differentiated positions. The vendor landscape exhibits moderate concentration, with established air traffic management suppliers leveraging certification relationships against agile software-native entrants. Three archetypes dominate: legacy ATM integrators repurposing radar fusion expertise, military communication specialists adapting encrypted link infrastructure, and cloud-native platform developers offering subscription-based corridor access. Competitive dynamics center on strategic partnerships with telecommunications providers and portfolio diversification into edge computing hardware.
Within the legacy ATM integrator tier, Thales Group and Leonardo S.p.A. represent European defense-aerospace conglomerates with established regulatory relationships and certified safety-critical software development capabilities. L3Harris Technologies occupies a position among military communication specialists adapting hardware for civilian network requirements. These three companies exemplify how vendor archetypes align with divergent procurement preferences across EASA U-space and FAA BVLOS regulatory jurisdictions.
| Leading Market Players |
|---|
| Thales Group |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| Airbus SE |
| Altitude Angel |
| Frequentist |
| Leonardo S.p.A. |
| Unifly |
| Nova Systems |
| Others |
Supply Flow & Price Mechanics
EASA U-space certification mandates for detect-and-avoid hardware are compressing vendor margins as buyers demand military-grade encryption standards, forcing supply chains toward qualified semiconductor foundries and extending procurement timelines. This specification tightening elevates pricing power among certified safety-critical software developers while squeezing modular component suppliers into commodity tiers.
Pricing Analysis
Volume concentrates in Traffic Monitoring Systems where radar fusion processors command standard-tier margins; premium pools sit with AI-based Analytics subscriptions. Price differentiation separates FAA BVLOS-compliant configurations from uncertified alternatives, with after-sales service bundling widening spreads. Cost compression in entry-tier communication hardware is intensifying because REACH-compliant material redesigns inflate enclosure costs. Logistic Companies show highest price sensitivity due to variable flight volumes, while Government Agencies absorb premium positioning for sovereign infrastructure control.
Supply Chain Analysis
Dual-sourcing requirements from German and Swiss corridor operators mandate qualified second sources for edge computing chipsets and ADS-B receivers, fragmenting procurement leverage. Manufacturing concentrates in Germany, Switzerland, and the United States for safety-critical avionics; Taiwan and South Korea supply advanced semiconductors for neural network inference. Raw material dependencies include aluminum-magnesium alloys for REACH-compliant housings, C-band RF components, and thermal management substrates. Single-source vulnerability runs through qualified DO-178C software engineering capacity. Distribution runs through system integrators with regulatory certification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified software engineer scarcity props pricing for safety-critical development, constraining vendor scaling velocity and sustaining margin premiums for qualified incumbents.
For Market Incumbents: Extend radar fusion expertise into edge-native AI inference hardware to capture onboard neural network deployment demand from Dubai and Singapore operators. Fortify EASA U-space certification relationships before FAA BVLOS waiver frameworks consolidate buyer leverage. Prioritize captive supply of military-grade encryption chipsets to deflect margin pressure from cybersecurity certification burdens. For New Entrants and Emerging Players: Mid-tier Logistic Companies in Singapore and Dubai present underserved demand for subscription-based UTM-as-a-service models with elastic corridor access. Penetrate drone-as-a-service platforms by offering API-native telemetry exchange without perpetual licensing friction. Position through telecommunications partnerships leveraging 5G network slicing for command-and-control link redundancy. For Investors and Strategic Acquirers: The window for entry favors cloud-native platform developers with existing FAA or EASA regulatory relationships over hardware-centric entrants facing certification timelines. Long-term viability hinges on cross-border interoperability capabilities as jurisdictional standardization determines scalable revenue models. Monitor which regulator first achieves standardized UTM interoperability as the inflection signal for geographic sequencing of acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EASA U-space Service Provider Certification | Creates immediate procurement pull from Swiss and German fleet operators seeking corridor access. |
| Edge-Native AI Inference Hardware Development | Captures margin migration from ground servers to onboard avionics in Dubai and Singapore deployments. |
| Telecommunications Infrastructure Partnership | Positions 5G network slicing as shared service layer for sub-100-millisecond command-and-control links. |
| REACH-Compliant Supply Chain Reconfiguration | Maintains European deployment timelines through qualified aluminum-magnesium alloy enclosure sourcing. |
| Drone-as-a-Service Platform Integration | Displaces perpetual licensing among mid-tier Singapore and Dubai operators with variable flight volumes. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across UTM platform developers, aviation regulatory affairs leads, corridor operators in Switzerland and Dubai, telecommunications infrastructure planners, and semiconductor procurement specialists at avionics vendors. FAA BVLOS waiver documentation, EASA U-space certification registries, and Civil Aviation Authority of Singapore sandbox disclosures supplied segmentation validation. Bottom-up unit economics from fleet operator deployments reconciled with top-down infrastructure spending projections across the analysis window.
Data-stream reconciliation across Traffic Monitoring Systems, UAV Control Systems, Communication Networks, and Data Management Platforms shaped volume allocation, with AI-based Analytics, Sensor Technology, Cloud Computing, and Geolocation Services driving technology-segment growth rates. Delivery Services, Emergency Response, Airspace Management, and Infrastructure Inspection applications modeled separately by route density economics. CAGRs derived from regulatory mandate timelines and fleet deployment schedules, incorporating edge computing adoption curves and 5G network slicing penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-border spectrum allocation agreements and sovereign cybersecurity standard harmonization. Forecasts reflect documented assumptions regarding EASA-FAA regulatory convergence and BVLOS waiver approval velocity. A model refresh is warranted upon material change in multi-jurisdiction certification parallelism or breakthrough detect-and-avoid latency standards below 50 milliseconds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
Norway Autonomous Navigation Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market