
 Blind Spot Detection Market | 2026-2036
Blind Spot Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Blind Spot Detection Market Outlook
German automotive sensor suppliers are pivoting toward higher-resolution radar architectures for next-generation blind spot modules. Continental AG leverages in-house semiconductor capabilities to sustain margin control across the sensor stack. Robert Bosch GmbH anchors European OEM supply through integrated radar-camera fusion platforms. Denso Corporation dominates Japanese domestic fitment rates with compact 77 GHz radar designs.
Blind spot detection comprises electronic sensor arrays—typically operating at 24 GHz or 77 GHz for radar, or via machine-vision cameras with 120-degree field-of-view coverage—that monitor adjacent vehicle lanes and trigger driver alerts when obstacles occupy invisible zones adjacent to the host vehicle. Radar systems lead volume shipments due to all-weather reliability and lower per-unit cost curves, while camera systems capture premium positioning through object-classification depth. OEM end users concentrate procurement leverage, though aftermarket retrofits are gaining share among aging vehicle parc owners seeking affordable safety upgrades.
NHTSA mandates drive United States fitment rates upward, while Euro NCAP scoring protocols and Japan's Ministry of Land, Infrastructure, Transport and Tourism type-approval standards enforce comparable sensor performance thresholds across their respective markets. The European Union's General Safety Regulation mandates blind spot information systems on trucks and buses, tightening compliance timelines for commercial vehicle suppliers. Stakeholders must monitor divergence between regional frequency allocation rules for 77 GHz radar and the pace of camera-based AI validation standards to align product roadmaps with enforcement calendars.
Market Dynamics
The Blind Spot Detection Market is undergoing a fundamental sensor-stack transition as 77 GHz radar architectures displace legacy 24 GHz modules, driven by tighter angular resolution requirements from Euro NCAP and NHTSA protocols that now penalize coarse detection thresholds.
Growth Catalysts
- Euro NCAP 2026 Protocols:The European safety body's updated test scenarios mandate blind spot intervention for heavy commercial vehicles, forcing fleet-wide retrofits across German, French, and Italian truck parcs.
- Machine-vision AI validation:Camera-based systems with edge-computing inference are securing type approvals in Japan and South Korea, opening premium passenger vehicle segments previously radar-dominated.
- Commercial vehicle fleet consolidation:Large logistics operators in the United States are standardizing active safety specifications across Class 8 tractors, creating concentrated procurement volumes that amortize sensor development costs.
Market Restraints
- 77 GHz frequency allocation fragmentation:Divergent spectrum rules between the United States FCC, European CEPT, and Japan's Radio Law force module variants that inflate BOM costs and inventory complexity.
- Semiconductor foundry concentration:Advanced radar MMIC production clusters in Taiwan and South Korea expose supply continuity to geopolitical friction and capacity allocation decisions.
- Camera system weather dependency:Machine-vision performance degradation in heavy precipitation limits all-climate reliability, constraining deployment in Nordic and Alpine markets where radar maintains functional superiority.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Domestic manufacturing incentives are attracting radar module assembly investments to serve emerging OEM demand from Tata Motors and Mahindra & Mahindra.
- Radar-lidar fusion architectures:Next-generation highway pilot systems are integrating solid-state lidar with 77 GHz radar for redundant object confirmation in autonomous lane-change maneuvers.
- Aftermarket retrofit channels:Aging vehicle parc owners in Germany and Japan are purchasing dealer-installed blind spot kits as affordable alternatives to new vehicle acquisition.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates among Tier 1 suppliers, constraining validation throughput for new market entrants.
- Legacy vehicle electrical architecture integration:CAN bus bandwidth limitations in pre-2020 vehicle platforms require gateway module development that extends retrofit installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blind Spot Detection Market |
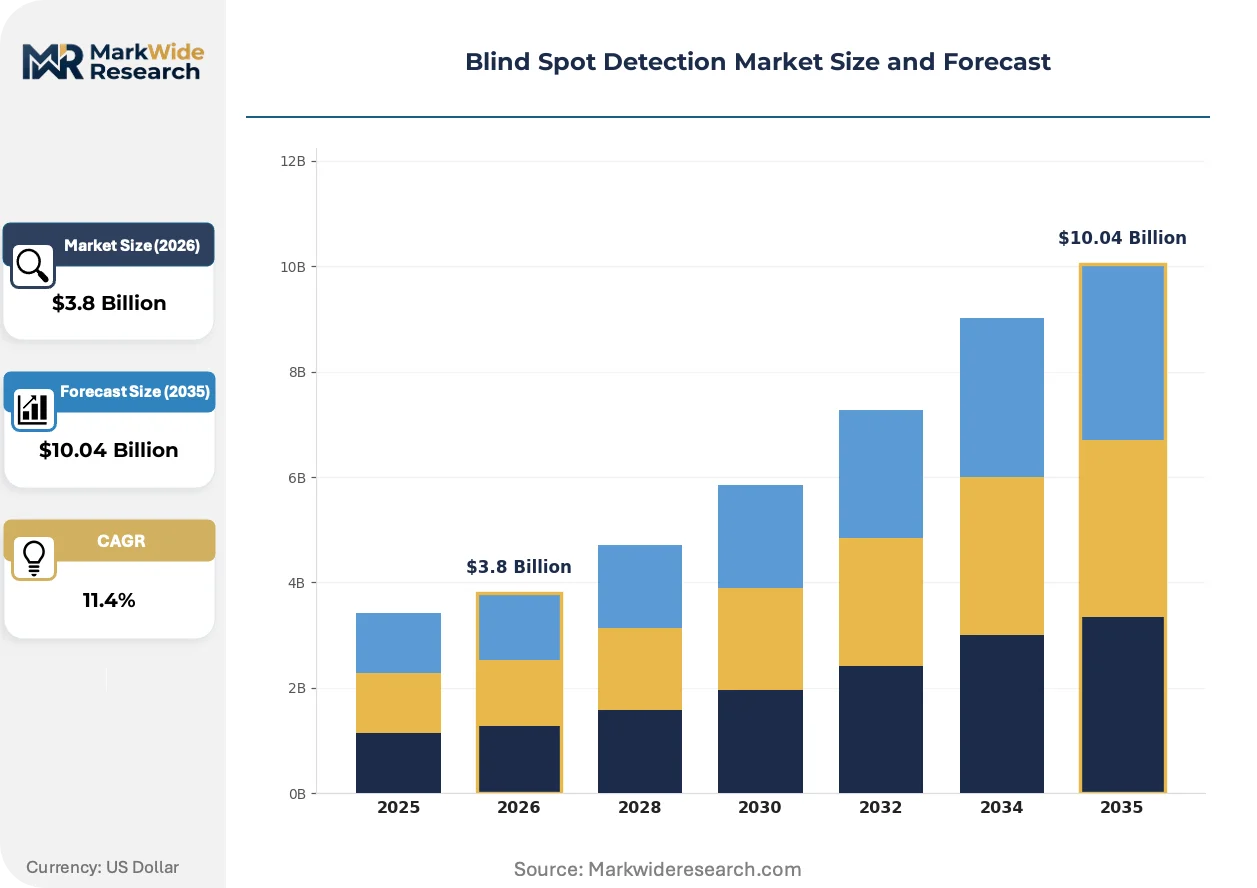
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Systems, Camera Systems, Ultrasonic Sensors, LiDAR Systems End User: OEMs, Aftermarket Providers, Vehicle Fleet Operators, Insurance Companies Installation Type: Integrated Systems, Aftermarket Solutions, Factory-Fitted, Retrofitted Technology: Active Systems, Passive Systems, Hybrid Approach, Advanced Driver Assistance Systems |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Magna International Inc., Valeo SA, Aptiv, ZF Friedrichshafen AG, Autoliv Inc., Sensata Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blind Spot Detection Market Strategic Shifts
Sensor fusion architectures are collapsing discrete component boundaries as radar and camera pipelines merge into unified perception stacks, compressing supplier margins while elevating system-level performance thresholds.
Imaging radar with MIMO antenna arrays is converging with machine-vision processing pipelines to deliver dense point clouds that rival lidar spatial resolution at substantially lower unit economics. European premium OEMs are piloting these fused modules for Level 3 conditional automation, where redundant perception paths satisfy safety redundancy requirements without duplicating hardware cost structures. The convergence is compressing standalone camera supplier margins while rewarding semiconductor houses with radar DSP and AI accelerator integration capabilities.
REACH substance restrictions and RoHS recast directives are forcing solder material and PCB substrate substitutions that alter thermal management properties in high-frequency radar modules. European module suppliers are redesigning stack-ups to maintain 77 GHz signal integrity with lead-free alloy compositions that exhibit different creep behavior under thermal cycling. The regulatory pressure is accelerating qualification timelines and disqualifying legacy Asian component sources lacking EU chemical compliance documentation.
Fleet procurement departments are consolidating safety system specifications into multi-year master service agreements that bundle blind spot detection with adjacent ADAS functions. Large North American trucking operators are bypassing traditional dealer channels to negotiate direct sensor supply contracts with Tier 1s, compressing aftermarket distributor margins and forcing channel restructuring. This concentration is most visible in United States long-haul segments where ten fleet operators control substantial Class 8 tractor procurement volumes.
Blind Spot Detection Market Segmentation
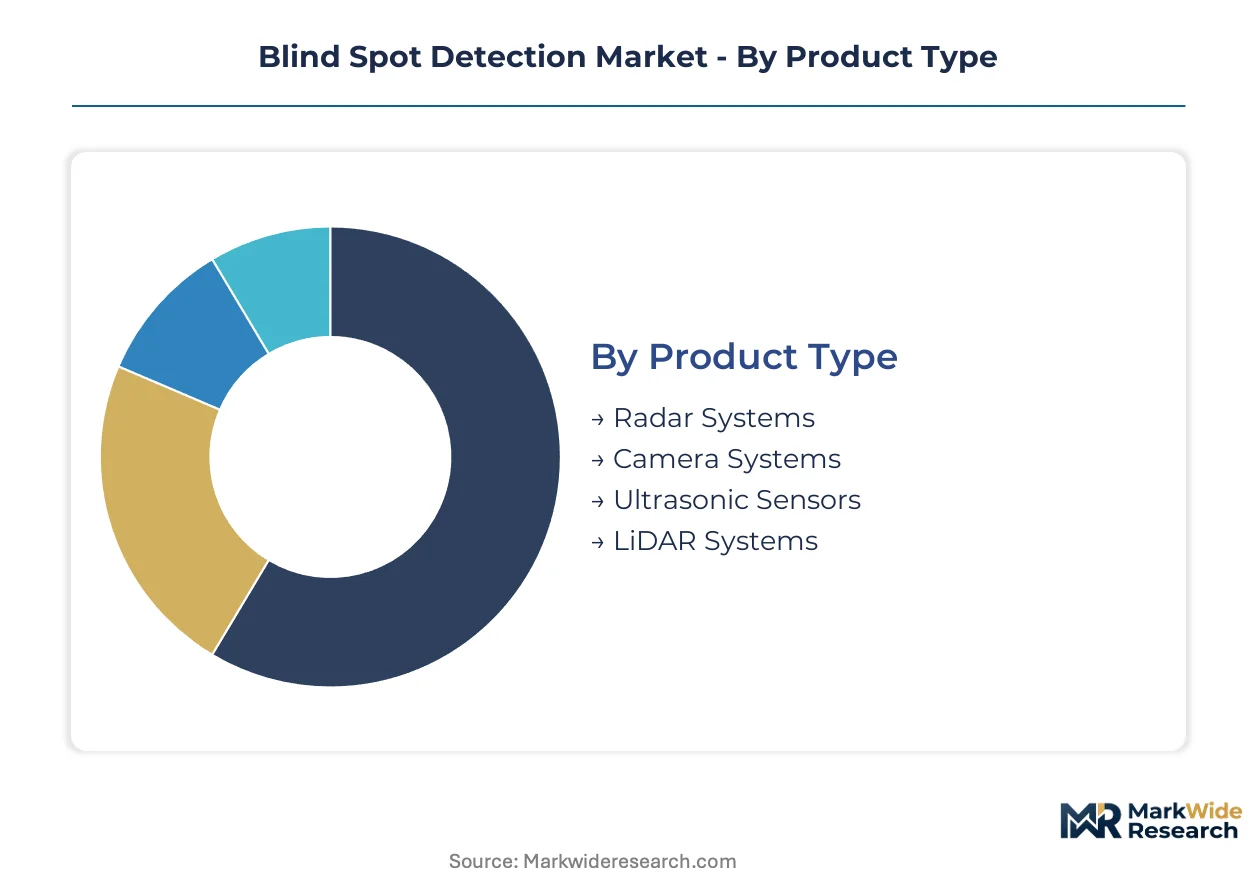
Blind spot detection procurement patterns diverge sharply across sensor modalities and installation channels. Fleet operators prioritize standardized active systems while individual owners favor cost-effective retrofit pathways.
Product Type:
Radar architectures demand the heaviest upfront capital commitment due to MMIC foundry tooling and RF calibration infrastructure.
- Radar Systems:77 GHz and 24 GHz modules dominate commercial vehicle fitment through all-weather reliability. German and Japanese OEMs concentrate procurement for heavy truck platforms where NHTSA mandates enforce minimum detection thresholds.
- Camera Systems:Machine-vision arrays with 120-degree field-of-view enable object classification depth for premium passenger segments. Type approvals in Japan and South Korea are accelerating adoption where edge-computing inference meets regulatory validation standards.
- Ultrasonic Sensors:Short-range parking-assist derivatives serve economy vehicle tiers with limited lane-change functionality.
- LiDAR Systems:Solid-state units are piloting in Level 3 highway automation for redundant object confirmation.
Radar Systems absorb the bulk of installed capacity; Camera Systems are expanding most quickly.
End User:
Procurement leverage concentrates among entities with multi-year fleet standardization authority.
- OEMs:Vehicle manufacturers integrate blind spot modules at platform design phase, locking in sensor specifications across model generations. European premium brands specify fused radar-camera stacks for Level 3 automation readiness.
- Vehicle Fleet Operators:Class 8 tractor buyers in the United States negotiate direct Tier 1 contracts, bypassing dealer markups. Ten major logistics groups control substantial procurement volumes that amortize sensor development costs.
- Aftermarket Providers:Dealer-installed kits target aging vehicle parc owners in Germany and Japan seeking affordable safety upgrades.
- Insurance Companies:Risk-based premium discounts incentivize policyholder retrofits in select European markets.
OEMs dominate absolute unit absorption; Vehicle Fleet Operators are climbing the fastest as procurement centralization accelerates.
Installation Type:
Factory integration commands premium pricing while retrofit channels compete on installation speed.
- Factory-Fitted:Modules installed during vehicle assembly achieve optimal sensor alignment and CAN bus integration. Euro NCAP scoring protocols favor these configurations for heavy commercial vehicle compliance.
- Integrated Systems:Multi-function ADAS bundles combine blind spot with adjacent safety features under unified ECU control.
- Retrofitted:Standalone kits address pre-2020 vehicle platforms with gateway modules that overcome legacy electrical architecture limitations.
- Aftermarket Solutions:Wireless-enabled units reduce installation complexity for independent repair channels.
Factory-Fitted maintains volume leadership; Retrofitted is gaining share fastest among parc renewal demand.
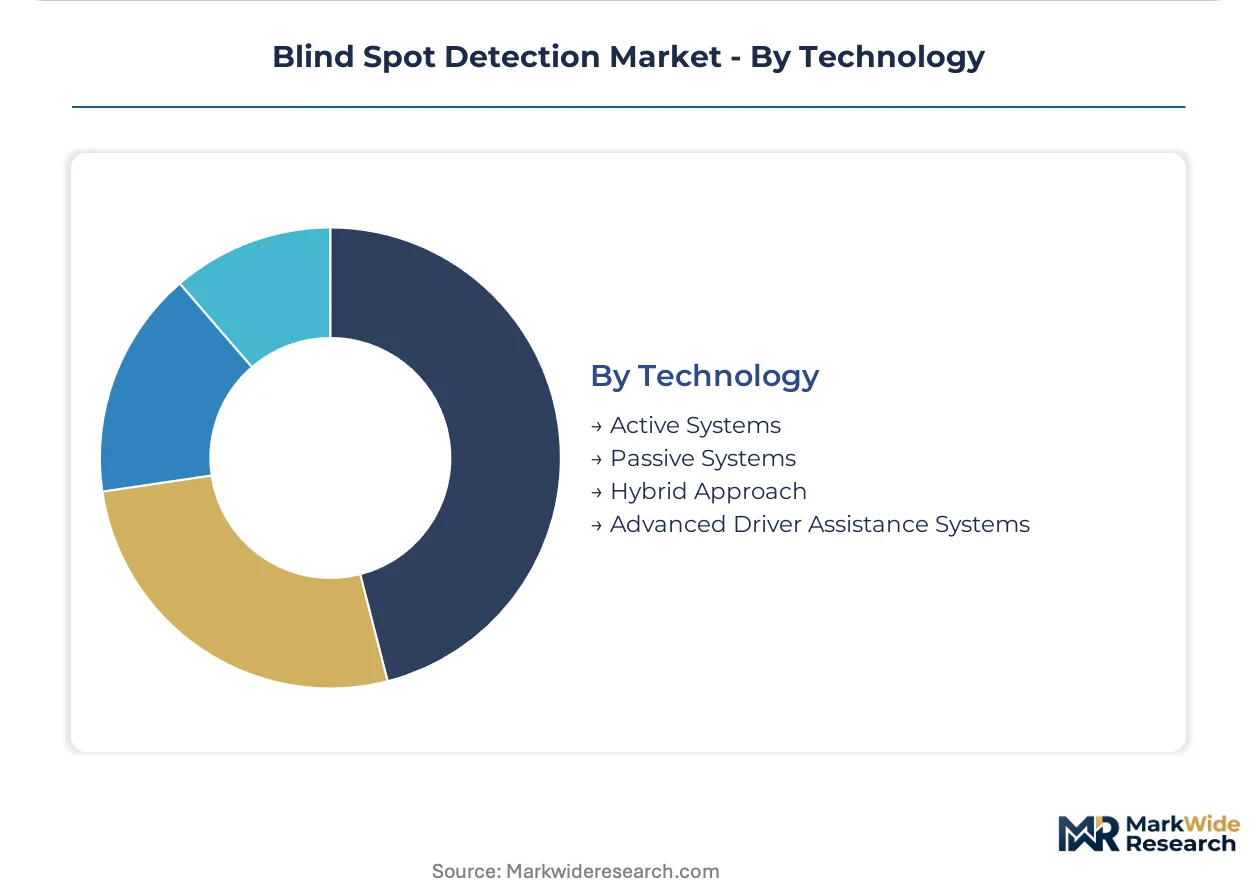
Technology:
Active sensing architectures require continuous power and data processing investment versus passive alternatives.
- Active Systems:Radar and camera units with real-time processing trigger immediate driver alerts and intervention signals. These configurations satisfy NHTSA and Euro NCAP mandates for commercial vehicle safety.
- Advanced Driver Assistance Systems:Integrated stacks merge blind spot with lane-keeping and adaptive cruise for highway automation. European premium OEMs pilot these for Level 3 conditional operation.
- Hybrid Approach:Redundant sensor combinations balance cost and coverage for mid-market vehicle tiers.
- Passive Systems:Convex mirror extensions and optical aids serve emerging market price segments without electronic complexity.
Active Systems command the installed base; Advanced Driver Assistance Systems show the steepest expansion trajectory as automation tiers converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium arsenide foundry capacity in Taiwan anchors semiconductor supply for radar MMICs that power blind spot modules worldwide. Regional procurement patterns diverge sharply between mature automotive clusters and emerging manufacturing zones.
United States
Class 8 tractor fleet operators in Michigan and Ohio negotiate direct Tier 1 contracts that bypass traditional dealer channels. NHTSA mandates enforce minimum detection thresholds for commercial vehicles operating interstate corridors. Detroit-Warren-Dearborn MSA concentrates radar module integration facilities serving domestic OEM platforms.
Germany
Premium passenger vehicle manufacturers in Bavaria specify fused radar-camera stacks for Level 3 automation readiness. The EU General Safety Regulation mandates blind spot information systems on trucks and buses with tightening compliance timelines. Stuttgart and Ingolstadt anchor Continental AG and Robert Bosch GmbH production clusters for 77 GHz module supply.
Japan
Compact 77 GHz radar designs from Denso Corporation dominate domestic fitment rates across Toyota and Honda platforms. The Ministry of Land, Infrastructure, Transport and Tourism enforces type-approval standards comparable to Euro NCAP performance thresholds. Aichi Prefecture houses concentrated sensor development facilities serving Japanese OEM integration pipelines.
China
Domestic OEMs in Shanghai and Guangzhou accelerate local sourcing of radar modules to reduce import dependency for ADAS platforms. MIIT frequency allocation rules for 77 GHz radar diverge from FCC and CEPT standards, forcing module variants. Yangtze River Delta clusters host emerging radar assembly investments targeting BYD and Geely procurement specifications.
South Korea
Hyundai-Kia platforms in Gyeonggi Province integrate edge-computing camera systems that secure type approvals under MFDS-equivalent automotive electronics standards. Machine-vision AI validation protocols open premium passenger segments previously radar-dominated. Seoul Capital Area concentrates R&D facilities for next-generation sensor fusion architectures.
Blind Spot Detection Market Competitive Environment
Global majors compete with regional champions across semiconductor integration depth and OEM relationship tenure. The vendor base stratifies between full-stack sensor developers, radar-specialized fabricators, and camera-module integrators. Three archetypes dominate: captive Tier 1 subsidiaries with in-house MMIC production, independent radar specialists licensing DSP cores, and vision-system houses pivoting toward fusion platforms. Competitive moves concentrate on backward integration into semiconductor supply and multi-year fleet service agreement capture.
Among German-based integrated suppliers, Continental AG and Robert Bosch GmbH exemplify the captive semiconductor archetype through in-house foundry relationships and RF calibration infrastructure. Denso Corporation anchors the Japanese specialist tier with concentrated domestic OEM supply relationships. These three entities represent divergent geographic anchoring strategies—European full-stack integration versus Asia-Pacific platform-specific optimization—while competing for identical regulatory certification thresholds across NHTSA, Euro NCAP, and Japan's type-approval frameworks.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Magna International Inc. |
| Valeo SA |
| Aptiv |
| ZF Friedrichshafen AG |
| Autoliv Inc. |
| Sensata Technologies, Inc. |
| Others |
Value Chain & Pricing Dynamics
MMIC foundry tooling costs cascade through radar module pricing tiers, with 77 GHz RF calibration infrastructure expenses concentrating in German and Japanese production clusters before reaching fleet procurement departments and aftermarket retrofit channels.
Pricing Analysis
Extended warranty and over-the-air update bundling separate OEM contract structures from unbundled aftermarket kits. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with Euro NCAP-compliant modules commanding substantial premiums. Cost compression in economy tiers is intensifying because semiconductor foundry allocation decisions favor high-volume automotive contracts. Fleet operators exhibit lowest price sensitivity due to amortized sensor development across Class 8 tractor parcs, while independent repair channels face acute margin pressure.
Supply Chain Analysis
Refurbishment flows for legacy 24 GHz modules and end-of-life radar units create secondary material recovery channels that feed gallium arsenide reclamation facilities in Taiwan. Taiwan, South Korea, and Germany anchor MMIC fabrication and RF calibration equipment supply. Gallium arsenide substrates, specialized RF laminates, and lead-free solder alloys constitute critical input dependencies. Single-source vulnerability concentrates in advanced radar DSP foundry capacity. Distribution runs through captive Tier 1 subsidiaries to OEM assembly plants, with aftermarket channels served by independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blind spot detection has become a vertical-integration race where semiconductor fabrication capabilities and fleet service agreement tenure determine margin capture, with upstream MMIC production and downstream multi-year maintenance contracts as the decisive levers.
For Market Incumbents: Deploy captive foundry relationships to lock in 77 GHz MMIC supply priority against emerging Chinese radar specialists. Secure ISO 26262 ASIL-D certification pipelines ahead of Euro NCAP 2026 protocol enforcement. Reinforce fleet service agreement capture through bundled ADAS maintenance contracts that extend beyond sensor hardware replacement cycles. For New Entrants and Emerging Players: Launch via wireless-enabled aftermarket retrofit kits targeting Germany and Japan's aging vehicle parc owners seeking dealer-installed safety upgrades. India's PLI scheme for automotive electronics offers the most penetrable geography for radar module assembly investments. Pursue direct procurement relationships with mid-size logistics operators bypassing established Tier 1 channels. For Investors and Strategic Acquirers: NHTSA mandate expansion into additional commercial vehicle classes is the leading indicator that fleet standardization will accelerate sensor volume concentration. Over the projection horizon, targets with in-house RF calibration infrastructure and existing Euro NCAP validation certificates offer strongest acquisition rationale. Monitor divergence between FCC, CEPT, and MIIT frequency allocation rules for early signals of module variant proliferation costs.| Strategic Initiative | Industry Significance |
|---|---|
| MMIC Foundry Backward Integration | In-house gallium arsenide production insulates Continental AG and Robert Bosch GmbH from Taiwan capacity allocation decisions. |
| Fleet Master Service Agreement Capture | Direct Tier 1 contracts with Class 8 operators in Michigan and Ohio compress aftermarket distributor margins and lock in volume. |
| Radar-Camera Fusion Platform Development | Unified perception stacks satisfy Level 3 automation redundancy requirements without duplicating hardware cost structures. |
| India PLI Scheme Manufacturing Investment | Domestic radar module assembly serves emerging OEM demand from Tata Motors and Mahindra & Mahindra procurement specifications. |
| Imaging Radar MIMO Array Deployment | Dense point cloud generation rivals lidar spatial resolution at substantially lower unit economics for highway automation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution channel heads, and fleet safety specification directors. NHTSA rulemaking dockets, Euro NCAP test protocol documentation, Japan's Ministry of Land, Infrastructure, Transport and Tourism type-approval records, and vehicle production databases provided validation anchors. Bottom-up sensor shipment estimates triangulated against top-down ADAS content-per-vehicle projections.
Data-stream reconciliation across vehicle registration databases, IHS Markit production forecasts, and semiconductor trade flows informed the analytical framework. Segmentation dimensions modeled include sensor modality, vehicle class, installation type, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline shipment volumes, with sensitivity analysis around Euro NCAP protocol adoption timelines and commercial vehicle fleet replacement cycles.
The model assumes a particular technology adoption path; alternative pathways for solid-state lidar fusion architectures would alter the outlook. Forecasts reflect assumptions about NHTSA mandate enforcement calendars and REACH substance restriction implementation. Practitioners should monitor frequency allocation rule harmonization progress and imaging radar type-approval velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
Europe IoT Connected Cars Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Automotive Predictive Technology Market