
 Canada Autonomous Navigation Market | 2026-2036
Canada Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Autonomous Navigation Market Insights
Canada's net-zero emissions commitments under the Canadian Net-Zero Emissions Accountability Act is decoupling autonomous navigation procurement from fossil-fuel-dependent platforms across federal and provincial fleets. Lockheed Martin leverages its Ottawa engineering center to sustain defense robotics contracts with the Canadian Armed Forces. L3Harris Technologies anchors maritime autonomous navigation development through its Halifax-adjacent operations serving Atlantic naval programs.
Autonomous navigation encompasses sensor-fusion systems that integrate LiDAR point-cloud data, radar returns, and computer vision inference to generate real-time positional awareness without human intervention, typically achieving localization accuracy within centimeter-scale tolerances for path planning in GPS-denied environments. The technology serves industrial and commercial purposes ranging from automated port logistics to military reconnaissance in contested electromagnetic environments. Computer vision segments command concentrated R&D investment as convolutional neural network architectures mature for edge deployment, while LiDAR retains premium positioning in applications demanding dense 3D environmental mapping. Deployment models gravitate toward hybrid architectures that balance latency-sensitive processing at the vehicle level with fleet-scale optimization through cloud connectivity.
Transport Canada, the Canadian Radio-television and Telecommunications Commission, and Defence Research and Development Canada collectively shape certification timelines, spectrum allocation for vehicle-to-infrastructure links, and sovereign capability requirements for military autonomy. Health Canada and PMRA oversight extends to agricultural drone applications where autonomous navigation intersects with pesticide dispersion protocols. Stakeholders must monitor evolving liability frameworks as provincial insurance regulators grapple with fault attribution in mixed autonomous-conventional traffic environments.
Market Dynamics
Canada's defense procurement refresh under Strong, Secure, Engaged policy is concentrating sovereign capability requirements for unmanned ground systems, while Transport Canada accelerates beyond-visual-line-of-sight certification timelines that reshape commercial operator economics.
Growth Catalysts
- Strong, Secure, Engaged policy:The Canadian Armed Forces procurement mandates prioritize domestic defense robotics development, creating sustained demand for autonomous navigation in tactical ground vehicles.
- Beyond-visual-line-of-sight regulations:Transport Canada certification pathways for commercial drone operators unlock precision agriculture and infrastructure inspection applications across provincial jurisdictions.
- Toronto-Waterloo corridor concentration:Automotive R&D clustering around autonomous vehicle testing facilities generates spillover demand for sensor-fusion talent and component suppliers.
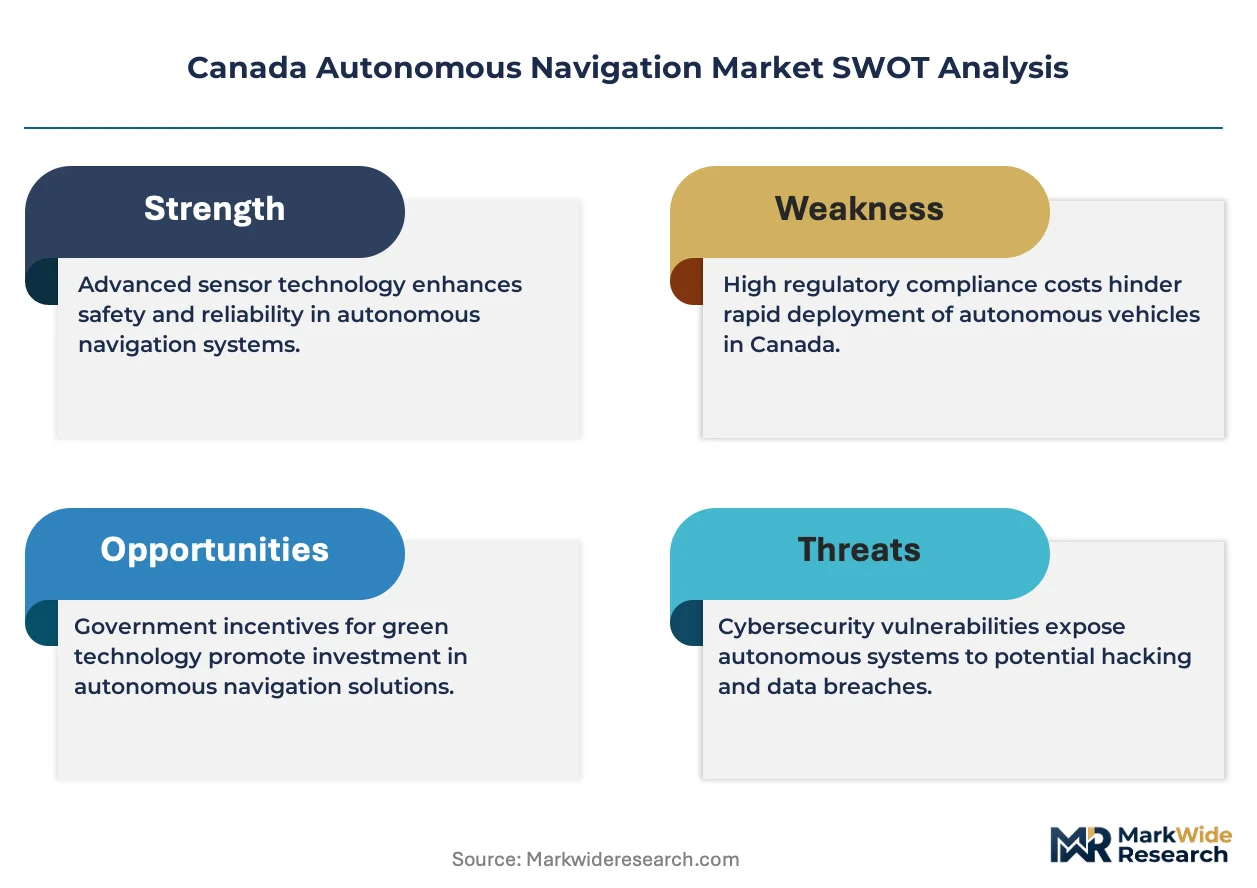
Market Restraints
- LiDAR cost structure:Dense 3D environmental mapping hardware retains premium positioning that compresses margins for commercial drone operators in agricultural applications.
- Spectrum allocation friction:Canadian Radio-television and Telecommunications Commission vehicle-to-infrastructure link licensing creates deployment delays for urban autonomous vehicle pilots.
- Convolutional neural network limitations:Edge deployment of computer vision inference struggles with adverse weather classification accuracy in maritime environments.
Strategic Opportunities
- Atlantic naval programs:Maritime autonomous navigation development for contested electromagnetic environments offers uncrowded procurement channels outside Ontario's technology corridor.
- Canadian Net-Zero Emissions Accountability Act:Federal and provincial fleet decarbonization mandates accelerate autonomous navigation procurement for electric platform integration.
- Sensor-fusion convergence:Integration of radar returns with LiDAR point-cloud data enables GPS-denied localization for underground mining operations in Quebec and British Columbia.
Industry Challenges
- Fault attribution frameworks:Provincial insurance regulators lack standardized protocols for mixed autonomous-conventional traffic liability, delaying commercial fleet deployment.
- Electromagnetic spectrum engineering:Defence Research and Development Canada sovereign capability requirements demand cleared personnel pipelines that constrain supplier scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Autonomous Navigation Market |
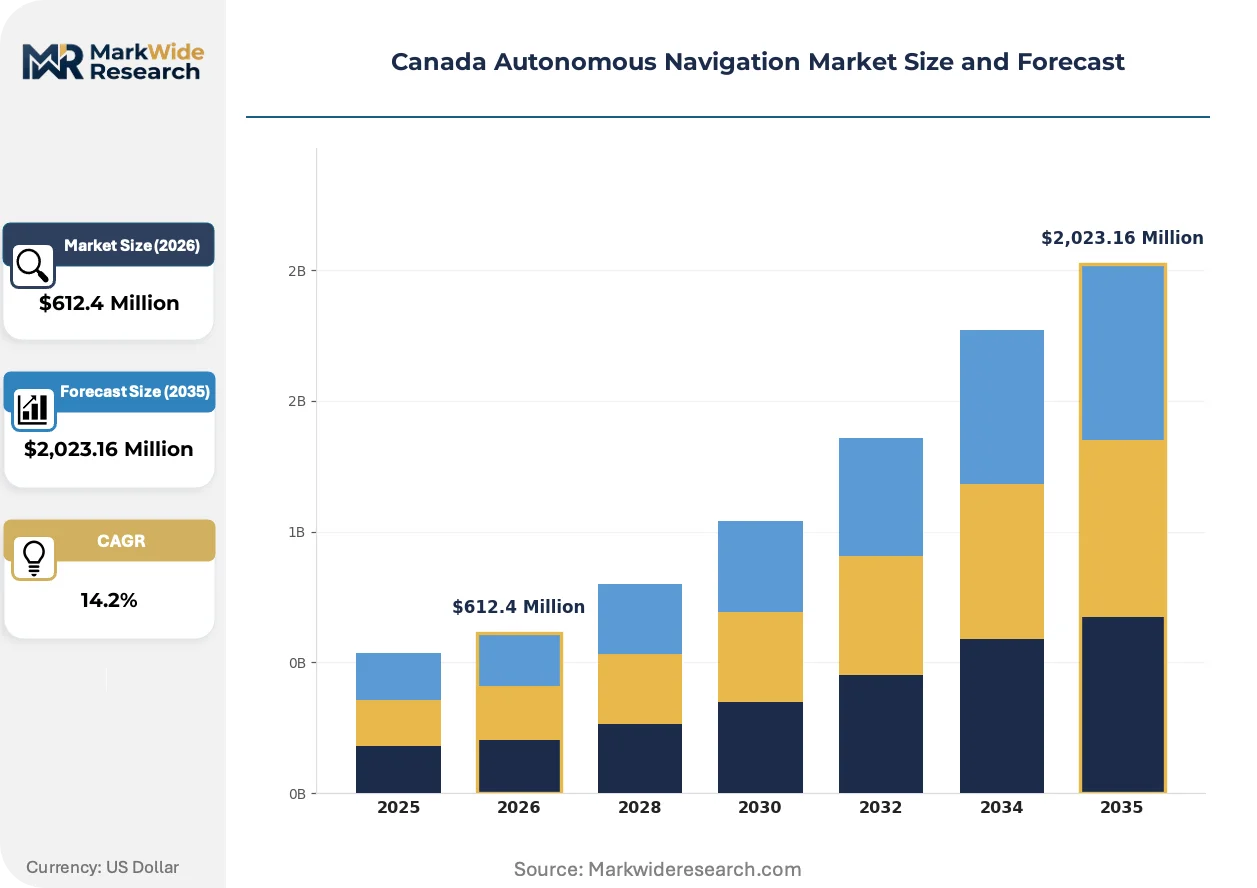
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,023.16 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Radar, Computer Vision, Ultrasonic Sensors Application: Automated Vehicles, Drones, Robotics, Marine Vessels End User: Transport Companies, Logistics Providers, Defense Contractors, Research Institutions Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Lockheed Martin, Northrop Grumman Corporation, L3Harris Technologies, General Dynamics Corporation, BAE Systems, Honeywell International, Raytheon Technologies Corporation, Safran, Thales Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Autonomous Navigation Market Trends and Innovations
Computer vision architectures and hybrid edge-cloud processing models are compressing development cycles for autonomous navigation platforms serving defense and commercial end-uses.
Sensor-fusion middleware is modularizing around standardized LiDAR-radar-vision interfaces that reduce integration overhead for unmanned ground vehicle developers. Defense contractors in Ottawa and Halifax are adopting these modular stacks to accelerate Canadian Armed Forces program delivery. The approach is modularizing subsystem procurement, allowing prime contractors to swap component suppliers without redesigning localization pipelines.
Transport Canada and the Canadian Radio-television and Telecommunications Commission are co-developing integrated certification frameworks that collapse sequential approval stages for beyond-visual-line-of-sight operators. The regulatory consolidation reduces timeline uncertainty for commercial drone service providers seeking agricultural and infrastructure inspection contracts. Agricultural drone applications face the tightest compliance windows as Health Canada and PMRA coordinate pesticide dispersion protocols with autonomous navigation certification.
Federal procurement patterns are consolidating around performance-based contracting that ties vendor payments to operational availability metrics rather than hardware delivery. The Canadian Armed Forces and Transport Canada pilot programs are displacing traditional cost-plus arrangements for unmanned systems. Defense robotics contracts in Ottawa now emphasize sustained engineering support over initial platform acquisition, reflecting Strong, Secure, Engaged policy priorities for sovereign sustainment capability.
Canada Autonomous Navigation Market Segmentation
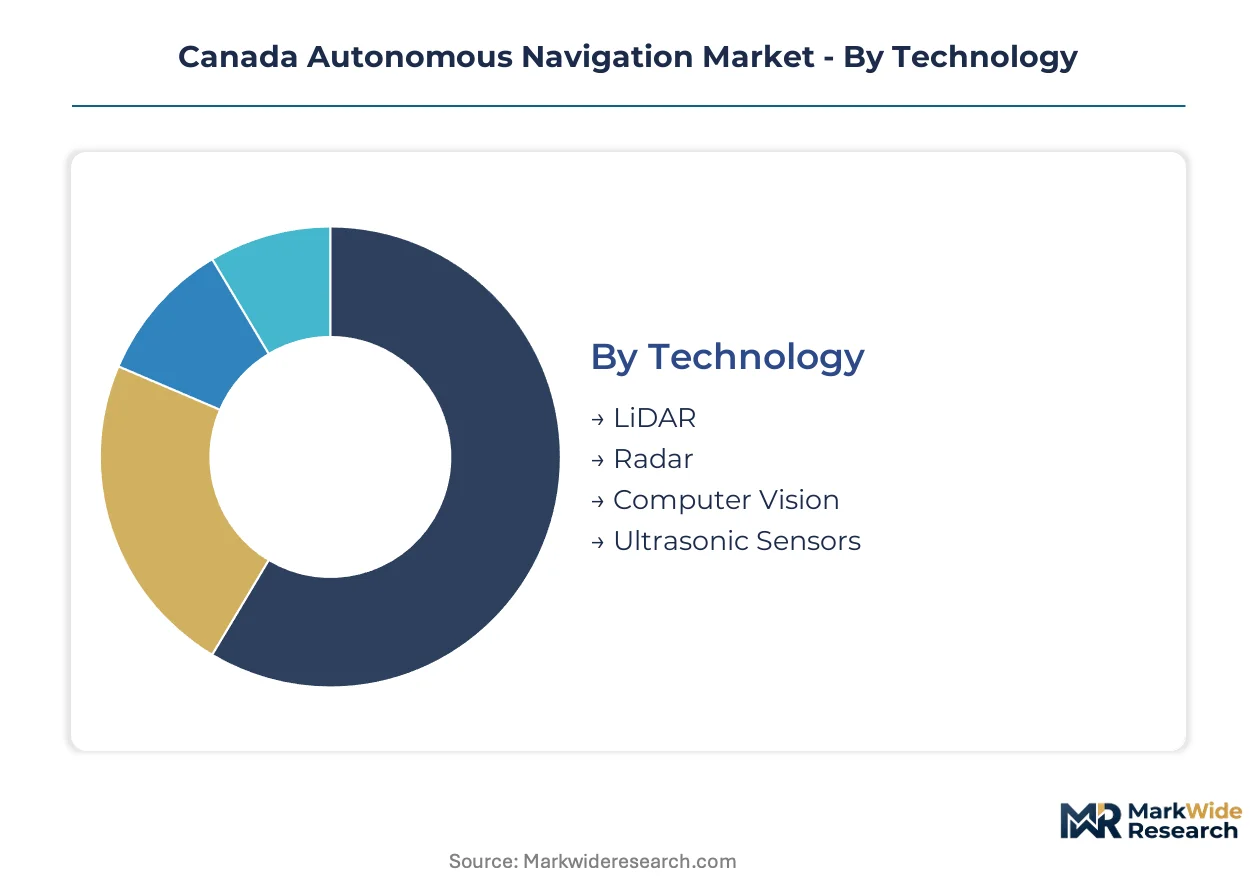
Autonomous navigation procurement in Canada fragments across sensor modalities, platform types, and operational architectures that each impose distinct certification requirements and supplier economics. Understanding these segment boundaries clarifies where Transport Canada regulations, Defence Research and Development Canada mandates, and commercial operator constraints create divergent competitive dynamics.
Technology:
Standardization dominates LiDAR and radar hardware interfaces, while computer vision architectures remain highly customized to platform-specific training datasets and inference pipelines.
- LiDAR:Dense 3D point-cloud generation through pulsed laser arrays achieves centimeter-scale localization accuracy for automated vehicle testing in Ontario's Toronto-Waterloo corridor. Transport Canada certification timelines for beyond-visual-line-of-sight operations favor LiDAR-equipped platforms in infrastructure inspection contracts.
- Computer Vision:Convolutional neural network inference at the edge processes camera feeds for real-time object classification in GPS-denied environments. Health Canada and PMRA coordination on agricultural drone pesticide dispersion protocols accelerates demand for vision-based navigation in precision farming applications across Saskatchewan and Manitoba.
- Radar:Robust all-weather sensing for maritime autonomous navigation serving Atlantic naval programs.
- Ultrasonic Sensors:Short-range obstacle detection for indoor robotics and warehouse automation deployments.
Leading the category by volume: Computer Vision. Growing fastest: LiDAR.
Application:
Defense procurement concentrates in ground robotics and marine vessels, while commercial momentum clusters around automated vehicles and drone platforms.
- Automated Vehicles:Sensor-fusion systems integrating LiDAR, radar, and vision enable SAE Level 4 testing on public roads under Ontario's automated vehicle pilot program. The Toronto-Waterloo technology corridor's automotive R&D clustering generates sustained demand for localization talent and component validation facilities.
- Drones:Beyond-visual-line-of-sight certification pathways unlock precision agriculture, mining survey, and linear infrastructure inspection across provincial jurisdictions. Transport Canada regulatory consolidation reduces timeline uncertainty for commercial operators seeking multi-provincial contracts.
- Robotics:Unmanned ground systems procurement under Strong, Secure, Engaged policy mandates.
- Marine Vessels:Autonomous navigation for contested electromagnetic environments in Atlantic naval programs.
Volume leadership sits with Automated Vehicles. Steepest expansion trajectory: Drones.
End User:
Defense contractors command premium pricing for sovereign capability requirements, while logistics providers drive standardization through fleet-scale procurement.
- Defense Contractors:Performance-based contracting tied to operational availability metrics displaces traditional cost-plus arrangements for unmanned systems. Ottawa engineering centers and Halifax-adjacent operations anchor Canadian Armed Forces robotics development with cleared personnel pipelines constraining supplier scaling.
- Transport Companies:Fleet decarbonization under the Canadian Net-Zero Emissions Accountability Act accelerates autonomous navigation procurement for electric platform integration in urban transit and intermodal corridors.
- Logistics Providers:Automated port and warehouse navigation for supply chain optimization.
- Research Institutions:Fundamental sensor-fusion algorithm development and training dataset curation.
Defense Contractors capture the highest per-unit value. Transport Companies are expanding contract volumes fastest.
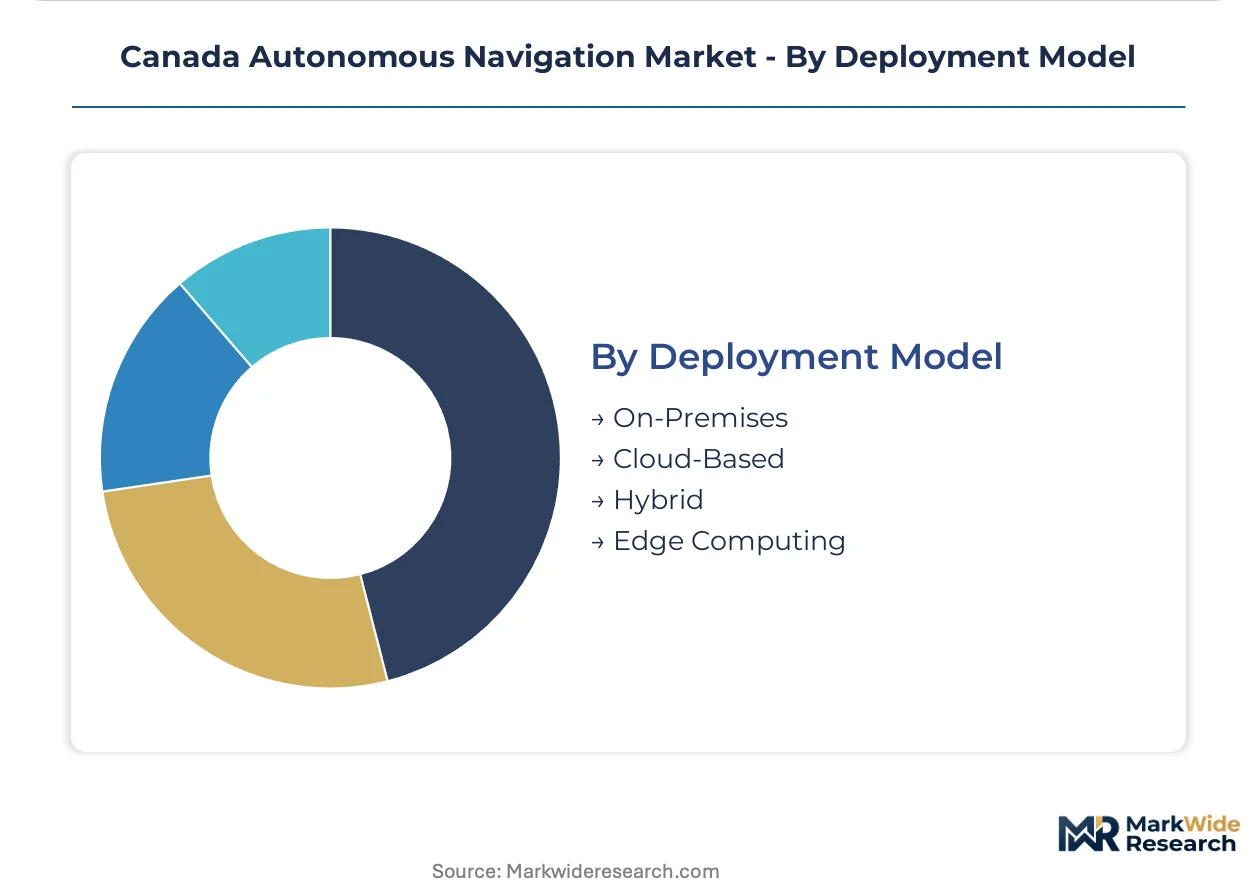
Deployment Model:
Edge computing dominates latency-critical defense applications, while hybrid architectures balance commercial fleet optimization with real-time vehicle autonomy.
- Hybrid:Split processing between vehicle-level localization and cloud-scale fleet coordination enables over-the-air map updates and route optimization for automated vehicle operators. The Canadian Radio-television and Telecommunications Commission vehicle-to-infrastructure spectrum allocation creates deployment friction for urban pilot programs.
- Edge Computing:Fully localized inference eliminates connectivity dependencies for underground mining operations in Quebec and British Columbia where GPS denial and bandwidth constraints prohibit cloud reliance.
- On-Premises:Isolated compute stacks for defense robotics with sovereign data residency requirements.
- Cloud-Based:Centralized training pipeline management and fleet telemetry aggregation for commercial drone service providers.
Hybrid deployments lead current installations. Edge Computing is gaining share fastest in resource extraction applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Toronto-Waterloo technology corridor anchors Canadian autonomous navigation development, concentrating sensor-fusion R&D, automotive testing facilities, and defense engineering centers within a 100-kilometer radius that generates disproportionate procurement activity relative to national population distribution.
Ontario
Automated vehicle testing under Ontario's pilot program drives LiDAR and computer vision validation demand. Transport Canada coordinates with the province on beyond-visual-line-of-sight certification pathways. The Toronto-Waterloo corridor's automotive R&D clustering sustains talent pipelines for sensor-fusion engineering.
Quebec
Underground mining operations in the Abitibi-Témiscamingue region require GPS-denied autonomous navigation for haulage and drilling equipment. The province's Ministry of Natural Resources and Forests regulates autonomous equipment deployment in subterranean environments. Montreal's aerospace engineering base feeds defense robotics development for Canadian Armed Forces programs.
British Columbia
Mountainous terrain and forestry applications create demand for radar-enhanced navigation in low-visibility conditions. WorkSafeBC oversees autonomous equipment safety protocols for resource extraction sites. Vancouver's port logistics sector pilots automated container handling with Transport Canada maritime certification support.
Atlantic Canada
Maritime autonomous navigation development concentrates around Halifax-adjacent operations serving naval programs in contested electromagnetic environments. Defence Research and Development Canada Atlantic Research Centre shapes sovereign capability requirements. The region's ocean technology cluster supports underwater vehicle autonomy for seabed mapping and pipeline inspection.
Prairie Provinces
Precision agriculture applications in Saskatchewan and Manitoba accelerate commercial drone adoption under Health Canada and PMRA pesticide dispersion protocols. Large-scale farming operations generate economies of scale for beyond-visual-line-of-sight service providers. Calgary's energy sector engineering base diversifies into autonomous systems for oil sands monitoring and pipeline surveillance.
Canada Autonomous Navigation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sovereign capability certification tiers, with cleared personnel requirements and defense security clearances creating structural separation between federal contractors and commercial operators. The vendor base organizes around three strategic archetypes: integrated defense primes with Ottawa engineering centers, maritime specialists anchored to Atlantic naval programs, and sensor-component suppliers feeding Toronto-Waterloo automotive testing clusters. Competitive moves concentrate on performance-based contracting displacement of cost-plus arrangements and modular subsystem procurement that enables prime contractors to swap component suppliers without redesigning localization pipelines.
Among defense-anchored primes, Lockheed Martin, L3Harris Technologies, and Northrop Grumman Corporation occupy positions shaped by Strong, Secure, Engaged policy procurement mandates. Lockheed Martin exemplifies the Ottawa-centric engineering center archetype sustaining Canadian Armed Forces robotics contracts. L3Harris Technologies represents the maritime specialization vector through Halifax-adjacent operations. Northrop Grumman Corporation sits within the tier of integrated primes pursuing sovereign sustainment capability requirements.
| Leading Market Players |
|---|
| Lockheed Martin |
| Northrop Grumman Corporation |
| L3Harris Technologies |
| General Dynamics Corporation |
| BAE Systems |
| Honeywell International |
| Raytheon Technologies Corporation |
| Safran |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Captive integration of sensor-fusion engineering talent within Ottawa defense engineering centers and Toronto-Waterloo automotive clusters anchors both supply security and pricing power for Canadian autonomous navigation vendors serving federal procurement and commercial testing programs.
Pricing Analysis
Operational availability metrics anchor value-based pricing for defense contractors serving Canadian Armed Forces programs under performance-based contracting arrangements. Three-tier pricing structure across sovereign-capability, dual-use, and commercial-off-the-shelf levels reflects cleared personnel requirements and certification grade differentiation. Cost compression in commercial drone tiers stems from LiDAR hardware commoditization pressures. Agricultural operators in Saskatchewan and Manitoba exhibit highest price sensitivity, while defense primes with Ottawa engineering centers command lowest elasticity due to sustainment capability mandates.
Supply Chain Analysis
Cleared personnel pipeline constraints in Canadian manufacturing geographies tether component sourcing for defense robotics to domestic engineering centers with security clearance infrastructure. LiDAR arrays draw from Taiwanese and South Korean optical component suppliers, while radar modules source from US and European defense electronics manufacturers. Single-source vulnerability concentrates in high-grade inertial measurement units for GPS-denied navigation. Distribution runs through prime contractor integration facilities in Ottawa and Halifax rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as Transport Canada certification timelines and Defence Research and Development Canada sovereign capability requirements force subscale commercial operators toward acquisition or exit.
For Market Incumbents: Deepen vertical integration into LiDAR-radar-vision sensor-fusion middleware to lock in modular subsystem procurement advantages against emerging software-defined navigation entrants. Expand Ottawa engineering center capacity to capture Strong, Secure, Engaged policy sustainment contracts displacing traditional cost-plus arrangements. For New Entrants and Emerging Players: Begin with Atlantic naval programs and underground mining applications in Quebec and British Columbia where sovereign capability requirements create protected procurement channels outside Ontario's saturated technology corridor. Target precision agriculture drone services in Saskatchewan and Manitoba where Health Canada and PMRA compliance complexity deters incumbent expansion. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime acquisition of modular sensor-fusion software specialists with Transport Canada certification track records and cleared personnel pipelines. Long-term viability favors targets with hybrid edge-cloud deployment expertise spanning both federal performance-based contracts and commercial fleet optimization. Watch Transport Canada beyond-visual-line-of-sight regulatory consolidation velocity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting Transition | Canadian Armed Forces procurement now ties vendor payments to operational availability metrics rather than hardware delivery. |
| Modular Sensor-Fusion Middleware Development | Standardized LiDAR-radar-vision interfaces enable prime contractors to swap component suppliers without redesigning localization pipelines. |
| Transport Canada Certification Acceleration | Integrated approval frameworks collapse sequential stages for beyond-visual-line-of-sight commercial drone operators. |
| Halifax-Adjacent Maritime Capability Expansion | Atlantic naval programs in contested electromagnetic environments offer uncrowded procurement channels outside Ontario's technology corridor. |
| Net-Zero Fleet Electrification Integration | Federal and provincial decarbonization mandates accelerate autonomous navigation procurement for electric platform integration. |
Research Methodology
Independent corroboration across primary interviews with defense procurement officers, commercial drone operators, automotive platform engineers, and sensor-component suppliers underwrites the qualitative findings. Secondary validation draws from Transport Canada regulatory filings, Canadian Armed Forces procurement disclosures, Defence Research and Development Canada technical reports, and Ontario automated vehicle pilot program documentation. Bottom-up segment sizing triangulates against top-down federal budget allocation analysis.
Rate-of-change decomposition across technology, application, end user, and deployment model dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level demand elasticity modeling calibrated to Transport Canada certification velocity and Strong, Secure, Engaged policy procurement patterns. Forecast inputs incorporate LiDAR cost curve trajectories and convolutional neural network edge deployment maturity curves.
Underlying measurement precision varies by segment; defense contractor and automated vehicle segments carry tighter precision than emerging agricultural drone applications. Forecasts reflect assumptions on regulatory timeline adherence and sovereign capability requirement stability. Material deviation in Transport Canada beyond-visual-line-of-sight certification velocity or Defence Research and Development Canada personnel clearance pipeline capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Automated Truck Technology Market