
 Autonomous Taxi Market | 2026-2036
Autonomous Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Taxi Market Analysis
The EU Green Deal's emissions benchmarks for urban transport fleets is consolidating procurement criteria across European municipal buyers. Waymo sustains technology leadership through its lidar-first sensor stack and extensive mapping infrastructure. Baidu dominates Beijing's regulatory sandbox deployments with government-backed testing permits. Tesla leverages its vertically integrated computer vision pipeline to reduce per-vehicle sensor costs.
An autonomous taxi is a self-driving vehicle classified at SAE Level 4 or Level 5 autonomy, operating without human intervention within predefined operational design domains using fused sensor arrays typically comprising lidar units, radar modules, and camera-based computer vision systems. Its primary commercial purpose is to deliver on-demand passenger mobility without a human driver, reducing per-mile operating costs and enabling continuous fleet utilization. Sedans and SUVs anchor current deployment volumes due to passenger capacity optimization and regulatory familiarity, while shuttle services represent the fastest-expanding service model as campuses and airport corridors adopt fixed-route automation. Lidar technology commands premium positioning in safety-critical urban environments, though computer vision is displacing multi-sensor stacks in cost-constrained fleet expansions.
The NHTSA in the United States, the MIIT in China, and the EU AI Act collectively shape vehicle-type approval, data governance, and cross-border operational permits for autonomous taxi services. NHTSA exemption processes determine fleet scale limits, while MIIT connectivity standards mandate V2X integration for public road access. Stakeholders must monitor which regulatory jurisdiction first harmonizes insurance liability frameworks with autonomous fault attribution, as this alignment will dictate geographic rollout sequencing and capital allocation priorities.
Market Dynamics
Fleet electrification mandates from the EU Green Deal and California's Advanced Clean Cars II are compressing powertrain transition timelines, forcing autonomous taxi operators to synchronize autonomy roadmaps with zero-emission vehicle procurement cycles.
Growth Catalysts
- V2X Infrastructure Deployment:China's MIIT connectivity standards mandate vehicle-to-everything integration for public road access, accelerating sensor fusion validation in dense urban corridors.
- Operational Design Domain Expansion:Regulatory sandboxes in Germany's KBA framework are permitting nighttime and inclement-weather testing, broadening revenue-generating hours per vehicle.
- Lidar Cost Curves:Solid-state lidar manufacturing scale-up is reducing per-unit sensor expenses below legacy mechanical systems, enabling multi-sensor redundancy in mass-market deployments.
Market Restraints
- LiDAR Supply Concentration:High-performance lidar emitters concentrate among Japanese and Israeli component specialists, creating single-source vulnerability for SAE Level 4 stacks.
- Insurance Liability Fragmentation:No jurisdiction has harmonized fault attribution between autonomous system manufacturers and fleet operators, freezing commercial scale-up.
- HD Mapping Capital Intensity:Sub-centimeter map maintenance requires continuous street-level data collection, locking smaller entrants out of geographic expansion.
Strategic Opportunities
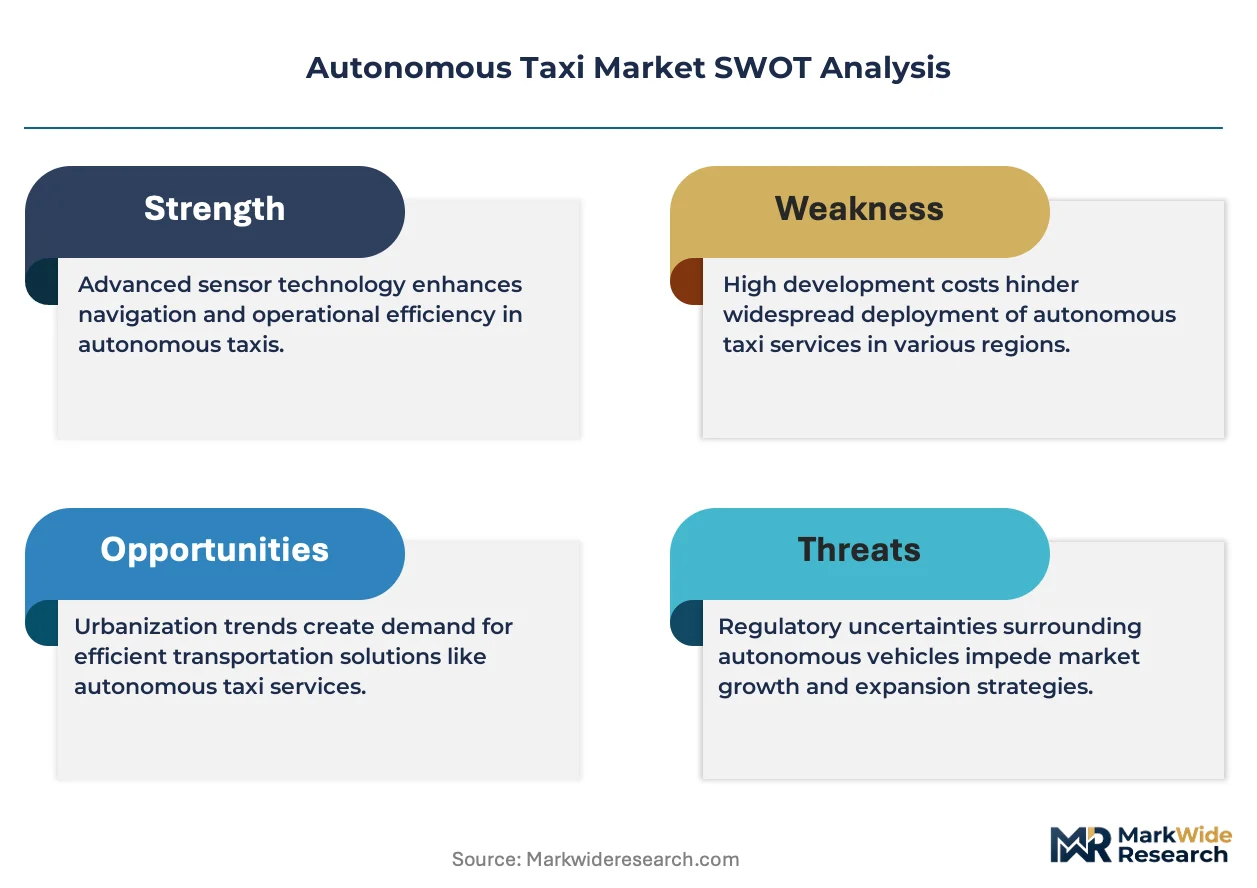
- Airport-Campus Shuttle Corridors:Fixed-route automation in controlled environments bypasses complex urban edge cases while generating operational data for broader ODD expansion.
- EU AI Act Compliance Services:Third-party algorithmic auditing and safety case documentation represent emerging revenue streams as type-approval requirements crystallize.
- Teleoperation Integration:Remote human oversight for edge-case disengagements is unifying fleet efficiency with regulatory comfort, opening suburban deployment zones previously restricted to fully uncrewed operation.
Industry Challenges
- Safety Engineer Scarcity:Functional safety certification under ISO 26262 requires specialized talent pools concentrated among automotive Tier-1 suppliers, constraining startup hiring velocity.
- Sensor Calibration Drift:Camera-lidar-radar fusion requires continuous recalibration across temperature and vibration cycles, complicating maintenance protocols for 24/7 fleet utilization targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Taxi Market |
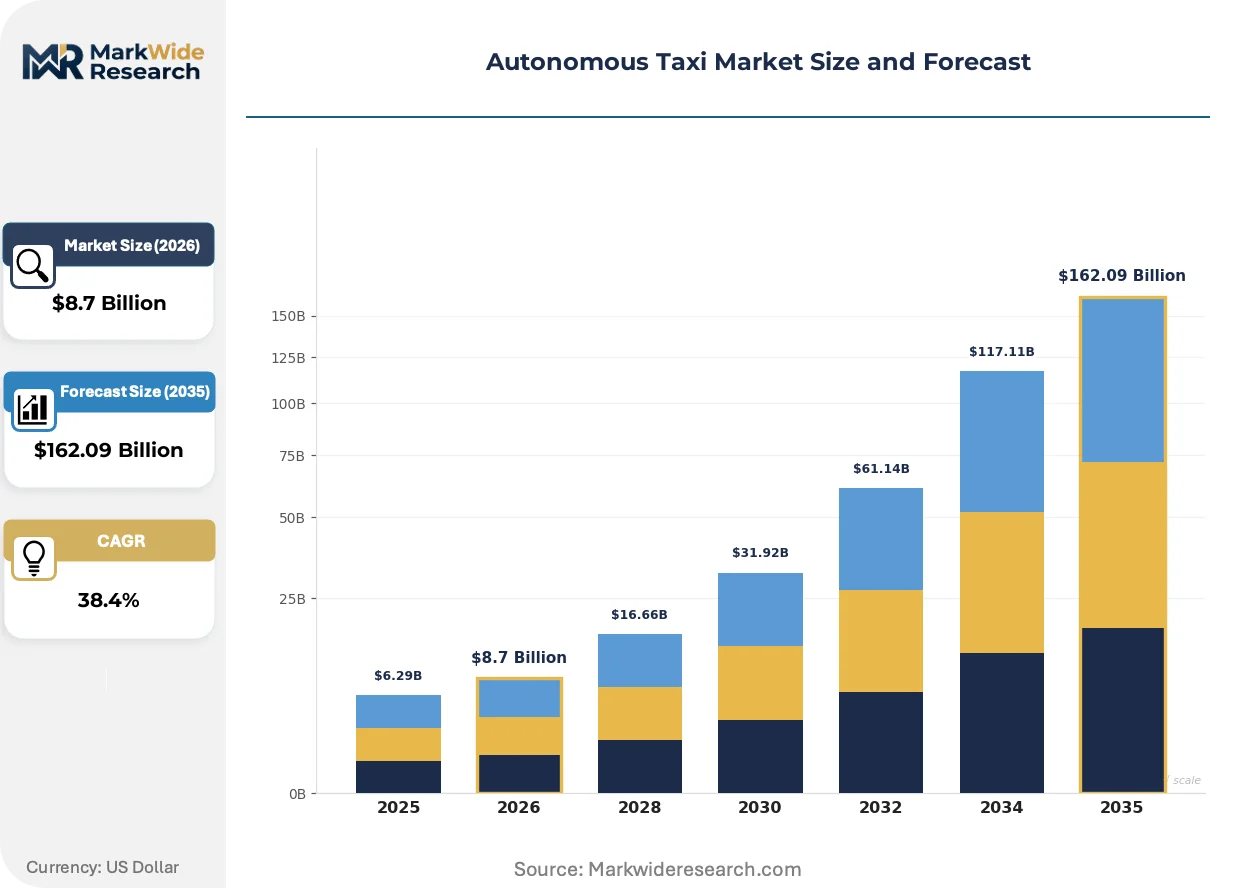
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $162.09 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedans, SUVs, Vans, Shuttles Technology: Lidar, Computer Vision, Machine Learning, Radar Service Model: Ride-Hailing, Carpooling, Shuttle Services, Delivery End User: Urban Commuters, Tourists, Corporate Clients, Delivery Services |
| Companies Covered | Uber Technologies, Zoox, Waymo, DiDi Chuxing, Baidu, Pony.ai, Tesla, Motional, WeRide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Taxi Market Emerging Trajectories
Sensor fusion architectures are compressing from multi-modality redundancy toward vision-first stacks, while regulatory frameworks coalesce around algorithmic transparency requirements. These shifts are redrawing competitive moats around data infrastructure and safety certification speed.
End-to-end neural networks are unifying perception, prediction, and planning into single-model architectures. Waymo and Baidu are deploying these systems in limited ODDs, reducing hand-engineered component count. This unifying approach is compressing development timelines and enabling faster geographic expansion, though it complicates regulatory explainability requirements under emerging AI Act mandates.
The EU AI Act's risk-classification framework for autonomous vehicles is mandating conformity assessments and post-market monitoring. Manufacturers must document training data provenance and model performance across demographic distributions. German and French regulators are piloting these protocols first, creating a compliance template that other European markets are adopting verbatim.
Fleet procurement is consolidating around mobility-as-a-service platforms rather than direct vehicle ownership. Municipal transit authorities and corporate campus operators are contracting for guaranteed availability per mile rather than capital expenditure. This shift is most visible in Singapore and Dubai, where government-backed fleet operators are structuring decade-long service agreements with autonomy providers.
Autonomous Taxi Market Segmentation
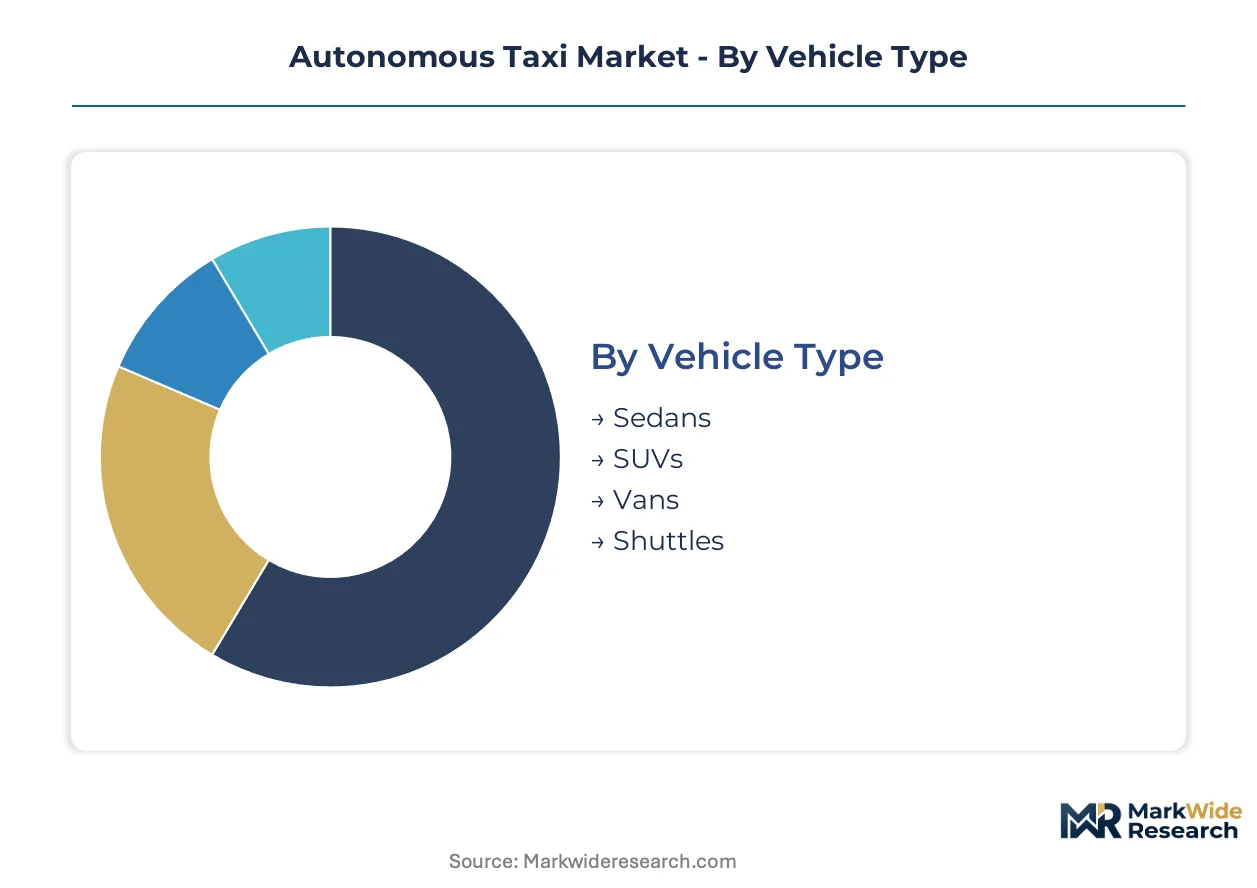
Autonomous taxi segmentation determines which vehicle configurations and technology stacks align with specific regulatory pathways. Certification requirements from NHTSA, KBA, and MIIT vary sharply across vehicle classes and sensor modalities, shaping operator procurement priorities.
Vehicle Type:
Sedans and SUVs carry heavier type-approval burdens under NHTSA exemption protocols, while shuttles navigate streamlined campus-specific certifications. Vans fall between these poles depending on passenger capacity thresholds.
- Sedans:Four-door passenger configurations dominate urban ride-hailing deployments. Demand concentrates in Phoenix and San Francisco where Waymo operates commercial fleets under NHTSA exemptions; sedan proportions reflect regulatory familiarity with traditional taxi formats.
- SUVs:Higher-ride-height platforms accommodate larger sensor arrays and battery packs. German operators prefer SUVs for KBA nighttime testing permits due to improved camera positioning and thermal management capacity.
- Vans:Wheelchair-accessible configurations serve municipal paratransit contracts. Accessibility mandates in California and European cities drive procurement specifications.
- Shuttles:Low-speed fixed-route vehicles bypass complex urban traffic scenarios. Airport and campus corridors in Singapore and Dubai generate concentrated orders.
Leading the category by volume: Sedans. Growing fastest: Shuttles.
Technology:
Technology choices split between multi-sensor redundancy for safety-critical urban environments and vision-first cost optimization for scaled fleet deployment. MIIT mandates V2X integration regardless of primary perception modality.
- Lidar:Solid-state and mechanical spinning units provide sub-centimeter ranging accuracy. Chinese deployments under MIIT standards require lidar for public road access in dense Shanghai and Beijing corridors.
- Computer Vision:Camera-based perception reduces hardware costs and maintenance complexity. Tesla's neural networks demonstrate viability in simplified operational design domains with lower regulatory scrutiny.
- Machine Learning:End-to-end neural architectures unify perception and planning. EU AI Act documentation requirements complicate deployment timelines for black-box models.
- Radar:Frequency-modulated continuous-wave sensors supplement primary perception in adverse weather. Automotive Tier-1 suppliers dominate component sourcing.
Widest deployment: Lidar. Steepest cost decline: Computer Vision.
Service Model:
Service models determine revenue structure and operational complexity. Ride-hailing requires dynamic routing algorithms; shuttles operate on fixed schedules with predictable maintenance windows.
- Ride-Hailing:On-demand point-to-point mobility generates per-mile revenue. Phoenix and San Francisco commercial zones demonstrate unit economics under NHTSA frameworks.
- Carpooling:Shared-ride configurations maximize vehicle utilization. Corporate campus contracts in Austin and Mountain View specify guaranteed-availability pricing.
- Shuttle Services:Fixed-route automation in controlled environments. Singapore's Punggol district and Dubai Expo corridors provide operational data for broader expansion.
- Delivery:Goods transport without passenger safety requirements. Pizza and grocery chains in Houston pilot last-mile configurations.
Highest revenue concentration: Ride-Hailing. Expanding most quickly: Shuttle Services.
End User:
End-user categories reflect trip purpose and payment authority. Corporate clients contract through procurement departments; tourists require multilingual interface standards.
- Urban Commuters:Daily work-trip passengers form the core addressable market. Beijing and Shenzhen regulatory sandboxes prioritize commuter corridor coverage.
- Tourists:Visitors demand predictable routing to landmarks and airports. Las Vegas and Orlando operators customize voice interfaces for international travelers.
- Corporate Clients:Enterprise contracts specify service-level agreements and data governance. German automotive suppliers negotiate dedicated campus fleets under KBA permits.
- Delivery Services:Logistics providers optimize for cargo capacity over passenger comfort. Meituan and JD.com deployments in Beijing prioritize thermal compartments.
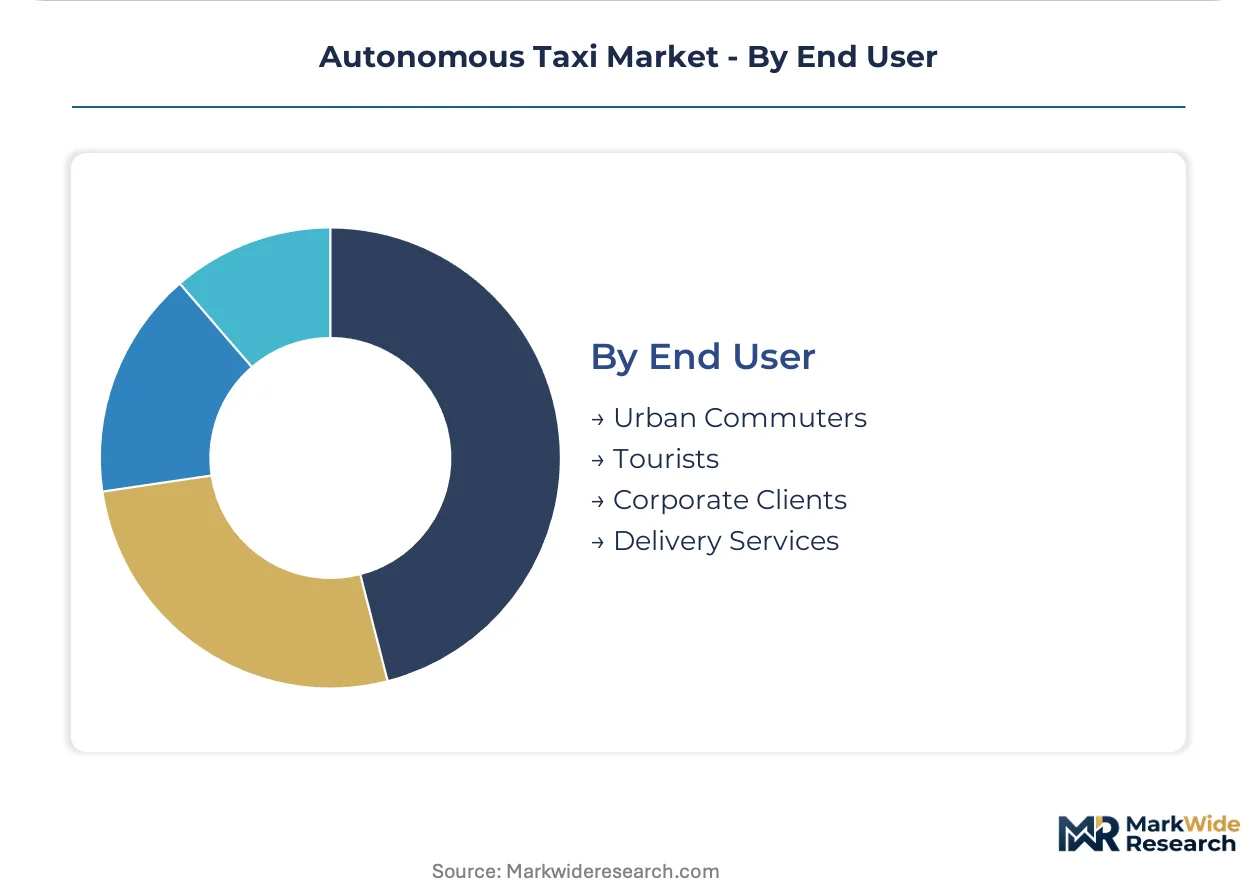
Largest contracted volume: Urban Commuters. Fastest contract growth: Corporate Clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phoenix anchors commercial deployment velocity with Waymo's expanded ride-hailing operations under NHTSA exemptions. Regulatory sandboxes in Beijing, San Francisco, and Berlin are compressing testing-to-commercialization timelines across three continents.
United States
California and Arizona host the densest operational fleets, with Phoenix and San Francisco generating continuous mileage data for safety validation. NHTSA exemption protocols limit fleet scale but permit revenue service in designated zones. The Bay Area's sensor engineering cluster supplies lidar and compute hardware to domestic operators.
China
Beijing and Shanghai concentrate government-backed testing permits under MIIT V2X connectivity mandates. Baidu and Pony.ai deploy in designated corridors with real-time traffic infrastructure integration. The Yangtze River Delta manufacturing base produces solid-state lidar and autonomous compute modules at scale.
Germany
Munich and Berlin host KBA regulatory pilots for nighttime and adverse-weather testing, expanding operational design domains beyond fair-weather limits. The EU AI Act's risk-classification framework is crystallizing conformity assessment templates here first. Baden-Württemberg's automotive supplier network feeds sensor calibration and functional safety expertise.
Singapore
The Punggol district and Changi Airport corridors generate fixed-route shuttle data for broader urban expansion. Government-backed fleet operators structure decade-long service agreements with autonomy providers. The city-state's compact geography enables rapid HD mapping coverage and V2X infrastructure deployment.
United Arab Emirates
Dubai's Expo corridors and downtown districts host commercial shuttle and ride-hailing pilots under MOHAP and municipal transport authority permits. The emirate's tourism concentration drives demand for predictable airport-to-hotel routing. NEOM's northwest development zone is planning autonomous mobility as foundational infrastructure.
Autonomous Taxi Market Vendor Landscape
The competitive structure tilts toward technology-stack differentiation over manufacturing scale. Consolidation pressures concentrate among sensor suppliers and mapping data providers rather than fleet operators. Two archetypes dominate: vertically integrated full-stack developers and modular component specialists. Dominant competitive moves include strategic partnerships for HD mapping access and geographic licensing agreements to bypass capital-intensive map-building.
Within the full-stack developer tier, Waymo, Baidu, and Tesla exemplify divergent sensor strategies. Waymo represents the multi-sensor redundancy archetype with extensive proprietary mapping infrastructure. Baidu occupies a position within government-coordinated regulatory sandboxes, leveraging state-backed testing permits. Tesla anchors the vision-first cost-optimization archetype, demonstrating viability in simplified operational domains. These three entities collectively illustrate how technology choices and regulatory relationships, rather than fleet size alone, determine competitive positioning.
| Leading Market Players |
|---|
| Uber Technologies |
| Zoox |
| Waymo |
| DiDi Chuxing |
| Baidu |
| Pony.ai |
| Tesla |
| Motional |
| WeRide |
| Others |
Supply Flow & Price Mechanics
Lidar sensor module price indices cascade through autonomous taxi manufacturing tiers, compressing hardware costs for vision-first stacks while solid-state mechanical premiums persist in safety-critical urban deployments. This commodity dynamic stratifies fleet procurement across premium multi-sensor redundancy, standard hybrid fusion, and economy camera-only configurations.
Pricing Analysis
Availability-based pricing anchors autonomous taxi service contracts, with municipal buyers contracting for guaranteed uptime per mile rather than capital expenditure. Price differentiation separates SAE Level 4 certified fleets from Level 2+ supervised alternatives, with certification tier commanding premiums in German KBA and Chinese MIIT jurisdictions. Cost compression in computer vision tiers is intensifying because Tesla's vertically integrated neural networks reduce per-vehicle sensor counts. Corporate campus operators exhibit highest price sensitivity, while airport authorities prioritize reliability guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and Israeli lidar emitter specialists, concentrating high-performance ranging components among fewer than five qualified suppliers. Manufacturing draws from China's Yangtze River Delta for solid-state lidar assembly, Germany's Baden-Württemberg for functional safety engineering, and Taiwan for autonomous compute silicon. Tariff exposure threatens cross-border component flows between US and Chinese technology tiers. Distribution runs through mobility-as-a-service platform aggregators rather than direct OEM procurement, with Singapore and Dubai government fleet operators consolidating decade-long service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous taxi market occupies a technology-transition phase, with end-to-end neural networks displacing hand-engineered perception stacks and reshaping competitive moats around data infrastructure rather than hardware scale.
For Market Incumbents: Anchor market position through proprietary HD mapping infrastructure that locks geographic expansion behind capital-intensive data collection. Invest in ISO 26262 functional safety certification velocity to constrain startup hiring pools. Defensive consolidation should target sensor calibration specialists, as temperature-drift maintenance protocols determine 24/7 fleet utilization economics. Threat substitution from vision-first cost optimization demands multi-sensor redundancy differentiation in safety-critical urban corridors. For New Entrants and Emerging Players: Airport-campus shuttle corridors represent the most penetrable white-space target, bypassing complex urban edge cases while generating operational data for broader ODD expansion. Fixed-route automation in controlled environments faces lower regulatory scrutiny than dynamic ride-hailing. Municipal paratransit contracts for wheelchair-accessible van configurations offer procurement pathways outside saturated Phoenix and San Francisco zones. Go-to-market positioning should emphasize teleoperation integration for suburban deployment zones previously restricted to fully uncrewed operation. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular component specialists with MIIT V2X compliance and EU AI Act documentation capabilities in German regulatory pilot zones. Long-term viability across the analysis window hinges on algorithmic transparency rather than black-box performance, favoring targets with post-market monitoring infrastructure. Signal to watch: which jurisdiction first harmonizes insurance liability frameworks with autonomous fault attribution, as this alignment will unlock commercial scale-up capital flows.| Strategic Initiative | Industry Significance |
|---|---|
| HD Mapping Partnership | Strategic licensing agreements bypass capital-intensive street-level data collection for geographic expansion. |
| V2X Infrastructure Integration | MIIT connectivity mandates in Beijing and Shanghai accelerate sensor fusion validation in dense urban corridors. |
| EU AI Act Compliance Investment | Third-party algorithmic auditing services capture emerging revenue as German KBA protocols crystallize. |
| Solid-State Lidar Manufacturing Scale-Up | Per-unit sensor cost reduction below mechanical systems enables multi-sensor redundancy in mass-market deployments. |
| Teleoperation Platform Development | Remote human oversight unifies fleet efficiency with regulatory comfort for suburban zone expansion. |
Methodological Framework
Document review covered NHTSA exemption filings, MIIT V2X connectivity standards, EU AI Act risk-classification frameworks, and KBA regulatory pilot protocols, complemented by interviews with autonomous fleet operators, Tier 1 sensor procurement leads, municipal transit authority planners, and mobility-as-a-service platform engineers. Secondary validation drew from automotive supplier SEC disclosures, vehicle production databases, and customs records for lidar component trade flows. Bottom-up fleet deployment counts triangulated against top-down market sizing across vehicle type, technology stack, and service model dimensions.
Market value outputs were generated through segmented demand modeling across sedans, SUVs, vans, and shuttles, with technology splits between lidar-first, vision-first, and hybrid fusion architectures. Service model differentiation captured ride-hailing, carpooling, shuttle, and delivery configurations. CAGR derivation incorporated fleet electrification mandate synchronization, regulatory sandbox expansion timelines, and sensor cost curve trajectories. Industry-specific inputs included NHTSA exemption fleet scale limits, MIIT public road access permits, and EU AI Act conformity assessment requirements.
Caveats apply where insurance liability framework harmonization delays, lidar supply concentration disruptions, or HD mapping capital intensity constraints could materially shift the outlook. Forecasts reflect documented assumptions about regulatory sandbox geographic expansion and V2X infrastructure deployment velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
Fully Autonomous Driving Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
In-Vehicle AI Robot Market