
 Asia-Pacific less-Than Container Load (LCL) Market | 2026-2036
Asia-Pacific less-Than Container Load (LCL) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific less-Than Container Load (LCL) Market Insights
Buyer concentration among e-commerce platforms and direct-to-consumer brands is expanding across Southeast Asia, fragmenting traditional importer profiles while creating volume anchors for consolidators. DHL Global Forwarding leverages its CFS network density to capture this shift. Kuehne+Nagel International sustains margin through pharmaceutical cold-chain LCL specialization. Kerry Logistics Network anchors intra-Asia lane control via its Greater China hub infrastructure.
Asia-Pacific less-Than Container Load (LCL) denotes maritime freight consolidation where multiple shippers share container space, typically involving cargo below twenty cubic meters or six metric tons, coordinated through container freight stations for stuffing and de-stuffing. The service enables cost-efficient ocean access for shipments lacking full-container economics, with transit times averaging seven to twenty-one days depending on lane and consolidation frequency. Door-to-Door service commands premium positioning as shippers absorb complexity, while CFS-to-CFS retains volume leadership among cost-sensitive manufacturing exporters. E-commerce Companies represent the fastest-growing customer type, forcing providers to compress booking-to-departure windows below forty-eight hours.
China's SAMR enforces freight forwarding licensing standards that filter market access, while Singapore's Maritime and Port Authority mandates digital manifest submission through its port community system. India's DGFT trade documentation requirements shape customs-bonded CFS operations, creating compliance differentiation among operators. Stakeholders must monitor how ASEAN single-window harmonization and carbon-border adjustment pilots reshape consolidation economics and lane selection criteria.
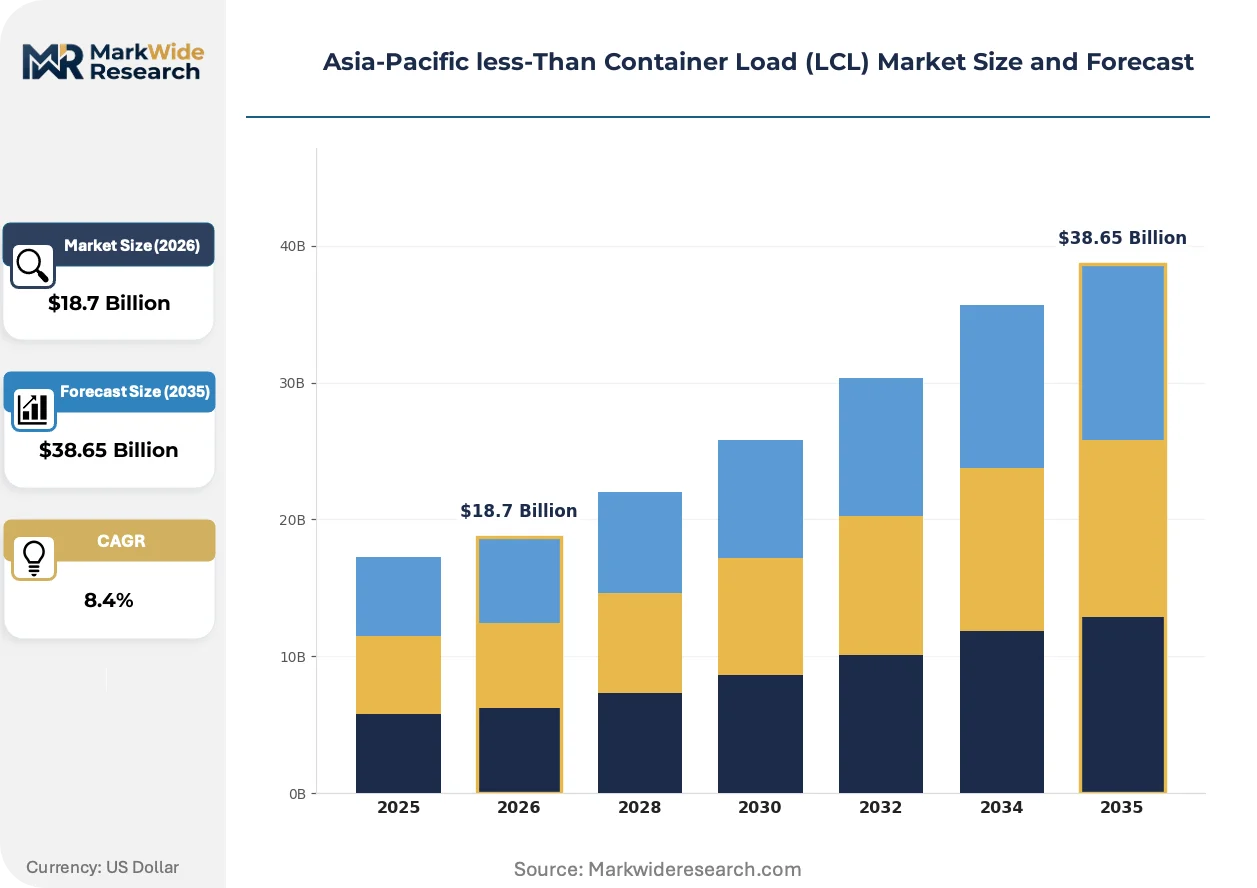
Market Dynamics
Consolidation frequency compression is restructuring Asia-Pacific LCL economics as e-commerce platforms demand sub-forty-eight-hour booking-to-departure windows, forcing container freight stations to reconfigure stuffing operations around velocity rather than pure cost optimization.
Growth Catalysts
- Singapore's Maritime and Port Authority digital manifest mandates:The port community system accelerates customs pre-clearance, reducing dwell times for Vietnam-origin electronics exports transiting through Singapore hub infrastructure.
- Pharmaceutical cold-chain specialization:India's DGFT trade documentation requirements for temperature-controlled exports create compliance premiums that specialized LCL operators capture in Mumbai and Hyderabad pharmaceutical corridors.
- Intra-Asia manufacturing relocation:Southeast Asian electronics assemblers in Vietnam and Indonesia are fragmenting sourcing across multiple component origins, multiplying consolidation points for regional feeder services.
Market Restraints
- Container equipment supply concentration:China's dual carbon goals and green port mandates restrict domestic chassis and reefer container availability, creating equipment access bottlenecks for non-Chinese consolidators.
- Fuel cost volatility in bunker-linked contracts:Low-sulfur fuel oil price swings transmit directly into LCL per-cubic-meter pricing, compressing margin predictability for fixed-rate contract portfolios.
- Substitution by express air freight:Time-critical e-commerce shipments below fifty kilograms increasingly bypass ocean consolidation entirely, capping LCL volume capture in high-velocity corridors.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical export hubs:Ahmedabad and Visakhapatnam lack bonded CFS density relative to Mumbai, creating first-mover positioning for temperature-controlled consolidation infrastructure.
- ASEAN single-window harmonization:Cross-border electronic documentation integration between Thailand, Vietnam, and Indonesia will compress multi-country consolidation cycle times and reduce customs-related detention.
- Blockchain-IoT convergence:Immutable container condition records combined with real-time reefer monitoring enable outcome-based cargo integrity guarantees that differentiate premium LCL service tiers.
Industry Challenges
- Digital platform integration complexity:Legacy freight forwarding operating systems require expensive API redevelopment to connect with e-commerce marketplace order management systems, straining mid-tier operator technology budgets.
- Reefer technician skill scarcity:Temperature-controlled container maintenance and pre-trip inspection expertise concentrates in Chinese and South Korean port clusters, creating service quality gaps in emerging Southeast Asian CFS locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific less-Than Container Load (LCL) Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Door-to-Door, Port-to-Port, CFS-to-CFS, Port-to-Door Customer Type: Small Businesses, E-commerce Companies, Retailers, Importers End User: Manufacturing, Retail, Healthcare, Consumer Goods Delivery Model: Direct Shipping, Consolidation, Deconsolidation, Intermodal |
| Companies Covered | DHL Global Forwarding, Kuehne+Nagel International, DSV, C.H. Robinson, Expeditors International of Washington, DB Schenker, Nippon Express, CEVA Logistics, Kerry Logistics Network, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific less-Than Container Load (LCL) Market Trends and Innovations
Velocity-based service design is displacing cost-centric consolidation models across Asia-Pacific lanes, with technology investments concentrating on booking automation and predictive container utilization rather than pure asset scale expansion.
Artificial intelligence-driven container stuffing optimization is consolidating demand forecasting with dynamic space allocation algorithms. E-commerce platforms and direct-to-consumer brands in Vietnam and Thailand are adopting these tools fastest, compressing the traditional weekly sailing cycle into bi-weekly or tri-weekly frequency on dense corridors. The technology is consolidating smaller forwarders into network-dependent partnerships rather than standalone operations.
China's SAMR freight forwarding licensing standards are tightening market access for cross-border operators, filtering out non-compliant intermediaries from Shanghai and Shenzhen consolidation corridors. The regulation elevates capital and compliance requirements for new entrants. Established operators with existing SAMR licenses are absorbing displaced volumes from delicensed competitors in Yangtze River Delta manufacturing zones.
Direct platform integration is replacing traditional email-and-phone booking workflows for SME shippers. E-commerce marketplace sellers in Indonesia and the Philippines now expect instant quoting embedded within their sourcing platforms, bypassing forwarder sales teams entirely. This behavioral shift is most visible in consumer electronics and fast-fashion verticals where order fragmentation and velocity requirements are highest.
Asia-Pacific less-Than Container Load (LCL) Market Segmentation
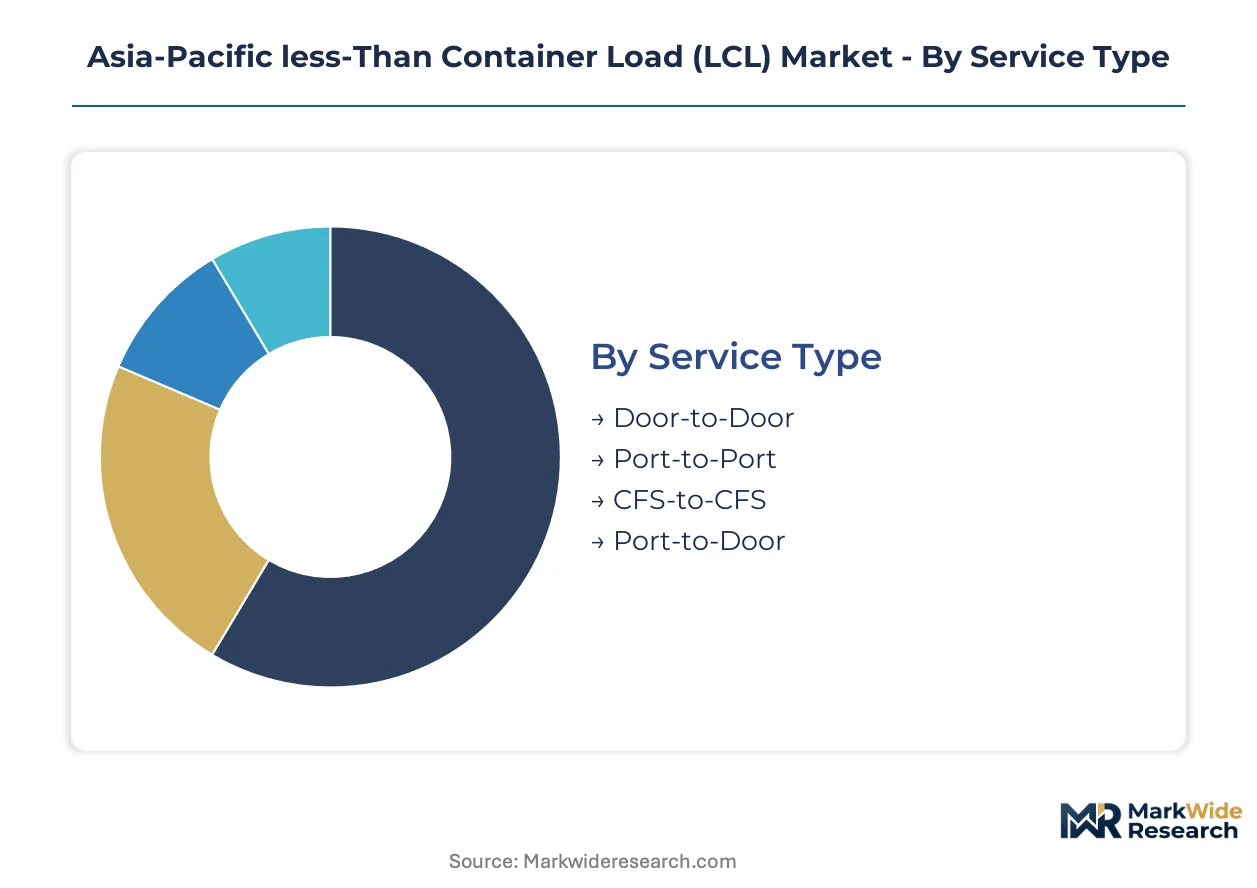
Segmentation in Asia-Pacific LCL reflects the tension between commodity consolidation and specialized service tiers. Shippers select across service types, customer profiles, end-use verticals, and delivery models based on cargo value density, compliance requirements, and velocity tolerance.
Service Type:
Standardization dominates commodity lanes while customization premiums concentrate in high-velocity corridors and regulated cargo categories.
- CFS-to-CFS:Container freight station-to-station service involves shipper delivery to origin CFS and consignee collection at destination CFS, with consolidators managing stuffing and de-stuffing operations. Cost-sensitive manufacturing exporters in Vietnam's electronics corridors and Indonesia's textile clusters anchor volume here, accepting longer transit times in exchange for per-cubic-meter rate minimization. The segment absorbs the highest shipment frequency across Asia-Pacific lanes.
- Door-to-Door:End-to-end managed service covers origin pickup through final delivery, with consolidators absorbing customs brokerage, inland haulage, and documentation complexity. E-commerce platforms and direct-to-consumer brands in Thailand and the Philippines absorb premium positioning here, demanding sub-forty-eight-hour booking-to-departure compression and real-time visibility integration.
- Port-to-Port:Traditional ocean leg-only service requires shippers to arrange pre-carriage and on-carriage independently. Mature trade lanes between Shanghai, Singapore, and Busan sustain this stripped-down option.
- Port-to-Door:Hybrid configuration covers ocean carriage plus destination inland delivery, appealing to importers with established origin logistics capabilities but fragmented destination distribution networks.
Leading the category by volume: CFS-to-CFS. Growing fastest: Door-to-Door.
Customer Type:
Volume concentration shifts toward digitally native shippers while legacy trade intermediaries retain lane density in established manufacturing corridors.
- E-commerce Companies:Online marketplace sellers and direct-to-consumer brands generate fragmented, high-velocity shipment profiles with compressed booking windows and embedded platform integration requirements. These shippers in Indonesia, Vietnam, and the Philippines are forcing consolidators to reconfigure CFS operations around velocity rather than pure cost optimization, with pharmaceutical and consumer electronics verticals showing highest platform adoption rates.
- Small Businesses:SME manufacturers and traders lack full-container economics and depend on LCL for ocean access, with cross-border sourcing expansion across Southeast Asia multiplying consolidation points for regional feeder services. These shippers prioritize rate predictability over service customization.
- Retailers:Brick-and-mortar and omnichannel retail chains manage seasonal inventory flows with moderate velocity tolerance, concentrating volume in pre-holiday windows.
- Importers:Traditional trading houses and procurement agents retain volume leadership in established lanes but face margin compression from platform-disintermediated alternatives.
Volume leadership sits with Small Businesses. Steepest expansion trajectory: E-commerce Companies.
End User:
Compliance intensity and cargo value density determine service tier selection across vertical applications.
- Manufacturing:Electronics assemblers in Vietnam, automotive component suppliers in Thailand, and machinery exporters across China's Yangtze River Delta generate base-load consolidation demand with moderate customization requirements. Fragmented sourcing across multiple component origins multiplies consolidation points for regional feeder services.
- Healthcare:Pharmaceutical and medical device shipments impose temperature-controlled handling, documentation rigor, and chain-of-custody requirements that create compliance premiums for specialized operators. India's DGFT trade documentation requirements shape customs-bonded CFS operations in Mumbai and Hyderabad corridors.
- Retail:Fashion and general merchandise flows concentrate in fast-fashion verticals with highest order fragmentation and velocity requirements.
- Consumer Goods:Electronics, appliances, and packaged goods sustain steady lane density with moderate service tier differentiation.
Manufacturing commands volume leadership. Healthcare shows fastest premium-tier expansion.
Delivery Model:
Asset intensity and network control vary sharply across execution approaches, with technology investments concentrating in coordination layers rather than pure asset scale.
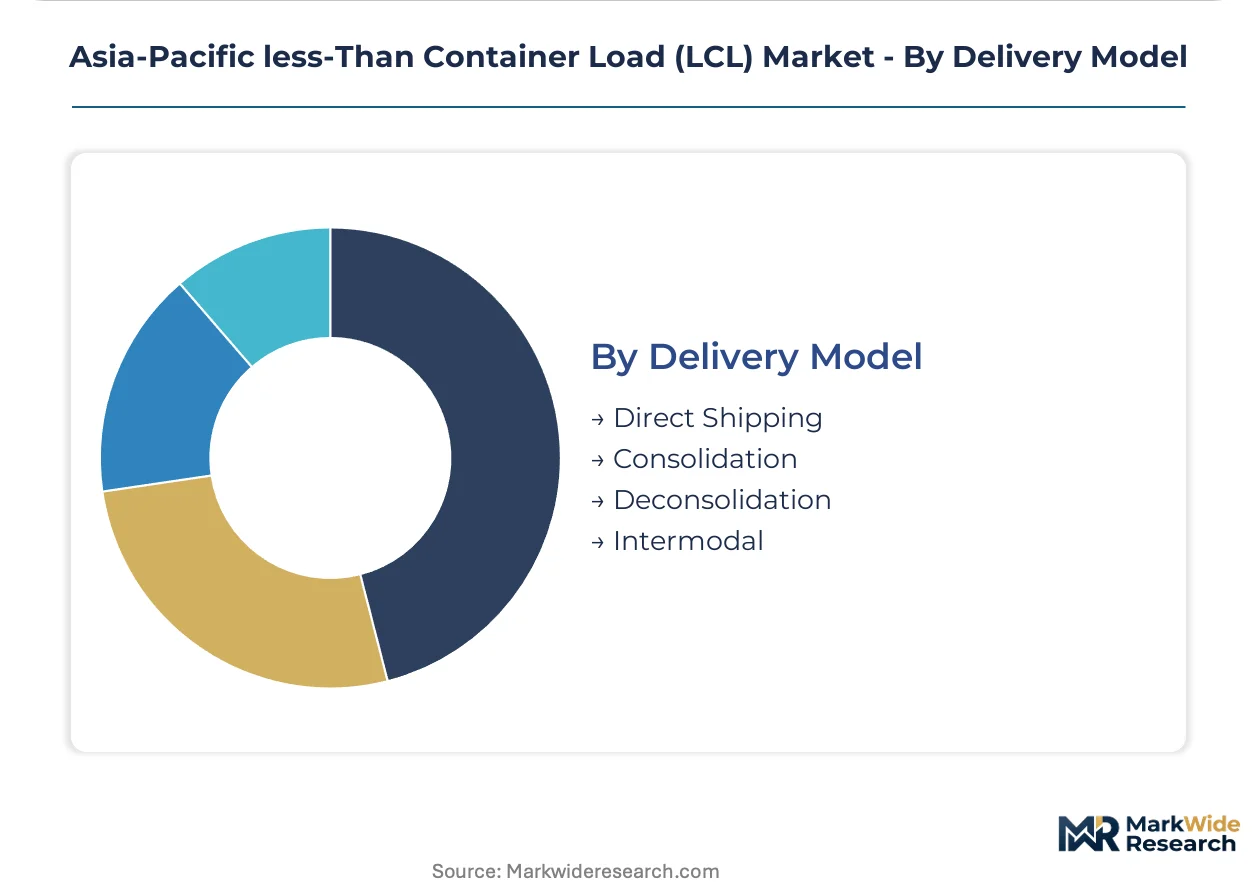
- Consolidation:Multi-shipment container stuffing at origin CFS enables cost-efficient space utilization, with artificial intelligence-driven optimization algorithms compressing traditional weekly sailing cycles into bi-weekly or tri-weekly frequency on dense corridors. E-commerce platforms in Vietnam and Thailand adopt these tools fastest.
- Direct Shipping:Dedicated container allocation bypasses consolidation delays for time-sensitive or high-value cargo, commanding rate premiums on lane pairs with sufficient volume density.
- Deconsolidation:Destination CFS break-bulk operations manage final-mile distribution complexity, with Singapore's Maritime and Port Authority digital manifest mandates accelerating customs pre-clearance.
- Intermodal:Rail-sea and barge-feeder combinations extend consolidation economics inland, particularly relevant for China's interior manufacturing zones and India's hinterland access.
Consolidation leads by shipment volume. Intermodal is gaining share fastest on cost-optimization priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consolidation demand concentrates in Vietnam's manufacturing corridors and India's pharmaceutical export hubs, with cross-border e-commerce expansion fragmenting traditional importer profiles across Southeast Asian markets.
China
Electronics assemblers in the Yangtze River Delta generate base-load consolidation demand with moderate customization requirements. SAMR freight forwarding licensing standards filter market access, elevating capital requirements for new entrants. Shanghai and Shenzhen consolidation corridors absorb displaced volumes from delicensed competitors.
Vietnam
Manufacturing relocation from China multiplies consolidation points for regional feeder services serving electronics and textile exporters. The country's trade documentation harmonization with ASEAN single-window protocols compresses customs clearance cycles. Ho Chi Minh City and Hanoi corridors anchor volume growth for intra-Asia lane operators.
India
Pharmaceutical cold-chain exports from Mumbai and Hyderabad create compliance premiums for specialized LCL operators. DGFT trade documentation requirements shape customs-bonded CFS operations, differentiating established temperature-controlled infrastructure providers. Ahmedabad and Visakhapatnam lack comparable bonded CFS density, creating positioning opportunities.
Singapore
Hub infrastructure for Vietnam-origin electronics transiting through Southeast Asia sustains consolidation economics. Maritime and Port Authority digital manifest mandates accelerate customs pre-clearance, reducing dwell times for transshipment cargo. The port community system integration anchors regional feeder service coordination.
Indonesia
E-commerce marketplace sellers in Jakarta and Surabaya force consolidators to compress booking-to-departure windows below forty-eight hours. Fragmented component sourcing across multiple origins multiplies consolidation points for textile and consumer electronics exporters. Platform integration requirements strain mid-tier operator technology budgets.
Asia-Pacific less-Than Container Load (LCL) Market Competitive Landscape
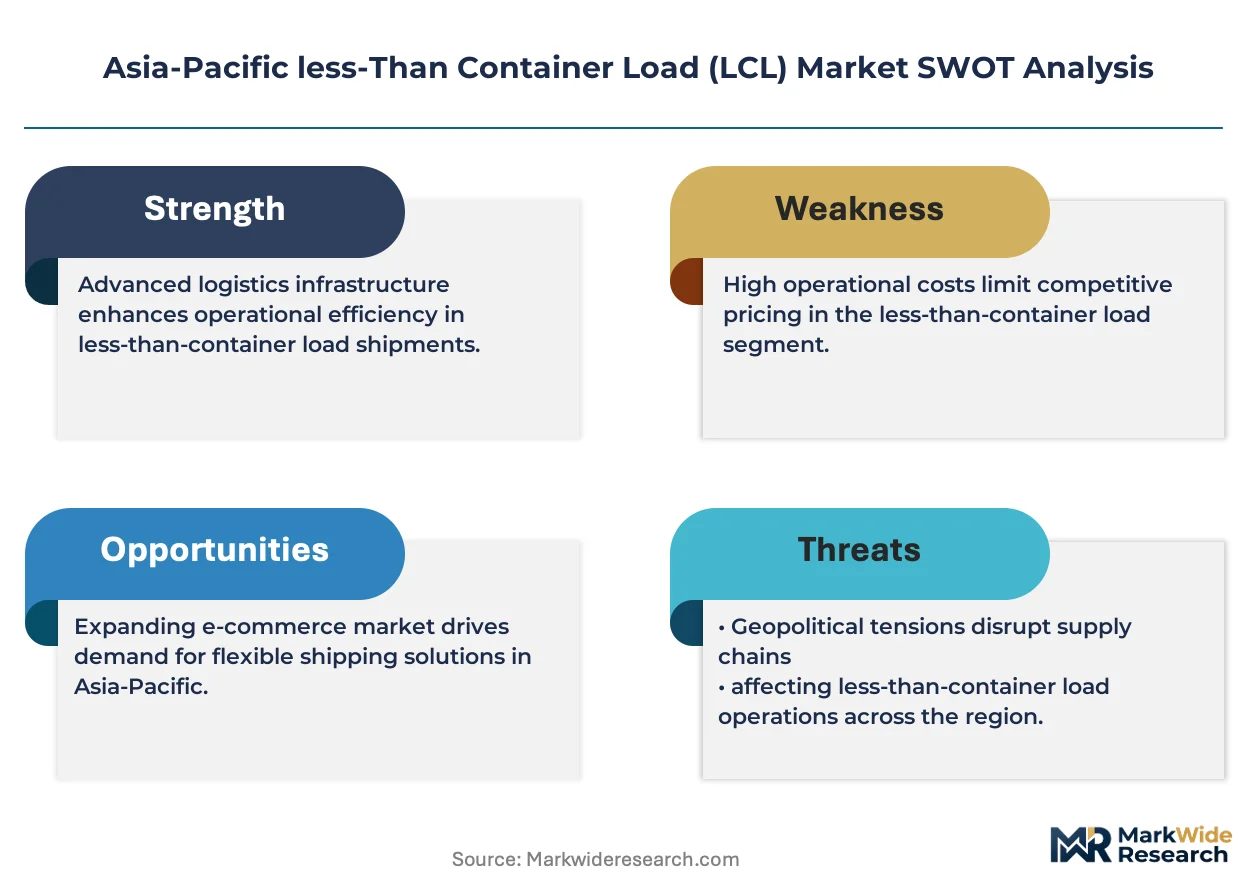
Established forwarders occupy the premium service tier; emerging digital platforms pursue SME market penetration through embedded quoting tools. The vendor base concentrates among multinational logistics networks with dense CFS infrastructure, while regional specialists defend niche corridors through pharmaceutical cold-chain certification. Three archetypes dominate: global integrators with end-to-end control, regional hub operators with intra-Asia lane density, and technology-enabled aggregators connecting fragmented shipper demand. Competitive moves center on API-based platform integration and AI-driven container stuffing optimization rather than pure asset expansion.
Within the global integrator tier, DHL Global Forwarding leverages CFS network density to capture e-commerce volume shifts, while Kuehne+Nagel International sustains margin through pharmaceutical cold-chain specialization. Kerry Logistics Network anchors intra-Asia lane control via its Greater China hub infrastructure. These three exemplify divergent strategic positions: technology-enabled scale, vertical specialization, and regional corridor dominance.
| Leading Market Players |
|---|
| DHL Global Forwarding |
| Kuehne+Nagel International |
| DSV |
| C.H. Robinson |
| Expeditors International of Washington |
| DB Schenker |
| Nippon Express |
| CEVA Logistics |
| Kerry Logistics Network |
| Others |
Pricing and Supply Chain Analysis
Bunker-linked fuel cost volatility transmits directly into per-cubic-meter LCL pricing, compressing margin predictability for fixed-rate contract portfolios while forcing shippers toward spot-market exposure or premium Door-to-Door service tiers that absorb complexity premiums.
Pricing Analysis
Volume leadership concentrates in CFS-to-CFS commodity lanes with thin margins, while Door-to-Door services capture premium positioning through velocity guarantees and customs brokerage bundling. Price differentiation hinges on consolidation frequency and cold-chain certification tier, with pharmaceutical cold-chain LCL commanding substantial premiums over standard dry cargo. Pricing pressure stems from express air freight substitution for sub-fifty-kilogram e-commerce shipments, eroding LCL volume capture in high-velocity corridors. Small businesses exhibit highest price sensitivity, accepting extended transit times for rate minimization, whereas e-commerce platforms absorb premium positioning for sub-forty-eight-hour booking-to-departure compression.
Supply Chain Analysis
Single-source vulnerability sits with Chinese container equipment manufacturers, where dual carbon goals and green port mandates restrict domestic chassis and reefer container availability, creating equipment access bottlenecks for non-Chinese consolidators. Manufacturing concentration spans China's Yangtze River Delta electronics clusters, Vietnam's textile and electronics corridors, and India's pharmaceutical export hubs in Mumbai and Hyderabad. Raw material dependencies include low-sulfur fuel oil for vessel operations, specialized reefer container units for temperature-controlled cargo, and bonded CFS infrastructure for customs-bonded consolidation. Supply chain risk centers on tariff exposure from carbon-border adjustment pilots reshaping lane economics. Distribution runs through Singapore's hub infrastructure for transshipment coordination and regional feeder service integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story, where China's SAMR freight forwarding licensing standards erect barrier-to-entry moats that filter non-compliant intermediaries and elevate capital requirements for new market access.
For Market Incumbents: Deploy API-based platform integration to capture e-commerce marketplace volume shifts, while expanding temperature-controlled CFS infrastructure in underpenetrated Indian pharmaceutical corridors. Consolidators must absorb displaced volumes from delicensed competitors in Shanghai and Shenzhen corridors, using established SAMR licenses as defensive positioning against emerging digital-native entrants.
For New Entrants and Emerging Players: Enter via specialized pharmaceutical cold-chain certification in Ahmedabad and Visakhapatnam, where bonded CFS density lags Mumbai and Hyderabad. Target ASEAN single-window harmonization corridors between Thailand, Vietnam, and Indonesia for cross-border electronic documentation integration. Pursue white-label technology partnerships with mid-tier forwarders lacking capital for legacy system redevelopment.
For Investors and Strategic Acquirers: Blockchain-IoT convergence in reefer monitoring is the leading indicator that outcome-based cargo integrity guarantees will differentiate premium service tiers and justify acquisition premiums for technology-enabled operators. Long-term viability favors consolidators with dense CFS networks and vertical specialization in pharmaceutical or e-commerce verticals. Monitor SAMR enforcement actions as signals of competitive displacement volume becoming available for compliant acquirers.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Container Stuffing Optimization | Vietnam and Thailand e-commerce platforms compress weekly sailing cycles into bi-weekly frequency through dynamic space allocation algorithms. |
| Pharmaceutical Cold-Chain CFS Expansion | Ahmedabad and Visakhapatnam infrastructure gaps create first-mover positioning for temperature-controlled consolidation in India's DGFT-regulated corridors. |
| API-Based Platform Integration | Indonesia and Philippines marketplace sellers demand instant quoting embedded within sourcing platforms, bypassing traditional forwarder sales teams. |
| Blockchain-IoT Reefer Monitoring | Immutable container condition records enable outcome-based cargo integrity guarantees that differentiate premium LCL service tiers. |
| ASEAN Single-Window Harmonization | Cross-border electronic documentation integration between Thailand, Vietnam, and Indonesia compresses multi-country consolidation cycle times. |
Research Methodology
Multi-period observation of consolidation frequency compression, e-commerce platform adoption rates, and SAMR licensing enforcement anchored the trend analysis, supplemented by interviews with container freight station operators, pharmaceutical export logistics managers, e-commerce marketplace supply chain leads, and maritime regulatory affairs specialists. Secondary validation drew from Singapore Maritime and Port Authority digital manifest filings, India DGFT trade documentation databases, China SAMR licensing registries, and ASEAN single-window protocol implementation trackers. Bottom-up shipment volume modeling triangulated against top-down carrier capacity disclosures.
Input-output matrices mapped service type, customer profile, end-use vertical, and delivery model segmentation dimensions across the projection horizon, with CAGRs derived from trend extrapolation of velocity-based service adoption and pharmaceutical cold-chain infrastructure deployment. Industry-specific forecast inputs included low-sulfur fuel oil price trajectory assumptions and reefer container equipment availability constraints under China's dual carbon mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon-border adjustment pilot expansion, express air freight rate wars, or ASEAN single-window implementation delays. Forecasts reflect documented assumptions about consolidation frequency compression sustaining and e-commerce platform integration requirements intensifying. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
ASEAN Domestic Courier Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Less-Than-Truckload Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Project Logistics Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
Nigeria Air Freight Market