
 Automotive Autonomous Shuttle Market | 2026-2036
Automotive Autonomous Shuttle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Autonomous Shuttle Market Outlook
Chinese manufacturing capacity for sensor-integrated vehicle platforms is broadening as domestic suppliers scale L4 automation hardware. Baidu leverages its Apollo autonomous driving stack to anchor deployment partnerships across Asian smart-city corridors. NVIDIA sustains high R&D intensity in edge-computing silicon for real-time shuttle perception. Yutong Bus dominates volume manufacturing of electric shuttle chassis purpose-built for autonomous retrofit.
An automotive autonomous shuttle is a self-guiding, electrically propelled passenger vehicle operating at SAE Level 4 autonomy or above, typically integrating LiDAR arrays, redundant braking systems, and V2X communication modules for fixed-route or geofenced service. Its primary commercial purpose is to replace conventional diesel transit on low-density routes where driver labor costs exceed vehicle capital expenditure. Compact shuttles currently occupy the largest installed base due to lower per-unit procurement thresholds for municipal buyers. High-capacity variants are registering the fastest order growth as airport and corporate campus operators consolidate multiple small-vehicle contracts into fewer large-unit deployments.
The National Highway Traffic Safety Administration in the United States sets crashworthiness and operational safety baselines that determine which shuttle designs gain federal deployment waivers. The European Union AI Act imposes risk-classification requirements on autonomous decision systems, directly affecting LiDAR-to-steering control validation protocols for EU market entry. Stakeholders must monitor how fragmented national liability frameworks for driverless passenger injury will reshape insurance underwriting and fleet procurement timelines.
Market Dynamics
Fixed-route electrification mandates are compressing procurement timelines for municipal transit authorities, forcing parallel validation of autonomous platforms alongside conventional electric bus replacements.
Growth Catalysts
- EU AI Act risk-classification framework:The regulation creates explicit validation pathways for LiDAR-to-steering control systems, reducing regulatory uncertainty for shuttle operators seeking EU market entry.
- Campus last-mile connectivity:University and corporate campus operators in the United States are consolidating pilot programs into permanent procurement frameworks, establishing recurring revenue baselines for fleet suppliers.
- Sensor-integrated chassis manufacturing:Chinese domestic suppliers are scaling L4 automation hardware production, lowering per-unit sensor procurement costs for shuttle retrofitters.
Market Restraints
- LiDAR supply concentration:Solid-state LiDAR manufacturing remains concentrated among a limited supplier base in Asia, creating input cost volatility for shuttle integrators.
- NHTSA deployment waiver timelines:Federal crashworthiness baseline approvals for novel shuttle designs require 18-24 month review cycles, compressing fleet launch schedules.
- Fixed-route service substitution:Micromobility services and conventional electric minibuses compete directly for low-density route contracts, capping price premiums for autonomous capability.
Strategic Opportunities
- Airport ground transport consolidation:Terminal operators are replacing multiple small-vehicle contracts with fewer high-capacity autonomous shuttles, creating demand for 20+ passenger platforms.
- German regulatory sandboxes:Berlin and Hamburg testing corridors provide real-world validation environments that accelerate certification for broader EU deployment.
- V2X infrastructure convergence:Integration of vehicle-to-everything communication modules with smart-city traffic management systems is opening municipal procurement channels previously closed to autonomous platforms.
Industry Challenges
- Autonomous systems engineering talent:The shortage of validation engineers with combined expertise in functional safety and machine learning perception is extending development timelines.
- Multi-jurisdiction liability fragmentation:Inconsistent national frameworks for driverless passenger injury allocation are forcing shuttle operators to maintain redundant insurance coverage across operating territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Autonomous Shuttle Market |
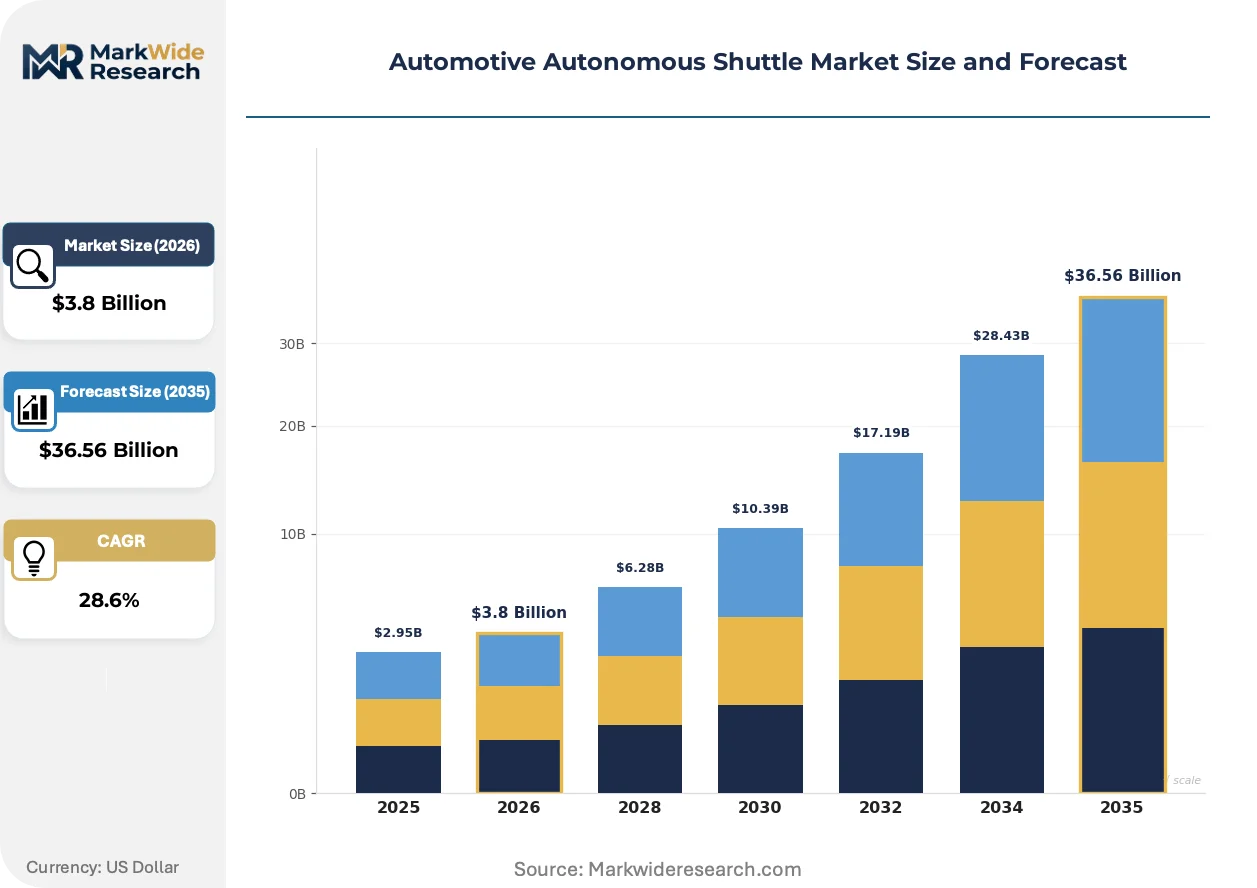
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Shuttle, High-Capacity Shuttle, Luxury Shuttle, Modular Shuttle Technology: LiDAR, Computer Vision, Radar, Ultrasonic Sensors End User: Public Transport, Corporate Shuttle, Campus Transport, Emergency Services Deployment: Urban Area, Suburban Area, Campus Environment, Industrial Zone |
| Companies Covered | EasyMile, NAVYA, Aptiv Inc., Robert Bosch GmbH, Continental AG, ZF Friedrichshafen, Baidu, Yutong Bus, NVIDIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Autonomous Shuttle Market Strategic Shifts
Edge-computing architectures are compressing perception-to-actuation latency windows, enabling real-time decision-making without persistent cloud connectivity. This shift is reshaping hardware procurement priorities across the shuttle value chain.
LiDAR sensor fusion with camera-based perception stacks is decentralizing computational load from centralized vehicle controllers to distributed edge nodes. Airport operators are adopting these architectures first, driven by zero-tolerance requirements for tunnel and covered-terminal navigation. The structural consequence is compressing supplier margins on traditional centralized computing hardware.
The EU AI Act imposes mandatory conformity assessments on autonomous decision systems classified as high-risk, directly affecting validation protocols for steering and braking control algorithms. Manufacturers must now document training data provenance and model drift monitoring. German shuttle pilots are responding by front-loading documentation investment to secure faster MDR alignment.
Campus procurement officers are unbundling vehicle acquisition from operational service contracts, separating capital expenditure from fleet management liability. This bifurcation is displacing traditional turnkey vendors with specialized autonomous operations companies. The pattern is most visible in United States university systems, where transportation departments now contract distinct entities for platform supply and passenger service delivery.
Automotive Autonomous Shuttle Market Segmentation
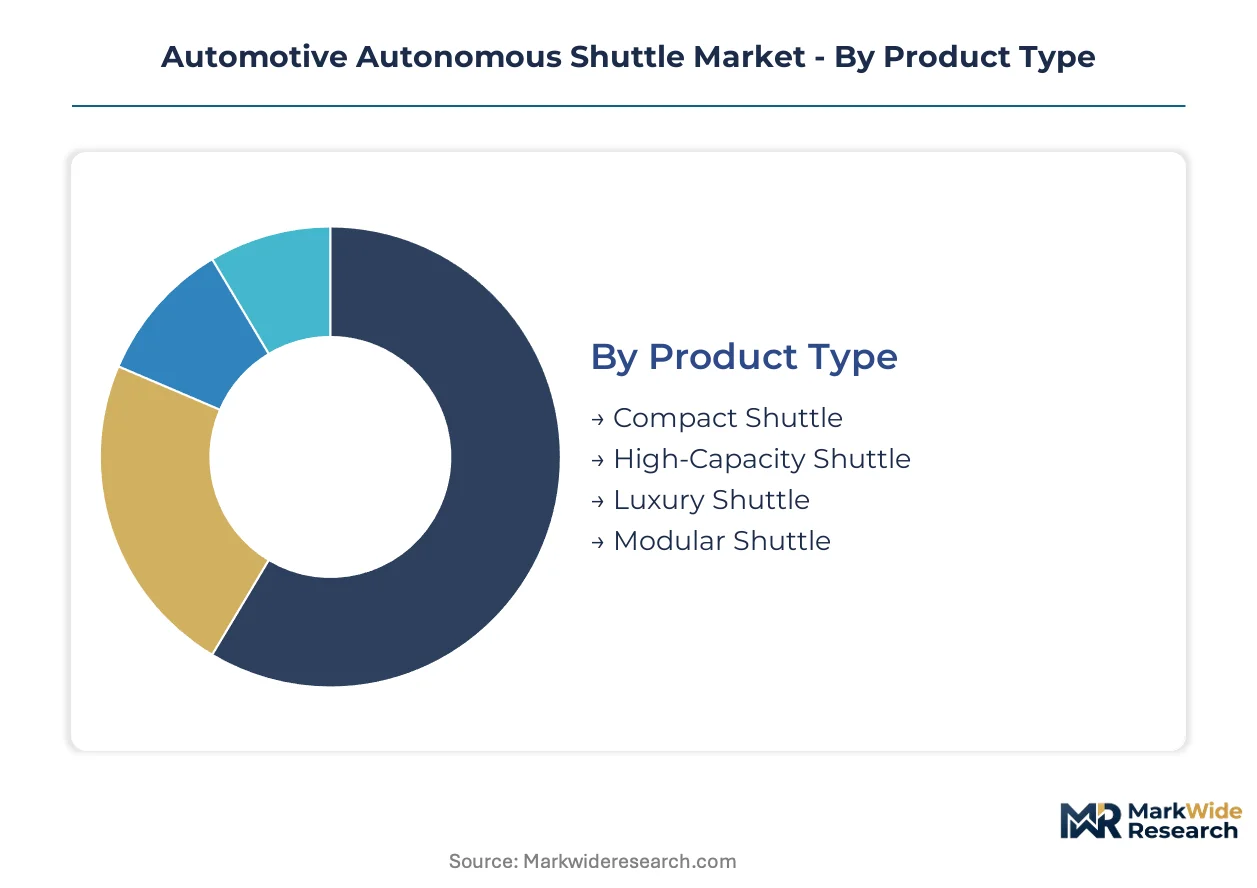
Segmentation in the automotive autonomous shuttle market reveals distinct procurement patterns across vehicle scale, sensor architecture, and operational environment. Municipal buyers prioritize capital efficiency in fleet specifications, while private operators emphasize passenger throughput and service differentiation.
Product Type:
Capital intensity varies sharply across shuttle configurations, with per-unit procurement thresholds ranging from compact retrofit platforms to purpose-built high-capacity chassis requiring dedicated manufacturing lines.
- Compact Shuttle:These 8-12 passenger vehicles utilize standardized electric skateboard platforms with modular sensor pods. Campus transport operators in the United States favor compact units for pilot-to-permanent fleet transitions where route density remains uncertain.
- High-Capacity Shuttle:Purpose-built 20+ passenger platforms consolidate multiple small-vehicle contracts into single-unit deployments. Airport ground transport operators in Germany are driving order growth for high-capacity variants as terminal operators seek to reduce fleet complexity.
- Luxury Shuttle:Premium interior specifications with executive seating configurations target corporate shuttle contracts. The segment commands elevated per-unit pricing but occupies limited installed base.
- Modular Shuttle:Swappable passenger and cargo configurations enable daytime transit and nighttime logistics service. European smart-city pilots are testing modular architectures for multi-use fleet economics.
Most installed capacity flows through Compact Shuttle platforms. Expansion is steepest in High-Capacity Shuttle configurations.
Technology:
Sensor procurement costs concentrate heavily in optical perception stacks, with LiDAR arrays representing the dominant hardware expenditure line in shuttle bill-of-materials.
- LiDAR:Solid-state and mechanical spinning arrays generate 3D point clouds for centimeter-level localization. The EU AI Act mandates documented training data provenance for LiDAR-to-steering control systems, extending validation timelines for European market entry.
- Computer Vision:Camera-based perception stacks leverage convolutional neural networks for object classification. Chinese domestic suppliers are scaling production of automotive-grade image sensors, compressing input costs for shuttle integrators.
- Radar:Frequency-modulated continuous-wave sensors provide velocity measurement and all-weather redundancy. Radar units occupy lower cost tier but deliver inferior spatial resolution versus optical alternatives.
- Ultrasonic Sensors:Short-range proximity detection for low-speed maneuvering and parking assistance. Ultrasonic arrays function as supplementary safety layers rather than primary perception modalities.
LiDAR dominates current procurement expenditure. Computer Vision is climbing the fastest as edge-computing architectures enable camera-first perception strategies.
End User:
Customer type determines liability frameworks and operational service models, with public authorities facing distinct certification requirements versus private campus operators.
- Public Transport:Municipal transit authorities operate under NHTSA deployment waivers in the United States and EU AI Act risk-classification frameworks. Fixed-route electrification mandates are compressing procurement timelines for autonomous platform validation.
- Corporate Shuttle:Private employers contract distinct entities for platform supply and passenger service delivery. United States technology campuses are unbundling vehicle acquisition from fleet management liability.
- Campus Transport:University systems prioritize last-mile connectivity with lower speed and geofenced operational domains. German regulatory sandboxes in Berlin and Hamburg accelerate real-world testing for campus operators.
- Emergency Services:Specialized autonomous platforms for medical supply and evacuation scenarios. The segment remains nascent with limited deployed units.
Public Transport accounts for the largest committed fleet volumes. Corporate Shuttle procurement is expanding most quickly as private operators consolidate pilot programs.
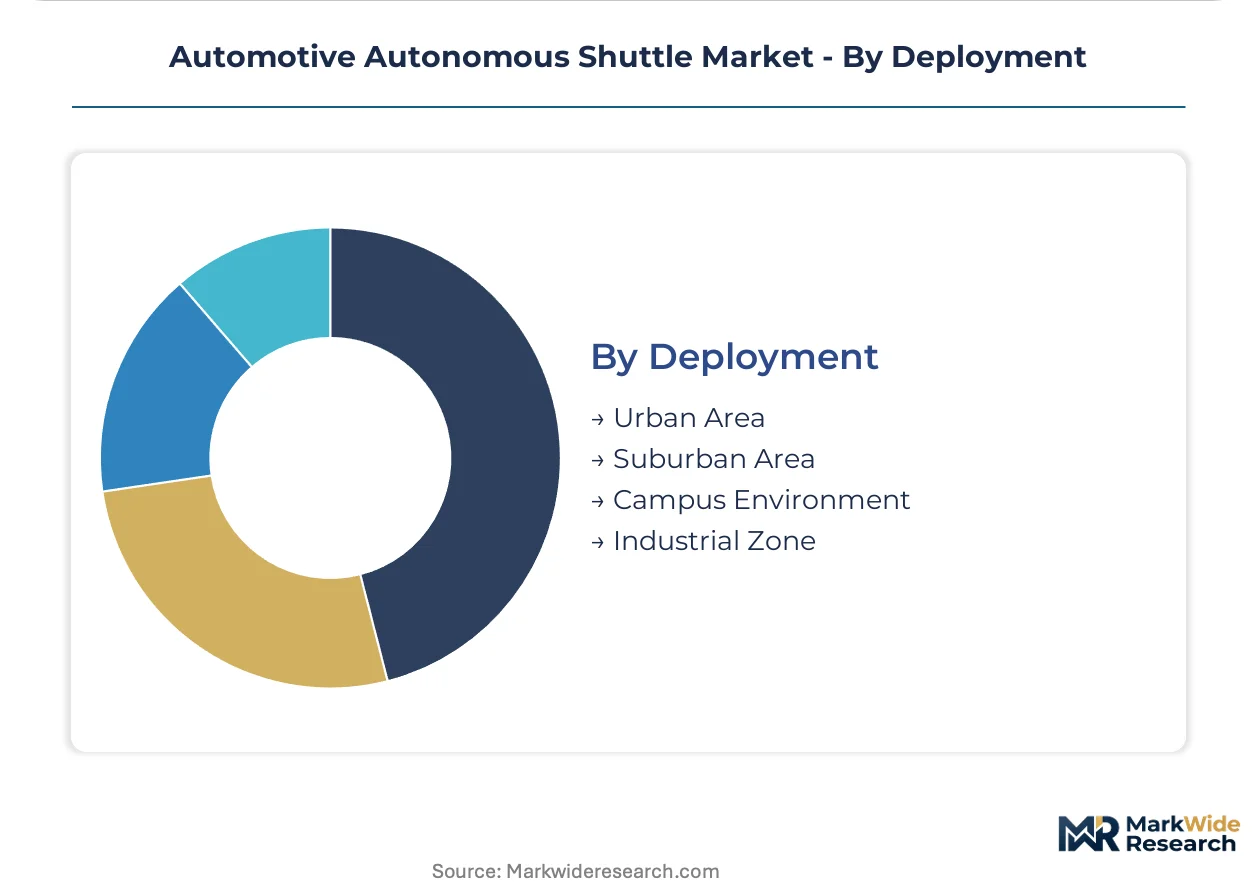
Deployment:
Operating environment shapes sensor redundancy requirements and V2X infrastructure dependencies, with covered terminals demanding superior localization versus open-road suburban corridors.
- Urban Area:Dense traffic interaction with mixed pedestrian and cyclist populations requires highest sensor fusion density. Smart-city traffic management integration opens municipal procurement channels previously closed to autonomous platforms.
- Suburban Area:Lower traffic density with higher operating speeds shifts perception priorities toward long-range detection. Suburban deployments face competition from conventional electric minibuses on cost-per-passenger metrics.
- Campus Environment:Controlled access roads with predictable pedestrian patterns enable reduced sensor configurations. Campus operators leverage geofenced domains to accelerate regulatory approval timelines.
- Industrial Zone:Private road networks with limited mixed traffic enable simplified operational design domains. Industrial deployments prioritize cargo-modular shuttle configurations over passenger service.
Campus Environment hosts the most validated operational kilometers. Urban Area deployment is gaining share fastest as V2X infrastructure converges with traffic management systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys regulatory sandboxes for real-world validation while the United States relies on federal waiver timelines that compress fleet launch schedules. China scales manufacturing capacity for sensor-integrated platforms. France and Japan concentrate on specific deployment environments with distinct infrastructure requirements.
United States
Campus transport operators consolidate pilot programs into permanent procurement frameworks across university systems. The NHTSA maintains 18-24 month deployment waiver review cycles for novel shuttle designs. Greater Boston and the San Francisco Bay Area concentrate operational testing for last-mile connectivity corridors.
Germany
Airport ground transport operators drive order growth for high-capacity autonomous platforms. The EU AI Act imposes mandatory conformity assessments on LiDAR-to-steering control systems. Berlin and Hamburg testing corridors provide real-world validation environments that accelerate certification timelines.
China
Domestic suppliers scale L4 automation hardware production for sensor-integrated vehicle platforms. MIIT frameworks govern intelligent connected vehicle testing and commercial deployment permissions. Shenzhen and Beijing smart-city corridors anchor deployment partnerships for fixed-route autonomous services.
France
Municipal transit authorities compress procurement timelines under fixed-route electrification mandates. ANSM and CNIL guidance intersects with EU AI Act risk-classification for passenger safety systems. Lyon and Paris metropolitan pilots validate geofenced autonomous operations in dense urban environments.
Japan
Corporate campus operators prioritize passenger throughput in consolidated fleet contracts. METI programs support autonomous mobility service demonstrations in designated special zones. Tokyo and Osaka metropolitan clusters test edge-computing architectures for covered-terminal navigation requirements.
Automotive Autonomous Shuttle Market Competitive Environment
Chinese producers anchor manufacturing scale; European specialists hold regulatory validation expertise. The vendor base organizes around tiered capability sets rather than consolidated market share. Three archetypes dominate: sensor-integrated chassis fabricators, autonomous driving stack providers, and fleet operations specialists. Competitive moves concentrate on strategic partnerships for V2X infrastructure integration and backward integration into solid-state LiDAR supply.
Within the autonomous driving stack tier, Baidu represents the integrated platform model while NVIDIA exemplifies edge-computing silicon specialization. Yutong Bus anchors volume manufacturing of electric shuttle chassis purpose-built for autonomous retrofit among Chinese fabricators. EasyMile and NAVYA occupy positions as European deployment specialists focused on fixed-route validation.
| Leading Market Players |
|---|
| EasyMile |
| NAVYA |
| Aptiv Inc. |
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen |
| Baidu |
| Yutong Bus |
| NVIDIA |
| Others |
Value Chain & Pricing Dynamics
Captive sensor integration by Chinese chassis fabricators anchors both supply security and pricing leverage for shuttle OEMs. This backward integration choice insulates tier-one suppliers from LiDAR spot-market volatility while compressing margins for non-integrated Western retrofitters competing on open-procurement sensor stacks.
Pricing Analysis
Capacity additions in China are reshaping price floors for solid-state LiDAR arrays and edge-computing silicon. Shuttle procurement stratifies across premium certified, standard validated, and economy pilot-tier configurations, with EU AI Act conformity assessment costs widening spreads between tiers. Price erosion runs through economy-tier compact shuttles as domestic Chinese suppliers flood campus transport tenders. Municipal transit authorities in Germany exhibit highest price sensitivity due to fixed-route electrification budget constraints, while airport operators in Japan absorb premium pricing for zero-failure covered-terminal specifications.
Supply Chain Analysis
Domestic-content mandates under China's MIIT intelligent connected vehicle framework are reshaping sourcing patterns for foreign shuttle integrators. Solid-state LiDAR production concentrates in China, South Korea, and Japan, while automotive-grade edge-computing silicon draws from Taiwan and the United States. Bill-of-materials hinges on rare-earth magnet supply for electric drivetrains and specialized photonics substrates for LiDAR emitters. Single-source vulnerability in solid-state LiDAR MEMS fabrication creates chokepoint exposure. Distribution runs through tier-one automotive supplier networks with direct OEM contracting for high-volume campus fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as campus operators and airport authorities shift procurement specifications toward EU AI Act-validated, high-redundancy platforms over minimum-viable pilot configurations.
For Market Incumbents: Cement certification moats by front-loading EU AI Act documentation investment and MDR alignment for LiDAR-to-steering control systems. Prioritize backward integration into solid-state LiDAR supply through joint development agreements with Chinese MEMS fabricators. Defend against modular shuttle entrants by locking multi-year campus service contracts that bundle operational liability with platform supply. For New Entrants and Emerging Players: Capture white-space in industrial-zone cargo-modular configurations where private-road operational design domains simplify validation timelines. Target German regulatory sandbox corridors in Berlin and Hamburg for fastest path to EU-wide certification. Lead with V2X infrastructure partnership proposals that open municipal procurement channels previously closed to autonomous platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where sensor-integrated chassis fabrication and autonomous driving stack development remain fragmented across separate vendor tiers. Frame long-term viability around captive sensor supply and regulatory validation expertise rather than fleet operations scale. Watch for inflection signals in NHTSA deployment waiver approval velocity for novel shuttle architectures.| Strategic Initiative | Industry Significance |
|---|---|
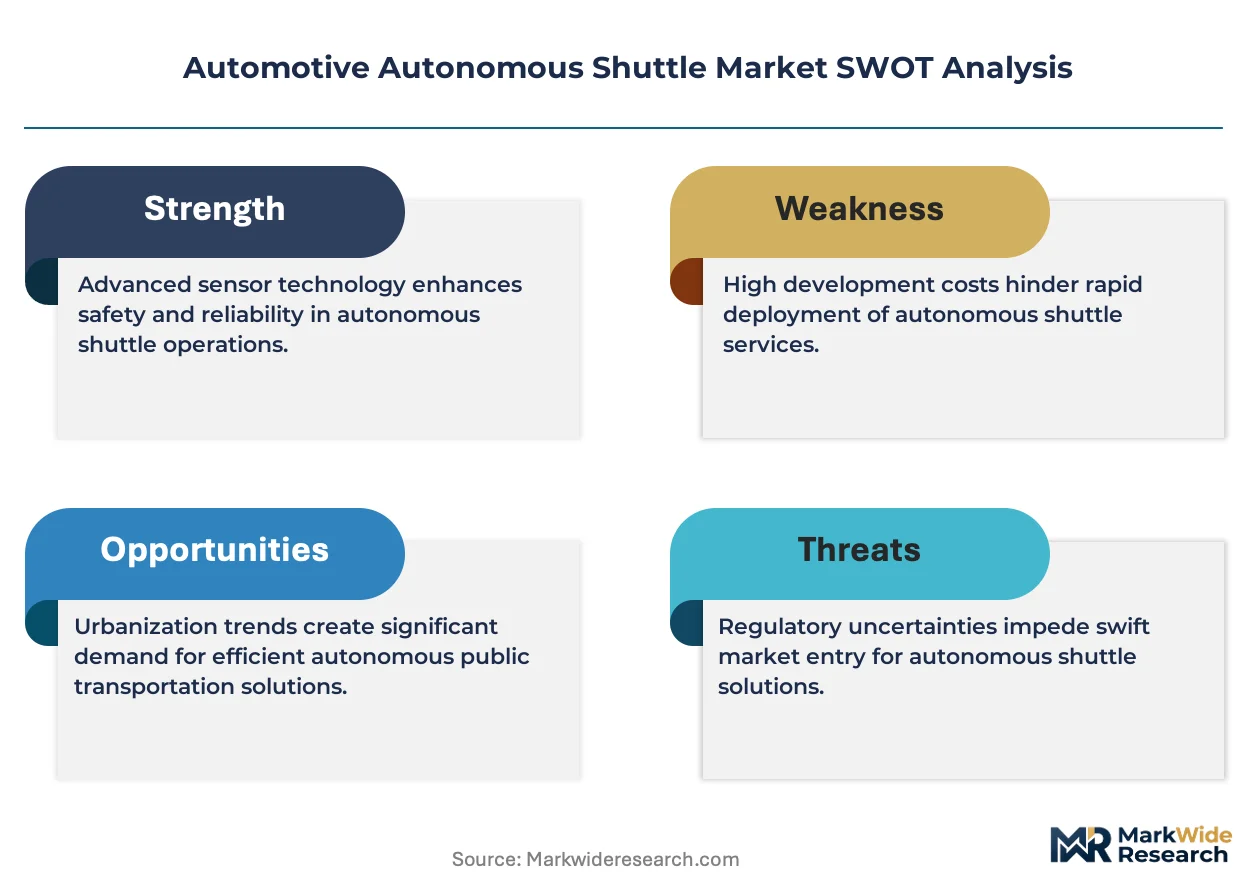
| Sensor-Integrated Chassis Manufacturing | Captive LiDAR and edge-computing production insulates margins from Asian supplier concentration. |
| EU AI Act Conformity Investment | Front-loaded documentation accelerates MDR alignment and unlocks German sandbox-to-EU deployment pathways. |
| V2X Infrastructure Partnership | Integration with smart-city traffic management systems opens closed municipal procurement channels. |
| High-Capacity Platform Development | Airport ground transport consolidation favors 20+ passenger designs over multiple small-vehicle contracts. |
| Modular Shuttle Architecture | Swappable passenger-cargo configurations enable multi-use fleet economics in European smart-city pilots. |
Study Parameters
Direct dialogue with shuttle fleet operators, autonomous driving stack engineers, municipal procurement officers, and regulatory validation consultants grounded the qualitative assessment. Secondary validation drew from NHTSA deployment waiver filings, EU AI Act implementing guidance, MIIT intelligent connected vehicle testing announcements, and airport authority procurement records. Bottom-up fleet deployment tracking and top-down market sizing triangulated volume estimates.
Bottom-up modeling segmented the market by vehicle class, sensor architecture tier, operational environment, and regional regulatory cluster across the projection horizon. Top-down cross-checks incorporated OEM platform engineering disclosures and tier-one supplier revenue attribution. CAGRs derived from deployment pipeline analysis and procurement timeline compression under fixed-route electrification mandates. Industry-specific inputs included LiDAR bill-of-materials cost curves and NHTSA waiver approval velocity trends.
Regulatory timeline delays, LiDAR supply disruptions, and liability framework fragmentation are the dominant revision risks to deployment forecasts. Forecasts reflect documented assumptions on certification pathway efficiency and infrastructure investment continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Italy Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
Driverless Taxi Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Autonomous Taxi Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Middle East and Africa ADAS Market