
 Automotive Wrap Films Market | 2026-2036
Automotive Wrap Films Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wrap Films Market Intelligence
The EU Green Deal's automotive sustainability mandates is consolidating demand for recyclable and low-emission wrap materials across European fleet operators. 3M leverages its multi-layer cast vinyl technology to sustain leadership in premium protective applications. Avery Dennison anchors its position through advanced adhesive science and color-matching systems for OEM-grade finishes.
Automotive wrap films are pressure-sensitive, multi-layer polymer assemblies—typically comprising PVC or polymeric face stock, adhesive layer, and release liner—engineered for conformable surface adhesion and removability without substrate damage. Cast vinyl dominates premium long-term applications due to dimensional stability and conformability around complex vehicle geometries. Protective wraps command the fastest expansion as paint preservation demand rises among luxury vehicle owners and lease-return fleets, while decorative applications retain the largest volume share through aftermarket customization channels.
EPA regulations on volatile organic compound emissions constrain solvent-based adhesive formulations in the United States, while REACH compliance in Europe mandates disclosure of phthalate and heavy metal content in PVC films. The EU AI Act and emerging digital printing standards are reshaping how wrap designs integrate with connected vehicle advertising systems. Stakeholders must monitor regulatory divergence between North American and European chemical standards when configuring global product portfolios.
Market Dynamics
REACH compliance in Europe and evolving EPA standards in the United States are forcing manufacturers toward lower-VOC adhesive formulations and recyclable face stock materials, compressing legacy solvent-based production lines while opening premium positioning for compliant suppliers.
Growth Catalysts
- Fleet Branding Demand:Commercial vehicle operators in the United States are deploying wraps as mobile advertising assets, converting idle fleet downtime into measurable impression-generating surfaces.
- REACH Chemical Mandates:European regulations on phthalate disclosure and heavy metal content are consolidating procurement around certified low-emission film suppliers with verified supply chain documentation.
- Cast Vinyl Technology:Multi-layer cast constructions with dimensional stability around complex geometries are displacing calendered films in premium long-term protective applications.
Market Restraints
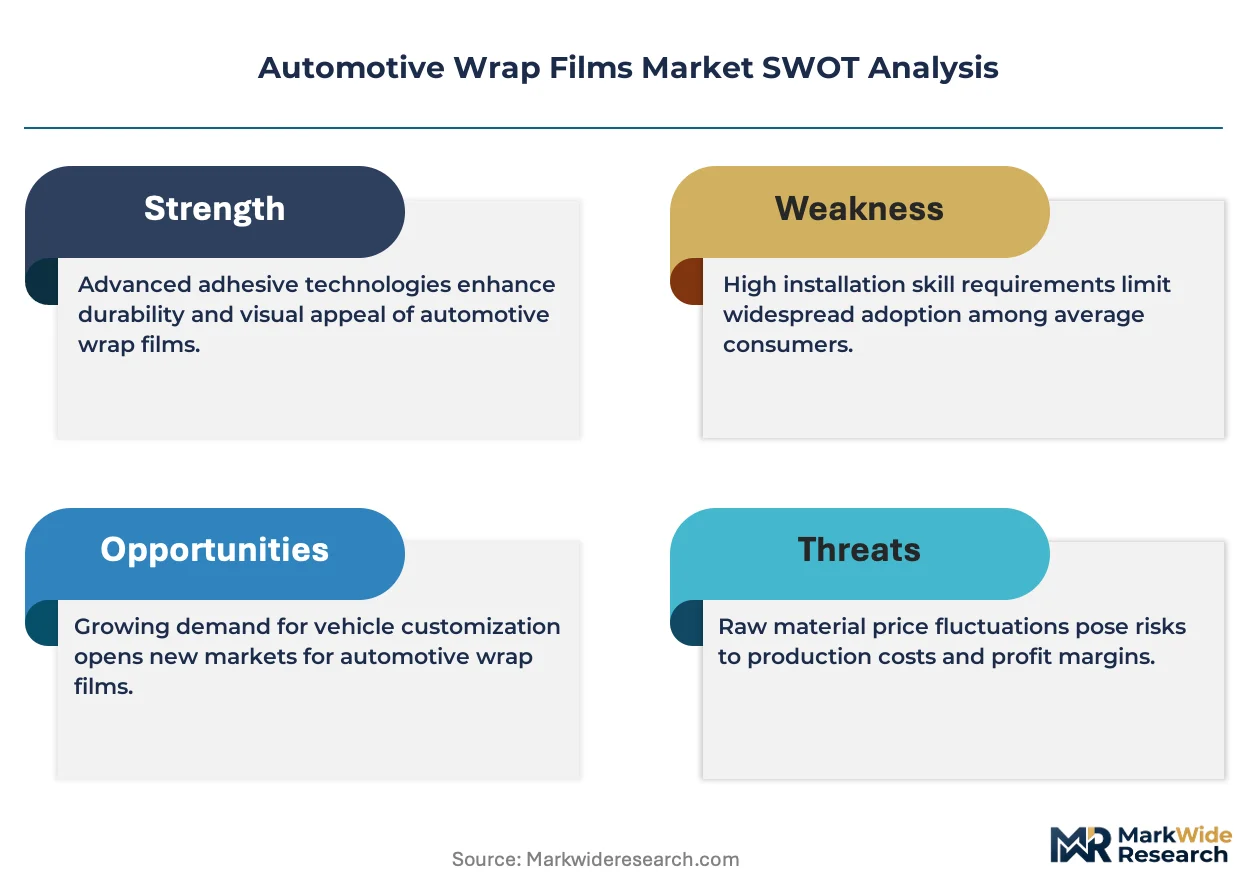
- Petrochemical Input Volatility:PVC resin and plasticizer costs fluctuate with crude oil derivatives, compressing margin predictability for film converters without backward integration into polymer supply.
- Adhesive Solvent Constraints:EPA volatile organic compound emission limits restrict solvent-based adhesive curing processes, requiring capital-intensive aqueous or UV-curing line conversions.
- Paint Protection Film Substitution:Thermoplastic polyurethane clear bra products compete directly with transparent protective wraps in luxury vehicle segments, fragmenting premium demand.
Strategic Opportunities
- Connected Vehicle Integration:The EU AI Act and emerging digital printing standards enable wrap designs with embedded NFC or QR connectivity for dynamic fleet advertising content updates.
- Lease-Return Fleet Services:Vehicle remarketing operations in Germany require damage-free paint preservation for residual value optimization, creating contracted wrap service demand.
- Recyclable Material Mandates:EU Green Deal sustainability targets position mono-material PET or polyolefin face stocks for regulatory preference in public fleet procurement.
Industry Challenges
- Skilled Installer Scarcity:Complex conformable application around compound curves requires certified technicians; training pipeline gaps limit service capacity expansion in high-demand markets.
- Multi-Jurisdiction Compliance:Divergent chemical disclosure requirements between EPA, REACH, and China's GB standards force SKU proliferation and inventory segmentation for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wrap Films Market |
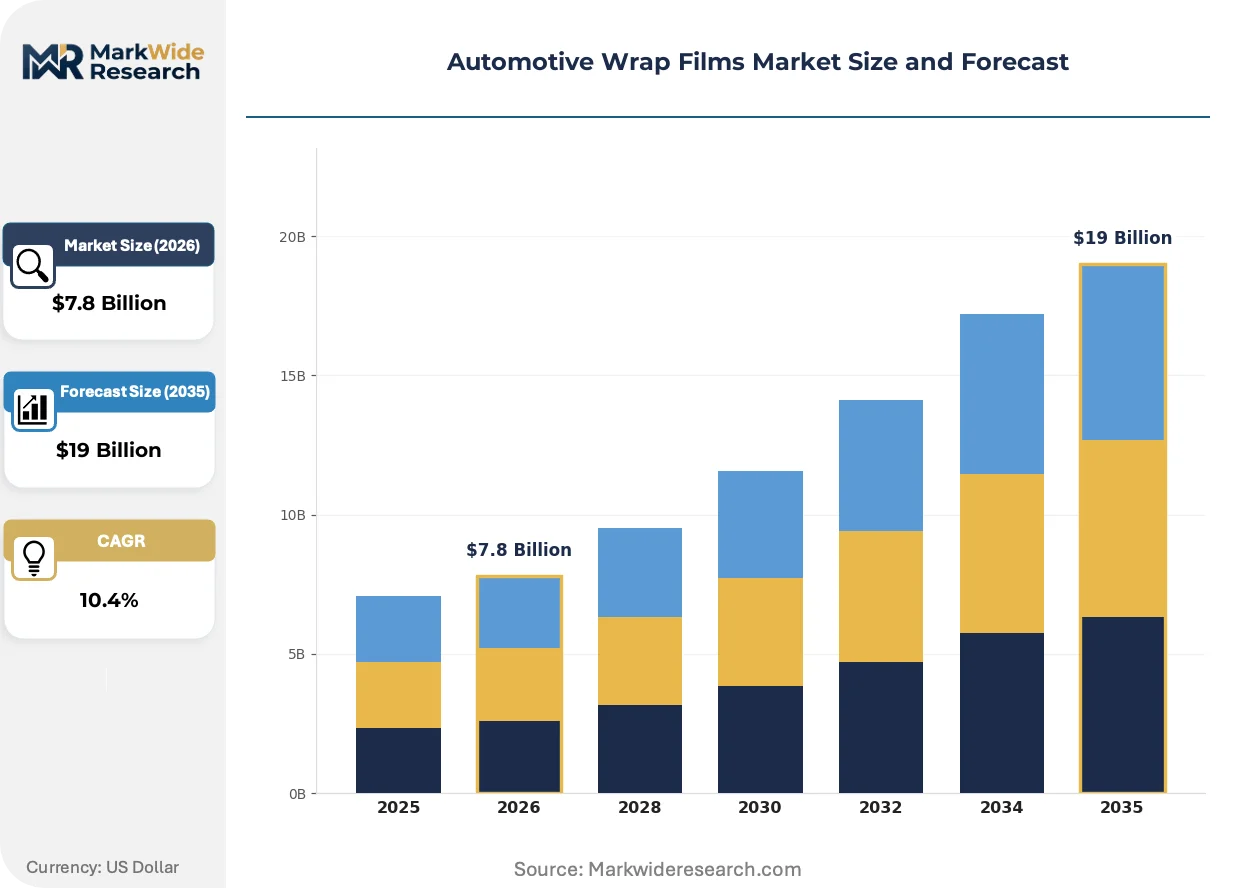
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $19 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Polymeric, Cast, Other Application: Decorative, Protective, Advertising, Branding End User: OEMs, Automotive Enthusiasts, Fleet Owners, Aftermarket Specialists Installation Method: DIY, Professional, Hybrid, Mobile |
| Companies Covered | 3M, Avery Dennison, Orafol Group, Hexis S.A., Arlon Graphics, Vvivid Vinyl, Kay Premium Marking Films, Ritrama S.p.A., Fedrigoni S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wrap Films Market Strategic Shifts & Innovations
Digital printing workflows and sustainable material science are converging to compress design-to-application cycles while elevating regulatory compliance from cost center to competitive differentiator in fleet and consumer segments.
Printable cast vinyl with embedded pressure-activated adhesive layers is modularizing the wrap production value chain. Fleet operators and aftermarket shops are adopting wide-format eco-solvent and latex printing systems in-house, bypassing traditional film converter intermediaries. This technology diffusion is compressing lead times from design approval to vehicle deployment from weeks to days.
The EU Green Deal's automotive sustainability mandates are mandating recyclable content thresholds and extended producer responsibility frameworks for vehicle exterior materials. Film manufacturers must now document end-of-life recovery pathways and carbon intensity across polymer sourcing. European fleet procurement specifications increasingly exclude PVC-based constructions, accelerating polyolefin and TPU material development.
Subscription-based fleet graphics programs are displacing outright purchase models among commercial vehicle operators. Leasing companies and logistics providers in the United States are bundling wrap design, installation, maintenance, and removal into per-vehicle monthly fees. This consumption-pattern shift transfers asset risk to service providers while locking in multi-year revenue relationships.
Automotive Wrap Films Market Segmentation
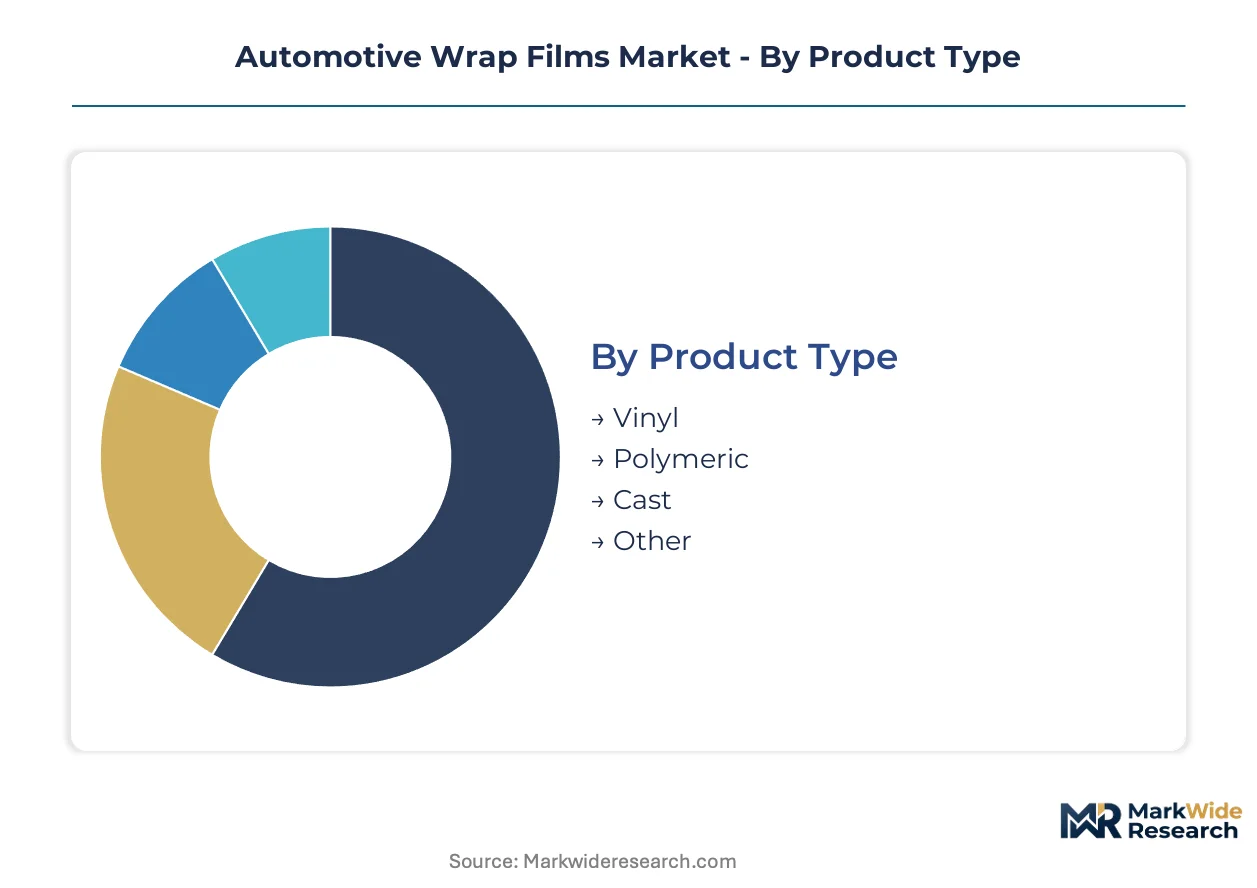
Automotive wrap film procurement hinges on durability requirements, installation complexity, and regulatory compliance across distinct buyer profiles. Segmentation reveals how material specifications, application intent, and service delivery models reshape vendor positioning and margin structures.
Product Type:
Buyers prioritize conformability and longevity when selecting film constructions, balancing upfront cost against removal characteristics and substrate protection.
- Cast:Multi-layer calendered constructions with pressure-activated adhesives deliver dimensional stability around compound curves and complex vehicle geometries. Luxury lease-return fleets in Germany specify cast films for damage-free paint preservation that optimizes residual value calculations.
- Vinyl:PVC-based face stocks dominate aftermarket customization channels through color breadth and print compatibility. United States fleet operators deploy vinyl wraps for mobile advertising campaigns requiring frequent graphic rotations.
- Polymeric:Intermediate durability films bridge cost-performance gaps for mid-term applications. These formulations attract price-sensitive automotive enthusiasts seeking 3-5 year aesthetic modifications without premium cast pricing.
- Other:Emerging PET and polyolefin mono-materials address EU Green Deal recyclability mandates for public fleet procurement.
Cast leads on scale; polymeric climbs the fastest as sustainability regulations tighten.
Application:
Application intent determines material specification, installation investment, and contract structure across consumer and commercial segments.
- Protective:Transparent or satin-finish films engineered for stone-chip resistance and UV degradation prevention. Paint preservation demand concentrates among luxury vehicle owners and United States lease-return operations managing residual value exposure.
- Decorative:Color-change and textured finishes serving personalization demand through aftermarket channels. Chinese automotive enthusiasts drive volume through matte, metallic, and chameleon effect specifications.
- Advertising:Fleet graphics converting commercial vehicles into impression-generating mobile assets. Subscription-based programs in the United States bundle design, installation, and removal into per-vehicle monthly fees.
- Branding:Corporate identity applications requiring precise color matching and regulatory compliance for cross-border fleet operations.
Decorative commands volume concentration; protective gains share fastest as vehicle prices escalate.
End User:
Procurement authority and technical sophistication vary sharply across buyer categories, reshaping sales channel configuration and service bundling.
- Fleet Owners:Commercial vehicle operators with centralized procurement and standardized specifications. Mobile advertising ROI calculations and multi-year service contracts dominate their vendor selection criteria.
- Aftermarket Specialists:Independent installers and regional shops serving enthusiast and local fleet demand. These intermediaries influence material specification through installer certification programs and equipment financing relationships.
- Automotive Enthusiasts:Individual consumers prioritizing aesthetic differentiation and social media visibility. Price sensitivity and DIY capability fragment this segment across online retailers and local installer networks.
- OEMs:Vehicle manufacturers integrating protective films into factory delivery or dealer accessory programs. Quality documentation and supply chain traceability requirements exceed aftermarket standards.
Fleet owners anchor revenue scale; aftermarket specialists drive installation capacity expansion.
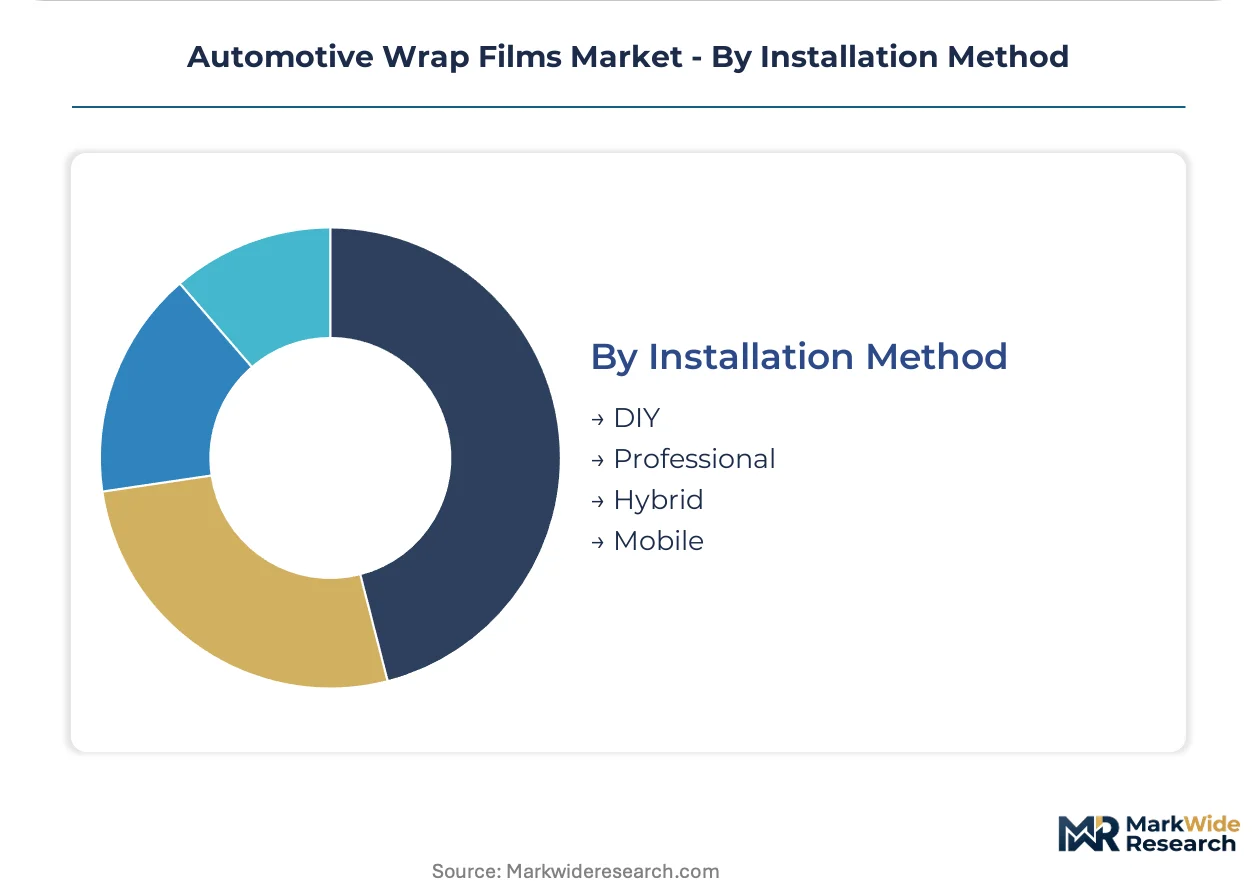
Installation Method:
Service delivery models are segmenting around labor availability, vehicle downtime constraints, and quality assurance requirements.
- Professional:Certified technician installation with climate-controlled bays and warranty-backed workmanship. Complex cast film applications around compound curves require this channel for defect-free outcomes.
- Mobile:On-site deployment reducing fleet vehicle downtime through containerized installation units. Logistics operators in Germany contract mobile services for distributed vehicle pools.
- DIY:Consumer self-application of pre-cut kits through e-commerce channels. Simplified geometries and air-release adhesive technologies expand accessible surface areas.
- Hybrid:Partial professional oversight with consumer completion for simpler panel sections.
Professional installation dominates value capture; mobile delivery expands fastest as fleet efficiency metrics tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive wrap films trace their industrial lineage to the United States, where 3M pioneered pressure-sensitive adhesive technologies for vehicle graphics in the 1960s. This foundational innovation established North America as the proving ground for cast vinyl formulations before manufacturing expertise diffused to European and Asian markets.
United States
Commercial fleet operators deploy wraps as mobile advertising assets, converting vehicle downtime into impression-generating surfaces. EPA volatile organic compound emission limits constrain solvent-based adhesive formulations, pushing converters toward aqueous curing systems. Installation capacity concentrates in Los Angeles, Dallas, and Atlanta, where climate-controlled bays support year-round professional application.
Germany
Lease-return fleet operations demand damage-free paint preservation to optimize residual value calculations. REACH compliance mandates disclosure of phthalate and heavy metal content in PVC films, consolidating procurement around certified low-emission suppliers. The KBA maintains type-approval standards for exterior vehicle modifications, shaping aftermarket specification requirements.
China
Automotive enthusiasts drive decorative wrap volume through matte, metallic, and chameleon effect specifications. MIIT oversees GB standards for vehicle exterior materials, creating compliance thresholds for imported film products. Manufacturing clusters in Guangdong and Zhejiang provinces host domestic film converters serving both local aftermarket and export markets.
United Kingdom
Corporate fleet branding programs require precise color matching for cross-border operational consistency. The DVLA maintains registration requirements for vehicle color changes, influencing wrap design documentation protocols. London-based installation specialists serve financial services and logistics sectors with subscription-based graphics programs.
Japan
Luxury vehicle owners prioritize paint protection films for stone-chip resistance and UV degradation prevention. METI promotes sustainable material innovation through its Green Innovation Fund, supporting polyolefin face stock development. Nagoya-Osaka industrial corridor hosts precision coating operations supplying OEM-grade protective film specifications.
Automotive Wrap Films Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the automotive wrap films value chain. Integrated polymer manufacturers with captive resin supply face pressure from specialized converters outsourcing base film procurement. The market structure segments into three archetypes: diversified materials conglomerates with multi-industry adhesive portfolios, dedicated graphics specialists focusing exclusively on vehicle and signage applications, and regional converters serving localized aftermarket demand. Competitive moves center on backward integration into polymer supply and geographic expansion through distributor network development.
Within the diversified materials tier, 3M and Avery Dennison exemplify scale-driven positioning through multi-layer cast vinyl technology and adhesive science capabilities respectively. Hexis S.A. represents the dedicated graphics specialist archetype, occupying a position focused on conformable film formulations for complex vehicle geometries. Orafol Group anchors the European specialist segment with manufacturing presence supporting REACH-compliant supply chains.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison |
| Orafol Group |
| Hexis S.A. |
| Arlon Graphics |
| Vvivid Vinyl |
| Kay Premium Marking Films |
| Ritrama S.p.A. |
| Fedrigoni S.p.A. |
| Others |
Cost & Logistics Intelligence
Petrochemical resin costs cascade through automotive wrap film pricing tiers from polymer converters in Germany and China to fleet procurement contracts in the United States, with REACH-compliant formulations commanding sustained premiums over legacy PVC constructions.
Pricing Analysis
Three-tier pricing structure across premium cast vinyl, standard calendered films, and economy polymeric grades anchors the market, with differentiation driven by certification tier (REACH/EPA-compliant versus legacy formulations) and volume scale from fleet operators. Price compression in the standard tier intensifies as wide-format digital printing adoption reduces converter margins. Fleet owners exhibit lowest price sensitivity due to bundled subscription models, while DIY enthusiasts drive volume at economy tiers.
Supply Chain Analysis
Certification gating through REACH disclosure mandates and EPA VOC emission standards concentrates qualified supply among integrated polymer manufacturers in Germany, the United States, and Japan. Raw material dependencies center on PVC resin, plasticizer additives, and pressure-sensitive adhesive polymers sourced from petrochemical feedstocks. Single-source vulnerability in specialty adhesive formulations creates structural risk. Distribution runs through authorized converter networks and direct fleet service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive wrap films represent a geographic-arbitrage play between European regulatory premium capture and Asian manufacturing cost structures, with REACH compliance costs in Germany running substantially above Chinese GB standard adherence.
For Market Incumbents: Lock in backward integration into specialty adhesive supply to defend against aqueous curing system shortages driven by EPA solvent constraints. Secure installer certification pipeline capacity in high-demand corridors like Dallas and Los Angeles to preempt service bottlenecks that fragment fleet contracts. For New Entrants and Emerging Players: Mobile installation service providers offer the most penetrable channel entry point, particularly for logistics operators in Germany managing distributed vehicle pools with downtime-sensitive operations. Pursue white-space positioning in polyolefin mono-material films ahead of EU Green Deal recyclability mandates excluding PVC from public procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale converters lack REACH documentation capabilities and face stranded inventory from divergent chemical standards between EPA and European requirements. Target acquisition archetypes include regional installers with captive fleet relationships and converters with verified low-emission supply chains. Watch for inflection when EU extended producer responsibility frameworks mandate end-of-life recovery infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Supply | Captive aqueous curing capacity insulates against EPA solvent restrictions and secures margin control. |
| Installer Certification Program Expansion | Trained technician pipelines in Atlanta and Dallas unlock fleet contract scalability in climate-controlled markets. |
| Polyolefin Face Stock Development | Mono-material PET constructions position suppliers for EU Green Deal public procurement exclusion of PVC films. |
| Mobile Service Infrastructure Deployment | Containerized installation units reduce fleet vehicle downtime and capture subscription-based recurring revenue. |
| REACH Compliance Documentation Investment | Verified supply chain traceability consolidates procurement preference among European lease-return fleet operators. |
Research Approach
Multiple input streams — primary interviews with film converter operations managers, fleet procurement directors, and aftermarket installer network heads; secondary validation through customs trade data, SEC filings from diversified materials conglomerates, and EPA emission standard disclosures; plus IHS Markit vehicle registration databases — were reconciled through bottom-up and top-down triangulation to establish market sizing.
Data-stream reconciliation across the projection horizon applied segmentation dimensions of film construction type, application intent, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from installed base growth rates and content-per-vehicle assumptions for protective and decorative applications, with fleet advertising spend patterns and lease-return volume cycles serving as automotive-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical price volatility and divergent regulatory enforcement between EPA and REACH jurisdictions. Forecasts reflect assumptions about installer capacity expansion and fleet subscription adoption trajectories. A model refresh is warranted upon material change in EU extended producer responsibility implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Foamed Polypropylene Films Market
Poly film
Stretch Films Packs Market
Poly film
Easy Peel Film Packaging Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Poly Coated Paper Market
Poly film
Bundling Film Market
Poly film
PVC Cling Film Market
Poly film
Laminating Film Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
Nylon Films Market
Poly film
Soft Touch Film Market
Poly film
In-Mould Label Film Market
Poly film
Global Fluoropolymer Films Market
Poly film
Global PVDC Coated Films Market
Poly film
APET Film Market
Poly film
France Plastic Packaging Films Market