
 Bundling Film Market | 2026-2036
Bundling Film Market Size, Share, and Industry Trends Forecast 2026-2036
Bundling Film Market Outlook
China is narrowing the gap in cast stretch film capacity through new extrusion lines in Zhejiang and Jiangsu provinces. Berry Global leverages captive resin sourcing across North American facilities to sustain margin stability. Amcor competes through multilayer barrier expertise in food-contact bundling formats. Mondi Group anchors European supply with kraft-paper hybrid solutions that reduce plastic intensity.
Bundling film comprises flexible polymer substrates engineered to unitize palletized goods, typically manufactured via cast or blown extrusion at thicknesses between 12 and 35 microns with elongation properties exceeding 200 percent. Stretch film dominates volume flows across industrial applications where load containment during transit represents the core functional requirement. Shrink film commands premium positioning in retail packaging where printed graphics and shelf-ready presentation justify higher unit economics. Polyethylene grades, particularly linear low-density formulations, absorb the majority of material demand due to cost efficiency and recyclability alignment with EU packaging directives.
EPA guidelines on plastic waste streams and FDA food-contact substance notifications shape product development pathways for domestic suppliers. REACH restrictions on phthalate plasticizers and EU Green Deal circularity targets force reformulation of PVC-containing bundling products across European markets. Stakeholders must monitor polymer feedstock volatility and evolving extended producer responsibility schemes to calibrate capacity commitments and material substitution strategies.
Market Dynamics
Europe's F-Gas Regulation and REACH compliance are compressing PVC-containing bundling formulations while pulling demand toward recyclable polyethylene grades. This regulatory pressure is restructuring supplier portfolios and extrusion capacity allocation across the value chain.
Growth Catalysts
- E-commerce fulfillment scaling:Third-party logistics operators in Germany and the Netherlands are expanding automated pallet-wrapping lines. Cast stretch film consumption per fulfillment center has risen sharply.
- REACH plasticizer restrictions:Phthalate bans under ECHA guidelines are forcing PVC film substitution. Linear low-density polyethylene grades capture displaced volume in food-contact applications.
- Automotive component bundling:German OEMs require high-clarity stretch solutions for just-in-time parts delivery. Thickness specifications have tightened to 15-20 microns for optical scanning compatibility.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracking margins in Rotterdam and Antwerp swing with crude differentials. Polyethylene resin contracts reset monthly, compressing film converter margins.
- Blown film supply concentration:Capacity clusters in northern Italy and eastern Germany. Transportation costs penalize buyers in Iberia and Scandinavia.
- Mechanical recycling contamination limits:Multi-layer barrier films fail EU Green Deal circularity thresholds. Sorting infrastructure cannot separate adhesive-laden bundling waste streams.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Labor and energy costs run 30-40% below German levels. Greenfield extrusion sites serve Central European automotive and food processing clusters.
- Paper-film hybrid formats:Mondi's kraft-paper laminate technology reduces plastic intensity by 40-60%. Retailers in France and Belgium specify these for shelf-ready produce trays.
- Extended Producer Responsibility schemes:France's Citeo and Italy's CONAI modulate fees by recyclability tier. Mono-material polyethylene designs qualify for lowest tariff bands.
Industry Challenges
- Multilayer coextrusion technician shortage:Blown film lines require operators skilled in die gap adjustment and bubble stability. Training programs in northern England and the Ruhr Valley cannot match retirement outflows.
- Food-contact migration testing timelines:EFSA compliance documentation for new additive packages extends 18-24 months. Product development cycles lag retailer sustainability commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bundling Film Market |
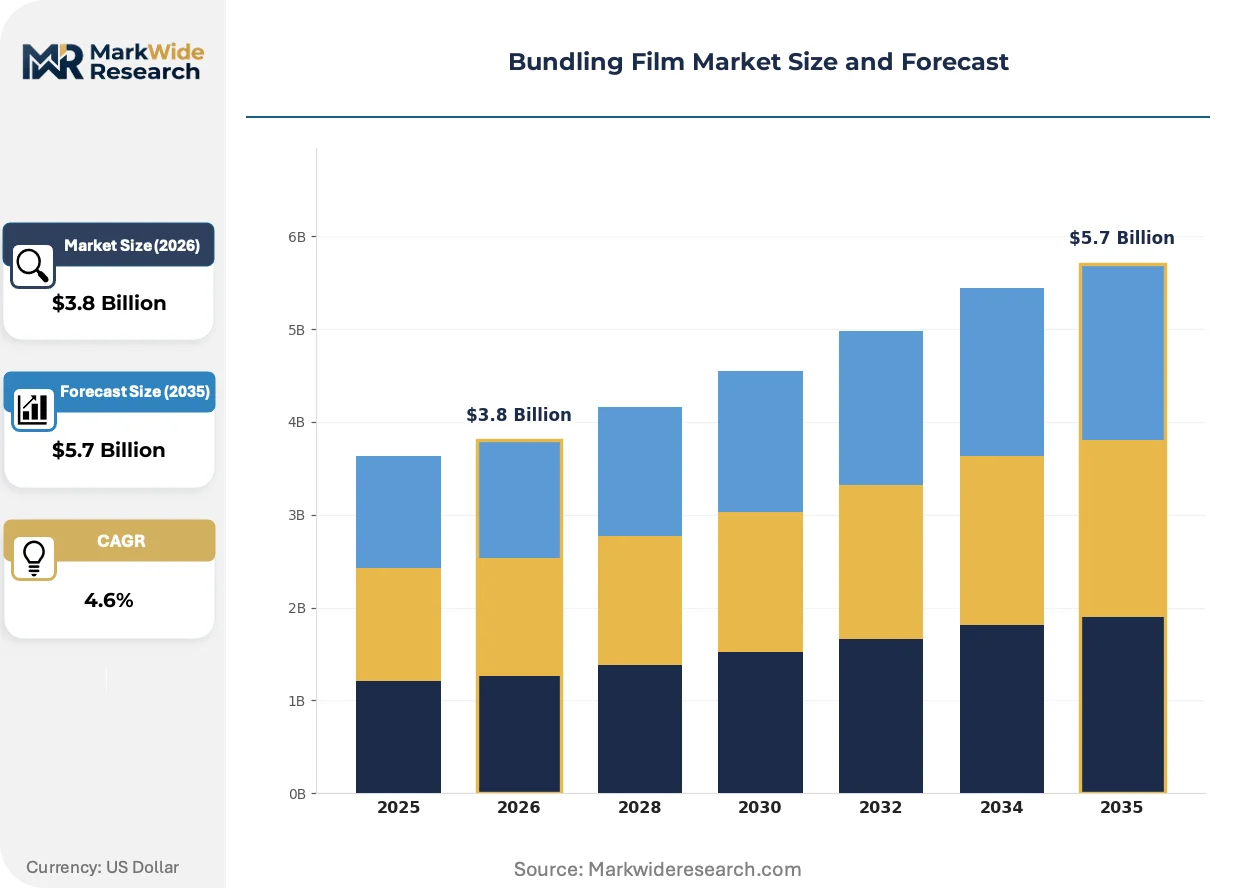
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, Thermal Film Material: Polyethylene, Polypropylene, PVC, PLA Application: Food Packaging, Medical Packaging, Industrial Use, Retail Packaging End User: Food Industry, Healthcare Sector, Manufacturing Sector, E-Commerce |
| Companies Covered | Berry Global, Amcor, Mondi Group, Sealed Air, Sigma Plastics Group, Intertape Polymer Group, Inteplast Group, RKW Group, Coveris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bundling Film Market Strategic Shifts
Active material substitution and regulatory redesign are compressing legacy PVC positions while elevating mechanically recyclable alternatives. Technology convergence between paper substrates and polymer coatings is creating new format categories.
Cast stretch film is hybridizing with bio-based feedstock integration. Braskem's I'm green polyethylene is entering European film formulations at 20-30% content levels. Food retailers in Denmark and Sweden specify these grades for private-label packaging. The technology is hybridizing cost structures between fossil and renewable resin pricing, forcing converters to manage dual supply contracts.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are eliminating legacy PVC stabilizer systems. Compounders in Belgium and the Netherlands have reformulated toward calcium-zinc alternatives. Automotive bundling applications in Stuttgart and Wolfsburg now reject any PVC-containing documentation, accelerating polyethylene displacement in component supply chains.
Consolidated procurement through European retail buying alliances is compressing supplier margins. Tesco, Carrefour, and Ahold Delhaize negotiate pan-continental film contracts with sustainability KPIs attached. Tier-2 converters in Portugal and Greece face exclusion unless they achieve ISCC PLUS certification. The shift concentrates volume with integrated resin-to-film operators who control Scope 3 emissions data.
Bundling Film Market Segmentation
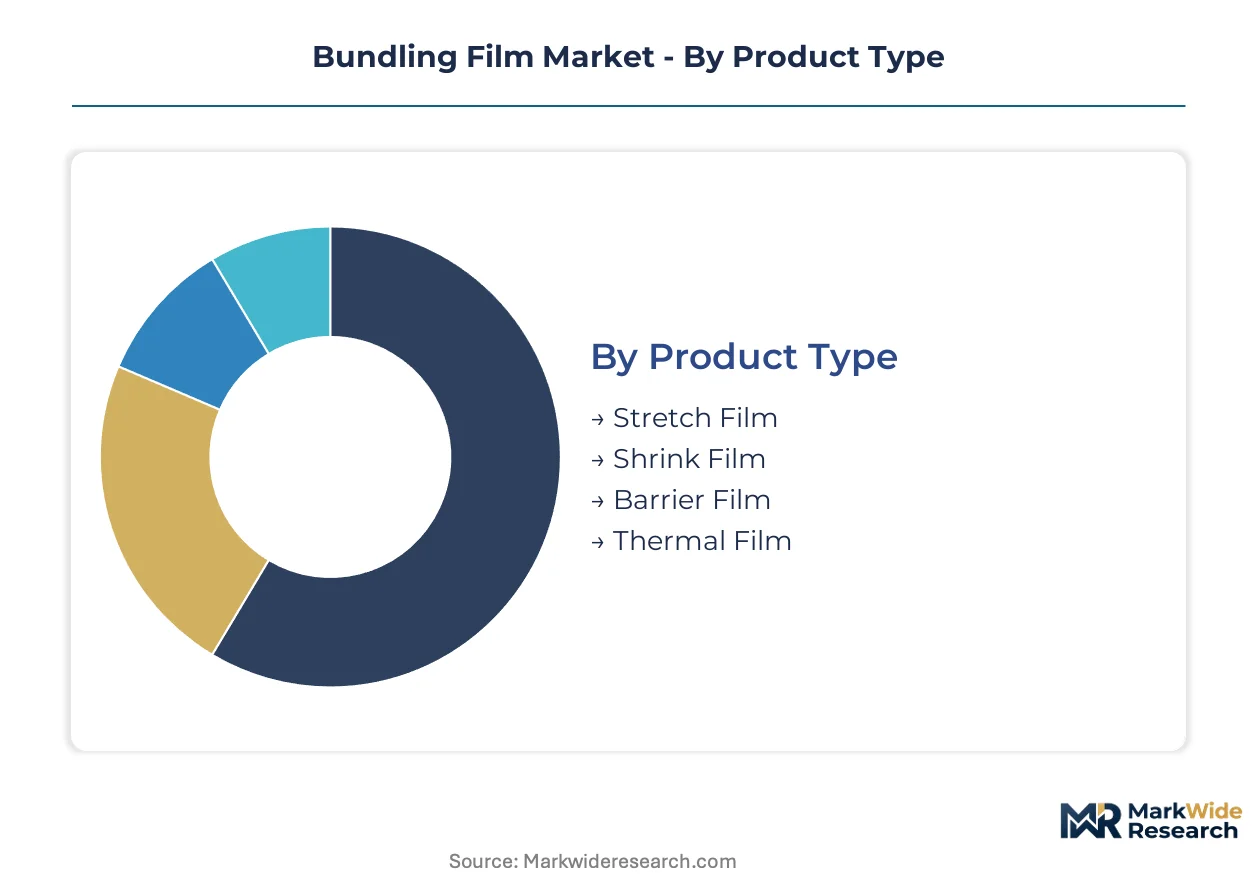
Segmentation in bundling film reveals divergent margin profiles and capital intensity across product architectures. Cycle times vary from weeks for commodity stretch grades to months for validated medical barrier formats. Procurement teams calibrate inventory policies against these velocity differentials.
Product Type:
Stretch film turns inventory fastest with standardized specifications, while barrier film locks working capital longest due to multi-layer qualification protocols.
- Stretch Film:Linear low-density polyethylene formulations dominate at 12-35 micron thicknesses with elongation exceeding 200 percent. Automated pallet-wrapping lines in German and Dutch fulfillment centers absorb the highest throughput volumes, though margin compression intensifies as resin contracts reset monthly.
- Shrink Film:Biaxially oriented structures with controlled shrink ratios enable printed graphics and shelf-ready presentation. French and Belgian retailers specify these for produce trays where optical clarity justifies premium unit economics over standard stretch alternatives.
- Barrier Film:Coextruded structures with EVOH or PA layers extend shelf life in modified atmosphere packaging.
- Thermal Film:Heat-sealable grades for lidding and tray sealing applications in ready-meal formats.
Stretch film anchors the volume base while barrier film gains share at the steepest rate.
Material:
Cost tiers separate fossil-derived commodity grades from bio-based and regulatory-constrained alternatives.
- Polyethylene:Linear low-density and metallocene grades absorb the majority of industrial demand due to cost efficiency and alignment with EU packaging directives on recyclability. Cast extrusion lines in Zhejiang and Jiangsu provinces are narrowing capacity gaps with European suppliers.
- PVC:Phthalate plasticizer bans under REACH Annex XVII are forcing rapid displacement in food-contact applications. Stuttgart and Wolfsburg automotive facilities now reject any PVC-containing documentation, accelerating polyethylene substitution in component supply chains.
- Polypropylene:Higher stiffness and temperature resistance serve medical sterilization and hot-fill applications.
- PLA:Bio-based polylactic acid grades from Braskem's I'm green portfolio enter European formulations at 20-30 percent content levels.
Polyethylene dominates current procurement volumes while PLA climbs the fastest among sustainability-mandated categories.
Application:
Customer type determines specification rigor, with industrial buyers prioritizing cost-per-pallet and medical buyers demanding migration-tested compliance.
- Food Packaging:Modified atmosphere and vacuum skin formats require oxygen transmission rates below 1 cc/m²/day. EFSA compliance documentation for new additive packages extends 18-24 months, lagging retailer sustainability commitments.
- Industrial Use:Load containment during transit represents the core functional requirement with minimal barrier specifications. Northern Italian and eastern German blown film capacity clusters serve this segment with transportation cost penalties for Iberian and Scandinavian buyers.
- Medical Packaging:Sterilization compatibility and particulate limits drive qualification protocols.
- Retail Packaging:Shelf-ready presentation and printability command premium positioning.
Industrial use commands the largest shipment volumes while food packaging expands most quickly under e-commerce fulfillment scaling.
End User:
Supply concentration varies sharply, with consolidated retail alliances squeezing margins versus fragmented manufacturing bases.
- Food Industry:Pan-continental buying alliances at Tesco, Carrefour, and Ahold Delhaize attach sustainability KPIs to film contracts. Tier-2 converters in Portugal and Greece face exclusion without ISCC PLUS certification.
- E-Commerce:Third-party logistics operators in Germany and the Netherlands are expanding automated pallet-wrapping lines with cast stretch consumption rising sharply per fulfillment center.
- Manufacturing Sector:Automotive component bundling in Stuttgart and Wolfsburg requires high-clarity stretch solutions with thicknesses tightened to 15-20 microns for optical scanning compatibility.
- Healthcare Sector:Sterile barrier validation and migration testing timelines extend procurement cycles.
The food industry provides the revenue foundation while e-commerce drives the steepest demand trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's polymer handling terminals anchor Europe's polyethylene resin flows, while the Rhine-Alpine rail corridor distributes bundling film stock to Stuttgart and Wolfsburg automotive clusters. These infrastructure assets concentrate extrusion capacity and dictate regional pricing spreads.
Germany
Automotive component bundling in Stuttgart and Wolfsburg demands high-clarity stretch film at 15-20 micron thicknesses for optical scanning compatibility. REACH Annex XVII phthalate restrictions eliminate PVC alternatives from just-in-time supply chains. The Ruhr Valley hosts blown film training programs that struggle to match technician retirement outflows.
China
New cast extrusion lines in Zhejiang and Jiangsu provinces narrow capacity gaps with European suppliers. The country's dual carbon goals pressure naphtha crackers toward efficiency upgrades. Shanghai port terminals handle growing resin imports for film converters serving e-commerce fulfillment networks.
United States
EPA guidelines on plastic waste streams and FDA food-contact substance notifications shape domestic product development pathways. Berry Global leverages captive resin sourcing across North American facilities to sustain margin stability. Gulf Coast ethane crackers supply cost-advantaged feedstock to Texas-based extrusion operations.
France
Citeo's extended producer responsibility scheme modulates fees by recyclability tier, favoring mono-material polyethylene designs. Retailers in Paris and Lyon specify Mondi's kraft-paper hybrid laminates for shelf-ready produce trays. The country's national packaging regulator enforces strict migration testing timelines for food-contact applications.
Poland
Greenfield extrusion sites serve Central European automotive and food processing clusters with labor and energy costs 30-40% below German levels. Warsaw and Łódź logistics hubs absorb cast stretch film volumes for third-party distribution networks. EU Green Deal circularity targets accelerate sorting infrastructure investments for mechanically recyclable waste streams.
Bundling Film Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin compounding and film conversion. The vendor base stratifies between integrated resin-to-film operators and independent converters dependent on spot resin contracts. Three archetypes dominate: multinational packaging conglomerates with captive resin sourcing, regional extrusion specialists serving single industries, and hybrid paper-film innovators reducing plastic intensity. Consolidated procurement through retail buying alliances and backward integration into resin production represent the dominant competitive moves reshaping margin structures.
Among North American integrated operators, Berry Global and Sealed Air occupy positions defined by scale and captive supply chain control. European supply anchors through Mondi Group, whose kraft-paper hybrid technology exemplifies the plastic-reduction archetype gaining traction with French and Belgian retailers. These three companies represent the strategic poles—resin-integrated volume, barrier expertise, and sustainability-led format innovation—around which tier-2 converters in Portugal and Greece must achieve ISCC PLUS certification to avoid exclusion from pan-continental contracts.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Mondi Group |
| Sealed Air |
| Sigma Plastics Group |
| Intertape Polymer Group |
| Inteplast Group |
| RKW Group |
| Coveris |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine rail corridor's freight cost dynamics amplify supply concentration effects in European bundling film markets, with Rotterdam-Antwerp resin hub proximity enabling price differentiation between integrated converters and spot-dependent competitors while naphtha-cracking margin volatility transmits downstream through monthly contract resets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISCC PLUS-certified film from commodity grades and PVC-containing legacy stock. Price differentiation hinges on certification tier and volume scale, with pan-continental retail alliances extracting steep discounts through consolidated procurement. Pricing pressure stems from consolidated buyer power and resin contract volatility, compressing margins most severely for tier-2 converters in peripheral markets. Industrial pallet-wrapping buyers exhibit highest price sensitivity, while food-contact barrier film purchasers prioritize compliance over unit cost.
Supply Chain Analysis
Ethylene feedstock sourcing draws from naphtha crackers concentrated in the Netherlands, Belgium, and Germany, with Gulf Coast ethane-based polyethylene increasingly arbitraged into European film formulations. Raw material dependencies center on linear low-density polyethylene resin, calcium-zinc stabilizer compounds, and bio-based feedstock certificates. Supply chain risk manifests in single-source vulnerability for multilayer coextrusion equipment and specialized die components. Distribution runs through polymer handling terminals at Rotterdam and Antwerp, with rail and barge networks serving extrusion clusters in the Ruhr Valley and northern Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bundling film incumbents face a substitution defense against paper-film hybrid formats and rigid plastic alternatives, with sustainability-mandated procurement at major retail alliances accelerating material transition timelines.
For Market Incumbents: Insulate core polyethylene positions through backward integration into resin compounding and ISCC PLUS certification investment, while accelerating kraft-paper laminate capability development to counter Mondi's hybrid format threat. Captive supply chain control and Scope 3 emissions data ownership represent critical defensive levers against consolidated retail procurement pressure.
For New Entrants and Emerging Players: Central European manufacturing underpenetration offers white-space entry points, with Poland and Czech Republic greenfield sites serving automotive and food processing clusters at 30-40% cost advantages versus German operations. Target bio-based feedstock integration at 20-30% content levels as the most penetrable sustainability tier, leveraging Braskem's I'm green polyethylene supply contracts as a differentiated go-to-market anchor.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging conglomerates divesting non-core film conversion assets; mid-scale extrusion specialists with automotive certification and Central European footprint present attractive acquisition profiles. Long-term viability across the analysis window favors operators with dual fossil and bio-based resin sourcing flexibility. Watch EFSA migration testing timeline acceleration as the signal for food-contact barrier film capacity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply insulates margin stability against Rotterdam naphtha-cracking volatility. |
| ISCC PLUS Certification Investment | Qualification for Citeo and CONAI lowest tariff bands secures pan-continental retail contract access. |
| Kraft-Paper Hybrid Format Development | Mondi's laminate technology reduces plastic intensity 40-60%, matching French retailer sustainability specifications. |
| Central European Greenfield Expansion | Polish and Czech sites capture automotive and food processing demand at labor cost advantages versus Germany. |
| Bio-Based Feedstock Integration | Braskem's I'm green polyethylene at 20-30% content meets Danish and Swedish private-label retailer mandates. |
Study Parameters
A standing panel of extrusion plant managers, procurement leads at German automotive OEMs, retail category buyers, and technical R&D directors at resin compounders provided ongoing calibration across the study period. Primary interview findings triangulated against customs and trade data, European Chemical Industry Council reports, SEC filings from integrated packaging operators, and FDA food-contact substance notification databases. Bottom-up capacity and consumption estimates reconciled with top-down value chain sizing.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeled by product architecture, material grade tier, end-use industry, and regional production hub. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment scaling, REACH regulatory phase-in schedules, and automotive just-in-time packaging specification evolution. Feedstock cost pass-through assumptions and extended producer responsibility fee structures informed price trajectory modeling.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by tier-1 packaging conglomerates or rapid paper-film hybrid technology diffusion would shift outcomes materially. Cross-checking against European Plastics Association production statistics and individual member state packaging waste reporting is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
North America Plastic Film Packaging Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
PP Film Blowing Machine Market
Poly film
Printed Plastic Films Market
Poly film
Global PVDC Coated Films Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
France Plastic Packaging Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Polypropylene Film Market
Poly film
Resealable Films Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
MOPP Packaging Films Market
Poly film
PCR Lidding Films Market