
 Laminating Film Market | 2026-2036
Laminating Film Market Size, Share, and Industry Trends Forecast 2026-2036
Laminating Film Market Analysis
REACH is hardening the cost-of-entry calculus for European laminating film suppliers, forcing reformulation of adhesive chemistries and expanded substance-testing budgets. Cosmo Films leverages backward integration into polyester resin production to absorb these compliance costs without margin erosion. Mondi plc anchors its position through captive pulp-to-film operations across Central European mills. Avery Dennison differentiates via solvent-free coating R&D programs that preempt regulatory tightening in multiple jurisdictions.
Laminating film comprises multilayer polymer substrates bonded through thermal, pressure-sensitive, or liquid adhesive processes, typically ranging from 25 to 250 microns in finished gauge, engineered to protect printed surfaces against moisture, abrasion, and UV degradation. Thermal Film dominates volume flows across high-speed packaging lines where heat-activated polyethylene and polyester constructions deliver throughput advantages. Pressure-Sensitive Film occupies premium segments in short-run printing services where tool-free application reduces job-change downtime. Water-Based coating technology is displacing solvent systems in European and North American regulatory environments, though solvent platforms retain cost advantages in price-sensitive Asian converting operations.
FDA food-contact regulations, EPA emissions standards for coating operations, and EU REACH chemical authorization frameworks collectively reshape product specifications and facility investment requirements across the laminating film value chain. BIS certification mandates in India and GB standards enforcement through SAMR in China add parallel compliance layers for exporters serving multiple national markets. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating regional production footprints and formulation portfolios to avoid stranded asset exposure from accelerated chemical restrictions.
Market Dynamics
REACH chemical authorization frameworks are forcing adhesive reformulation across European converting operations while water-based coating R&D absorbs capital that solvent-dependent Asian producers avoid. This regulatory divergence splits competitive economics between jurisdictions.
Growth Catalysts
- Food-contact compliance mandates:FDA regulations for direct-contact laminating films in US meal-kit packaging are accelerating certified substrate procurement from coextrusion specialists.
- Thermal film throughput advantages:Heat-activated polyethylene constructions dominate Maharashtra and Gujarat industrial corridors where high-speed packaging lines prioritize output velocity over application flexibility.
- BIS barrier certification:Indian packaging buyers under Bureau of Indian Standards mandates are scaling procurement of certified films for moisture-sensitive pharmaceutical and agrochemical exports.
Market Restraints
- Petroleum-based resin volatility:Polyester and polyethylene feedstock costs fluctuate with crude price cycles, compressing margin predictability for non-integrated converters.
- Adhesive chemistry lock-in:Solvent-based coating platforms retain cost advantages in price-sensitive Asian operations, creating reformulation friction for exporters serving multiple regulatory regimes.
- Substrate supply concentration:Biaxially oriented polyester film production clusters in China and South Korea, exposing downstream laminators to geographic supply risk and freight cost spikes.
Strategic Opportunities
- Pharmaceutical serialization compliance:EU Falsified Medicines Directive and US DSCSA track-and-trace mandates are creating demand for tamper-evident laminated labels with integrated verification features.
- Solvent-free coating convergence:UV-curable and electron-beam technologies are penetrating premium short-run printing services where VOC elimination commands price premiums.
- Rural India penetration:Underdeveloped laminating capacity in Bihar and Uttar Pradesh presents white-space expansion for regional converters serving agricultural packaging cooperatives.
Industry Challenges
- Multijurisdictional substance testing:REACH SVHC screening, FDA food-contact notification, and BIS migration testing create overlapping compliance timelines that delay product launches by 8-14 months.
- Skilled coating technician scarcity:Precision control of adhesive coat weights and thermal activation profiles requires specialized training unavailable in secondary converting labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminating Film Market |
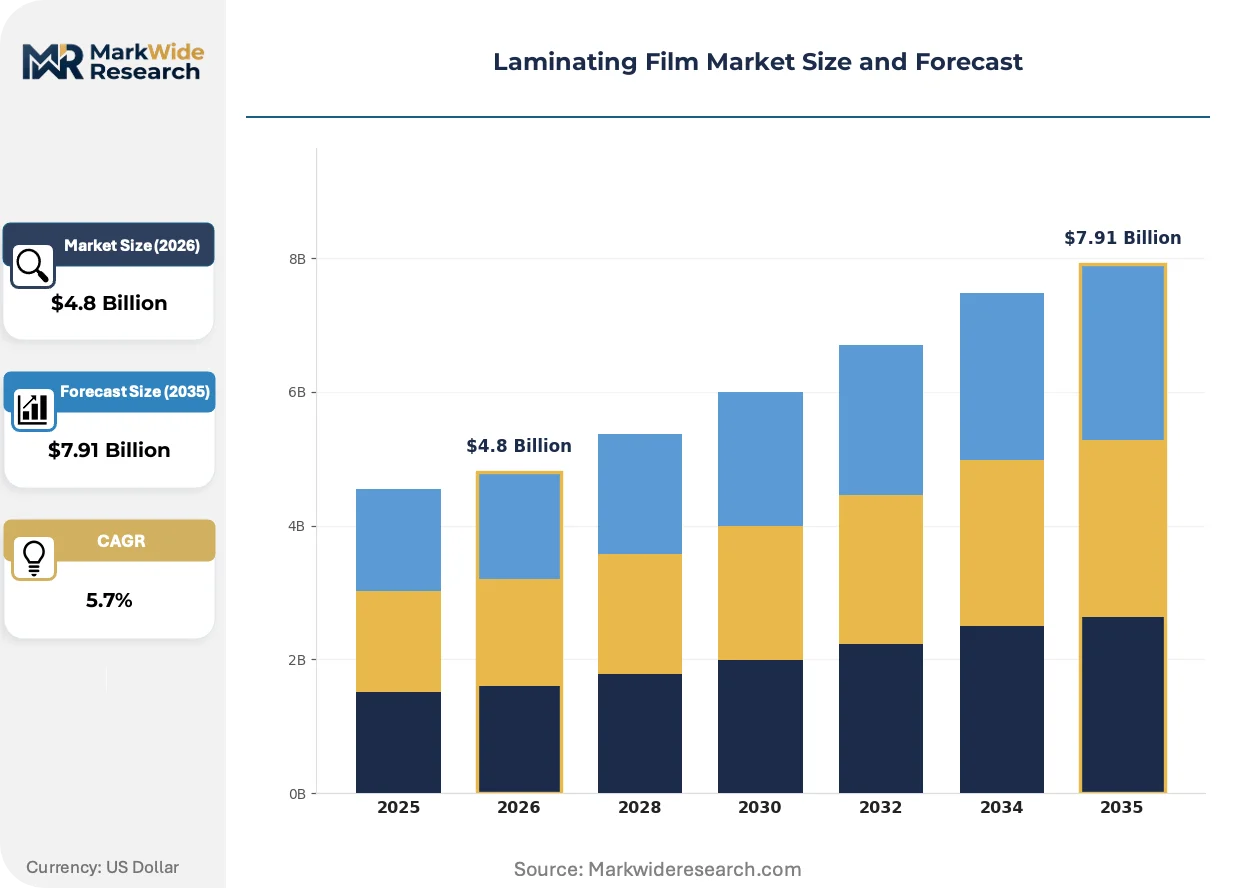
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Film, Pressure-Sensitive Film, Cold Lamination Film, Liquid Laminates Technology: Extrusion, Coating, Solvent-Based, Water-Based End User: Packaging Industry, Printing Services, Office Supplies, Education Sector Distribution Channel: Online Sales, Retail Outlets, Distributors, Direct Sales |
| Companies Covered | 3M, Cosmo Films, DuPont, Avery Dennison, Toray Plastics, Transilwrap, D&K, Mondi plc, UFLEX Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminating Film Market Emerging Trajectories
Water-based adhesive platforms are converging with bio-derived polymer substrates to preempt regulatory tightening across multiple jurisdictions. This chemistry-material pairing is reshaping capital allocation in coating operations.
Digital printing workflows are converging with pressure-sensitive laminating films in commercial print shops where job-change frequency rewards tool-free application. Short-run label converters in Germany and the Netherlands are adopting these combinations to compress make-ready intervals from hours to minutes. The technology pairing is converging with demand for mass-customized packaging in cosmetics and craft beverage segments.
EU REACH authorization requirements for phthalate plasticizers and isocyanate-based adhesives are forcing systematic substitution programs across film converting operations. Coating facilities in Belgium and northern Italy are retrofitting exhaust systems and validating alternative chemistries under ECHA substance evaluation timelines. Thermal film producers serving EU food-contact applications face the steepest compliance cost escalation.
Brand-owner sustainability scorecards are altering specification authority in packaging procurement. Multinational consumer goods companies in personal care and prepared foods are mandating recycled content thresholds and end-of-life recyclability certifications that bypass traditional converter-buyer relationships. This specification shift is most visible in Western European and North American markets where EPR frameworks assign producer responsibility for packaging waste streams.
Laminating Film Market Segmentation
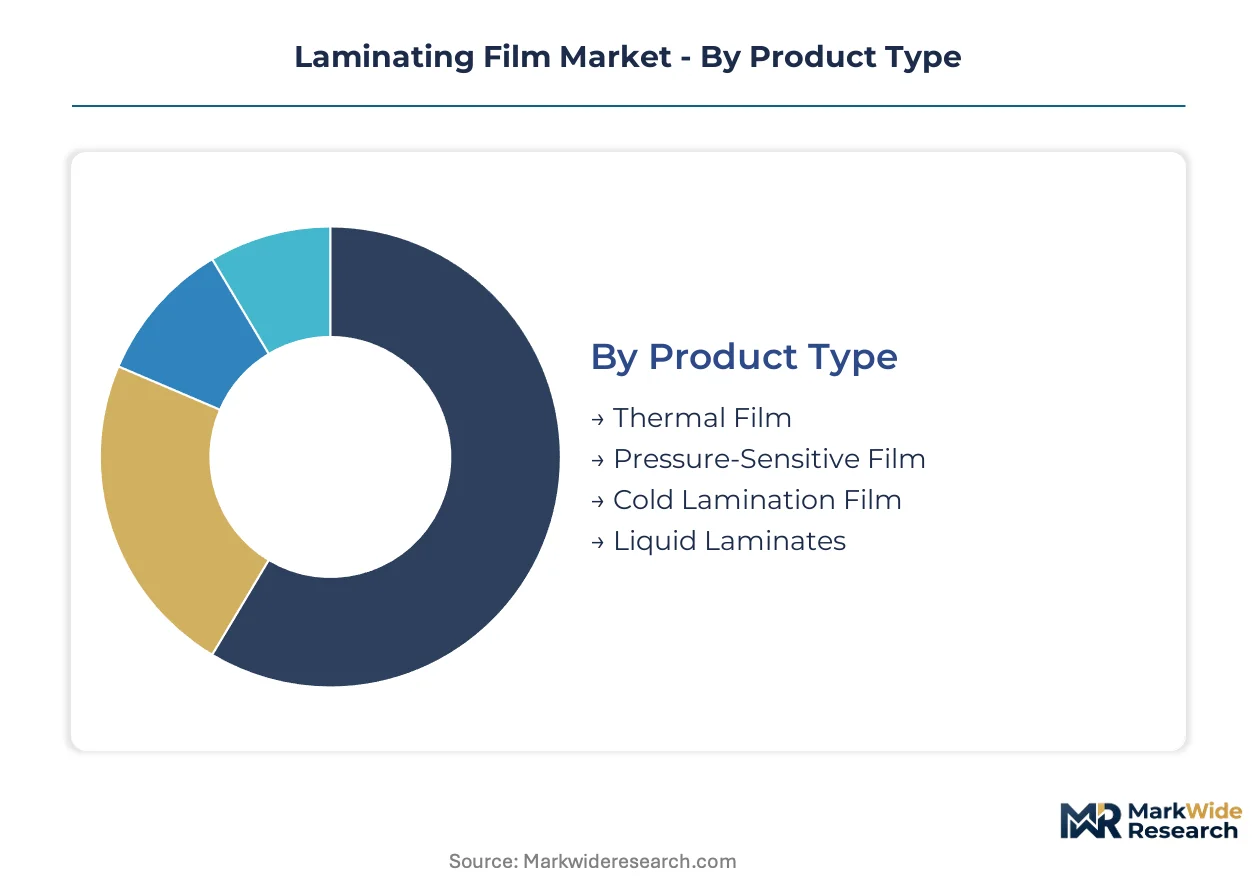
Segmentation in the laminating film market reveals how procurement priorities diverge across buyer types. Thermal film specifications dominate industrial packaging workflows, while pressure-sensitive formats serve fragmented commercial print operations with fundamentally different cost structures.
Product Type:
Buyers differentiate primarily by application speed versus setup flexibility tradeoffs.
- Thermal Film:Heat-activated polyethylene and polyester constructions bond through thermal rollers at 25-250 micron gauges. Maharashtra and Gujarat industrial corridors concentrate procurement where high-speed packaging lines prioritize throughput velocity over job-change agility.
- Pressure-Sensitive Film:Acrylic or rubber-based adhesives enable tool-free application without heat activation. German and Dutch short-run label converters favor this format for compressing make-ready intervals from hours to minutes in digital print workflows.
- Cold Lamination Film:Pressure-activated bonding eliminates thermal equipment requirements. Education sector buyers in budget-constrained districts favor this format for in-house document protection without capital investment.
- Liquid Laminates:UV-curable or water-based coatings applied via roller or spray systems. Wide-format print shops serving outdoor signage specify these for conforming to irregular substrates that rigid films cannot cover.
Volume sits with Thermal Film; growth tilts toward Pressure-Sensitive Film.
Technology:
Process selection hinges on regulatory jurisdiction and capital intensity tolerance.
- Extrusion:Molten polymer forced through dies creates multilayer substrates with controlled gauge uniformity. Backward-integrated producers like Cosmo Films leverage captive polyester resin production to absorb feedstock volatility without margin erosion.
- Coating:Adhesive deposition onto carrier films via gravure or slot-die methods. Belgian and northern Italian facilities are retrofitting exhaust systems under ECHA substance evaluation timelines for phthalate and isocyanate substitution.
- Solvent-Based:Organic solvent carriers enable rapid drying and strong bond formation. Asian converting operations retain this platform for cost-sensitive export production despite REACH-driven reformulation pressure in European markets.
- Water-Based:Aqueous adhesive systems eliminate VOC emissions at the cost of slower drying curves. North American and European regulatory environments are accelerating R&D capital allocation toward this chemistry.
Extrusion commands installed capacity; Water-Based is climbing the fastest.
End User:
Specification authority varies dramatically between centralized procurement and fragmented purchasing.
- Packaging Industry:High-volume converters serving meal-kit and pharmaceutical segments mandate FDA food-contact compliance and EU Falsified Medicines Directive serialization features. BIS-certified barrier films are scaling for Indian agrochemical and pharmaceutical exports.
- Printing Services:Commercial print shops and label converters prioritize job-change speed and substrate versatility. Mass-customized cosmetics and craft beverage packaging drives pressure-sensitive film pairing with digital workflows.
- Office Supplies:Stapled distribution through retail channels emphasizes price-per-sheet metrics and universal machine compatibility. Standard thermal pouch formats dominate this procurement.
- Education Sector:School districts and universities specify cold lamination for document preservation and display materials. Budget cycles drive seasonal purchasing concentration.
Revenue concentrates in Packaging Industry; Printing Services delivers the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects order fragmentation and technical support requirements.
- Online Sales:E-commerce platforms aggregate small-lot buyers with standardized specifications. Office supplies and education procurement increasingly routes through this channel for price transparency.
- Retail Outlets:Big-box office supply chains stock thermal pouch assortments for immediate fulfillment. Geographic coverage determines shelf space allocation.
- Distributors:Regional converting specialists provide technical consultation and inventory financing. Industrial packaging buyers rely on distributor relationships for specification guidance and just-in-time delivery.
- Direct Sales:Large-format print shops and multinational packaging converters negotiate annual contracts directly with film manufacturers. Volume commitments secure customized gauge and adhesive formulations.
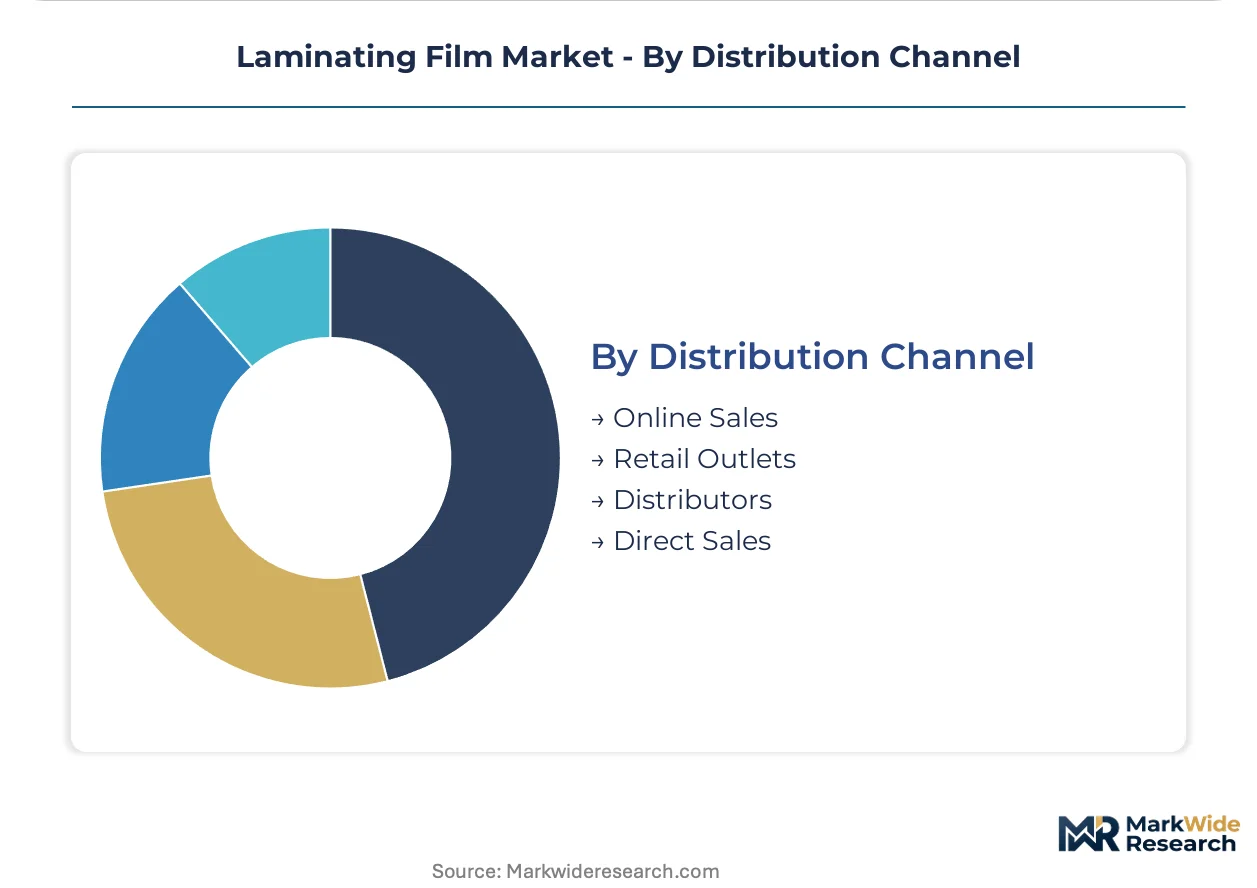
Distributors hold volume share; Online Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Maharashtra and Gujarat concentrate thermal film production capacity, drawing packaging converters through tax incentives and proximity to petrochemical feedstock corridors.
United States
Meal-kit packaging expansion and pharmaceutical serialization mandates drive certified substrate procurement. FDA food-contact regulations shape converter specifications for direct-contact applications. Midwest industrial corridors host high-throughput laminating operations serving CPG distribution networks.
Germany
Short-run digital printing workflows accelerate pressure-sensitive film adoption in commercial print shops. REACH authorization timelines force adhesive reformulation investments across coating facilities. Bavarian and North Rhine-Westphalian converting clusters retrofit exhaust systems under ECHA substance evaluation protocols.
China
Biaxially oriented polyester film production clusters supply downstream laminators across Asia-Pacific. GB standards enforcement through SAMR adds compliance layers for domestic and export markets. Yangtze River Delta and Pearl River Delta regions concentrate extrusion capacity serving global packaging demand.
India
Agrochemical and pharmaceutical export growth scales BIS-certified barrier film procurement. Bureau of Indian Standards mandates reshape specification authority in packaging procurement. Maharashtra and Gujarat industrial corridors dominate thermal film consumption on high-speed packaging lines.
Netherlands
Mass-customized cosmetics packaging drives pressure-sensitive film pairing with digital workflows. EU Green Deal sustainability scorecards alter brand-owner specification priorities. Randstad logistics hubs facilitate just-in-time distribution to Western European converting operations.
Laminating Film Market Vendor Landscape
European producers anchor the regulatory-compliance tier; Asian specialists hold cost-advantaged positions in export-oriented supply. Market structure tilts toward consolidation among backward-integrated resin producers, while fragmented coating converters compete on formulation agility. Two strategic archetypes dominate: captive polymer producers absorbing feedstock volatility, and formulation specialists pivoting toward water-based chemistries. Capacity expansion and adhesive reformulation partnerships constitute the primary competitive moves across jurisdictions.
Among diversified materials conglomerates, 3M and DuPont occupy positions exemplifying multi-segment portfolio breadth. Cosmo Films represents the backward-integrated archetype through captive polyester resin production. Mondi plc anchors the pulp-to-film vertical integration model across Central European operations. Avery Dennison sits within the specialty-coating tier, with formulation R&D programs addressing regulatory tightening across multiple jurisdictions.
| Leading Market Players |
|---|
| 3M |
| Cosmo Films |
| DuPont |
| Avery Dennison |
| Toray Plastics |
| Transilwrap |
| D&K |
| Mondi plc |
| UFLEX Limited |
| Others |
Supply Flow & Price Mechanics
BIS-certified barrier film mandates from Indian pharmaceutical and agrochemical exporters are compressing procurement timelines for certified substrates, forcing supply chains to absorb validation costs or cede volume to backward-integrated competitors. This specification pressure stratifies pricing across compliance tiers while concentrating procurement power among converters with captive testing capabilities.
Pricing Analysis
Short lead-time premiums command substantial markups as Maharashtra and Gujarat packaging corridors face compressed delivery windows for BIS-validated thermal films. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant European formulations from solvent-based Asian exports and spot-market commodity grades. Price differentiation hinges on certification tier and volume scale, with FDA food-contact notification and BIS migration testing adding substantial cost layers. Price erosion runs through economy-tier solvent platforms as Asian converters absorb margin compression to retain export share.
Supply Chain Analysis
Single-source vulnerability sits with biaxially oriented polyester film production clusters in China and South Korea, exposing downstream laminators to geographic concentration risk and freight cost spikes. Raw material dependencies draw from petroleum-based polyester and polyethylene resins, adhesive chemical feedstocks, and release liner substrates. Tariff exposure threatens cost structures as regulatory divergence between REACH-compliant European formulations and solvent-dependent Asian platforms fragments trade flows. Distribution runs through regional converting specialists providing technical consultation and inventory financing to industrial packaging buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive resin production and in-house coating capabilities determine margin sustainability against feedstock volatility and regulatory compliance cost escalation.
For Market Incumbents: Anchor market position through backward integration into polyester resin production to absorb petroleum-based feedstock volatility without margin erosion. Prioritize solvent-free coating R&D investments to preempt REACH authorization tightening across European jurisdictions. Defend against emerging water-based chemistry specialists by locking long-term supply agreements with pharmaceutical and meal-kit packaging converters requiring FDA food-contact certification. For New Entrants and Emerging Players: The price-point gap between premium REACH-compliant films and economy solvent-based grades creates entry space for mid-tier converters with hybrid formulation capabilities. Target underpenetrated rural India converting capacity in Bihar and Uttar Pradesh serving agricultural packaging cooperatives. Pursue white-label manufacturing partnerships with established distributors lacking captive coating facilities. For Investors and Strategic Acquirers: The window for entry favors backward-integrated mid-cap specialists with captive resin production and regional certification expertise across multiple jurisdictions. Long-term viability rests on exposure to pharmaceutical serialization compliance and sustainable packaging mandates reshaping brand-owner procurement. Monitor ECHA substance evaluation timelines for phthalate and isocyanate restrictions as inflection indicators for adhesive chemistry substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Cosmo Films and Mondi plc absorb feedstock volatility through captive polyester and pulp supply chains. |
| Solvent-Free Coating R&D Investment | Avery Dennison preempts REACH authorization tightening with UV-curable and electron-beam technology platforms. |
| BIS Certification Partnership | Converters serving Indian pharmaceutical exports secure barrier film mandates through Bureau of Indian Standards validation. |
| Rural India Capacity Expansion | Regional converters penetrate Bihar and Uttar Pradesh agricultural packaging cooperatives with localized production. |
| Pharmaceutical Serialization Compliance | Tamper-evident laminated labels with EU Falsified Medicines Directive features capture track-and-trace mandate demand. |
Methodological Framework
Document review covered customs and trade flow databases, SEC 10-K filings, and ECHA substance registration data, complemented by interviews with plant managers at coating facilities, procurement leads at downstream packaging converters, distribution channel partners, and technical R&D directors specializing in adhesive formulation. Bottom-up volume estimates from extrusion and coating capacity utilization were triangulated against top-down demand projections from end-use sector procurement patterns.
Cross-referencing historical pricing trajectories against panel input from industry stakeholders shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, coating technology, end-user industry, and geographic production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating pharmaceutical serialization compliance mandates and sustainability scorecard penetration in Western European and North American brand-owner procurement.
Inputs from ECHA substance evaluation timelines and BIS certification registries were available through the study window; gaps in real-time coating facility utilization rates introduce uncertainty bands around capacity expansion assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Co Extruded Films Market
Poly film
PVC Film for Medical Market
Poly film
Vietnam Plastic Packaging Films Market
Poly film
Polycarbonate Films Market
Poly film
MDO-PE Films Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
Twist Wrap Film Market
Poly film
PP Laminating Films Market
Poly film
Cleanroom Film and Bags Market
Poly film
Chocolate Wrapping Films Market
Poly film
Global Reclosable Films Market
Poly film
Blown Film Extruder Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market