
 France Plastic Packaging Films Market | 2026-2036
France Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
France Plastic Packaging Films Market Insights
Asset-light leasing models for extrusion equipment is narrowing the capital barrier for mid-tier converters seeking to compete with integrated multinationals. Toray Films Europe leverages its captive resin compounding and biaxial orientation lines to sustain margin control across specialty barrier grades. Berry Global Inc. anchors its position through blown film capacity concentrated near French agricultural supply chains. Klöckner Pentaplast differentiates via pharmaceutical-grade cleanroom certification that commands premium positioning in drug blister packs.
France plastic packaging films comprise polymer-based flexible substrates typically manufactured through blown or cast extrusion processes, with thicknesses ranging from ultra-thin films below 12 microns to heavy-gauge structures exceeding 100 microns, engineered primarily for product containment, preservation, and unitization across industrial and consumer supply chains. Barrier films lead value generation due to oxygen and moisture transmission specifications demanded by protein and dairy processors, while stretch films dominate volume throughput in palletized logistics for the food industry. Cast film extrusion occupies the most mature margin pool, whereas co-extrusion lines are attracting capital as brand owners specify multi-layer structures with discrete functional layers for recyclability.
ANSES and ADEME jointly shape compliance pathways for food-contact materials and circular economy targets, while the EU Single-Use Plastics Directive transposed into French law mandates minimum recycled content thresholds that redirect procurement toward post-consumer feedstock-qualified suppliers. The AGEC anti-waste statute imposes eco-modulated extended producer responsibility fees that penalize non-recyclable multi-material laminations. Stakeholders must monitor how rapidly mechanical recycling infrastructure scales to absorb the volume shifts that regulatory timelines are forcing through specification changes.
Market Dynamics
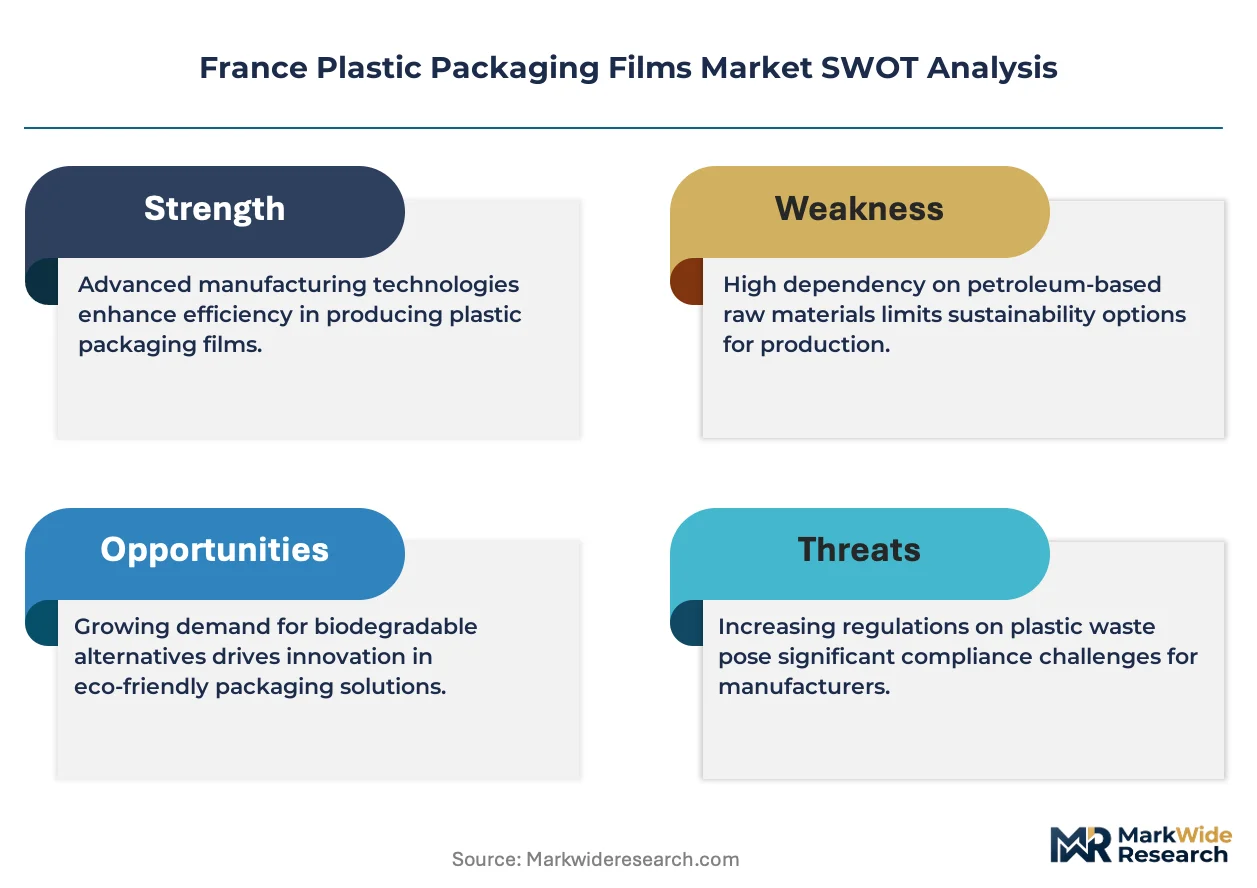
France's plastic packaging films sector is compressing under the AGEC law's eco-modulated extended producer responsibility framework, which penalizes multi-material laminations and forces specification changes across the entire converter base before mechanical recycling infrastructure can absorb the volume shifts.
Growth Catalysts
- AGEC Anti-Waste Statute:The eco-modulated EPR fee structure creates direct financial pressure for mono-material designs, accelerating converter investment in recyclable barrier architectures.
- Île-de-France Logistics Concentration:Paris-based distribution centers and packaging converters cluster near major freight corridors, reducing film transportation costs for fresh food retail chains.
- High-Performance Barrier Films:Protein and dairy processors specify oxygen and moisture transmission rates that extend shelf life, driving premium film specifications across the cold chain.
Market Restraints
- Post-Consumer Feedstock Scarcity:Mechanical recycling infrastructure in France lacks capacity to supply qualified recycled resin at the volumes mandated by EU Single-Use Plastics Directive thresholds.
- Resin Price Volatility:Polypropylene and polyethylene input costs fluctuate with naphtha-cracker economics in Northwest Europe, squeezing converter margins on fixed-price annual contracts.
- Multi-Material Technical Lock-In:Existing co-extrusion lines and barrier specifications cannot be retrofitted to mono-material designs without capital-intensive line reconfiguration.
Strategic Opportunities
- Pharmaceutical-Grade Certification:Cleanroom-certified film production for drug blister packs commands premium positioning as ANSM tightens food-contact material oversight.
- Bio-Based Feedstock Integration:ADEME circular economy targets create procurement incentives for converters qualifying bio-attributed resins through mass-balance certification.
- Asset-Light Equipment Leasing:Extrusion line leasing models lower capital barriers for mid-tier converters seeking to compete with integrated multinationals in specialty barrier grades.
Industry Challenges
- Mono-Material Design Expertise Gap:Formulation chemists capable of engineering barrier performance without adhesive lamination layers command scarcity premiums and extended recruitment timelines.
- Recyclability Certification Bottlenecks:ANSES and Citeo qualification protocols for food-contact recycled content create multi-month approval delays that mismatch brand owner launch schedules.
- Legacy Line Integration Complexity:Retrofitting cast film extrusion assets for digital thickness control and inline spectroscopy requires operational downtime that conflicts with just-in-time delivery commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Plastic Packaging Films Market |
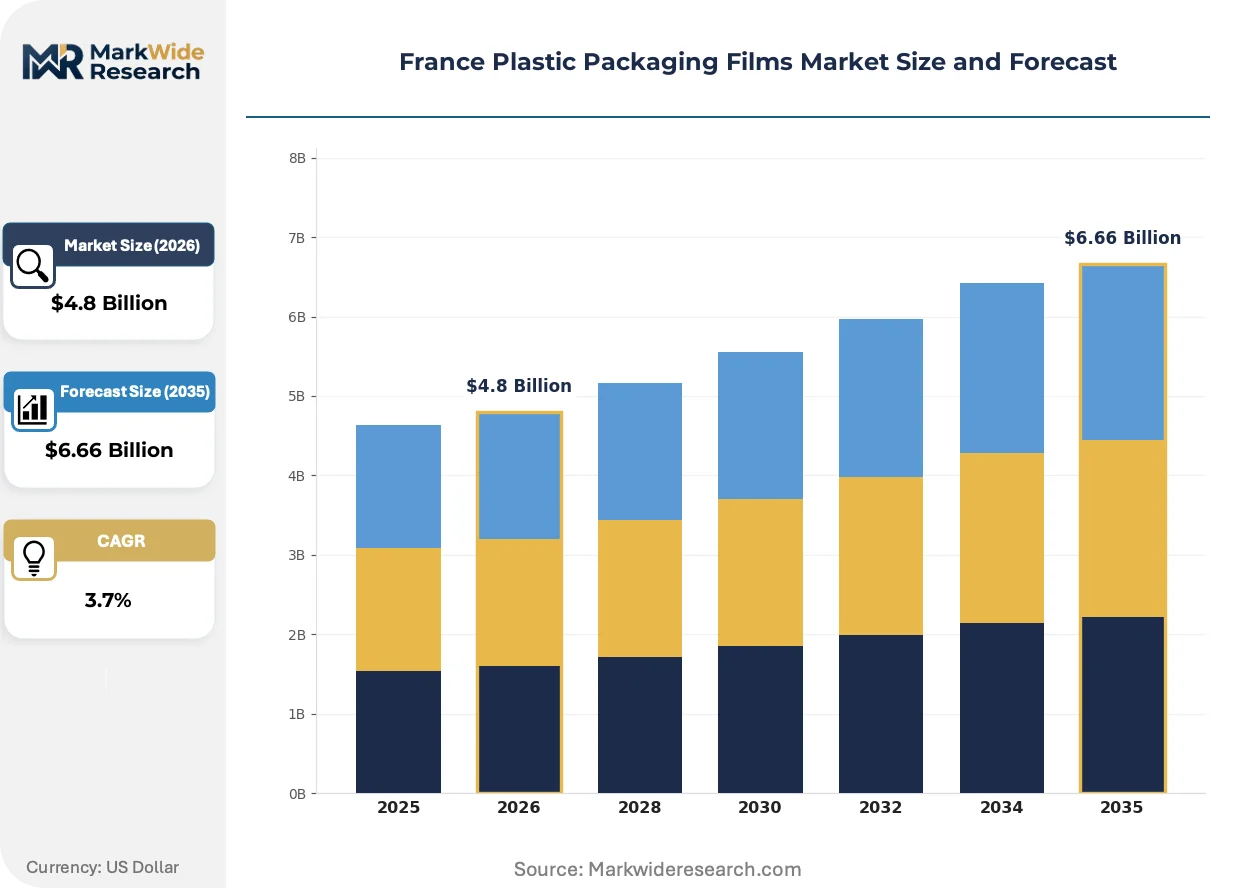
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, Iron-on Film End User: Food Industry, Pharmaceutical Sector, Cosmetic Sector, Electronics Packaging Production Process: Blown Film Extrusion, Cast Film Extrusion, Co-extrusion, Thermoforming Thickness: Thin Film, Medium Film, Thick Film, Ultra-thin Film |
| Companies Covered | Toray Films Europe, Innovia Films (CCL Industries Inc.), Berry Global Inc., Klöckner Pentaplast, Groupe Barbier, Trioworld Group, Polyfilms, Compagnie de Saint-Gobain, Cosmo Films, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Plastic Packaging Films Market Trends and Innovations
Active specification rewriting across French retail and pharmaceutical supply chains is compressing traditional multi-layer architectures into recyclable mono-material alternatives, with technology migration and regulatory compliance timelines running in parallel tension.
Barrier film formulation is migrating from ethylene-vinyl alcohol copolymer and aluminum oxide metallization toward high-density polyethylene with plasma-enhanced chemical vapor deposition. Dairy and meat processors in Brittany and Normandy are piloting these structures for 12-18 month validation cycles. The technology is migrating from niche organic produce applications toward mainstream protein packaging as Citeo recyclability certification becomes a procurement gate.
ANSES and ADEME jointly enforce the AGEC law's food-contact material pathways and circular economy targets, creating overlapping compliance obligations for converters. The industrial consequence is mandatory third-party certification for post-consumer recycled content claims before products reach French retail shelves. Pharmaceutical blister pack manufacturers face the tightest timelines, as ANSM drug packaging regulations now reference the same recyclability standards as consumer goods.
Fresh food retail chains are consolidating film procurement through central buying offices in Paris, displacing regional converter relationships that dominated the 2010s. Hypermarket and hard-discount banners now specify pan-French supply contracts with recyclability clauses that override local sourcing preferences. The concentration is most visible in the Île-de-France region, where Carrefour and Auchan headquarters direct specification changes that cascade through national agricultural supply chains within single growing seasons.
France Plastic Packaging Films Market Segmentation
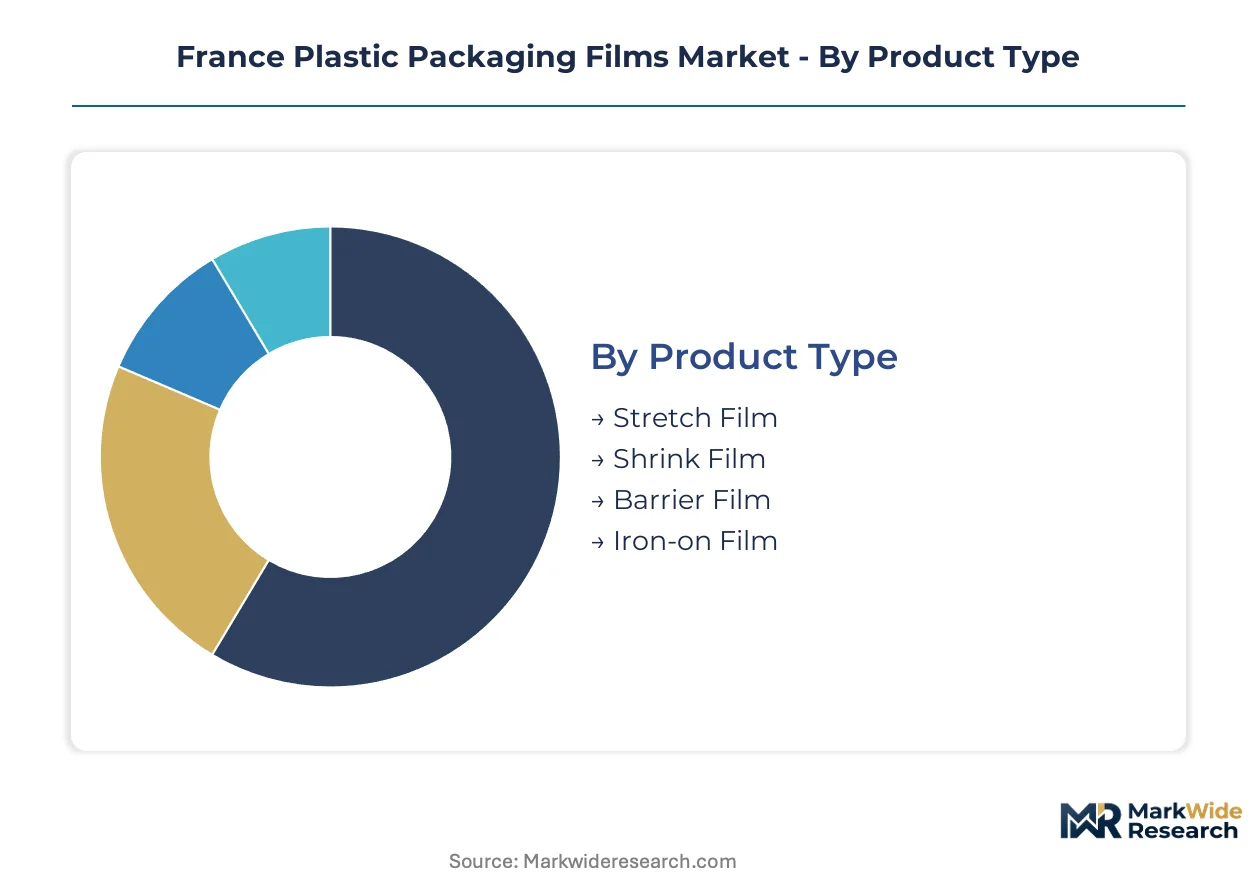
Segmentation in the France plastic packaging films market exposes how regulatory pressure and end-use performance requirements fracture demand across incompatible technical specifications. Each dimension reveals distinct procurement patterns that converters must navigate simultaneously.
Product Type:
After-sales service intensity varies sharply across film categories, with barrier films demanding formulation troubleshooting and metallization line maintenance contracts that stretch film suppliers rarely match.
- Stretch Film:Linear low-density polyethylene formulations dominate pallet unitization for Île-de-France distribution centers. Demand concentrates in automated wrapping systems where thickness consistency reduces film breakage downtime.
- Barrier Film:Multi-layer co-extruded structures with ethylene-vinyl alcohol or aluminum oxide layers preserve protein and dairy shelf life. Brittany meat processors and Normandy cheese makers specify oxygen transmission rates below 1 cc/m²/day, driving premium resin selection.
- Shrink Film:Polyolefin formulations conform to irregular product geometries for retail-ready packaging. Food retail chains in Paris specify high-clarity grades for produce display applications.
- Iron-on Film:Heat-activated adhesive layers bond to textile substrates for industrial labeling and garment protection. Specialty converters in Lyon supply automotive and aerospace maintenance sectors.
By volume, stretch film leads. By growth pace, barrier film is ahead as AGEC recyclability mandates force specification upgrades.
End User:
Cost tier differentiation separates commodity film buyers from pharmaceutical and cosmetic purchasers who absorb premium pricing for certified cleanroom production.
- Food Industry:Protein processors, dairy cooperatives, and fresh produce distributors account for the dominant share of film consumption. Cold chain logistics in the Île-de-France corridor specify high-performance barrier grades.
- Pharmaceutical Sector:ANSM-mandated cleanroom certification for drug blister packs creates entry barriers. Klöckner Pentaplast and Toray Films Europe compete on particulate contamination controls.
- Cosmetic Sector:Premium skincare and fragrance brands specify metallized films with holographic security features. Paris-based luxury houses drive demand for custom-printed laminated structures.
- Electronics Packaging:Antistatic and moisture-barrier films protect semiconductor components during transit. Toulouse aerospace suppliers and Grenoble microelectronics clusters specify dessicant-integrated pouches.
By volume, food industry consumption dominates. By margin expansion, pharmaceutical sector demand is climbing the fastest.
Production Process:
Application requirements dictate process selection, with blown film serving commodity volume and co-extrusion capturing multi-layer functional specifications.
- Blown Film Extrusion:Annular die extrusion with air cooling produces biaxially oriented films for stretch and shrink applications. Berry Global Inc. concentrates capacity near French agricultural supply chains.
- Cast Film Extrusion:Chill-roll casting yields high-clarity, uniform-thickness films for lamination and printing. The most mature margin pool faces pressure from energy-intensive drying requirements.
- Co-extrusion:Multi-layer die heads combine disparate resins into functional sandwiches. Brand owners now specify discrete recyclable layers to meet Citeo certification protocols.
- Thermoforming:Heated sheet forming creates rigid trays and blisters from cast film feedstock. Pharmaceutical cleanroom operations in the Grand Est region favor inline thermoforming for contamination control.
By installed capacity, blown film extrusion leads. By capital inflow, co-extrusion lines are gaining share fastest as converters retrofit for mono-material recyclability.
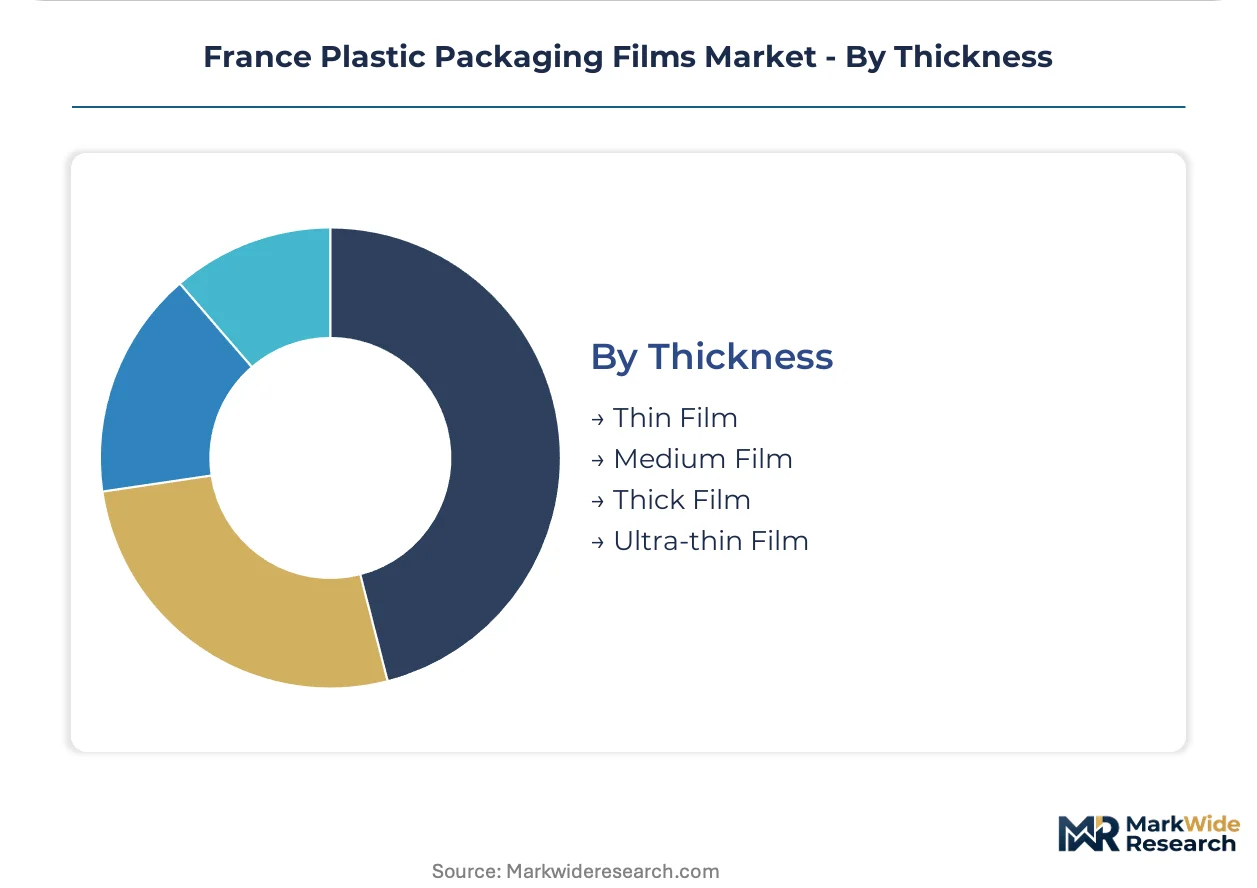
Thickness:
Volume scale inversely correlates with thickness, as ultra-thin films serve high-area coverage applications while thick films target structural protection.
- Thin Film:12-25 micron gauges serve secondary packaging and overwrap functions. Supermarket distribution centers in Lyon and Marseille specify thin stretch films for cost-efficient palletization.
- Medium Film:25-50 micron structures balance mechanical strength with material economy. The standard specification for most food-contact barrier applications.
- Thick Film:50-100 micron gauges provide puncture resistance for industrial unitization and construction membrane applications. Building supply distributors in the Hauts-de-France region specify UV-stabilized grades.
- Ultra-thin Film:Below 12 micron gauges reduce material intensity for environmental compliance. Emerging applications in produce wrapping face technical challenges in tear resistance and sealing performance.
By volume throughput, medium film leads. By specification innovation, ultra-thin film is expanding most quickly as AGEC eco-modulated fees penalize material overuse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's plastic packaging films trade flows reflect a structural deficit in specialty barrier grades, with Île-de-France distribution centers importing high-performance substrates while exporting commodity stretch films to neighboring Benelux markets.
Île-de-France
Paris-based retail headquarters and logistics corridors concentrate film procurement decisions for national grocery chains. ANSES food-contact compliance pathways shape converter qualification timelines. Citeo operates its largest sorting and recycling certification facility in the region, validating post-consumer feedstock claims for brand owners.
Auvergne-Rhône-Alpes
Lyon's specialty chemical cluster supplies formulation additives for barrier film compounding. The AGEC law's eco-modulated fees hit regional converters hard due to legacy multi-material lamination capacity. Saint-Étienne houses pharmaceutical packaging cleanroom operations serving ANSM-regulated drug blister supply chains.
Provence-Alpes-Côte d'Azur
Marseille-Fos port infrastructure handles imported resin feedstocks for regional blown film extrusion. Fresh produce exporters in the Var specify ultra-thin films to minimize AGEC material-intensity penalties. The Nice-Cannes corridor sustains niche demand for metallized cosmetic packaging films.
Hauts-de-France
Dunkirk's petrochemical complex anchors polyethylene resin supply for northern converters. Building supply distributors specify thick-gauge UV-stabilized films for construction membrane applications. Lille-based logistics platforms source stretch films for cross-border palletized freight into Belgium.
Brittany and Normandy
Dairy cooperatives and meat processors pilot mono-material barrier structures to meet Citeo recyclability certification. Rennes and Caen host mid-tier converters retrofitting cast film lines for digital thickness control. Regional agricultural supply chains face compressed validation cycles as Paris buying offices mandate specification changes.
France Plastic Packaging Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper formulation expertise. The vendor base compresses into three recognizable tiers: integrated resin-to-film multinationals, regional converters with captive agricultural relationships, and niche specialists holding pharmaceutical cleanroom certifications. Consolidation pressure intensifies as AGEC recyclability mandates favor capital-heavy players capable of multi-layer co-extrusion retrofits. Two dominant competitive moves define current positioning: backward integration into resin compounding to secure margin control, and asset-light equipment leasing to lower entry barriers for mid-tier converters.
Among integrated multinationals, Toray Films Europe and Berry Global Inc. exemplify divergent strategic postures. Toray's biaxial orientation capability represents the resin-captive archetype, while Berry's proximity to French agricultural supply chains anchors a logistics-responsive model. Klöckner Pentaplast occupies the specialist tier, with pharmaceutical-grade cleanroom certification serving as a premium-positioning mechanism under tightening ANSM oversight. Regional fabricants like Groupe Barbier and Polyfilms sit between these poles, competing on converter-to-grower relationships that Paris-based central buying offices increasingly displace.
| Leading Market Players |
|---|
| Toray Films Europe |
| Innovia Films (CCL Industries Inc.) |
| Berry Global Inc. |
| Klöckner Pentaplast |
| Groupe Barbier |
| Trioworld Group |
| Polyfilms |
| Compagnie de Saint-Gobain |
| Cosmo Films |
| Others |
Pricing and Supply Chain Analysis
The A10 motorway freight corridor linking Paris to Normandy ports transmits resin cost volatility directly into converter pricing power, compressing margins for mid-tier suppliers while amplifying premium capture for integrated multinationals with captive polyethylene supply.
Pricing Analysis
Industrial OEM buyers anchor contract structures around annual volume commitments with price-adjustment clauses tied to naphtha-cracker feedstock indices. Three-tier pricing separates pharmaceutical-grade cleanroom film from standard food-contact barrier grades and commodity stretch film. Cost compression in the standard tier is intensifying because converters cannot pass through full resin volatility on fixed-price supermarket contracts. Protein processors and dairy cooperatives exhibit highest price sensitivity due to thin agricultural margins, while ANSM-certified drug blister pack buyers absorb premiums without volume elasticity.
Supply Chain Analysis
Polyethylene and polypropylene resin feedstocks draw from petrochemical complexes in Belgium, the Netherlands, and Germany, with naphtha-derived ethylene forming the dominant cost anchor. Masterbatch additives for oxygen barrier performance and slip agents for high-speed wrapping equipment represent critical formulation inputs. Single-source vulnerability concentrates in metallized film substrates where vacuum deposition capacity clusters with Toray Films Europe's Luxembourg operations. Distribution runs through Île-de-France logistics platforms serving national retail chains, with regional converters in Brittany and Normandy maintaining direct-to-grower relationships that Paris central buying offices increasingly displace.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France plastic packaging films market sits at a platform-economics inflection where Citeo recyclability certification operates as a gatekeeper function, with interoperability between mechanical recycling infrastructure and converter qualification protocols determining which suppliers capture volume shifts.
For Market Incumbents: Harden barrier film margins through backward integration into resin compounding and biaxial orientation capacity, neutralizing feedstock cost volatility that squeezes fixed-price contract profitability. Prioritize co-extrusion line retrofits for mono-material architectures before AGEC eco-modulated fee penalties render multi-layer lamination capacity stranded. Certification investment with ANSES and Citeo creates switching costs that defend against mid-tier converters leasing asset-light extrusion equipment.
For New Entrants and Emerging Players: Mid-tier pharmaceutical packaging converters in Auvergne-Rhône-Alpes represent the most penetrable entry point, as ANSM cleanroom certification requirements create scarcity premiums that incumbents cannot fully service. Ultra-thin film specifications for fresh produce applications in Provence-Alpes-Côte d'Azur offer white-space growth as AGEC material-intensity penalties accelerate demand for sub-12 micron gauges. A go-to-market angle anchored on mass-balance bio-attributed resin qualification through ADEME pathways differentiates against petroleum-dependent incumbents.
For Investors and Strategic Acquirers: Regional converters with captive agricultural relationships in Brittany and Normandy present consolidation targets, as their grower-direct positioning erodes under Paris-based central procurement consolidation. Long-term viability hinges on mechanical recycling infrastructure scaling to absorb volume shifts that regulatory timelines are forcing through specification changes. The signal to watch is Citeo certification queue lengths, which indicate whether recyclability-validated supply capacity is tightening or loosening relative to brand owner launch schedules.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply from Dunkirk petrochemical complex neutralizes naphtha-cracker margin volatility. |
| Mono-Material Co-Extrusion Retrofit | AGEC recyclability mandates render multi-layer lamination lines economically obsolete without capital reconfiguration. |
| ANSM Cleanroom Certification Investment | Pharmaceutical blister pack qualification creates premium pricing power under tightening drug packaging regulations. |
| Mass-Balance Bio-Attribution Qualification | ADEME circular economy targets redirect procurement toward converters with certified renewable feedstock claims. |
| Asset-Light Equipment Leasing Model | Extrusion line leasing lowers capital barriers for mid-tier converters competing with integrated multinationals. |
Research Methodology
Desk research of trade flow databases, customs records, and ANSES regulatory filings preceded structured interviews with extrusion line operators, retail procurement directors, dairy cooperative supply managers, pharmaceutical packaging engineers, and Citeo certification auditors. Secondary validation drew from SEC filings of listed packaging multinationals, EU Single-Use Plastics Directive implementation reports, and ADEME circular economy progress assessments. Bottom-up volume estimates from converter capacity utilization were triangulated against top-down demand projections from end-use sector consumption patterns.
Forecast assumptions held AGEC law implementation timelines and EU Single-Use Plastics Directive recycled content thresholds fixed across the analysis window, while varying resin price scenarios and mechanical recycling infrastructure buildout pace. Segmentation dimensions modeled include product type, end-use industry, production process, thickness grade, and regional production cluster. CAGRs were derived from slope analysis of normalized volume trajectories, with pharmaceutical sector demand curves and fresh food retail procurement concentration serving as primary forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in naphtha-cracker economics, agricultural commodity prices, or euro-zone industrial production would shift the trajectory. Material shifts in ANSES food-contact material pathways or Citeo recyclability certification protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Bundling Film Market
Poly film
In-Mould Label Film Market
Poly film
Cast Stretch Packaging Films Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
LDPE Films Market
Poly film
Foamed Polypropylene Films Market
Poly film
Light Reflective Film Market
Poly film
Biaxially Oriented Polypropylene (BOPP) Films Market
Poly film
Polyethylene Cast Film Market
Poly film
Laminated Packaging Films Market
Poly film
MDO-PE Films Market
Poly film
Laminating Film Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
Packaging Film Market