
 Printable Tags Market | 2026-2036
Printable Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Printable Tags Market Analytics
The EU Green Deal is rebalancing material specifications across European printable tag supply chains, compelling converters to certify substrates for recyclability and reduced chemical content. Avery Dennison Corporation leverages its polymer science portfolio to develop adhesive systems compatible with these mandates. Zebra Technologies Corporation anchors its position through thermal transfer and direct thermal printing ecosystems that integrate with enterprise asset management platforms. Brady Corporation specializes in harsh-environment identification products where regulatory compliance and durability intersect.
Printable tags are substrate-based identification media—typically paper, synthetic film, or textile—engineered to receive variable data through thermal, inkjet, or impact printing methods, with face stock weights ranging from 60 to 200 gsm and adhesive classes from removable to permanent. Their primary purpose spans inventory tracking, brand communication, regulatory disclosure, and supply chain authentication across physical goods ecosystems. Plastic tags lead volume in logistics and industrial applications where moisture resistance and mechanical durability justify unit cost premiums, while fabric tags capture margin pools in apparel branding where soft-hand feel and wash-cycle endurance command specialized coating and weaving processes. Digital printing represents the fastest-growing technology segment as brands demand shorter run lengths, versioned graphics, and regional customization without plate changeover economics.
FDA 21 CFR Part 201 governs drug labeling substrates and print permanence in pharmaceutical supply chains, while EPA TSCA Section 6 restricts certain phthalate plasticizers in synthetic tag films, and ISO 9001 quality management certification shapes supplier qualification protocols for multinational buyers. These frameworks collectively elevate material traceability and testing documentation from procurement preference to contractual requirement. Stakeholders must monitor evolving extended producer responsibility schemes and substrate carbon intensity disclosures as these criteria penetrate supplier scorecards and tender specifications.
Market Dynamics
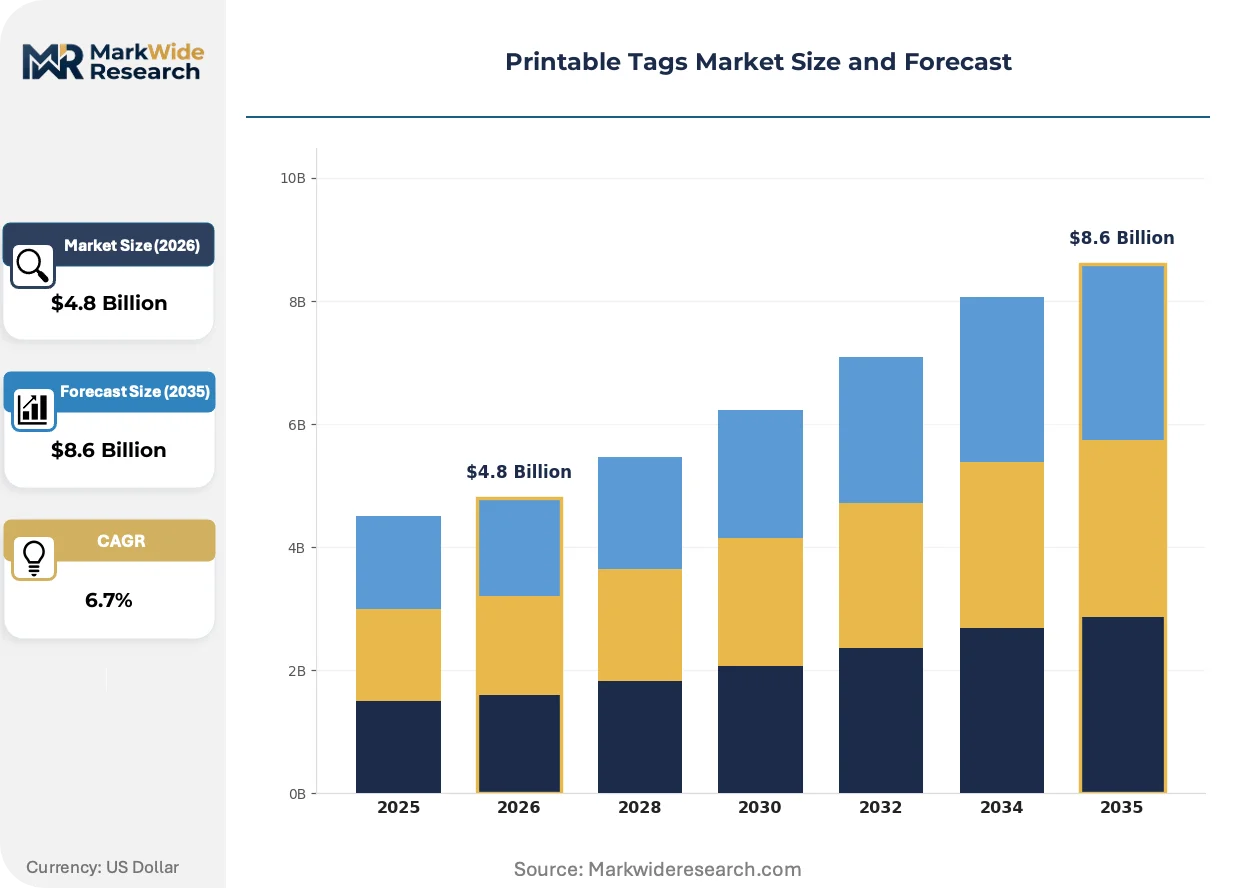
EU Green Deal packaging waste directives are forcing substrate recertification across European supply chains, while RFID integration in retail inventory systems accelerates demand for dual-capability tags that bridge physical and digital tracking ecosystems.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclability certification requirements are pulling converters toward bio-based adhesives and repulpable face stocks, expanding addressable substrate portfolios for compliant suppliers.
- RFID-thermal hybrid printing:Retailers deploying unified encoding and variable-data printing infrastructure are consolidating vendor relationships around suppliers offering integrated inlay and printable tag solutions.
- Automotive traceability standards:Germany's KBA and OEM part-marking specifications are mandating durable thermal-transfer tags for component lifecycle tracking through assembly and aftermarket service.
Market Restraints
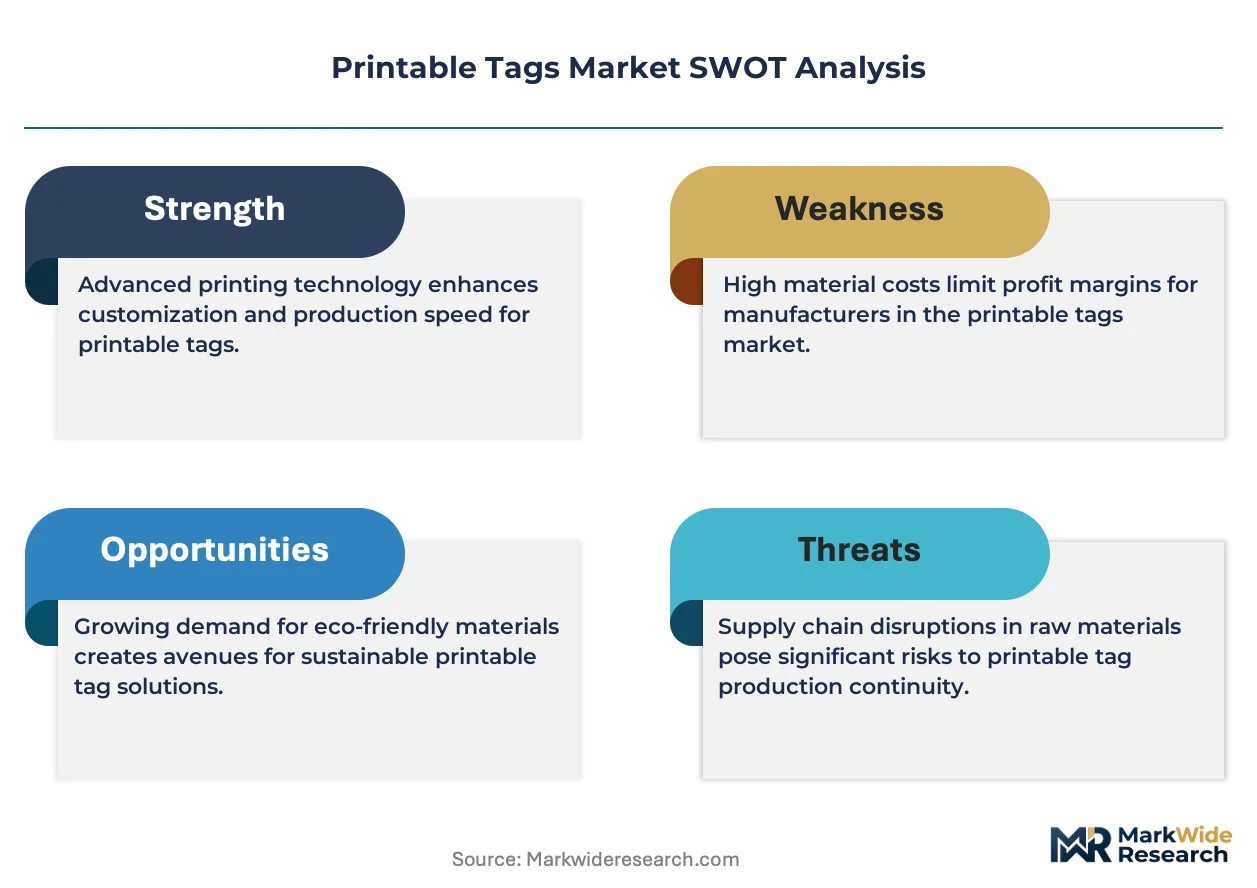
- Petrochemical input volatility:Synthetic film substrates depend on propylene and ethylene derivatives, exposing converters to margin compression when polymer feedstock prices spike.
- Adhesive supply concentration:Acrylic and rubber-based pressure-sensitive adhesive production clusters in Germany and the US, creating single-source vulnerability for European tag converters.
- Digital watermark substitution:Blockchain-linked digital product passports are displacing physical authentication tags in luxury goods and high-value electronics verticals.
Strategic Opportunities
- India apparel export labeling:PLI scheme incentives for textile manufacturing are expanding demand for wash-durable fabric tags with regional language variable printing.
- Pharmaceutical serialization convergence:Integration of tamper-evident substrates with track-and-trace compliance is opening premium positioning for converters with FDA 21 CFR Part 201 documentation capabilities.
- Direct-to-factory digital distribution:E-procurement platforms are compressing channel layers, enabling mid-size converters to capture margin previously absorbed by distribution intermediaries.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists capable of balancing adhesive tack, recyclability, and regulatory compliance command premium compensation and extended recruitment cycles.
- Multi-certification timelines:Concurrent ISO 9001, FSC chain-of-custody, and REACH SVHC documentation requirements extend supplier qualification periods to 12-18 months for multinational buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printable Tags Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Tags, Plastic Tags, Fabric Tags, Metal Tags End User: Retailers, Manufacturers, Event Organizers, Logistics Providers Application: Inventory Management, Branding, Pricing, Product Identification Technology: Digital Printing, Flexographic Printing, Screen Printing, Offset Printing |
| Companies Covered | Avery Dennison Corporation, Zebra Technologies Corporation, Brady Corporation, Sato Holdings Corporation, Smartrac Technology Group, CCL Industries, Multi-Color Corporation, 3M, R.R. Donnelley & Sons Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printable Tags Market Evolving Landscape
Variable-data printing infrastructure is fragmenting run-length economics while substrate chemistry and encoding technologies converge around circularity and traceability imperatives.
Digital inkjet printing systems with UV-curable or water-based formulations are modularizing short-run production workflows. Apparel brands and regional distributors are adopting these systems for same-day turnaround on versioned promotional tags. This modularizing capability is compressing minimum order quantities from thousands to hundreds of units, enabling mass customization without plate inventory costs.
REACH SVHC candidate list expansion is restricting certain halogenated flame retardants and phthalate plasticizers in synthetic tag films. Converters are reformulating polyethylene and polypropylene face stocks to maintain dimensional stability while eliminating restricted substances. German automotive and French cosmetics labeling supply chains are absorbing the highest compliance costs, driving qualification of alternative polymer grades from certified compounders.
Brand-owner sustainability scorecards are elevating substrate carbon intensity and end-of-life pathway documentation to primary selection criteria. Retail procurement teams are unbundling tag specifications from historical supplier relationships, issuing RFQs that weight recyclability certification above unit price. This behavioral shift is most pronounced in Benelux and Nordic markets where extended producer responsibility schemes assign packaging waste fees based on material recoverability.
Printable Tags Market Segmentation
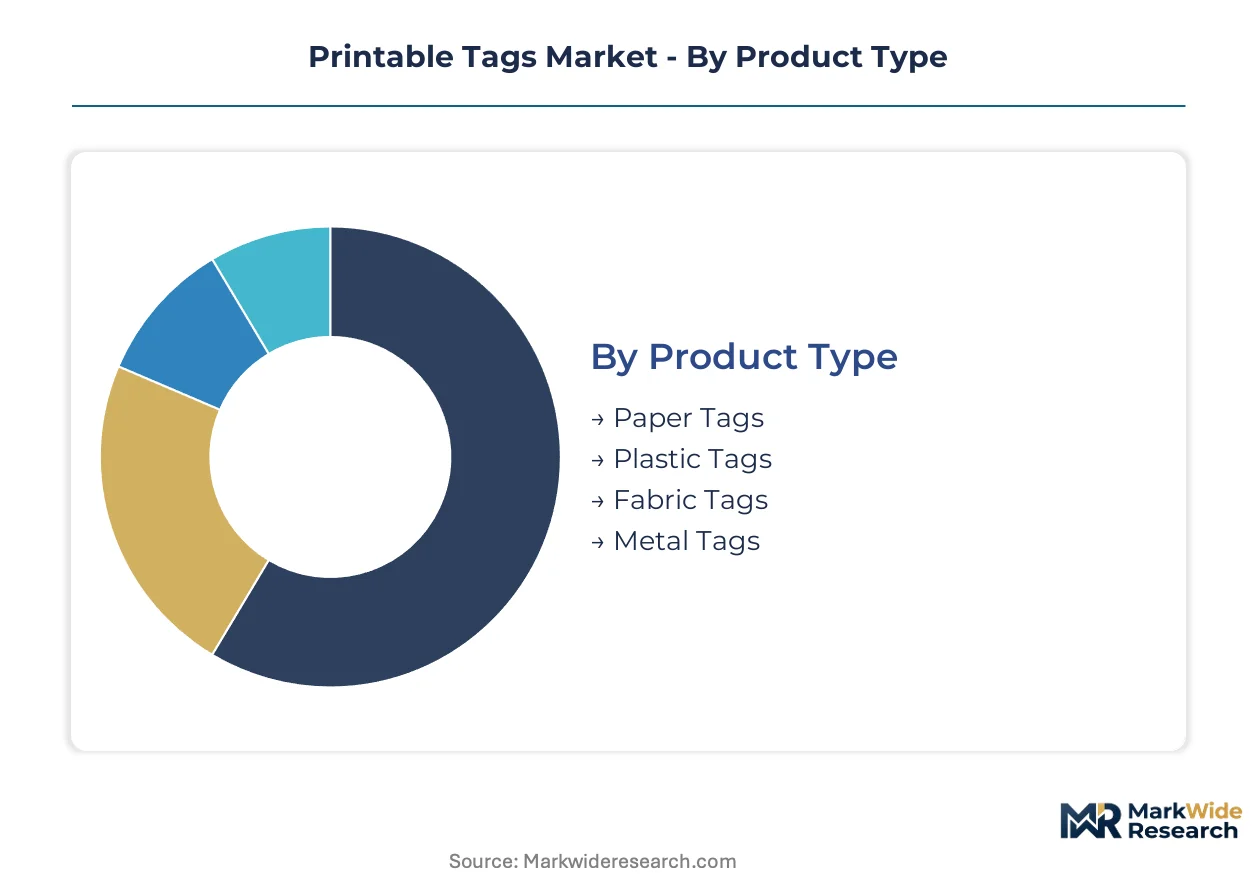
Printable tag specifications diverge sharply across end-use environments, with material selection and encoding technology determining compliance eligibility and unit economics. Procurement teams segment supplier portfolios by substrate durability requirements and variable-data integration needs rather than treating tags as commoditized consumables.
Product Type:
Supply concentration clusters around synthetic film converters in Germany and coated paper specialists in the Benelux region, creating distinct procurement corridors for moisture-resistant versus cost-optimized applications.
- Plastic Tags:Polyethylene and polypropylene face stocks with acrylic pressure-sensitive adhesives deliver moisture resistance and mechanical durability for logistics and industrial part marking. German automotive OEMs specify these substrates for component lifecycle tracking through KBA-mandated thermal-transfer encoding.
- Paper Tags:Coated and uncoated wood-pulp face stocks ranging from 60 to 200 gsm dominate retail pricing and promotional applications where unit cost minimization outweighs environmental exposure. Benelux retailers are migrating toward FSC-certified and repulpable grades under EU Green Deal packaging waste directives.
- Fabric Tags:Woven or printed textile substrates with soft-hand coatings serve apparel branding and care-label requirements.
- Metal Tags:Anodized aluminum or stainless-steel substrates withstand extreme temperatures and chemical exposure for industrial asset identification.
Plastic tags absorb the bulk of installed capacity; fabric tags are expanding most quickly.
End User:
Customer procurement sophistication varies by vertical, with pharmaceutical and automotive buyers imposing multi-certification requirements that filter supplier pools.
- Retailers:Omnichannel operators deploy RFID-thermal hybrid tags bridging physical inventory and digital tracking systems, consolidating vendor relationships around integrated inlay and printable substrate suppliers.
- Manufacturers:Industrial producers specify thermal-transfer tags for work-in-process tracking and finished-goods serialization, with German automotive suppliers driving demand for durable polymer face stocks.
- Event Organizers:Short-run badge and wristband applications favor digital inkjet-compatible synthetic papers with same-day turnaround requirements.
- Logistics Providers:Third-party warehousing and parcel carriers prioritize scan-rate reliability and all-temperature adhesive performance over substrate aesthetics.
Manufacturers absorb the bulk of installed capacity; retailers are expanding most quickly.
Application:
Functional requirements determine substrate-adhesive-ink system compatibility, with regulatory disclosure applications imposing the most stringent permanence and legibility standards.
- Inventory Management:Barcode and RFID-encoded tags for warehouse tracking and cycle counting require high-contrast print receptivity and abrasion-resistant topcoats.
- Branding:Apparel hangtags and promotional labels command premium positioning through specialty substrates, foil stamping, and variable-data personalization.
- Pricing:Point-of-sale tags and shelf labels prioritize cost-optimized paper stocks with removable or repositionable adhesive classes for frequent updates.
- Product Identification:Regulatory compliance labels for pharmaceuticals, chemicals, and electronics must satisfy FDA 21 CFR Part 201, REACH SVHC, and OEM part-marking specifications.
Inventory management absorbs the bulk of installed capacity; product identification is expanding most quickly.
Technology:
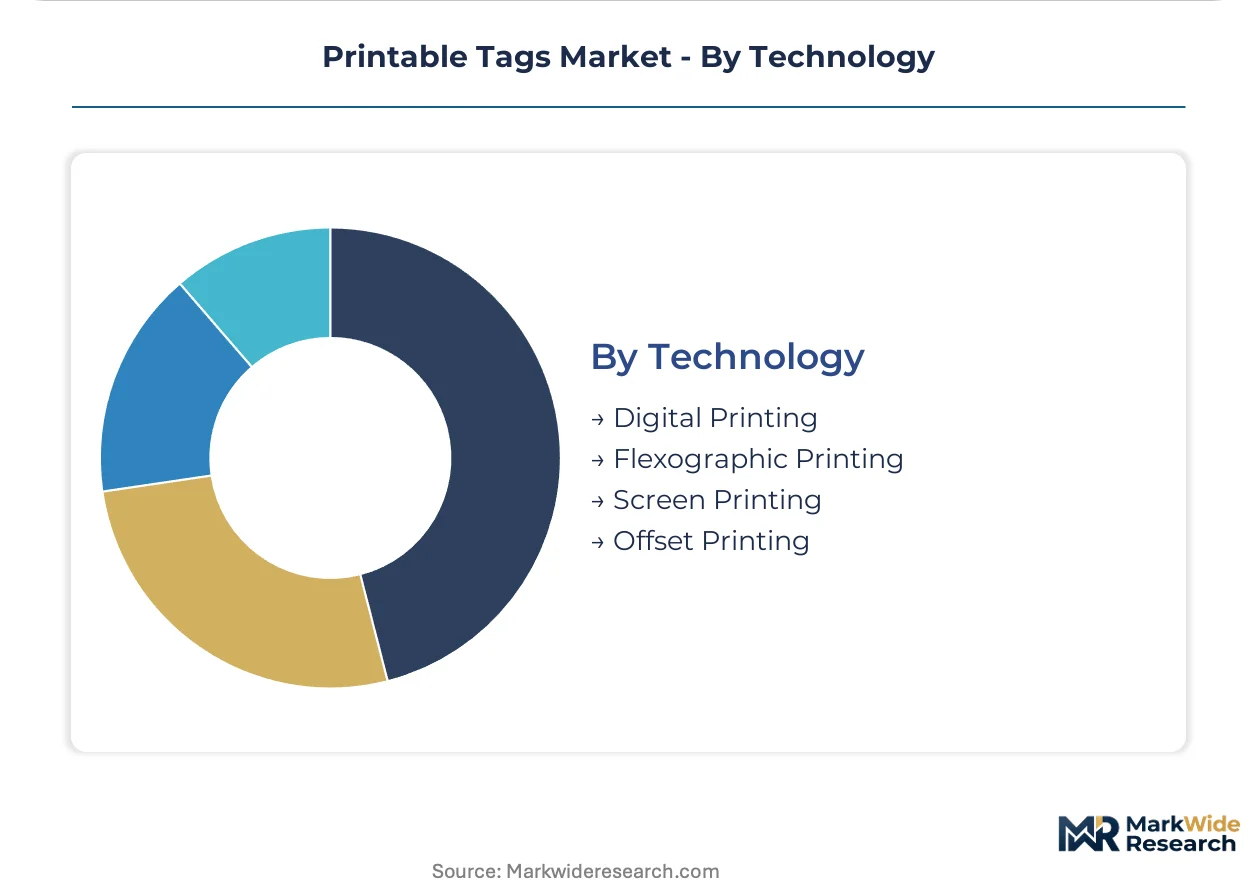
Capital equipment footprints and run-length economics stratify converter capabilities, with digital systems modularizing short-run production and conventional presses defending volume segments.
- Digital Printing:Inkjet and toner-based systems enable versioned graphics, regional customization, and lot-size-of-one production without plate inventory. Apparel brands and promotional marketers are adopting UV-curable and water-based inkjet for same-day turnaround on campaign-specific tags.
- Flexographic Printing:Rotary letterpress analog systems with photopolymer plates dominate high-volume label and tag production for retail and logistics accounts.
- Screen Printing:Thick-film ink deposition suits heavy-duty industrial tags requiring solvent resistance and outdoor durability.
- Offset Printing:Lithographic sheetfed systems capture premium cosmetic and electronics packaging tag segments requiring fine-line detail and color consistency.
Flexographic printing absorbs the bulk of installed capacity; digital printing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf-Cologne corridor anchors European printable tag substrate production, with converter clusters serving automotive OEMs and pharmaceutical serialization mandates. This industrial concentration shapes procurement patterns across the continent's labeling supply chains.
Germany
Automotive traceability requirements from KBA and OEM part-marking specifications drive demand for durable thermal-transfer tags. EU Green Deal packaging directives compel converters toward repulpable face stocks and bio-based adhesives. Stuttgart and Wolfsburg industrial corridors concentrate polymer film extrusion capacity for component lifecycle tracking.
United States
FDA 21 CFR Part 201 pharmaceutical labeling standards and EPA TSCA Section 6 chemical restrictions shape substrate compliance requirements. Retail RFID-thermal hybrid deployment accelerates through omnichannel inventory modernization. Chicago-Milwaukee manufacturing belt hosts thermal transfer ribbon and adhesive coating operations.
China
MIIT industrial standardization and dual carbon goals push converters toward lower-carbon intensity substrates. Apparel export manufacturing clusters demand wash-durable fabric tags with variable-data printing. Yangtze River Delta concentration around Shanghai and Suzhou integrates digital inkjet production with textile labeling supply chains.
India
PLI scheme textile manufacturing incentives expand demand for regional language variable printing on fabric tags. BIS quality certification and DGFT export documentation requirements elevate substrate traceability standards. Tiruppur and Surat apparel clusters drive adoption of same-day digital production workflows.
France
ANSM pharmaceutical labeling regulations and extended producer responsibility schemes assign packaging waste fees based on material recoverability. REACH SVHC compliance costs concentrate in cosmetics and luxury goods labeling supply chains. Lyon-Grenoble chemical corridor supplies reformulated polymer compounds for reduced-substance synthetic films.
Printable Tags Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and substrate customization capabilities. The vendor base stratifies between integrated material science conglomerates with polymer formulation capabilities and specialized converters focused on single technology segments. Two strategic archetypes dominate: adhesive and substrate compounders with captive raw material integration, and digital printing equipment OEMs bundling hardware with consumable supply contracts. Competitive moves center on M&A for adhesive technology access and capacity expansion in India and Southeast Asia to capture apparel export labeling growth.
Within the integrated material science tier, Avery Dennison Corporation and 3M exemplify compounders with polymer science portfolios spanning adhesive systems and face stock substrates. Zebra Technologies Corporation anchors the printing equipment and consumables convergence archetype. These three entities represent distinct competitive vectors: substrate-adhesive formulation depth, hardware-software integration, and enterprise asset management platform connectivity.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Zebra Technologies Corporation |
| Brady Corporation |
| Sato Holdings Corporation |
| Smartrac Technology Group |
| CCL Industries |
| Multi-Color Corporation |
| 3M |
| R.R. Donnelley & Sons Company |
| Others |
Value Network & Pricing Analysis
Polymer formulation chemist concentration in the Düsseldorf-Cologne corridor creates labor-cost differentials that widen pricing-tier spreads between premium certified substrates and commodity paper grades. These specialized workforce pools enable German converters to command value-based premiums for REACH-compliant synthetic films while Asian competitors compress unit economics on standard paper tags.
Pricing Analysis
Value-based pricing anchored to inventory tracking uptime and scan-reliability outcomes dominates RFID-thermal hybrid segments, separating premium certified suppliers from commodity converters. Price differentiation rests on ISO 9001 documentation depth and FSC chain-of-custody certification status. Cost compression in paper-based promotional tags is intensifying because digital inkjet modularization lowers entry barriers for short-run competitors. Mass-market retailers exhibit highest price sensitivity; pharmaceutical serialization buyers prioritize compliance documentation over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and the United States operate hub-and-spoke patterns serving converter networks across automotive and pharmaceutical corridors. Raw material dependencies include propylene derivatives for synthetic films, acrylic monomers for pressure-sensitive adhesives, and wood pulp for coated paper stocks. Single-source vulnerability concentrates in German adhesive coating operations. Distribution runs through converter-direct relationships with OEM procurement teams, bypassing traditional distribution intermediaries in e-procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EU Green Deal substrate recertification costs will force sub-scale converters into strategic exits or acquisition.
For Market Incumbents: To counter digital watermark substitution in luxury goods authentication, deepen backward integration into bio-based adhesive formulation and expand captive polymer compounding capacity in Stuttgart industrial corridors. Capture margin pools by consolidating RFID inlay and printable substrate offerings into unified enterprise asset management bundles. For New Entrants and Emerging Players: Digital inkjet workflow modularization offers the most penetrable wedge for same-day turnaround services in Indian apparel export clusters. Target Tiruppur and Surat textile manufacturing zones with regional language variable printing capabilities. Pursue direct-to-factory e-procurement channel partnerships bypassing established distribution layers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-size converters possessing concurrent ISO 9001, FSC, and REACH documentation capabilities given pharmaceutical serialization convergence tailwinds. Long-term viability favors suppliers with polymer science talent retention and multi-certification infrastructure. Watch for extended producer responsibility scheme expansion across Benelux and Nordic markets as inflection indicator for recyclability-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Formulation | Captures margin from German acrylic monomer suppliers while ensuring REACH SVHC compliance. |
| RFID-Thermal Hybrid Platform Integration | Consolidates vendor relationships for retailers deploying unified encoding infrastructure. |
| Capacity Expansion in Indian Apparel Corridors | Captures PLI scheme textile manufacturing growth with same-day digital production workflows. |
| Green Manufacturing Transition | Aligns substrate portfolios with EU Green Deal packaging waste directives and carbon intensity disclosures. |
| Long-term Supply Agreement with Automotive OEMs | Secures thermal-transfer tag volumes under KBA-mandated component lifecycle tracking specifications. |
Research Methodology
Document review covered SEC 10-K filings, EU ECHA substance registrations, and FSC chain-of-custody databases, complemented by interviews with polymer formulation chemists, automotive OEM procurement managers, pharmaceutical regulatory affairs leads, and retail category buyers. Secondary validation drew from customs trade data, ISO certification registries, and REACH SVHC candidate list updates. Bottom-up substrate volume estimates triangulated against top-down end-use demand models.
Segmented outputs across substrate type, printing technology, end-use vertical, and geographic production cluster informed value projections over the analysis window. CAGRs derived from regression against industrial production indices, retail inventory modernization spend, and pharmaceutical serialization compliance timelines. Model inputs included adhesive raw material price indices, digital printing equipment installation rates, and extended producer responsibility fee schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical feedstock volatility and accelerated digital product passport adoption. Outputs reflect documented assumptions around regulatory implementation timelines and technology substitution curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Die Cut Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Water Dissolvable Labels Market
Labels
Hot Melt Glue Labeler Market
Labels
ESD Protective Signage Labels Market
Labels
Direct Thermal Linerless Labels Market
Labels
Canning Labels Market
Labels
HAZMAT Labels Market
Labels
Sleeve Label Market
Labels
Linerless Labels Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
GCC Labeling Market
Labels
Global Laminated Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Cut and Stack Labels Market