
 In-Mould Label Film Market | 2026-2036
In-Mould Label Film Market Size, Share, and Industry Trends Forecast 2026-2036
In-Mould Label Film Market Foresight
Market Context
Digital printing integration with in-mould labeling workflows is fragmenting traditional supply relationships between converters and molders. CCL Industries leverages captive film extrusion capacity to control substrate quality across North American operations. Taghleef Industries anchors European supply through specialized biaxially oriented polypropylene lines designed for high-cycle injection molding. Constantia Flexibles competes via backward integration into coating and metallization, reducing dependency on external substrate suppliers.
Technical Definition and Segment Structure
In-mould label film denotes a pre-printed decorative substrate, typically polypropylene or polyethylene ranging from 30 to 80 microns in thickness, that fuses permanently with a plastic container during injection molding, blow molding, or thermoforming to deliver scratch-resistant, wash-off-proof branding. Polypropylene dominates material selection due to crystallinity matching common container resins and compatibility with existing recycling streams, while polyethylene gains traction in flexible packaging extensions where lower stiffness proves advantageous. Food packaging applications command the deepest margin pools owing to stringent migration limits and extended shelf-life requirements, whereas beverage containers represent the fastest-expanding application as carbonated soft drink and dairy brands convert from pressure-sensitive labels to in-mould solutions for line efficiency.
Regulatory Frame and Outlook
EMA food contact compliance, EU Packaging and Packaging Waste Regulation, and FDA indirect food additive standards govern substrate migration limits and recyclability claims across major demand centers. REACH chemical restrictions and evolving extended producer responsibility frameworks compel film producers to validate mono-material constructions and eliminate adhesive layers that contaminate mechanical recycling streams. Stakeholders must monitor polymer-to-polymer compatibility testing protocols and emerging digital watermark standards that will determine which substrate grades retain market access under tightening circular economy mandates.
Market Dynamics
Mono-material polypropylene constructions are displacing multi-layer substrates as EFSA migration limits and EU Green Deal recyclability mandates force reformulation across European food packaging supply chains.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases accelerates conversion to in-mould labeling from solvent-based wet glue systems in German dairy packaging.
- Injection molding cycle efficiency:Beverage brands in Italy adopt high-speed IML lines to eliminate post-mold labeling stations and reduce line footprint.
- Polypropylene crystallinity matching:Substrate-to-container resin compatibility enables clean mechanical recycling streams that satisfy emerging extended producer responsibility frameworks.
Market Restraints
- Propylene feedstock volatility:Crude oil price swings transmit directly to biaxially oriented polypropylene film margins, compressing converter profitability during cost spikes.
- Specialized molder concentration:High-precision IML mold fabrication clusters in southern Germany, creating geographic supply risk for converters outside Central Europe.
- Pressure-sensitive label substitution:Shrink sleeve technologies retain cost advantage in short-run promotional campaigns where IML minimum order quantities prove prohibitive.
Strategic Opportunities
- Indian food packaging modernization:FSSAI food contact compliance upgrades drive replacement of direct-printed containers with migration-tested IML solutions in Mumbai and Delhi processing corridors.
- Digital watermark integration:AIM DPP and GS1 standards enable substrate-embedded sorting signals that unlock premium recyclability certifications for mono-material constructions.
- Automotive interior applications:Decorative films for injection-molded dashboard components bypass leather wrapping costs while meeting NHTSA flammability standards.
Industry Challenges
- Multi-axis registration precision:Sustained ±0.1mm tolerance during high-speed molding demands specialized maintenance protocols that outstrip available technician training pipelines.
- REACH SVHC notification:Evolving substance of very high concern lists force continuous reformulation of slip agents and antistatic coatings, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Mould Label Film Market |
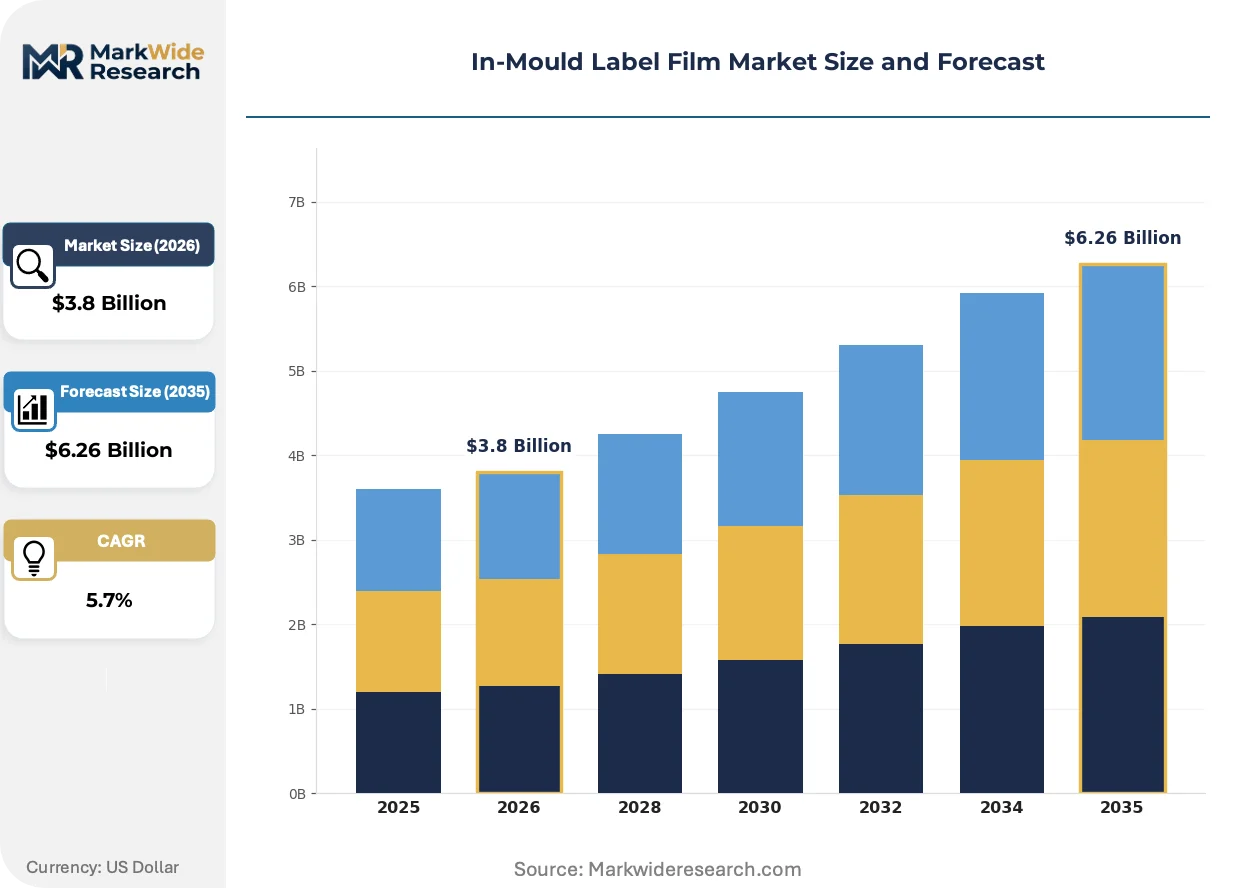
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, PVC, PET Application: Food Packaging, Consumer Goods, Electronics, Beverage Containers End User: Manufacturers, Brand Owners, Retailers, Distributors Technology: Digital Printing, Flexographic Printing, Offset Printing, Gravure Printing |
| Companies Covered | CCL Industries, Taghleef Industries, Constantia Flexibles, Coveris Holdings, Jindal Films Americas, Cosmo Films, Innovia Films, Avery Dennison, Huhtamaki Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Mould Label Film Market Shifts & Advancements
Workflow digitization and substrate chemistry advances are compressing traditional development cycles while regulatory chemistry restrictions force material redesigns across multiple jurisdictions simultaneously.
Water-based barrier coatings are collapsing the performance gap between mono-material polypropylene and metallized multi-layer constructions. Dairy and ready-meal brands in France and the Netherlands are transitioning production lines to these formulations to preempt EFSA migration threshold tightening. The shift is collapsing demand for ethylene vinyl alcohol copolymer tie layers that previously complicated mechanical recycling.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling film producers to eliminate fluorinated process aids from biaxial orientation lines. German compounders are validating silicone-based alternatives that maintain slip performance without contaminating recycling streams. Food contact notification timelines have extended by four to six months as EFSA reviews novel additive packages.
Brand owners are consolidating label procurement under single-source IML converters who control captive film extrusion and pre-press design. This pattern displaces fragmented purchasing across separate substrate, printing, and molding suppliers. The concentration is most pronounced in German automotive parts labeling and Italian personal care packaging.
In-Mould Label Film Market Segmentation
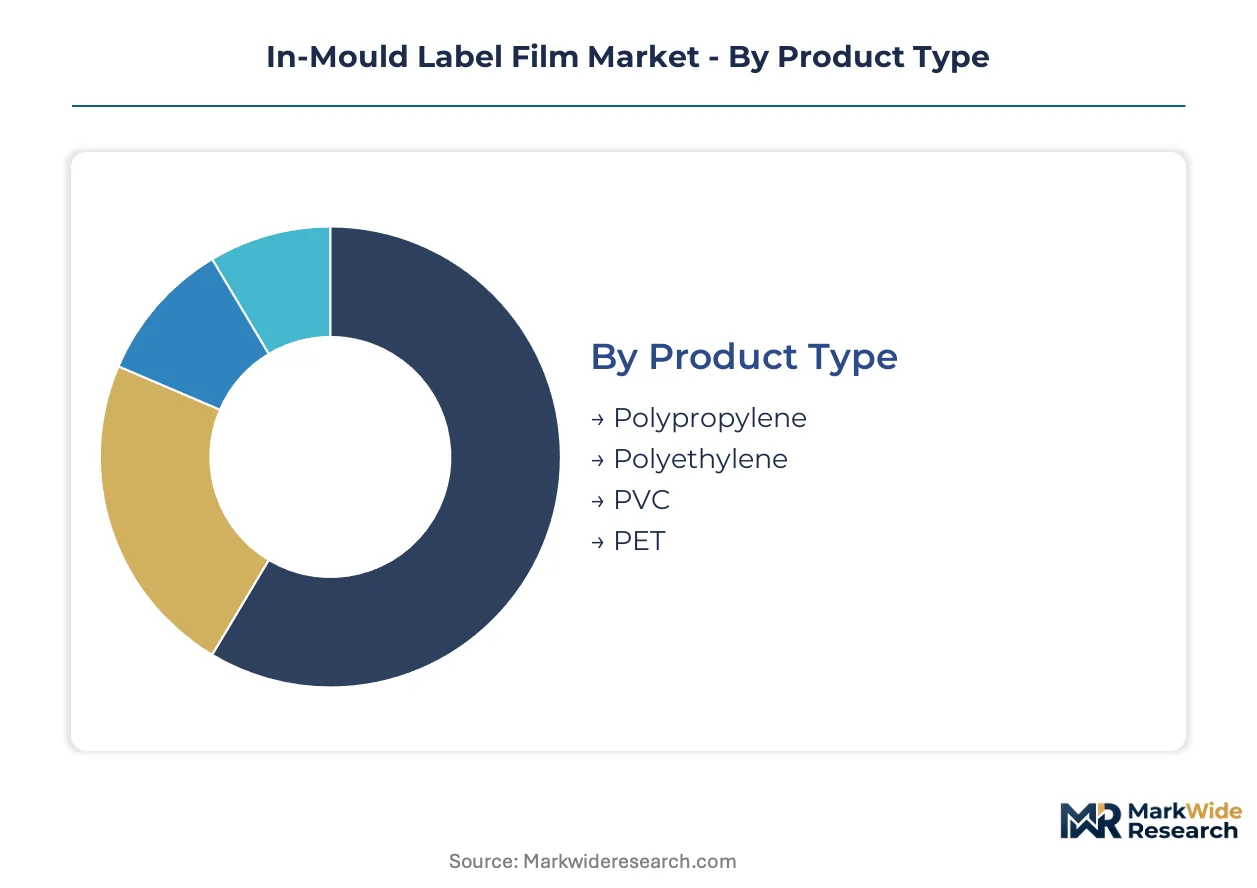
In-mould label film segmentation reflects the tension between substrate chemistry compatibility and end-use performance requirements. Material selection directly determines recyclability credentials and migration compliance, while application verticals impose divergent tolerance specifications and volume scales.
Product Type:
Material composition defines crystallinity matching with container resins and downstream sorting compatibility in mechanical recycling streams.
- Polypropylene:Biaxially oriented grades dominate food contact applications due to crystalline structure alignment with common thermoplastics. German dairy processors specify mono-material PP constructions to satisfy EFSA migration limits and EU Green Deal recyclability mandates.
- Polyethylene:Lower stiffness profiles enable flexible packaging extensions where container deformation tolerance exceeds rigid requirements. Indian converters in Mumbai processing corridors adopt PE films for FSSAI-compliant ready-meal trays.
- PVC:Cost-positioned for non-food industrial containers with limited thermal stress exposure.
- PET:High-clarity grades serve premium cosmetic packaging requiring glass-like aesthetic properties.
Polypropylene commands the established base. The steepest expansion runs through polyethylene as flexible packaging converters seek mono-material alternatives.
Application:
End-use verticals impose distinct regulatory thresholds, shelf-life demands, and line speed requirements that filter substrate specifications.
- Food Packaging:EFSA migration limits and extended shelf-life requirements drive specification rigor. French and Dutch dairy brands are transitioning to water-based barrier coatings to preempt tightening thresholds.
- Beverage Containers:Carbonated soft drink and dairy brands convert from pressure-sensitive labels to capture line efficiency gains. Italian bottlers deploy high-speed IML lines to eliminate post-mold labeling stations.
- Consumer Goods:Personal care and household product containers prioritize scratch resistance and wash-off-proof branding.
- Electronics:Precision tolerance requirements for small-form-factor device housings limit qualified supplier pools.
Food packaging absorbs the deepest margin investment. Beverage containers are climbing the fastest as carbonation-resistant constructions gain technical validation.
End User:
Procurement authority concentration varies sharply across value chain positions, with backward integration reshaping traditional supplier relationships.
- Brand Owners:Consolidating label procurement under single-source IML converters who control captive film extrusion and pre-press design. This pattern displaces fragmented purchasing across separate substrate, printing, and molding suppliers.
- Manufacturers:Mold fabricators in southern Germany cluster high-precision IML tooling capacity, creating geographic supply risk for converters outside Central Europe.
- Retailers:Private-label packaging programs impose cost discipline that favors standardized substrate specifications over custom formulations.
- Distributors:Stock-and-sell positioning limited to commodity-grade films without food contact compliance requirements.
Brand owners concentrate strategic sourcing leverage. Manufacturers retain technical gatekeeper status through mold fabrication specialization.
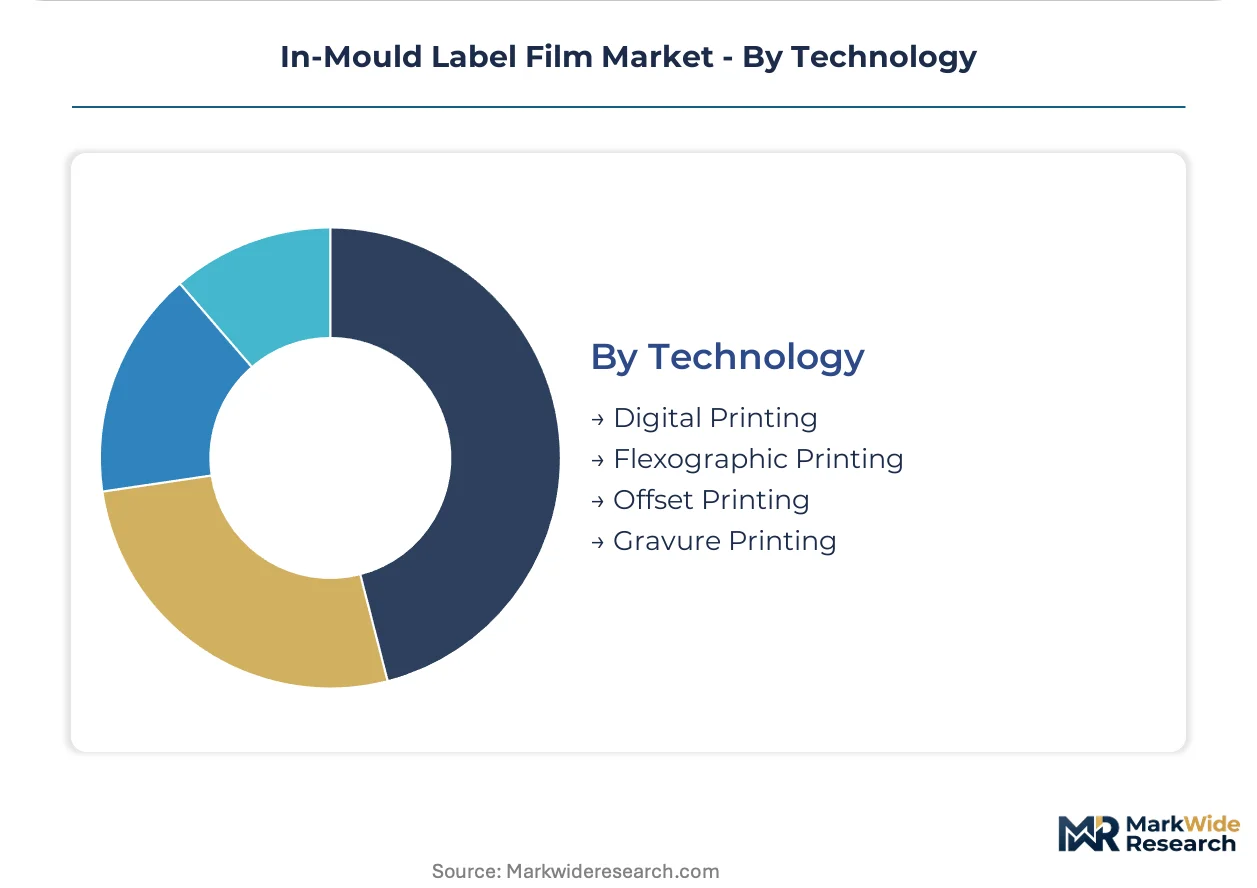
Technology:
Printing modality selection governs minimum order economics, color consistency, and integration speed with downstream molding workflows.
- Digital Printing:Fragmenting traditional supply relationships between converters and molders through short-run flexibility and variable data capability. CCL Industries leverages digital integration across North American operations.
- Flexographic Printing:Volume-efficient for standardized designs with extended production runs. Taghleef Industries anchors European supply through flexo-optimized biaxially oriented polypropylene lines.
- Offset Printing:Premium color fidelity for cosmetic and automotive interior applications requiring precise brand color matching.
- Gravure Printing:High-volume beverage and food packaging where cylinder amortization spreads across million-unit runs.
Flexographic printing maintains volume dominance. Digital printing is gaining share fastest as run lengths compress and versioning requirements multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German film extruders supply biaxially oriented polypropylene grades to Italian beverage converters and French dairy processors, establishing a north-south trade corridor across EU packaging demand centers.
Germany
Automotive interior applications and dairy packaging sustain demand for high-cycle IML substrates. The EU F-Gas Regulation accelerates conversion from solvent-based wet glue systems in Bavarian dairy processing. Southern German mold fabricators cluster high-precision IML tooling capacity around Stuttgart and Munich.
Italy
Carbonated soft drink and mineral water brands drive beverage container adoption for line efficiency gains. EFSA migration limits govern substrate specifications for food contact applications. High-speed IML lines in Emilia-Romagna eliminate post-mold labeling stations for major bottling operations.
France
Ready-meal and dairy brands transition to water-based barrier coatings to preempt tightening EFSA thresholds. The EU Green Deal recyclability mandates force mono-material polypropylene reformulation. Processing corridors around Paris and Lyon concentrate converter operations for major retail private-label programs.
India
FSSAI food contact compliance upgrades replace direct-printed containers with migration-tested IML solutions in Mumbai and Delhi processing corridors. Flexible packaging extensions favor polyethylene films for ready-meal tray applications. Domestic converters expand capacity to serve modernization of national food packaging infrastructure.
United States
FDA indirect food additive standards govern substrate migration limits for beverage and consumer goods applications. CCL Industries leverages captive film extrusion capacity across North American operations. Digital printing integration fragments traditional supply relationships between converters and molders in regional packaging hubs.
In-Mould Label Film Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structurally tiered market. Consolidation concentrates among film extruders with captive coating capacity, while fragmentation persists among regional converters lacking upstream substrate control. Three archetypes dominate: backward-integrated multinationals with global extrusion networks, specialized European film producers with biaxial orientation expertise, and North American converters leveraging digital printing workflows. Competitive moves center on capacity expansion in mono-material polypropylene lines and strategic partnerships linking substrate suppliers to high-speed molding equipment vendors.
Among backward-integrated multinationals, CCL Industries and Constantia Flexibles exemplify archetypes combining captive film production with converter operations. Taghleef Industries anchors the specialized European tier with biaxially oriented polypropylene expertise. These three occupy positions spanning substrate control, geographic coverage, and end-market diversification across food packaging, beverage, and industrial applications.
| Leading Market Players |
|---|
| CCL Industries |
| Taghleef Industries |
| Constantia Flexibles |
| Coveris Holdings |
| Jindal Films Americas |
| Cosmo Films |
| Innovia Films |
| Avery Dennison |
| Huhtamaki Group |
| Others |
Supply & Pricing Matrix
Biaxially oriented polypropylene film extrusion clusters in southern Germany and northern Italy concentrate upstream substrate supply, channeling margin capture toward converters who control captive coating capacity and direct relationships with high-cycle molders in Stuttgart and Munich automotive corridors.
Pricing Analysis
Digital printing workflows command premium positioning against flexographic and gravure alternatives, while conventional offset and gravure lines price defensively for million-unit beverage runs. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant food contact grades with water-based barrier coatings from industrial PVC constructions and commodity PE films for flexible packaging. Cost compression in standard-grade PP substrates is intensifying because propylene feedstock volatility transmits directly from crude oil swings to converter margins. Small-scale Indian converters and regional distributors exhibit highest price sensitivity, whereas German automotive tier suppliers and consolidated dairy brand owners prioritize migration compliance and lot-to-lot consistency over unit cost.
Supply Chain Analysis
Specialized mold fabrication concentrates among precision tooling houses in southern Germany, with secondary capacity clusters in northern Italy and emerging operations in Pune and Chennai serving Indian market expansion. Raw material flows draw from Saudi and Korean propylene suppliers, Belgian antistatic coating compounders, and Finnish pulp-based barrier coating innovators. Single-source vulnerability runs through high-precision IML mold fabrication, where qualified toolmakers for ±0.1mm tolerance maintenance remain geographically concentrated. Distribution runs through direct converter-to-molder relationships for automotive and dairy applications, with regional distributors handling commodity industrial container films lacking food contact compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The in-mould label film market tracks a cyclical recovery pattern as EU Green Deal recyclability mandates and EFSA migration threshold tightening force substrate reformulation cycles that mirror prior regulatory-driven replacement waves in food contact packaging.
For Market Incumbents: Pre-empt pressure-sensitive label substitution in short-run promotional campaigns by deploying digital printing integration that collapses minimum order quantities and compresses lead times. Capture backward integration into water-based barrier coating formulation to eliminate dependency on external metallized substrate suppliers as REACH Annex XVII restrictions on fluorinated process aids extend certification timelines. Defend against emerging Asian converters by locking multi-year supply agreements with southern German mold fabricators who control high-precision tooling capacity. For New Entrants and Emerging Players: Indian food packaging modernization offers the most penetrable expansion corridor, where FSSAI compliance upgrades replace direct-printed containers with migration-tested IML solutions in Mumbai and Delhi processing corridors. Target flexible packaging extensions in ready-meal tray applications where polyethylene film stiffness profiles enable mono-material alternatives to multi-layer constructions. Enter through partnership with domestic Indian converters expanding capacity to serve national infrastructure modernization, leveraging technical transfer agreements for coating and metallization processes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European film producers who acquired biaxial orientation lines during prior consolidation waves but lack downstream converter integration. Five-to-ten year viability hinges on successful mono-material polypropylene transition and digital watermark certification for premium recyclability positioning. Monitor EFSA food contact notification timelines and EU Packaging and Packaging Waste Regulation implementation cadence as inflection indicators for substrate grade obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material PP Line Expansion | Captures EU Green Deal recyclability mandates and EFSA migration compliance premiums in German dairy packaging. |
| Digital Printing Integration | Fragments traditional converter-molder relationships through short-run flexibility and variable data capability for Italian beverage brands. |
| Water-Based Barrier Coating Investment | Eliminates ethylene vinyl alcohol tie layers that complicate mechanical recycling streams for French ready-meal processors. |
| High-Precision Mold Fabrication Partnership | Secures ±0.1mm tolerance maintenance capacity for automotive interior dashboard applications in Stuttgart clusters. |
| Digital Watermark Certification | Unlocks AIM DPP and GS1 premium recyclability positioning for mono-material constructions in Dutch retail private-label programs. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with film extrusion plant managers, IML converter procurement leads, automotive tier supplier engineers, and EFSA regulatory affairs specialists; and secondary validation through REACH Annex XVII substance restriction databases, EU Packaging and Packaging Waste Regulation implementation trackers, customs trade data for biaxially oriented polypropylene film flows, and SEC filings from publicly traded packaging converters. Bottom-up volume estimates triangulated against top-down spending patterns from brand owner packaging procurement disclosures.
Forecast inputs considered material substitution rates from pressure-sensitive labels to in-mould solutions, injection molding line efficiency gains from elimination of post-mold labeling stations, and regulatory compliance cost pass-through to end-user pricing across the projection horizon. Segmentation dimensions modeled include substrate chemistry compatibility with container resins, crystallinity matching for mechanical recycling stream purity, printing modality integration speed with downstream molding workflows, and geographic regulatory cluster alignment with EFSA, FDA, and FSSAI migration limits. CAGRs derived from slope analysis of historical substitution patterns and regulatory-driven replacement cycle timing.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese film producers or accelerated digital printing adoption by North American converters would shift outcomes beyond modeled ranges. Quarterly review of propylene feedstock price volatility, EFSA food contact notification queue depth, and high-precision IML mold fabrication lead times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polybag Mailers Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Blown Film Extruder Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Metallized Film Market
Poly film
Chocolate Wrapping Films Market
Poly film
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market
Poly film
Global PVDC Coated Films Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Forming Films Market
Poly film
India BOPP Films Market
Poly film
Easy Peel Film Packaging Market
Poly film
China BOPP Film Market