
 Compression Baggers Market | 2026-2036
Compression Baggers Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Baggers Market Outlook
Equipment leasing and project finance for automated packaging lines is fragmenting the competitive landscape in compression baggers. FlexiCompress leverages its manufacturing scale to serve high-volume food manufacturers with turnkey installations. SafePack anchors its position through geographic dominance in European markets with stringent certification requirements. PackMaster differentiates by specializing in portable baggers for commercial kitchens and catering operations.
Compression baggers are electromechanical devices that evacuate air from flexible containers—typically achieving vacuum levels of 0.8 to 0.95 bar—then heat-seal the package to inhibit oxidation and microbial growth. These machines serve industrial food preservation, retail packaging, and consumer storage applications where extended shelf life and space reduction deliver measurable economic value. Vacuum sealers occupy the largest revenue pool among product types due to their ubiquity across food manufacturing and foodservice channels, while portable baggers represent the fastest-expanding segment as restaurants and catering operators prioritize mobility and countertop footprint reduction. Food preservation commands the dominant application share, though travel packing and outdoor activities are gaining traction as consumer brands bundle compression technology with lifestyle marketing.
FDA food contact material regulations and EU machinery safety directives (CE marking, MDR-adjacent standards) shape product design, material selection, and market access for compression baggers sold into regulated jurisdictions. The EPA's energy efficiency guidelines for commercial equipment and REACH chemical restrictions on certain polymer additives further constrain formulation choices and component sourcing. Stakeholders must monitor evolving refrigerant regulations and material compliance thresholds as equipment refresh cycles accelerate and sustainability credentials become procurement gatekeepers.
Market Dynamics
Equipment refresh cycles are compressing as the EU F-Gas Regulation forces refrigerant-phaseout across industrial food packaging infrastructure, triggering wholesale replacement of legacy vacuum sealing systems with energy-efficient electromechanical designs.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant-phaseout mandates in Germany, France, and Italy are accelerating equipment replacement cycles among export-grade food processors seeking compliance certification.
- Food manufacturing automation:Industrial bakeries and ready-meal producers are deploying high-throughput vacuum sealing lines to reduce labor costs and achieve consistent shelf-life extension.
- Polymer innovation:Multi-layer barrier films with enhanced oxygen transmission resistance are enabling thinner-gauge packaging that maintains vacuum integrity across extended distribution chains.
Market Restraints
- Stainless steel and copper input volatility:Electromechanical chassis and heat-sealing element production faces margin pressure from commodity price swings in industrial metals sourcing.
- German supply concentration:Precision vacuum pump manufacturing clusters heavily in Baden-Württemberg, creating geographic vulnerability for equipment assemblers dependent on just-in-time component delivery.
- Technical limitation:Current rotary vane pump designs struggle to achieve sub-0.85 bar vacuum levels consistently in high-humidity processing environments without accelerated seal degradation.
Strategic Opportunities
- Commercial kitchen penetration:Independent restaurants and catering operators in Spain and Portugal represent underdeveloped demand for countertop portable baggers with reduced footprint requirements.
- Outdoor recreation bundling:Consumer brands are packaging compression technology with camping and travel equipment, opening channel partnerships with specialty retailers.
- EU Green Deal alignment:Equipment manufacturers qualifying for circular economy equipment subsidies can capture public procurement tenders requiring documented carbon footprint reduction.
Industry Challenges
- Electromechanical technician scarcity:Vacuum pump calibration and heat-seal bar maintenance require specialized skills that food manufacturers struggle to source in regional labor markets.
- CE marking timeline compression:Machinery safety directive compliance documentation now averages 14-18 months, delaying product launches for modular system innovations.
- Legacy integration friction:New vacuum sealing lines must interface with existing conveyor and labeling systems running proprietary control protocols from 1990s-era installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Baggers Market |
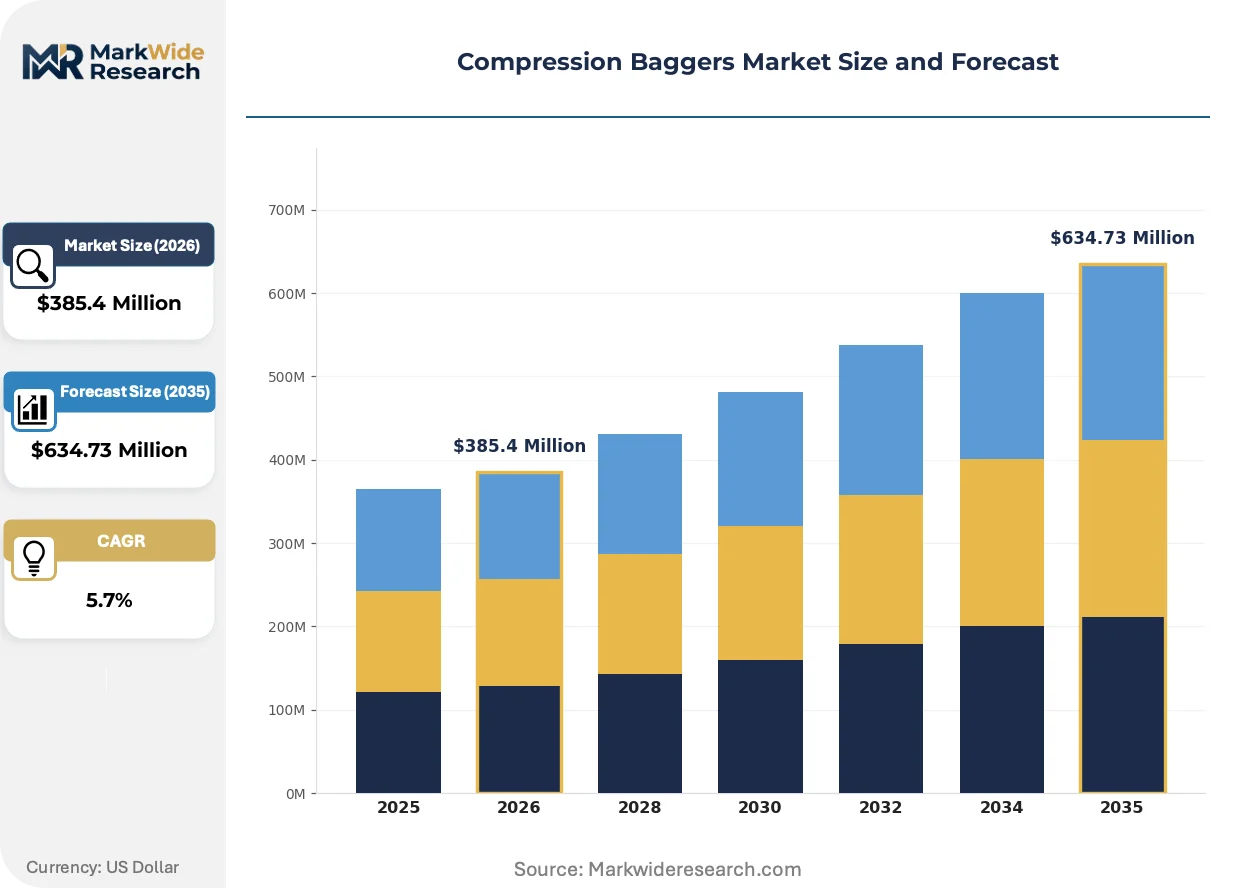
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $634.73 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Sealers, Portable Baggers, Stationary Baggers, Food Saver Systems Material: Plastic, Nylon, Polyurethane, Composite End User: Households, Restaurants, Food Manufacturers, Retail Stores Application: Food Preservation, Storage Solutions, Travel Packing, Outdoor Activities |
| Companies Covered | FlexiCompress, SafePack, PackMaster, CompressIt, PackShield, SecurePack, BagGuard, EcoWraps, EcoCompress Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Baggers Market Strategic Shifts
Predictive maintenance architectures are embedding into compression bagger control systems, shifting competitive differentiation from mechanical reliability to uptime guarantees and service monetization models.
IoT-enabled vacuum pump monitoring is digitizing field service operations for industrial food manufacturers. Sensor arrays tracking seal temperature, cycle count, and vacuum decay rates transmit fault alerts to remote diagnostics centers. Equipment lessors are bundling predictive maintenance subscriptions with hardware leases, compressing traditional break-fix service margins.
The EU F-Gas Regulation is forcing refrigerant-dependent thermal sealing systems toward obsolescence. Manufacturers are pivoting to solid-state heat-seal technologies using ceramic heating elements. German food exporters face the most acute compliance pressure, driving fastest adoption of electromechanical sealing platforms that eliminate refrigerant handling entirely.
After-sales service unbundling is fragmenting buyer-supplier relationships in commercial kitchen segments. Restaurant operators are purchasing portable baggers through foodservice distributors while sourcing maintenance through independent technician networks. Southern European markets show highest disintermediation intensity as price-sensitive buyers separate equipment acquisition from service contracts.
Compression Baggers Market Segmentation
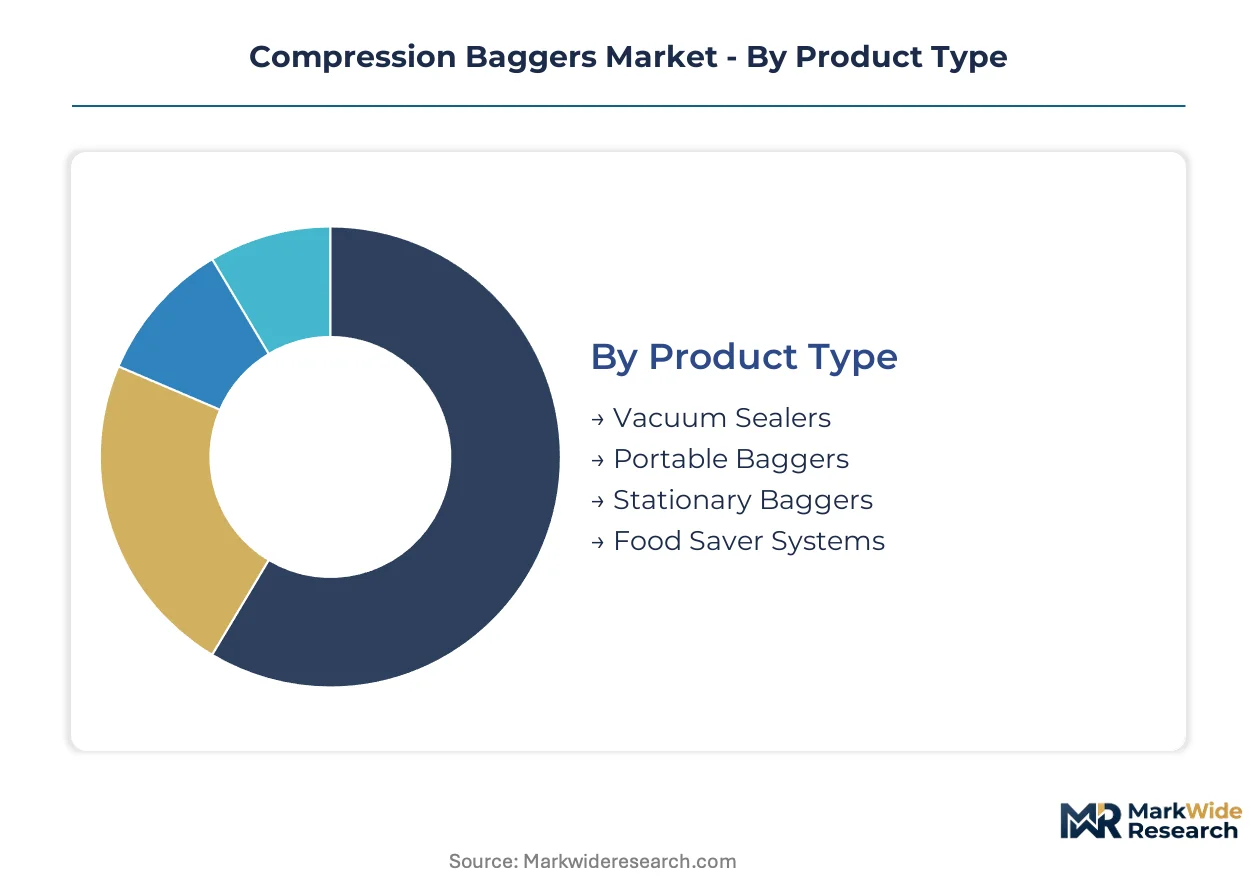
Compression bagger segmentation reveals divergent engineering requirements across product architectures, material specifications, and end-use intensity. Equipment manufacturers must balance vacuum pump durability against thermal sealing precision when configuring systems for industrial food lines versus countertop restaurant units.
Product Type:
Mature electromechanical platforms dominate industrial throughput, while emerging portable formats are capturing commercial kitchen adoption through footprint reduction.
- Vacuum Sealers:Chamber and external suction designs achieve 0.8 to 0.95 bar evacuation through rotary vane or diaphragm pump architectures. Food manufacturers in Germany deploy high-cycle units for export-grade meat and cheese packaging where shelf-life extension justifies capital intensity.
- Portable Baggers:Compact countertop units with integrated heat-seal bars and manual or semi-automatic operation. Restaurants in Spain and Portugal are adopting these for prep-kitchen flexibility where space constraints prohibit full chamber systems.
- Stationary Baggers:Fixed-installation industrial lines with conveyor integration and automated bag handling.
- Food Saver Systems:Consumer-grade appliances with simplified controls and proprietary bag formats.
Vacuum sealers handle the majority of throughput; portable baggers are gaining share fastest as foodservice operators prioritize mobility.
Material:
Cost tier differentiation separates commodity polymer feedstocks from engineered multi-layer barriers with oxygen transmission specifications.
- Plastic:Polyethylene and polypropylene monolayers serve cost-sensitive consumer storage applications with limited barrier performance.
- Nylon:Polyamide resins provide puncture resistance and moderate gas barrier for protein packaging in retail distribution.
- Polyurethane:Thermoplastic elastomer formulations enable flexible, reusable storage bags for travel and outdoor segments where repeated compression cycles demand fatigue resistance.
- Composite:Co-extruded multi-layer structures combining EVOH barrier cores with PE sealant layers achieve sub-5 cc/m²/day oxygen transmission rates for extended shelf-life meat and ready-meal applications.
Composites command premium positioning in food manufacturing; polyurethane is climbing fastest as outdoor recreation bundling expands.
End User:
Application intensity varies dramatically between intermittent household use and continuous industrial operation with 24-hour duty cycles.
- Food Manufacturers:Industrial bakeries, meat processors, and ready-meal producers operate high-throughput vacuum lines with automated loading and quality verification systems. The EU F-Gas Regulation is forcing refrigerant-dependent thermal systems toward electromechanical replacement in German export facilities.
- Restaurants:Independent operators and catering services utilize mid-duty countertop units for ingredient prep and portion control. Southern European markets show accelerating adoption as labor costs drive efficiency investments in commercial kitchens.
- Households:Consumer purchasers of countertop appliances for bulk purchasing and freezer organization.
- Retail Stores:In-store packaging operations for deli counters and custom meat cutting services.
Food manufacturers absorb the highest equipment spend per installation; restaurants are expanding most quickly as service automation penetrates mid-market operators.
Application:
Geographic concentration of demand clusters around food preservation maturity, with lifestyle applications emerging in peripheral markets.
- Food Preservation:Vacuum packaging for proteins, produce, and prepared meals to inhibit oxidation and microbial proliferation. German food exporters mandate compliance with EU machinery safety directives and FDA food contact material regulations for transatlantic shipment.
- Travel Packing:Volume reduction for luggage optimization, bundling with outdoor equipment retailers.
- Storage Solutions:Seasonal clothing and household item compression for space-constrained urban residences.
- Outdoor Activities:Camping and expedition use cases requiring waterproof protection and packability.
Food preservation commands installed base dominance; outdoor activities shows steepest expansion trajectory as specialty retail partnerships proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-grade food processors dominate equipment procurement, with regulatory compliance and automation intensity determining geographic demand distribution across industrialized markets.
Germany
Industrial bakeries and ready-meal producers drive vacuum sealer replacement cycles under EU F-Gas Regulation mandates. CE marking requirements and machinery safety directives compress product launch timelines for equipment vendors. Baden-Württemberg hosts precision vacuum pump manufacturing clusters supplying just-in-time components to domestic assemblers.
United States
FDA food contact material regulations shape polymer selection for meat and cheese packaging lines serving transatlantic export channels. EPA energy efficiency guidelines constrain commercial equipment specifications in foodservice deployments. Midwest industrial corridors concentrate automated packaging line installations for protein processing facilities.
France
Dairy exporters and charcuterie producers deploy high-throughput vacuum sealing to meet shelf-life specifications for premium product distribution. EU Green Deal circular economy subsidies accelerate electromechanical equipment adoption in processing facilities. Auvergne-Rhône-Alpes clusters specialized food machinery integrators serving artisanal and industrial producers simultaneously.
Spain
Independent restaurants and catering operators in Madrid and Barcelona represent underdeveloped demand for countertop portable baggers with reduced footprint requirements. National labor cost pressures drive efficiency investments in commercial kitchen automation. Catalonia-based distributors channel equipment through foodservice networks with separated maintenance contracting.
Italy
Pasta and prepared meal exporters mandate vacuum integrity standards for extended distribution chains across European retail networks. REACH chemical restrictions on polymer additives constrain multi-layer barrier film formulation choices. Emilia-Romagna concentrates packaging machinery engineering talent and component supply relationships.
Compression Baggers Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement pathways in food manufacturing and foodservice segments. Equipment leasing platforms and project finance providers are fragmenting traditional vendor-buyer relationships. Three archetypes dominate: scale-driven turnkey installers, certification-anchored regional specialists, and mobility-focused countertop innovators. Competitive moves concentrate on predictive maintenance service bundling and geographic expansion through distributor partnerships.
Among the named participants, FlexiCompress, SafePack, and PackMaster occupy representative positions across these strategic tiers. FlexiCompress exemplifies the scale-driven turnkey installation archetype serving high-volume food manufacturers. SafePack anchors the certification-focused regional specialist position with concentration in European markets facing stringent machinery safety requirements. PackMaster represents the mobility-specialist vector targeting commercial kitchens and catering operations with footprint-optimized equipment formats.
| Leading Market Players |
|---|
| FlexiCompress |
| SafePack |
| PackMaster |
| CompressIt |
| PackShield |
| SecurePack |
| BagGuard |
| EcoWraps |
| EcoCompress Solutions |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's precision vacuum pump manufacturing clusters anchor component supply for European equipment assemblers, concentrating margin capture upstream while downstream pricing power fragments across food manufacturer procurement teams and foodservice distributor networks.
Pricing Analysis
Certification level (CE marking, FDA food contact material compliance, EU machinery safety directives) creates the primary spread between premium and standard equipment tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium units bundling predictive maintenance subscriptions and extended warranty coverage. Cost compression in the economy tier is intensifying because stainless steel and copper input volatility squeezes electromechanical chassis margins. Food manufacturers exhibit lowest price sensitivity due to shelf-life extension ROI, while independent restaurants in Southern Europe show highest sensitivity, separating equipment acquisition from service contracts entirely.
Supply Chain Analysis
Extended payment terms from German precision component suppliers and supply-chain finance facilities from equipment lessors are restructuring working capital requirements for mid-tier assemblers. Component sourcing draws from Germany (vacuum pumps), Italy (heat-seal bar ceramics), and China (polymer films and electronic controllers). Raw material dependencies include stainless steel chassis, copper heating elements, and EVOH barrier film resins. Single-source vulnerability concentrates in Baden-Württemberg rotary vane pump manufacturing. Distribution runs through foodservice equipment distributors in Southern Europe and direct OEM relationships with German export-grade processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation is forcing refrigerant-dependent thermal sealing systems toward obsolescence, creating a high-growth disruption window for electromechanical platform vendors capable of delivering compliance-certified replacements at scale.
For Market Incumbents: Pre-empt margin erosion in the portable bagger segment by acquiring Southern European distributor networks before foodservice procurement fully disintermediates equipment from service. Incumbent scale advantages in turnkey installation face substitution threat from equipment leasing platforms fragmenting vendor-buyer relationships. Priority lever: deepen backward integration into ceramic heat-seal element production to offset copper price volatility.
For New Entrants and Emerging Players: Spain and Portugal's independent restaurant sector offers the most penetrable geography for countertop portable baggers with sub-50cm footprint specifications. Southern European labor cost pressures are accelerating commercial kitchen automation demand ahead of incumbent service network coverage. Go-to-market angle: partner with outdoor recreation retailers for camping equipment bundling, bypassing established foodservice distribution entirely.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed equipment leasing platforms holding compressed break-fix service margins as predictive maintenance subscriptions displace traditional revenue pools. Long-term viability hinges on IoT-enabled service monetization penetration across installed bases. Acquisition target archetype: mid-cap specialists with captive vacuum pump calibration capabilities. Signal to watch: CE marking timeline compression accelerating modular system innovation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Equipment lessors bundling sensor-based uptime guarantees capture recurring revenue from German food exporters. |
| Ceramic Heat-Seal Technology Transition | Solid-state sealing platforms eliminate refrigerant handling, satisfying EU F-Gas Regulation compliance mandates. |
| Southern European Distributor Acquisition | Channel control in Spain and Portugal secures access to price-sensitive restaurant operators before full disintermediation. |
| Outdoor Recreation Retail Partnership | Camping equipment bundling opens consumer segments beyond traditional food manufacturing and foodservice channels. |
| Backward Integration into Pump Manufacturing | In-house production of rotary vane components mitigates geographic concentration risk in Baden-Württemberg supply clusters. |
Study Parameters
Desk research of EU regulatory filings (F-Gas Regulation implementation reports, CE marking directive updates, REACH chemical restriction schedules), trade association publications (food machinery manufacturer associations), and equipment procurement databases preceded structured interviews with food manufacturing plant engineers, commercial kitchen equipment purchasers, predictive maintenance service directors, and polymer film procurement leads. Primary fieldwork validated secondary estimates through bottom-up installation tracking and top-down market sizing triangulation.
Assumptions held fixed include EU F-Gas Regulation phaseout timelines, CE marking compliance documentation periods, and observed equipment refresh cycle compression rates; variables included polymer innovation velocity and predictive maintenance adoption curves across foodservice segments. Segmentation dimensions modeled encompass product architecture (chamber vacuum sealers, external suction units, portable countertop formats), material specification (composite barrier films, polyurethane reusable formats), end-use intensity (24-hour industrial duty cycles versus intermittent commercial kitchen operation), and application type (food preservation, travel packing, outdoor recreation). CAGRs were derived from installed base replacement modeling and expansion coefficient analysis across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by IoT-native equipment lessors or ceramic heating element specialists would shift outcomes. Macroeconomic deviation in industrial metals pricing, regulatory acceleration of refrigerant phaseouts, or breakthrough diaphragm pump designs achieving sub-0.85 bar consistency in humid environments would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Liquid Packaging Bag Market
Bags and Containers
Carry Bag Market
Bags and Containers
Woven Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Net Bags Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Drum Liners Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Global Polypropylene Woven Bags and Sacks Market
Bags and Containers
Shopping Bag Market