
 Automotive Wheel Rims Market | 2026-2036
Automotive Wheel Rims Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wheel Rims Market Intelligence
Aftermarket refurbishment and reconditioning revenue is reshaping margin distribution across the value chain. Ronal AG leverages its European production footprint to sustain premium positioning in flow-formed alloy products. Wanfeng Auto Holding Group anchors high-volume supply through integrated casting and machining operations in Asia. Maxion Wheels competes across steel and aluminum portfolios, extending its reach into commercial vehicle fleets with durability-focused designs.
Automotive wheel rims are circular metal or composite structures that mount tires to vehicle axles, typically manufactured through casting, forging, or flow-forming processes with specifications ranging from 13 to 24 inches in diameter and load ratings up to several thousand kilograms. Their primary function is to support vehicle weight, transmit driving and braking forces, and maintain tire bead seating under dynamic operating conditions. Aluminum alloy rims dominate OEM fitment for passenger cars and SUVs due to their strength-to-weight ratio, while steel rims retain cost advantages in heavy commercial vehicles and entry-level fleet applications. The forged and flow-formed type categories command premium pricing in performance and electric vehicle segments where unsprung mass reduction directly impacts efficiency and handling.
The National Highway Traffic Safety Administration enforces FMVSS No. 120 and No. 139 requirements for rim strength, dimensional integrity, and labeling that govern market access in the United States. The European Union's REACH regulation and End-of-Life Vehicle Directive restrict hazardous substances in coatings and mandate recyclability standards that shape material selection across aluminum and magnesium alloy supply chains. China's Ministry of Industry and Information Technology administers GB standards for automotive wheels that mandate fatigue testing and impact resistance certification for domestic production and import. Stakeholders must monitor evolving weight-based emissions accounting methods and battery-electric vehicle platform architectures that redefine optimal rim specifications across vehicle classes.
Market Dynamics
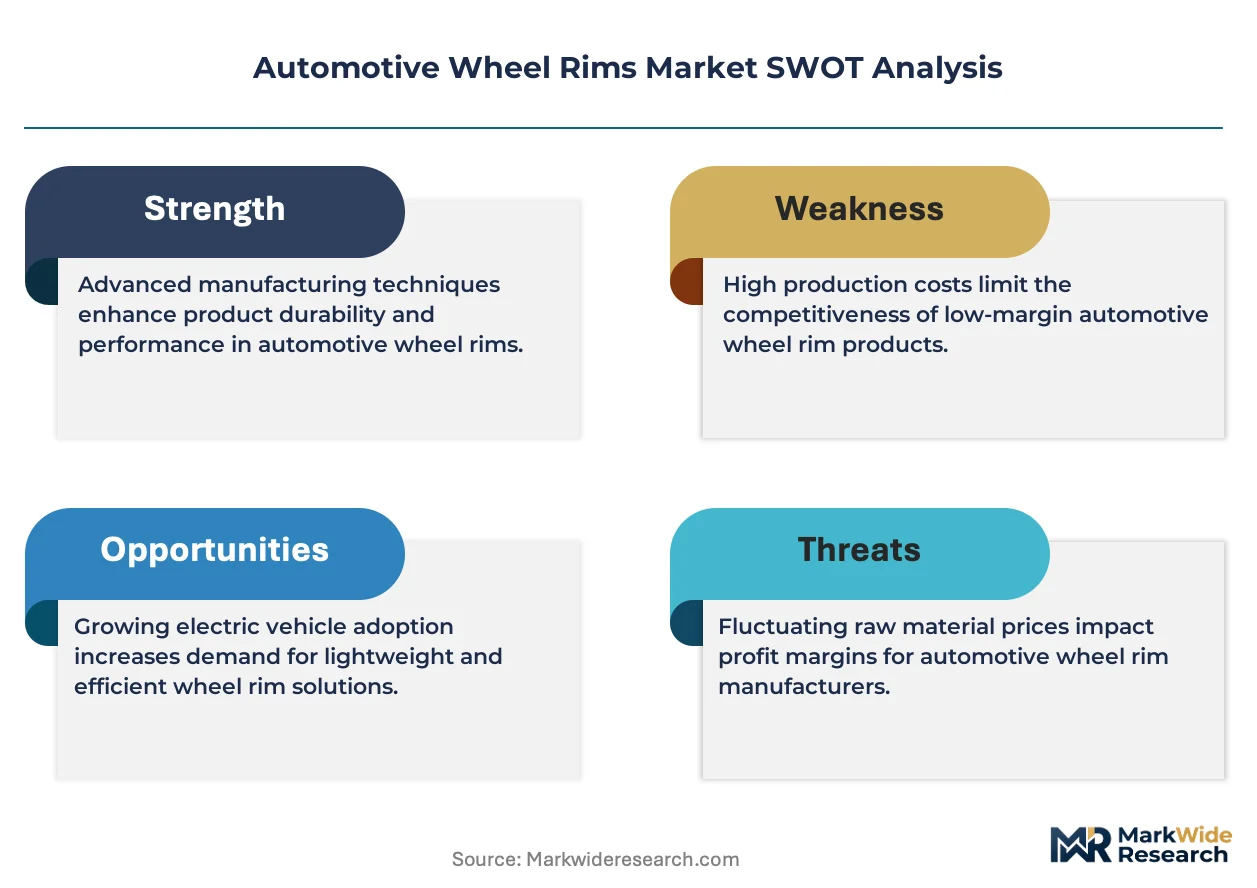
Electric vehicle platform architectures are forcing a fundamental recalibration of rim specifications as unsprung mass reduction becomes a direct lever for range extension and battery efficiency optimization.
Growth Catalysts
- EPA Fuel-Economy Standards:Stringent U.S. fleet efficiency mandates compel OEMs to specify lightweight aluminum alloy rims across passenger car segments, accelerating material substitution away from steel.
- EU CO2 Fleet Mandates:European emissions accounting methods now weight vehicle mass directly, positioning forged and flow-formed rims as compliance-critical components rather than cosmetic upgrades.
- China Production Concentration:Integrated casting and machining clusters in Zhejiang and Jiangsu provinces enable cost-competitive supply of certified alloy rims to domestic EV manufacturers scaling battery-electric platforms.
Market Restraints
- Aluminum Price Volatility:Primary aluminum ingot costs fluctuate with energy pricing and smelter curtailments, compressing margins for cast alloy rim producers unable to pass through input swings.
- Supply Concentration Risk:Premium flow-forming capacity concentrates among a limited set of European and Japanese equipment suppliers, creating bottleneck risks for OEMs qualifying new rim programs.
- REACH Compliance Friction:ECHA restrictions on hexavalent chromium coatings and specific alloy additives force reformulation of surface treatments, extending qualification timelines for European market entry.
Strategic Opportunities
- India Fleet Electrification:PLI scheme incentives for domestic EV manufacturing create demand for localized rim supply as Tata Motors and Mahindra scale battery-electric platforms requiring lightweight wheel specifications.
- Aftermarket Refurbishment Channels:Reconditioning networks for alloy rim repair and cosmetic restoration capture margin pools previously lost to scrap recycling, particularly in Germany's TÜV-certified inspection regimes.
- Solid-State Battery Convergence:Next-generation cell architectures promise vehicle mass redistribution, enabling rim designers to optimize for structural load paths rather than compensating for battery pack weight concentration.
Industry Challenges
- Flow-Forming Technician Scarcity:Specialized operator skills for rotary forging equipment remain concentrated in legacy automotive regions, constraining capacity expansion in emerging manufacturing hubs.
- GB Standard Certification Timelines:MIIT fatigue testing and impact resistance protocols require extended domestic validation cycles, delaying market access for foreign rim suppliers targeting Chinese OEM programs.
- Legacy Fleet Retrofit Complexity:Steel-to-aluminum rim conversions for existing commercial vehicle pools face axle load recertification requirements that fragment aftermarket demand into discrete regulatory batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wheel Rims Market |
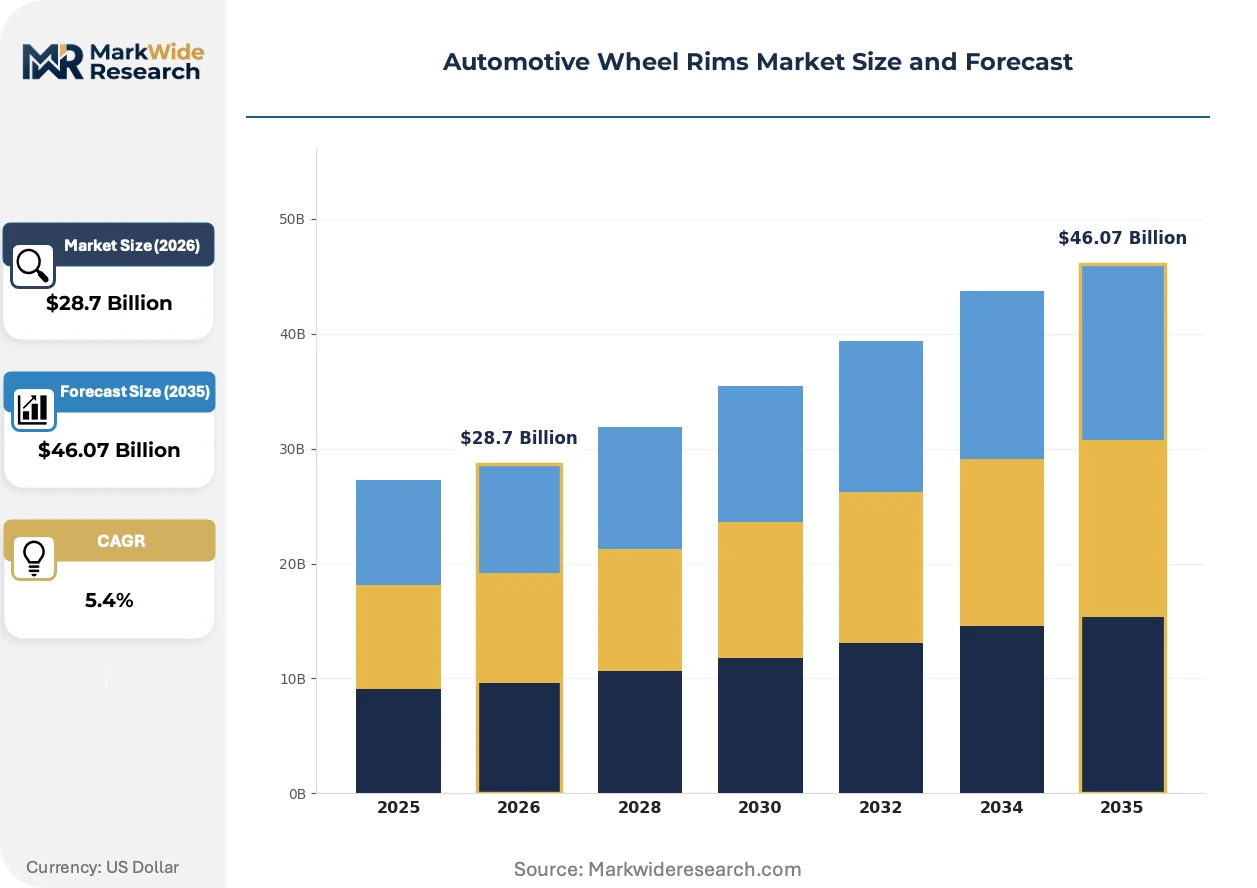
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum Alloy, Steel, Magnesium Alloy, Carbon Fiber, Composite Type: Cast, Forged, Machined, Multi-piece, Flow-formed Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, SUVs, Two-wheelers Distribution Channel: OEMs, Aftermarket Retailers, Direct-to-Consumer, Wholesalers, Online Marketplaces |
| Companies Covered | Ronal AG, Wanfeng Auto Holding Group Co. Ltd., Maxion Wheels, BORBET GmbH, Alcoa Wheels, CITIC Dicastal Wheel Manufacturing Co. Ltd., Superior Industries International Inc., Enkei International Inc., Steel Strips Wheels Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wheel Rims Market Strategic Shifts & Innovations
Digital manufacturing integration and closed-loop material recovery are redefining production economics while regulatory pressure on lifecycle emissions intensifies design-to-recyclability mandates across supply chains.
Flow-forming simulation software is digitizing rim development workflows by enabling virtual die design and stress prediction before physical prototyping. Tier-1 suppliers serving premium EV platforms deploy these tools to compress program timelines from eighteen to ten months. The technology is digitizing competitive positioning by separating capital-light engineering firms from asset-heavy manufacturers dependent on iterative tooling trials.
REACH Annex XVII restrictions on persistent organic pollutants in coatings are compelling reformulation of pretreatment chemistries across European rim finishing operations. Industrial consequence includes accelerated qualification of silane-based and zirconium conversion coatings as hexavalent chromium alternatives. Passenger car OEMs in Germany and France are responding by consolidating supplier panels to those with certified green chemistry pipelines, marginalizing smaller finishers.
Direct-to-fleet procurement contracts are consolidating rim specification authority away from traditional tiered distribution. Commercial vehicle operators with centralized maintenance operations now negotiate frame agreements specifying durability-rated steel rims with predictive replacement scheduling. This pattern is most visible in U.S. long-haul trucking fleets where total cost of ownership modeling favors standardized wheel programs over brand-agnostic aftermarket sourcing.
Automotive Wheel Rims Market Segmentation
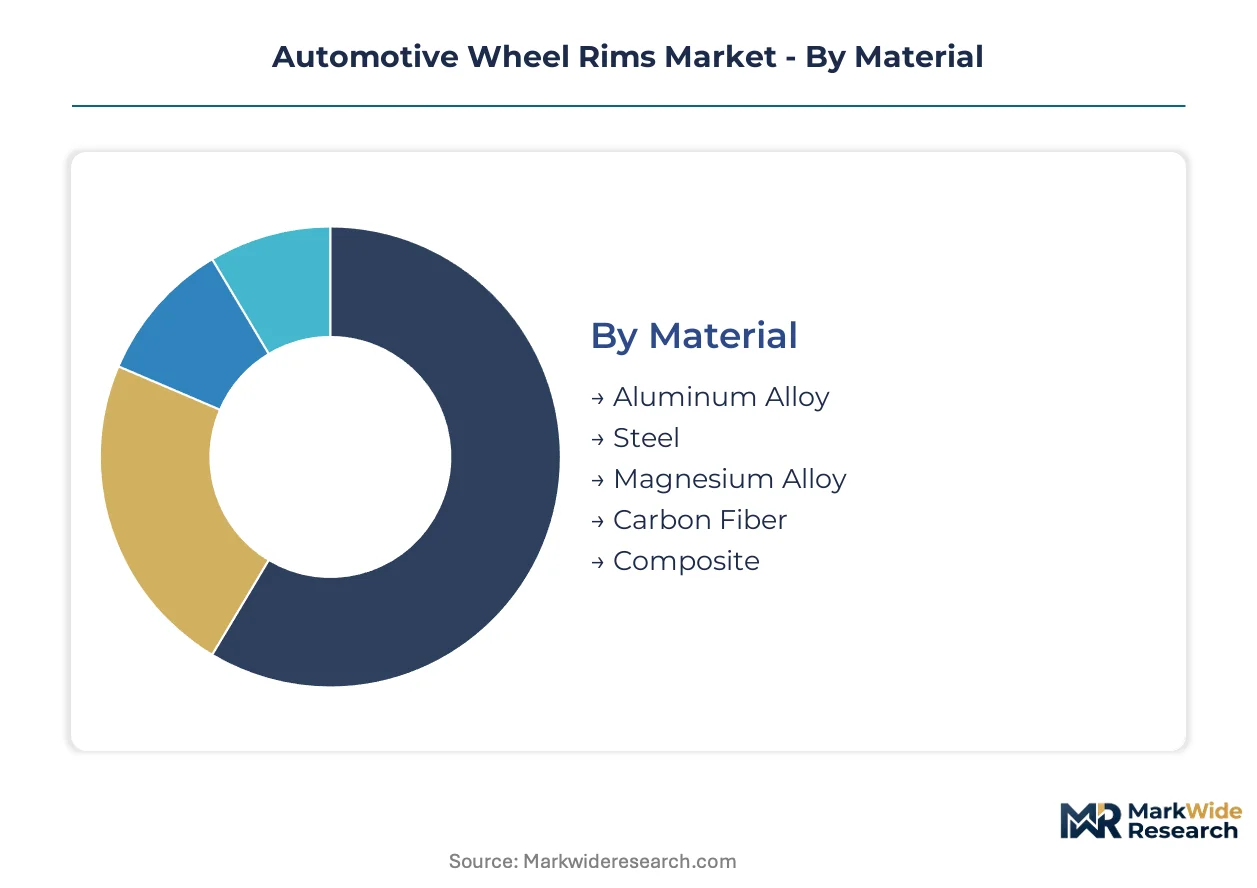
Segmentation in automotive wheel rims determines warranty exposure, refurbishment revenue cycles, and inventory velocity across distribution tiers. Material selection and manufacturing process choices cascade through pricing architecture, regulatory compliance pathways, and end-use performance requirements.
Material:
After-sales-service intensity varies dramatically by material category, with aluminum alloy rims generating substantial cosmetic repair and reconditioning revenue while steel rims drive predictive replacement programs in fleet operations.
- Aluminum Alloy:Cast or forged aluminum-silicon-magnesium formulations dominate OEM fitment for passenger cars and SUVs. Demand concentrates in Germany and China where EV manufacturers specify lightweight rims for range optimization under EU CO2 fleet mandates and MIIT efficiency regulations.
- Steel:Pressed-steel construction retains cost advantages in heavy commercial vehicles and entry-level fleet applications. Volume centers on U.S. long-haul trucking fleets where total cost of ownership modeling favors standardized durability-rated wheels over premium alternatives.
- Magnesium Alloy:AZ91 and AM60 alloys offer maximum specific strength for performance applications. Limited production runs serve motorsport and ultra-premium EV segments where unsprung mass reduction commands substantial price premiums.
- Carbon Fiber:Woven composite construction enables radical weight reduction for hypercar and aerospace-adjacent automotive programs. Niche positioning reflects lengthy qualification cycles and repair complexity that limit aftermarket serviceability.
- Composite:Hybrid material systems combining fiber reinforcement with metallic hubs target emerging EV architectures. Development activity clusters around battery-electric platform engineering centers in California and Bavaria.
By volume, Steel leads. By growth pace, Aluminum Alloy is ahead.
Type:
Manufacturing process selection separates capital-intensive forging operations from flexible casting capacity, with direct implications for margin structure and customer concentration.
- Cast:Gravity and low-pressure die casting produce the majority of OEM aluminum rims. Foundries in Zhejiang province supply high volumes to domestic Chinese EV manufacturers scaling production under PLI scheme incentives.
- Forged:Closed-die forging creates grain-aligned structures with superior fatigue resistance. Premium positioning in European performance segments reflects REACH-compliant surface treatment requirements and extended qualification timelines.
- Machined:CNC finishing operations refine cast or forged blanks to precise dimensional tolerances. Demand concentrates in aftermarket customization channels where dimensional flexibility commands value-added pricing.
- Multi-piece:Bolt-together rim assemblies enable width and offset customization for motorsport and luxury applications. Low-volume production sustains artisan manufacturing footprints in Italy and Japan.
- Flow-formed:Rotary forging stretches cast preforms to optimize wall thickness distribution. Equipment scarcity constrains capacity expansion despite premium positioning in EV range-optimization programs.
Cast processes dominate unit economics. Flow-formed technology is climbing the fastest.
Vehicle Type:
Axle load specifications and duty cycle intensity create divergent rim performance requirements across vehicle categories.
- Passenger Cars:C-segment and D-segment sedans specify aluminum alloy rims for weight-driven efficiency compliance. EPA fuel-economy standards accelerate material substitution in U.S. fleet procurement.
- SUVs:Higher curb weights and all-terrain duty cycles demand reinforced rim constructions. Flow-formed products gain share in premium electrified SUV platforms where unsprung mass reduction offsets battery pack weight.
- Light Commercial Vehicles:Delivery van and pickup applications balance payload capacity with durability requirements. Direct-to-fleet procurement contracts consolidate specification authority away from traditional distribution tiers.
- Heavy Commercial Vehicles:Steel rims retain dominance for load ratings exceeding 4,000 kilograms. NHTSA FMVSS No. 120 compliance governs market access for U.S. interstate trucking applications.
- Two-wheelers:Cast aluminum and pressed steel constructions serve motorcycle and scooter markets. Volume concentrates in India and Southeast Asia where two-wheeler electrification creates emerging rim specification requirements.
Passenger Cars anchor volume. SUVs are expanding most quickly.
Distribution Channel:
Channel structure determines margin capture position and technical specification authority across the value chain.
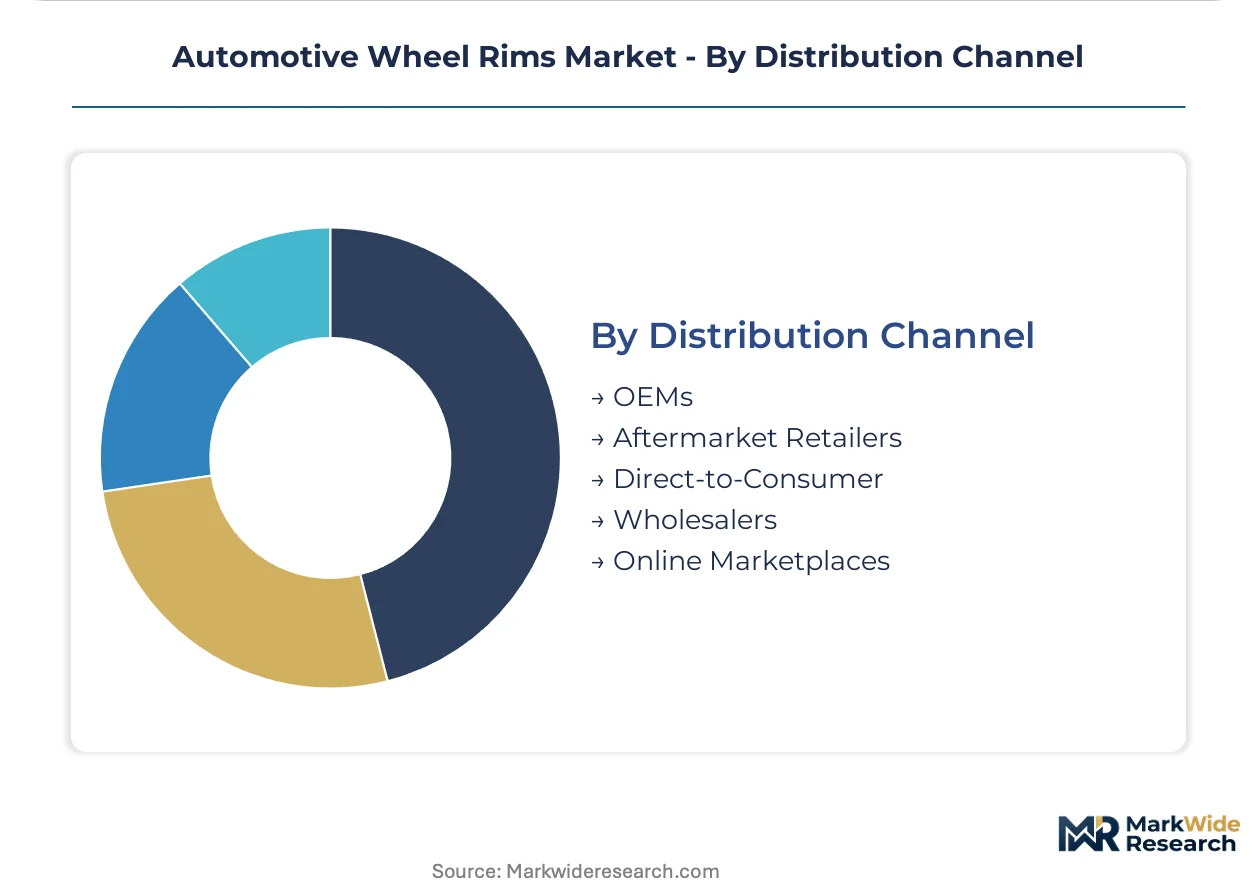
- OEMs:Direct supply contracts to vehicle manufacturers require IATF 16949 certification and program-specific tooling investments. Long-term agreements with German and Japanese automakers sustain premium pricing for qualified suppliers.
- Aftermarket Retailers:Independent shops and tire dealers handle replacement and upgrade demand. TÜV-certified inspection regimes in Germany create compliance barriers that consolidate share among established distributors.
- Direct-to-Consumer:Manufacturer-owned channels bypass traditional distribution for fitment-configured rim sets. Online configurators reduce return rates by validating vehicle compatibility before purchase.
- Wholesalers:Regional distributors aggregate demand from smaller retailers and repair chains. Inventory pooling absorbs demand volatility but compresses margins through price competition.
- Online Marketplaces:Platform-based sales expand access to price-sensitive segments. Counterfeit and non-certified product risks create liability exposure that favors marketplace operators with verification programs.
OEMs command value concentration. Online Marketplaces are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys aluminum alloy rims for EV range optimization while the United States favors steel durability in commercial trucking fleets, revealing a consumption-mix split between electrification efficiency and load-bearing economics.
China
Domestic EV manufacturers specify lightweight alloy rims for battery-electric platforms scaling under MIIT efficiency regulations. The Ministry of Industry and Information Technology enforces GB standards mandating fatigue testing and impact resistance certification. Integrated casting clusters in Zhejiang and Jiangsu provinces supply high volumes to BYD and NIO assembly lines.
Germany
Premium OEMs prioritize flow-formed rims for CO2 fleet compliance under EU emissions accounting methods. ECHA REACH restrictions on hexavalent chromium coatings force reformulation of surface treatments across finishing operations. Bavarian engineering centers coordinate rim qualification with Munich-based automakers developing next-generation EV architectures.
United States
Long-haul trucking fleets drive steel rim demand through total cost of ownership modeling favoring standardized durability programs. NHTSA FMVSS No. 120 governs rim strength and dimensional integrity for interstate commercial vehicles. Detroit-area procurement offices negotiate direct frame agreements with tier-1 suppliers for predictive replacement scheduling.
India
Tata Motors and Mahindra scale battery-electric platforms requiring localized lightweight rim supply under PLI scheme incentives. The Bureau of Indian Standards administers certification protocols for automotive wheels entering domestic production. Tamil Nadu and Gujarat manufacturing corridors attract rim foundries serving expanding two-wheeler and passenger EV segments.
Japan
Performance-oriented OEMs specify forged alloy constructions for unsprung mass reduction in hybrid and electric powertrains. METI industrial policy supports advanced materials development for next-generation mobility platforms. Aichi Prefecture production networks integrate rim supply with Toyota and Honda platform engineering centers.
Automotive Wheel Rims Market Key Industry Players
Capability concentration sits with European flow-forming specialists; scale advantage sits with Asian integrated foundries. The vendor base separates into three functional tiers: premium engineering houses commanding qualification timelines, high-volume casters serving mass-market OEM programs, and steel specialists anchored in commercial vehicle durability contracts. Two dominant competitive moves define current positioning: backward integration into primary aluminum supply and geographic expansion through joint ventures in emerging EV manufacturing hubs.
Within the premium engineering tier, Ronal AG and BORBET GmbH exemplify European capability concentration in flow-formed and forged product architectures. Wanfeng Auto Holding Group Co. Ltd. anchors the scale-driven Asian tier through integrated casting and machining operations. Maxion Wheels occupies a diversified position spanning steel and aluminum portfolios across passenger and commercial vehicle segments.
| Leading Market Players |
|---|
| Ronal AG |
| Wanfeng Auto Holding Group Co. Ltd. |
| Maxion Wheels |
| BORBET GmbH |
| Alcoa Wheels |
| CITIC Dicastal Wheel Manufacturing Co. Ltd. |
| Superior Industries International Inc. |
| Enkei International Inc. |
| Steel Strips Wheels Ltd. |
| Others |
Cost & Logistics Intelligence
Primary aluminum smelter curtailments in Yunnan and Guangxi provinces feed directly into margin compression for cast alloy rim producers serving mass-market EV platforms. Contract structures and raw material pass-through mechanisms determine which tiers capture value as energy costs fluctuate.
Pricing Analysis
Long-term offtake agreements dominate OEM supply relationships, insulating qualified suppliers from spot aluminum volatility while locking in volume commitments. Pricing stratifies across flow-formed premium, cast standard, and steel economy tiers based on certification grade and unsprung mass performance. Cost compression in the cast segment is intensifying because Chinese foundries compete on scale without full energy cost pass-through. Fleet procurement offices show lowest price sensitivity; independent aftermarket retailers absorb the highest margin pressure.
Supply Chain Analysis
Primary aluminum ingot draws from Chinese smelters, Russian hydro-powered capacity, and Middle Eastern producers with captive energy. Bauxite refining and alloying additives hinge on Australian ore and Chinese silicon-magnesium supply. Single-source vulnerability concentrates in European flow-forming equipment where Japanese and German machinery suppliers control rotary forging technology. Distribution runs through tier-1 direct contracts to OEMs, with aftermarket channels fragmenting into regional wholesalers and certified reconditioning networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive wheel rims track the capital equipment cycle, with EV platform refresh schedules and smelter energy economics driving demand troughs and peaks. OEM production ramp timelines and alloy price cycles set the recovery cadence.
For Market Incumbents: Insulate margin pools by securing captive aluminum supply through backward integration into primary smelting or long-term offtake with energy-hedged producers. Deepen certification barriers by accelerating GB standard and REACH-compliant surface treatment qualifications before emerging foundries complete validation cycles. Flow-forming equipment scarcity and technician training pipelines create defensive moats against Asian scale competitors.
For New Entrants and Emerging Players: Pursue aftermarket refurbishment networks in Germany and France where TÜV inspection regimes consolidate demand among certified reconditioners. Target India's PLI-supported EV manufacturing corridors where localized rim supply lags behind Tata Motors and Mahindra platform scaling. Direct-to-fleet procurement contracts for commercial vehicle operators offer entry with lower qualification barriers than OEM tier-1 status.
For Investors and Strategic Acquirers: Capital is best deployed toward European flow-forming specialists with locked OEM qualification timelines and irreplaceable technician expertise. Long-term viability centers on suppliers positioned for solid-state battery platform architectures where mass redistribution enables rim design optimization. Watch aluminum alloy price convergence with steel as the inflection signal for material substitution acceleration in commercial vehicle segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminum | Captive smelter supply insulates margins from Yunnan energy curtailment volatility. |
| Flow-Forming Capacity Expansion | Rotary forging equipment scarcity creates bottleneck for EV range-optimization programs. |
| REACH-Compliant Surface Treatment Certification | Silane-based coating qualification opens German and French OEM supplier panels. |
| India Manufacturing Joint Venture | Tamil Nadu and Gujarat corridors localize supply for PLI-scheme EV production. |
| Aftermarket Reconditioning Network Acquisition | TÜV-certified German inspection regimes consolidate refurbishment margin pools. |
Research Approach
Desk research of customs trade databases, SEC filings from listed automotive suppliers, and vehicle production registries preceded structured interviews with OEM platform engineers, tier-1 supplier procurement directors, aftermarket distributors, and foundry operations managers. Primary fieldwork captured qualification timeline data, contract structure terms, and capacity utilization rates. Secondary validation drew from MIIT certification records, ECHA REACH substance restrictions, and NHTSA FMVSS compliance filings. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Assumptions held aluminum price trajectories and EV platform launch schedules fixed at baseline scenarios while varying regulatory stringency and fleet electrification pace across sensitivity runs. The analytical framework modeled material, manufacturing process, vehicle class, and distribution channel dimensions over the projection horizon. CAGRs derived from segment-level volume buildups incorporating content-per-vehicle assumptions and regional production mix shifts. Forecast inputs included OEM platform engineering center locations, smelter energy cost structures, and flow-forming equipment lead times.
Macroeconomic conditions sit as an overlay; deviation in Chinese industrial electricity pricing, German automotive export demand, or U.S. long-haul freight volumes would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology substitution rates. Cross-checking against IHS Markit vehicle registration data and LME aluminum forward curves is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
GCC Tire Market
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Steel Tire Cord Market
Tires and Wheels
Tire Bead Wire Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Automotive Airless Tire Market