
 Automotive 3D Printed Tires Market | 2026-2036
Automotive 3D Printed Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive 3D Printed Tires Market Outlook
ISO/ASTM 52900 additive manufacturing qualification standards are unwinding competitive barriers for tire-grade polymer printing, forcing entrants to validate layer adhesion under dynamic load cycles. Michelin leverages captive materials science to sustain formulation leadership across thermoplastic polyurethane blends. The Goodyear Tire & Rubber Company anchors North American testing infrastructure for road-validated 3D printed prototypes. EOS competes on selective laser sintering throughput for geometrically complex tread patterns.
Automotive 3D printed tires are additively manufactured wheel coverings built from elastomeric or composite feedstocks, typically produced through selective laser sintering or material extrusion at layer resolutions below 0.3 millimeters, designed to deliver tunable stiffness gradients and on-demand tread geometries for specific road conditions. Radial tire architectures dominate current prototyping pipelines due to their compatibility with continuous fiber reinforcement paths, while performance tires capture concentrated R&D investment from motorsport validation programs. Thermoplastic polyurethane formulations lead material qualification cycles for their recyclability and shore hardness tunability, whereas carbon fiber composites occupy premium niche applications requiring extreme specific strength.
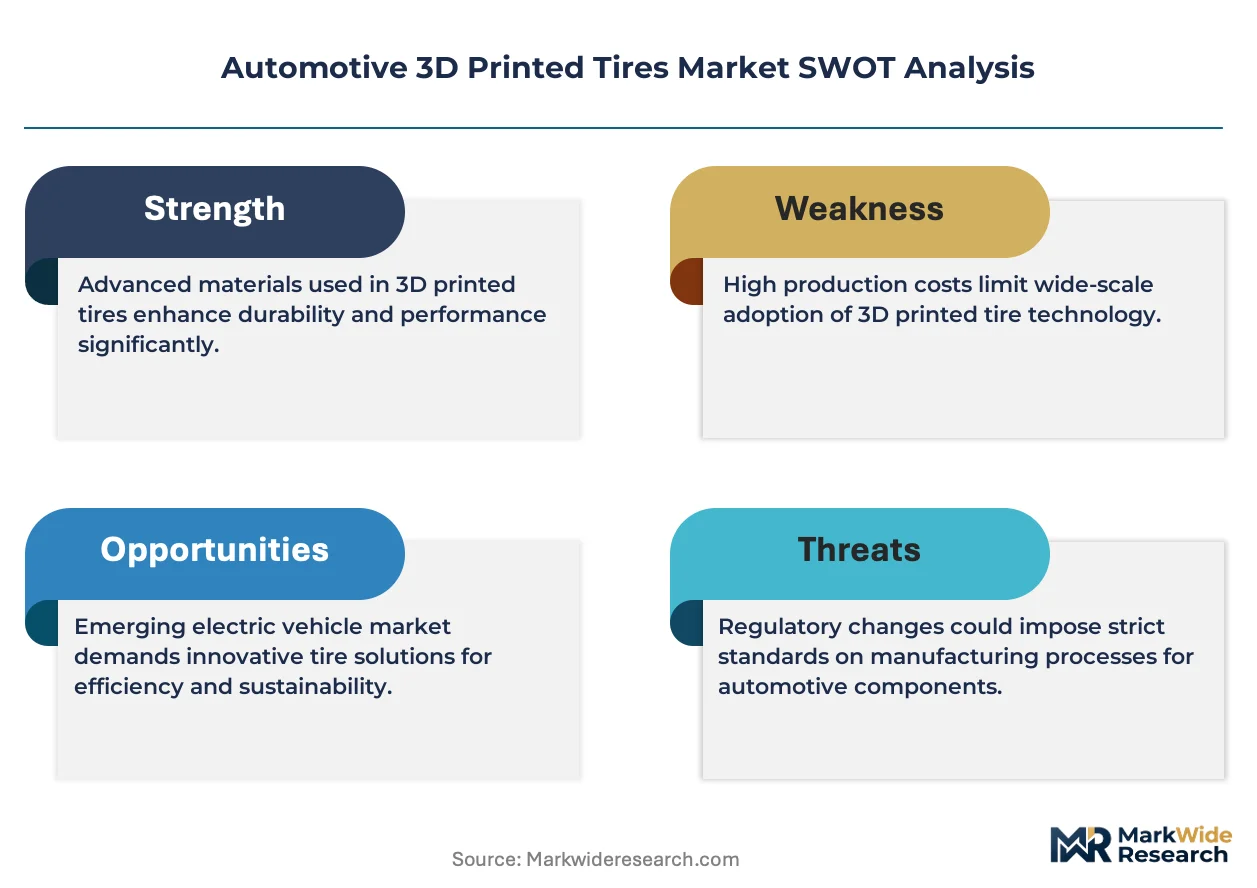
FDA material safety standards for indirect food-contact elastomers, EPA volatile organic compound emissions rules for tire manufacturing facilities, and NHTSA Federal Motor Vehicle Safety Standard 109 for tire performance collectively shape material selection and production site permitting for domestic manufacturers. The EU REACH restriction on polycyclic aromatic hydrocarbons in rubber extends compliance burdens to imported feedstock resins. Stakeholders must monitor how evolving tire labeling regulations in multiple jurisdictions treat additively manufactured products lacking decades of wear-test databases.
Market Dynamics
EU F-Gas Regulation and REACH compliance frameworks are compressing incumbent rubber chemistry while accelerating material substitutions toward recyclable thermoplastic polyurethanes, forcing tire manufacturers to revalidate entire additive manufacturing pipelines.
Growth Catalysts
- REACH polycyclic aromatic hydrocarbon restrictions:European chemical compliance mandates are eliminating conventional carbon black fillers, pulling demand toward certified thermoplastic polyurethane feedstocks that bypass aromatic content limits.
- Selective laser sintering throughput gains:Machine builders have doubled layer deposition rates for elastomeric powders, cutting prototype cycle times for geometrically complex tread patterns below 72 hours.
- Stuttgart-Munich supplier clustering:German automotive OEMs co-located with tier-one additive manufacturing R&D centers are generating captive demand for road-validated 3D printed tire architectures.
Market Restraints
- Thermoplastic polyurethane feedstock concentration:Specialty elastomer resin supply concentrates among three European chemical conglomerates, exposing buyers to allocation risk during polymerization facility turnarounds.
- NHTSA FMVSS 109 wear-test database gaps:Additively manufactured tires lack decades of accumulated road-wear validation data, extending type-approval timelines versus molded rubber equivalents.
- Continuous fiber reinforcement path complexity:Radial architectures with embedded carbon fiber tows require precision tension control that exceeds current multi-material extrusion reliability thresholds.
Strategic Opportunities
- India BIS certification pre-positioning:Domestic tire makers are establishing additive manufacturing cells ahead of anticipated mandatory rolling resistance labeling for passenger vehicle imports.
- Motorsport validation-to-road transfer:Performance tire R&D programs are generating IP portfolios that license into production electric vehicle platforms seeking customizable stiffness gradients.
- Recyclable TPU closed-loop service models:Fleet operators in Germany are piloting subscription-based tire replacement programs where end-of-life material returns directly to powder bed fusion feedstock streams.
Industry Challenges
- ISO/ASTM 52900 qualification specialist scarcity:Layer adhesion validation under dynamic load cycles requires metallurgists cross-trained in elastomer fracture mechanics, a skill intersection present in fewer than 200 engineers globally.
- Multi-jurisdictional tire labeling divergence:EU, US, and Japanese rolling resistance test protocols produce incompatible efficiency grades, forcing parallel certification campaigns for identical 3D printed constructions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive 3D Printed Tires Market |
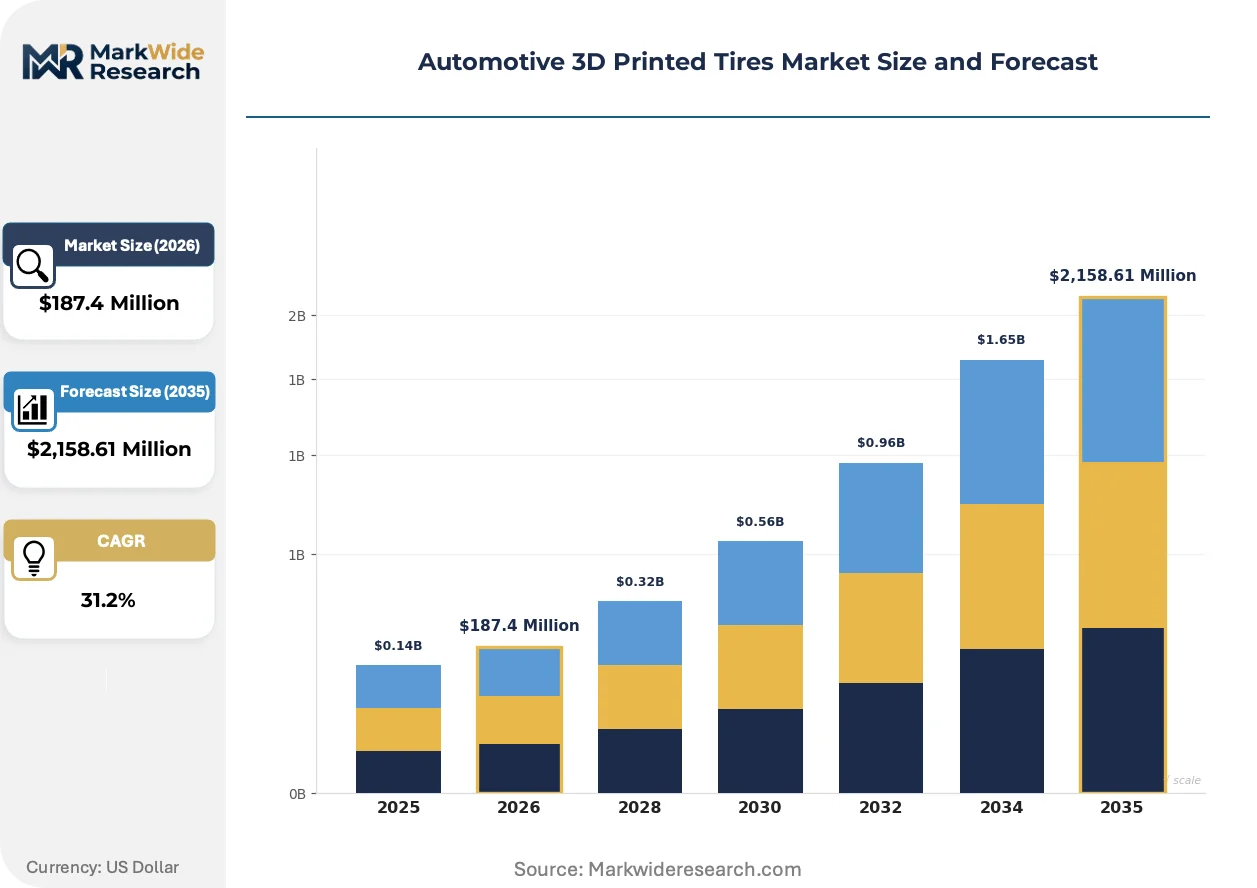
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,158.61 Million |
| CAGR (2026 – 2036) | 31.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias-Ply Tires, Performance Tires, All-Season Tires Material: Thermoplastic Polyurethane, Carbon Fiber, Rubber Compound, Composite Materials Technology: Stereolithography, Fused Deposition Modeling, Selective Laser Sintering, Material Extrusion End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions |
| Companies Covered | AB Volvo, HP, Michelin, 3D Systems, EOS, The Goodyear Tire & Rubber Company, Stratasys, Colibrium Additive, General Motors Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive 3D Printed Tires Market Strategic Shifts
Material extrusion systems are overtaking powder bed fusion for prototyping velocity, while regulatory chemistry constraints and fleet procurement model reinvention are compressing traditional mold-based manufacturing economics.
Thermoplastic polyurethane formulations with shore hardness tunability between 70A and 95A are decomposing the historical trade-off between rolling efficiency and wet grip performance. Luxury electric vehicle manufacturers are adopting these gradient-stiffness architectures for original equipment fitment within 18-month design cycles. This material versatility is decomposing the standardized tire SKU model into lot-size-one production economics.
EU F-Gas Regulation phase-down schedules are banning hydrofluorocarbon blowing agents used in conventional polyurethane tire foams, redirecting R&D investment toward supercritical CO2 physical foaming processes. German chemical regulators are fast-tracking safety data sheet approvals for these alternative expansion technologies. The restriction most acutely affects winter tire segments where cellular structures provide low-temperature compliance.
Fleet procurement departments are unbundling tire acquisition from vehicle lease agreements, creating direct purchasing relationships with additive manufacturing service bureaus. German logistics operators are contracting Stuttgart-based print shops for on-demand tread replacements matched to seasonal route conditions. This disintermediation is most visible in last-mile delivery electrification programs where downtime minimization outweighs unit cost premiums.
Automotive 3D Printed Tires Market Segmentation
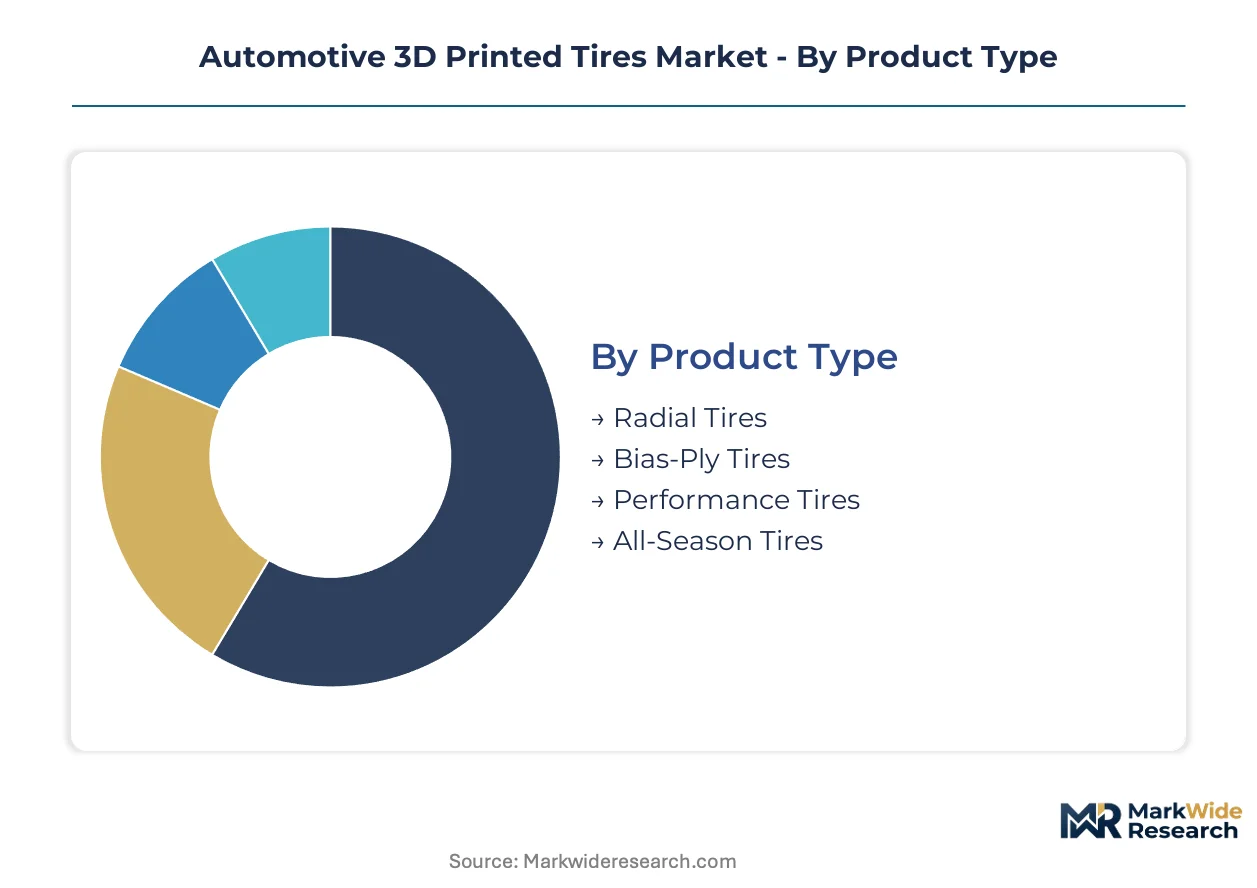
Segmentation in automotive 3D printed tires reveals how additive manufacturing economics fragment across distinct technical and commercial boundaries. Each dimension—product architecture, feedstock chemistry, deposition technology, and buyer type—carries unique qualification burdens and margin profiles that reshape competitive positioning.
Product Type:
Radial tire architectures flow through OEM validation channels requiring NHTSA FMVSS 109 compliance, while bias-ply variants concentrate in aftermarket service bureaus with shorter certification cycles.
- Radial Tires:Continuous fiber reinforcement paths compatible with belt-and-carcass construction enable tunable stiffness gradients for electric vehicle platforms. Stuttgart-based OEMs are validating these architectures for luxury EV fitment where rolling efficiency targets exceed 9.0 kg/t. Supply concentrates among tier-one suppliers with captive selective laser sintering capacity.
- Performance Tires:Motorsport validation programs generate IP portfolios that license into production platforms. German chemical regulators are fast-tracking material approvals for these constructions where shore hardness tunability between 70A and 95A decomposes wet grip trade-offs. Demand clusters around Munich R&D centers with dynamometer testing infrastructure.
- Bias-Ply Tires:Simpler carcass geometry suits prototype iterations with sub-72-hour turnaround requirements.
- All-Season Tires:Cellular tread structures face EU F-Gas Regulation constraints on hydrofluorocarbon blowing agents.
By volume, radial configurations lead. By growth pace, performance variants are climbing the fastest.
Material:
Feedstock chemistry determines recyclability credentials and REACH compliance exposure, with thermoplastic polyurethanes commanding premium positioning against carbon fiber composites.
- Thermoplastic Polyurethane:Shore hardness tunability and closed-loop recyclability align with EU Green Deal circular economy mandates. Three European chemical conglomerates control specialty elastomer resin supply, exposing buyers to allocation risk during polymerization facility turnarounds. Fleet operators in Germany pilot subscription models where end-of-life material returns directly to powder bed fusion streams.
- Carbon Fiber:Extreme specific strength suits premium niche applications requiring embedded tow reinforcement. Precision tension control for radial architectures exceeds current multi-material extrusion reliability thresholds, limiting adoption to selective laser sintering workflows with proven fiber path control.
- Rubber Compound:REACH polycyclic aromatic hydrocarbon restrictions are eliminating conventional carbon black fillers.
- Composite Materials:Hybrid formulations blend TPU matrices with discontinuous fiber reinforcement for cost-sensitive prototyping.
TPU formulations dominate current qualification cycles. Carbon fiber composites are gaining share fastest in motorsport-to-road transfer applications.
Technology:
Deposition method constrains geometric complexity against throughput economics, with powder bed fusion and material extrusion diverging across prototype versus production use cases.
- Selective Laser Sintering:Machine builders have doubled layer deposition rates for elastomeric powders, cutting prototype cycle times below 72 hours for geometrically complex tread patterns. EOS competes on throughput for architectures requiring gradient stiffness control. Stuttgart-Munich supplier clustering generates captive demand for road-validated prototypes.
- Material Extrusion:Overtaking powder bed fusion for prototyping velocity with simpler material handling and reduced powder recycling overhead. FDM-compatible TPU filaments enable desktop-scale iteration for design studios without cleanroom infrastructure.
- Stereolithography:Photopolymer elastomers face limited adoption due to UV degradation sensitivity in tire applications.
- Fused Deposition Modeling:Standardized nozzle architectures reduce equipment capital requirements for entry-tier service bureaus.
Selective laser sintering leads by installed base. Material extrusion is expanding most quickly among aftermarket providers.
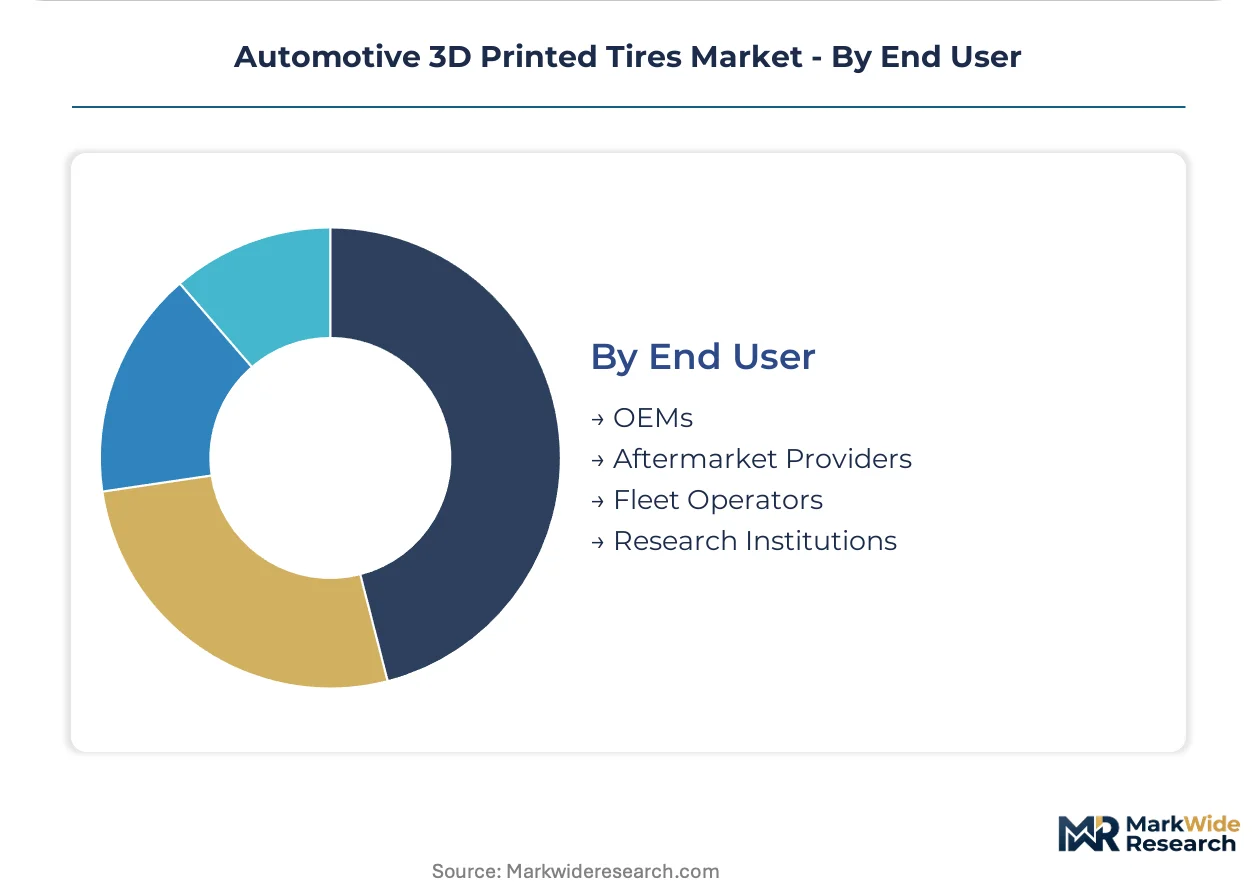
End User:
Procurement authority is unbundling from vehicle lease agreements, with fleet operators establishing direct relationships with additive manufacturing service bureaus.
- OEMs:18-month design cycles for luxury electric vehicle platforms demand road-validated architectures with complete NHTSA FMVSS 109 documentation. ISO/ASTM 52900 qualification requirements force validation of layer adhesion under dynamic load cycles, a capability intersection present in fewer than 200 engineers globally.
- Fleet Operators:Last-mile delivery electrification programs prioritize downtime minimization over unit cost premiums. German logistics operators contract Stuttgart-based print shops for on-demand tread replacements matched to seasonal route conditions.
- Aftermarket Providers:Shorter certification timelines suit bias-ply and all-season architectures without OEM validation burdens.
- Research Institutions:Motorsport validation programs generate foundational IP for performance tire technology transfer.
OEMs dominate value capture. Fleet operators are climbing the fastest as procurement unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German REACH compliance mandates and U.S. NHTSA safety frameworks are accelerating regional specialization in additive manufacturing tire development. National regulators are fragmenting certification pathways while industrial clusters concentrate R&D investment in specific metropolitan zones.
Germany
Luxury electric vehicle OEMs in Stuttgart and Munich generate captive demand for road-validated 3D printed tire architectures. ECHA REACH restrictions on polycyclic aromatic hydrocarbons are eliminating conventional carbon black fillers, pulling manufacturers toward certified thermoplastic polyurethane feedstocks. The Stuttgart-Munich corridor hosts tier-one additive manufacturing R&D centers co-located with automotive headquarters.
United States
NHTSA Federal Motor Vehicle Safety Standard 109 compliance requirements extend type-approval timelines for additively manufactured tires lacking decades of wear-test databases. EPA volatile organic compound emissions rules shape production site permitting for domestic manufacturers. Michigan and Ohio-based automotive testing infrastructure anchors North American prototype validation programs.
China
MIIT dual carbon goals and GB standards for automotive components are redirecting state-backed R&D investment toward recyclable elastomer formulations. Domestic EV manufacturers in the Yangtze River Delta are piloting customizable tire architectures for premium electric platforms. Shanghai and Shenzhen industrial parks host concentrated additive manufacturing service bureau capacity.
India
BIS certification pre-positioning by domestic tire makers is establishing additive manufacturing cells ahead of anticipated mandatory rolling resistance labeling for passenger vehicle imports. Central government PLI scheme incentives for advanced automotive components support technology transfer partnerships. Tamil Nadu and Maharashtra automotive clusters are attracting powder bed fusion equipment deployments.
Japan
METI industrial technology roadmaps prioritize next-generation mobility materials including gradient-stiffness tire architectures. JIS standards development for additively manufactured automotive components is advancing through Nagoya-based testing consortia. Kansai region chemical conglomerates control specialty elastomer resin supply chains serving regional tire manufacturers.
Automotive 3D Printed Tires Market Competitive Environment
Listed leaders compete with private specialists across additive manufacturing technology stacks, creating a tiered structure where scale-driven equipment providers coexist with captive automotive R&D divisions. The vendor base separates into three archetypes: chemical conglomerates with materials science depth, multi-national tire manufacturers with validation infrastructure, and pure-play 3D printing equipment specialists. Competitive positioning hinges on selective laser sintering throughput gains and closed-loop recyclability credentials. M&A activity concentrates on materials feedstock control, while strategic partnerships link equipment providers with automotive OEMs for co-development programs.
Within the chemical and materials tier, Michelin and The Goodyear Tire & Rubber Company exemplify integrated development models spanning formulation through road validation. Among equipment specialists, EOS and 3D Systems occupy positions defined by selective laser sintering throughput and geometric complexity capabilities. HP and Stratasys represent diversified technology conglomerates leveraging broader additive manufacturing portfolios to access automotive tire prototyping demand. Colibrium Additive and General Motors Company illustrate the split between independent service provision and captive OEM R&D integration.
| Leading Market Players |
|---|
| AB Volvo |
| HP |
| Michelin |
| 3D Systems |
| EOS |
| The Goodyear Tire & Rubber Company |
| Stratasys |
| Colibrium Additive |
| General Motors Company |
| Others |
Value Chain & Pricing Dynamics
NHTSA Federal Motor Vehicle Safety Standard 109 gates both supply qualification and price differentiation by mandating road-wear validation databases that only established tire manufacturers possess. This regulatory barrier forces additive manufacturing entrants to absorb extended type-approval costs while incumbent suppliers command certification premiums.
Pricing Analysis
Certification level creates the primary spread across the market. Three-tier pricing structure across NHTSA-validated, CE-marked, and prototype-grade tiers reflects accumulated validation investment. Cost compression in prototype-grade segments is intensifying because material extrusion equipment costs have fallen below selective laser sintering thresholds. Fleet operators exhibit the highest price sensitivity due to unbundled procurement from vehicle leases, while luxury electric vehicle OEMs absorb premiums for road-validated architectures.
Supply Chain Analysis
Germany, China, and the United States anchor specialty elastomer resin production and additive manufacturing equipment fabrication. Feedstock chemistry draws from polycyclic aromatic hydrocarbon-compliant thermoplastic polyurethanes, carbon fiber tow precursors, and supercritical CO2 physical foaming agents. Single-source vulnerability concentrates in three European chemical conglomerates controlling TPU polymerization capacity. Distribution runs through tier-one supplier networks co-located with Stuttgart-Munich and Shanghai-Shenzhen automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive 3D printed tires represent a high-growth disruption as EU F-Gas Regulation phase-downs eliminate hydrofluorocarbon blowing agents and redirect R&D toward recyclable thermoplastic polyurethane architectures.
For Market Incumbents: Fortify formulation leadership through captive materials science investment in shore hardness tunability between 70A and 95A. Deepen backward integration into TPU polymerization capacity to offset allocation risk during European facility turnarounds. Anchor North American testing infrastructure to extend NHTSA validation database advantages against emerging entrants.
For New Entrants and Emerging Players: Differentiate on closed-loop recyclability credentials aligned with EU Green Deal circular economy mandates. Target India BIS certification pre-positioning ahead of anticipated mandatory rolling resistance labeling. Pursue direct fleet operator relationships in German last-mile delivery electrification programs where downtime minimization outweighs unit cost premiums.
For Investors and Strategic Acquirers: EU REACH polycyclic aromatic hydrocarbon restrictions reshape the acquisition landscape by eliminating conventional carbon black fillers and elevating certified TPU feedstock specialists. Long-term viability centers on materials science depth spanning formulation through powder bed fusion compatibility. Watch for ISO/ASTM 52900 qualification specialist scarcity as the inflection signal indicating consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Recyclable TPU Closed-Loop Service Model | German fleet operators pilot subscription programs returning end-of-life material directly to powder bed fusion streams. |
| Motorsport Validation-to-Road IP Licensing | Munich R&D centers transfer performance tire architectures into production electric vehicle platforms. |
| Selective Laser Sintering Throughput Expansion | EOS and equipment specialists double layer deposition rates for elastomeric powders below 72-hour prototype cycles. |
| India BIS Certification Pre-Positioning | Domestic tire makers establish additive manufacturing cells ahead of mandatory rolling resistance labeling. |
| Supercritical CO2 Physical Foaming Process Development | German chemical regulators fast-track safety data sheet approvals for EU F-Gas Regulation compliant expansion technologies. |
Study Parameters
The analysis maps radial and bias-ply architectures, thermoplastic polyurethane and carbon fiber feedstocks, selective laser sintering and material extrusion technologies, each validated through tier-one supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operator logistics directors. Primary interview findings triangulate against secondary sources including NHTSA FMVSS 109 filings, ECHA REACH substance registrations, SEC automotive segment disclosures, and vehicle production databases. Bottom-up segment sizing reconciles with top-down market aggregation across the analysis window.
Volume and value outputs were validated against external benchmarks including installed base estimates for powder bed fusion equipment, chemical industry capacity disclosures, and automotive OEM procurement patterns. The forecast framework models product type, material chemistry, deposition technology, and end-user procurement authority dimensions throughout the projection horizon. CAGRs derive from segment-level growth trajectory analysis incorporating machine builder throughput gain announcements, regulatory phase-down schedules, and fleet electrification adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, NHTSA database accumulation timelines, or TPU feedstock supply stability would require recalibration. Forecasts reflect assumptions regarding layer adhesion validation specialist availability, multi-jurisdictional tire labeling convergence, and supercritical CO2 process scale-up economics. Recalibration cycles align with material shifts in F-Gas Regulation implementation, BIS certification mandate timing, and selective laser sintering equipment deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Saudi Arabia Tire Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Automotive All-Season Tire Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Rail Road Wheels Market