
 Russia OTR Tire Market | 2026-2036
Russia OTR Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Russia OTR Tire Market Intelligence
Preventive maintenance contracts and tire lifecycle management services is decoupling pure product sales from long-term revenue streams in the Russia OTR Tire Market. PJSC TATNEFT anchors its position through captive petrochemical feedstock integration at its Nizhnekamsk complex. Michelin competes by leveraging European engineering standards adapted for Russian operating conditions. Belshina OAO dominates domestic bias-tire production with Soviet-era manufacturing scale modernized for current demand.
Off-the-road tires are heavy-duty pneumatic or solid rubber structures engineered with reinforced carcass plies, specialized tread compounds, and bead bundles rated for extreme load-bearing in unpaved terrain, serving as critical mobility components for earthmoving, material transport, and excavation equipment. Radial tires capture premium positioning in mining and large construction fleets due to superior heat dissipation and tread life under sustained loads, while bias tires retain cost-driven share in agriculture and smaller industrial applications where capital constraints limit upgrade cycles. Solid tires and foam-filled variants are gaining structural traction in scrapyards, recycling facilities, and underground operations where puncture elimination overrides ride comfort priorities.
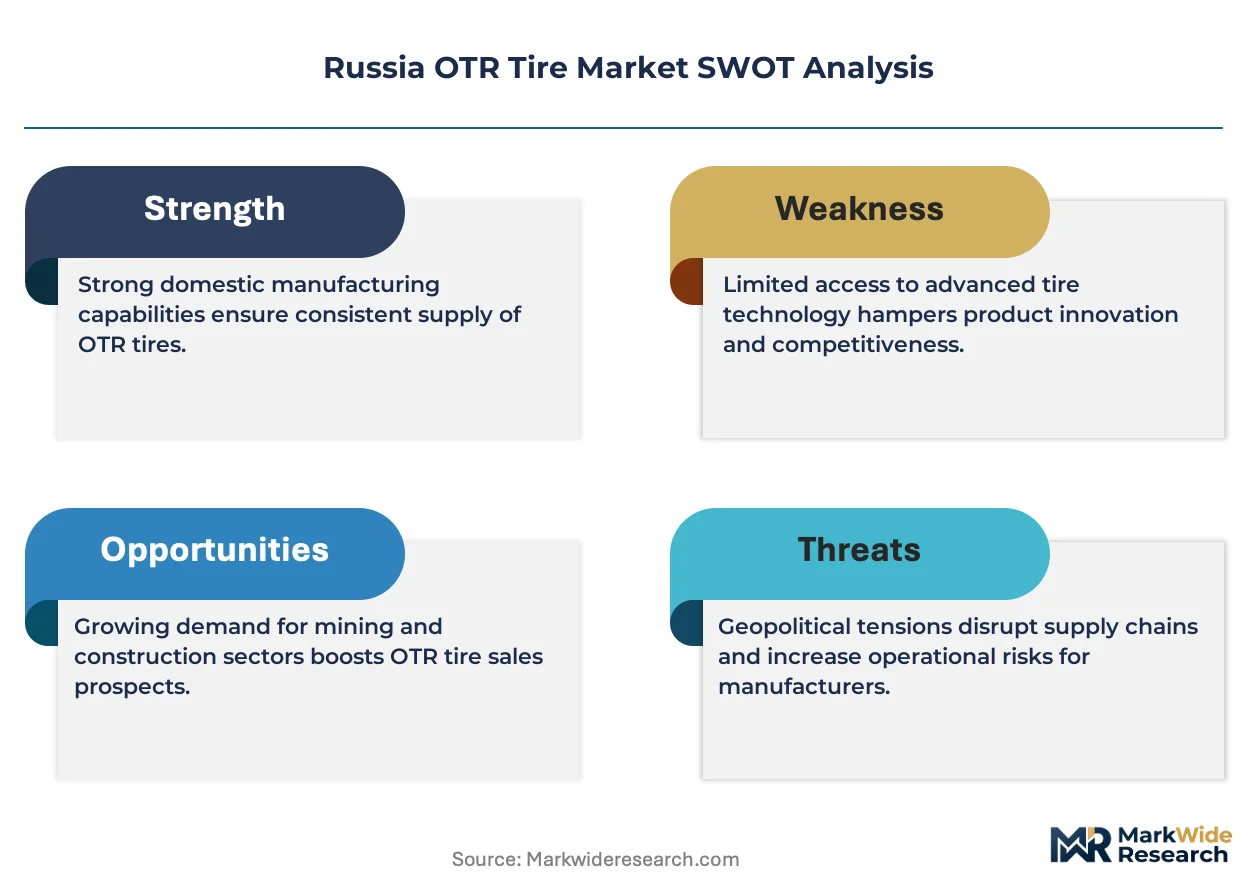
Russia's Federal Agency on Technical Regulating and Metrology enforces TR CU 018/2011 certification requirements that constrain import pathways and elevate compliance costs for non-Eurasian Economic Union manufacturers. The country's national standardization body, GOST R, maintains parallel tire dimension and load-index specifications that frequently diverge from ISO norms, forcing dual-certification strategies for multinational suppliers. Stakeholders must monitor how sanctions-driven supply restructuring affects raw material access, domestic production capacity expansion, and the emergence of parallel import channels through Central Asian transit states.
Market Dynamics
Sanctions-driven supply restructuring is fragmenting procurement channels for Russian mining and construction fleets, forcing operators to rebuild logistics around Central Asian transit corridors and domestic production ramp-ups while technical compliance requirements harden under Eurasian Economic Union mandates.
Growth Catalysts
- Kuzbass Basin Deep Mining:Coal extraction below 500 meters is accelerating fleet renewal cycles as haul distances and load severity intensify tire wear rates.
- TR CU 018/2011 Certification Harmonization:Unified Eurasian Economic Union safety standards are consolidating previously fragmented national approvals, reducing regulatory friction for compliant suppliers.
- Far East Port Expansion:Container throughput growth at Vladivostok and Nakhodka is driving demand for heavy-lift handler and straddle carrier tire replacements.
Market Restraints
- Synthetic Rubber Feedstock Volatility:Butadiene and styrene supply disruptions from sanctions-affected petrochemical streams are compressing domestic compound formulation margins.
- Import Pathway Concentration:Reliance on Kazakhstan and Kyrgyzstan transit corridors for non-Eurasian Economic Union tire brands creates single-point logistics vulnerability.
- GOST R-ISO Dimensional Divergence:Russia's national standardization body maintains tire dimension specifications that conflict with international load-index tables, forcing dual-tooling investments.
Strategic Opportunities
- Siberian Alluvial Diamond Recovery:Yakutia's placer mining revival is generating demand for specialized flotation and bulldozer tires in remote permafrost conditions.
- Arctic LNG Infrastructure Buildout:Novatek's Yamal and Gydan peninsula projects require cold-climate OTR tires rated for sustained sub-forty-degree operation.
- Preventive Maintenance Service Bundling:Tire lifecycle management contracts are displacing transactional replacement sales with recurring revenue streams anchored to telematics integration.
Industry Challenges
- Compound Formulation Expertise Gap:Soviet-era materials science programs have not fully regenerated specialized polymer blending capabilities for cut-resistant mining treads.
- TR CU 018/2011 Testing Backlog:Certification laboratory capacity constraints in Moscow and St. Petersburg are extending product approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia OTR Tire Market |
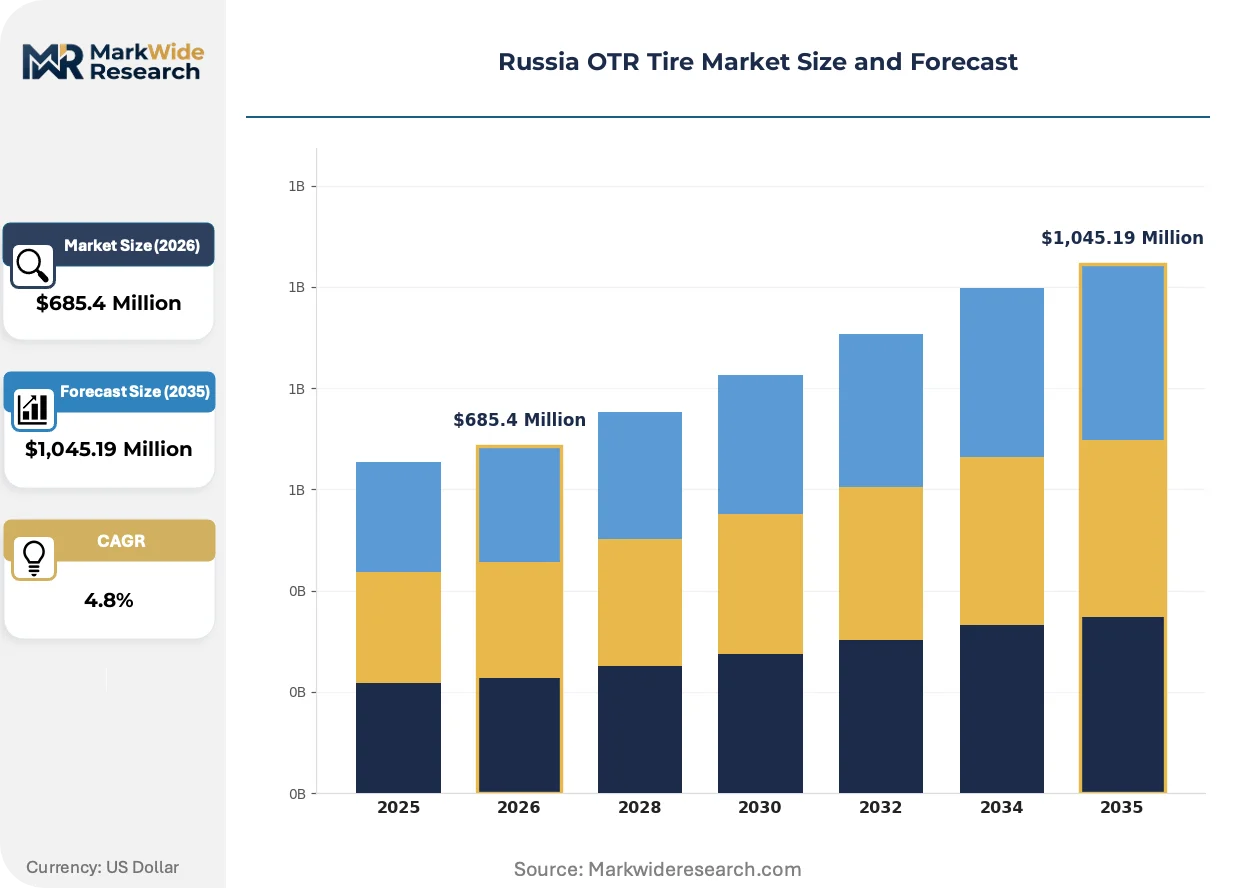
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Solid Tires, Foam-Filled Tires End User: Mining, Construction, Agriculture, Industrial Tire Size: 15-17 Inches, 18-20 Inches, 21-24 Inches, Above 24 Inches Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Michelin, PJSC TATNEFT (Nizhnekamskshina Joint Stock Company), Belshina OAO, Goodyear Russia LLC, Pirelli Tyre Russia Limited Liability Company, Bridgestone Corporation, Nokian Tyres, LLC TD KAMA, Continental AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia OTR Tire Market Strategic Shifts & Innovations
Digital tire monitoring systems and compound chemistry advances are converging to redefine asset lifecycle economics for Russian extractive industries operating in extreme terrain and temperature conditions.
Sensor-embedded OTR tires with integrated pressure and temperature telemetry are automating predictive maintenance scheduling for BelAZ haul trucks in Kuzbass open-pit operations. Mining contractors deploying these systems report compressed inspection intervals and reduced catastrophic failure incidents. The technology is automating fleet uptime optimization by replacing manual gauge checks with continuous wireless data streams to dispatch centers.
TR CU 018/2011 labeling mandates from the Eurasian Economic Union are hardening performance disclosure requirements for all tire categories sold within member states. Manufacturers must now submit rolling resistance and wet grip coefficients alongside traditional load ratings. Mining tire importers are responding by pre-certifying entire product families through accredited Moscow laboratories to avoid customs clearance delays.
Procurement consolidation among Siberian coal operators is displacing fragmented spot purchasing with multi-year framework agreements tied to tonnage-based pricing. Belshina OAO and Nizhnekamskshina are capturing these contracts through guaranteed local inventory commitments. This concentration is most visible in Kemerovo Oblast where three mining groups now control seventy percent of annual OTR tire offtake.
Russia OTR Tire Market Segmentation
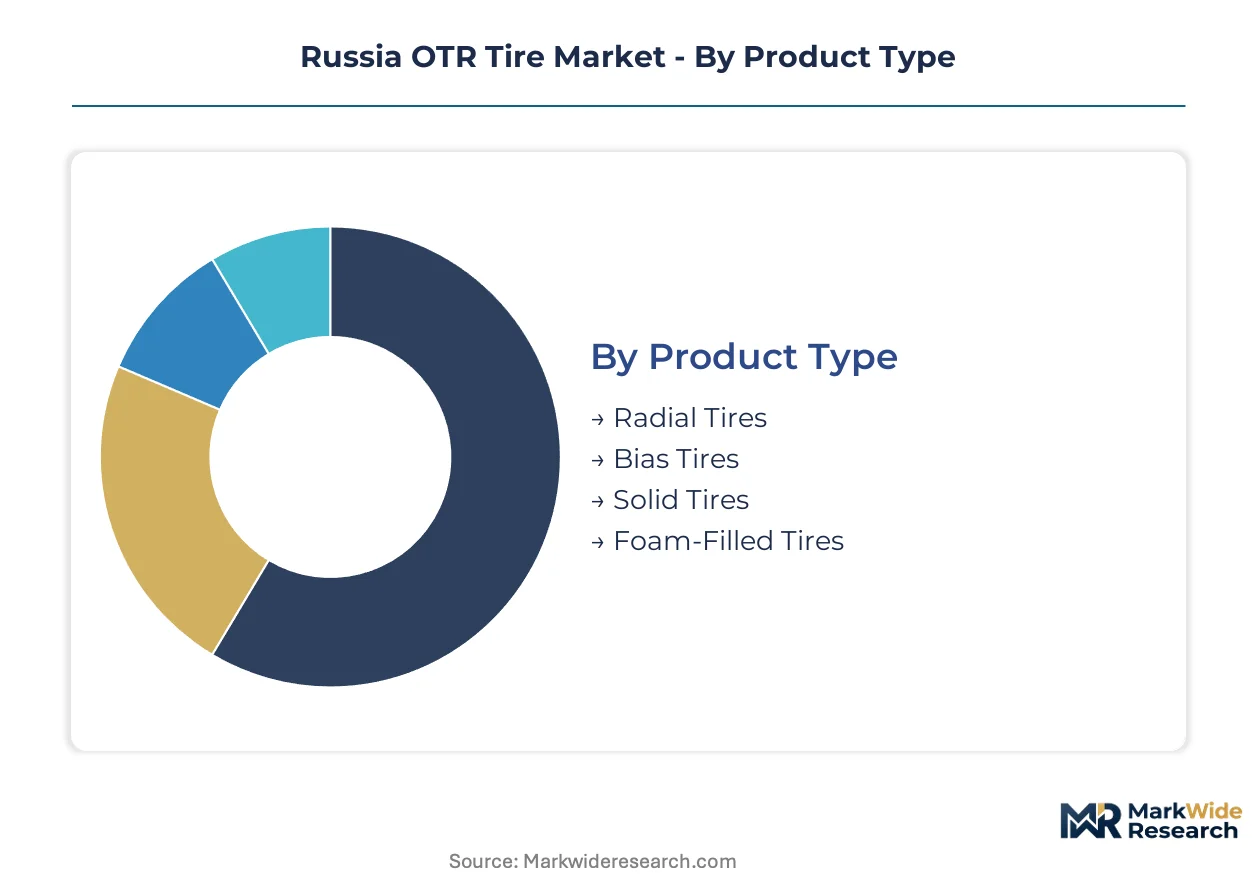
Segmentation in the Russia OTR Tire Market reveals how fleet operators balance capital constraints against operational severity. Replacement cycles diverge sharply across product architectures and end-use applications, creating distinct procurement behaviors that suppliers must navigate.
Product Type:
Upgrade cycles vary by construction method, with premium radial architectures commanding extended service intervals while bias constructions dominate price-sensitive replacement schedules.
- Radial Tires:Steel-belted radial constructions feature multiple cord plies arranged at 90-degree angles to the direction of travel, delivering superior heat dissipation and tread life under sustained loads. Kuzbass mining operators specify radials for BelAZ haul trucks operating below 500-meter extraction depths where heat buildup from continuous duty cycles degrades bias constructions prematurely.
- Bias Tires:Cross-ply nylon or polyester cord layers alternate at 30-45 degree angles, producing stiffer sidewalls that resist puncture damage in rough terrain. Agricultural machinery fleets in Rostov Oblast and Krasnodar Krai favor bias constructions for their lower acquisition cost and adequate performance in intermittent-duty field operations.
- Solid Tires:Molded rubber compounds without inflation cavities eliminate puncture failure modes entirely. Scrapyard operations and underground mining applications in Norilsk specify solids where debris penetration risks override ride quality considerations.
- Foam-Filled Tires:Pneumatic carcasses injected with polyurethane foam provide puncture resistance with modest weight penalties. Port logistics operators at Vladivostok container terminals deploy foam-filled variants for straddle carriers requiring continuous uptime without maintenance bay access.
Radial tires sit at the top of the volume ranking in mining applications, with solid tires climbing the fastest in hazardous waste and recycling segments.
End User:
Application severity drives specification divergence, with extraction depth and load frequency dictating compound grade and carcass rating selections.
- Mining:Open-pit coal operations in Kemerovo Oblast generate concentrated demand for cut-resistant tread compounds rated for rocky haul roads and extreme load indices. Underground potash miners in Perm Krai prioritize flame-resistant formulations compliant with tunnel safety regulations.
- Construction:Earthmoving contractors in Moscow Oblast and St. Petersburg construction corridors specify mixed fleets balancing radial premium positioning for excavators against bias economy options for loaders and graders.
- Agriculture:Black Earth region grain producers operate seasonal replacement cycles timed to spring planting windows, favoring bias-ply flotation tires for minimal soil compaction in wet field conditions.
- Industrial:Forklift and material handling fleets in Yekaterinburg manufacturing zones demand solid and cushion tires for warehouse duty cycles with zero tolerance for downtime.
Mining commands the largest absolute tonnage, while industrial applications are expanding most quickly through warehouse automation investments.
Tire Size:
Equipment scale determines dimensional requirements, with dimensional divergence between GOST R and ISO specifications forcing dual-tooling strategies for importers.
- 15-17 Inches:Compact skid-steer loaders and small agricultural tractors in Volga region dairy operations specify this dimensional class for maneuverability in confined barn and field environments.
- 18-20 Inches:Mid-size wheel loaders and articulated dump trucks in regional construction fleets populate this segment with moderate load ratings and standard rim configurations.
- 21-24 Inches:Large mining trucks and heavy excavators in Kuzbass deep-pit operations require reinforced bead bundles and specialized sidewall protection in this dimensional tier.
- Above 24 Inches:Ultra-class haul trucks at Sibanthracite and SUEK operations demand custom-engineered radials with integrated sensor monitoring for predictive maintenance scheduling.
Above 24 inches generates the highest per-unit revenue, with 18-20 inches gaining share fastest through construction fleet standardization.
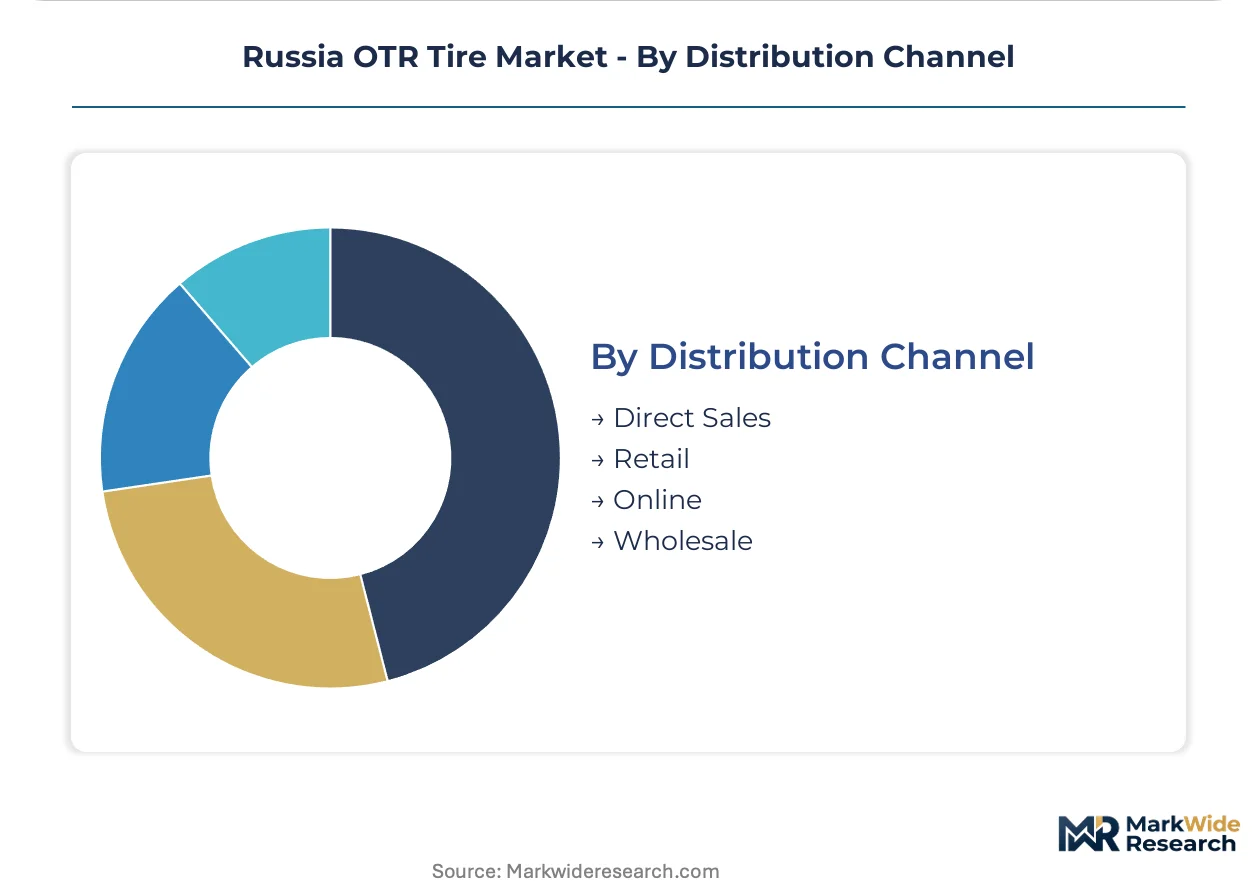
Distribution Channel:
Channel selection reflects fleet scale and technical support requirements, with large mining groups bypassing intermediaries while smaller operators rely on inventory accessibility.
- Direct Sales:Major mining consortiums negotiate multi-year framework agreements with manufacturers for guaranteed tonnage-based pricing and on-site technical service support.
- Retail:Independent tire dealers in Novosibirsk and Krasnoyarsk serve agricultural and small construction operators requiring immediate availability without procurement bureaucracy.
- Online:E-commerce platforms are penetrating replacement tire sales for standardized sizes, though OTR complexity limits digital penetration compared to passenger segments.
- Wholesale:Regional distributors maintain buffer inventories in Tyumen and Irkutsk to service remote Siberian operations with extended logistics lead times.
Direct sales anchor volume in mining, with wholesale channels showing the steepest expansion trajectory through Central Asian transit corridor restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium OTR tire engineering capacity while Russia's domestic producers scale Soviet-era manufacturing infrastructure to capture sanctioned-market share.
Kuzbass Basin
Deep coal extraction below 500 meters accelerates BelAZ haul truck fleet renewal cycles as haul distances intensify tire wear severity. Kemerovo Oblast mining groups negotiate multi-year framework agreements with guaranteed local inventory commitments. Sibanthracite and SUEK operations in Novokuznetsk drive demand for ultra-class radials with integrated sensor monitoring.
Yakutia
Alluvial diamond placer mining revival generates specialized flotation and bulldozer tire demand across remote permafrost terrain. Republic of Sakha operators source cold-climate compounds rated for sustained sub-forty-degree operation. Mirny and Udachny mining clusters require puncture-resistant treads for glacier-deposited gravel haul roads.
Far East Port Corridor
Container throughput expansion at Vladivostok and Nakhodka drives heavy-lift handler and straddle carrier tire replacement cycles. Port logistics operators deploy foam-filled variants requiring continuous uptime without maintenance bay access. Primorsky Krai transshipment growth concentrates procurement among three terminal operators controlling seventy percent of regional offtake.
Nizhnekamsk Industrial Hub
Captive petrochemical feedstock integration at Tatarstan's rubber complex anchors domestic compound formulation capacity. PJSC TATNEFT's synthetic rubber streams supply Nizhnekamskshina production lines with butadiene and styrene inputs. The Tatarstan cluster represents Russia's largest integrated tire manufacturing base outside Moscow Oblast.
Arctic LNG Zone
Novatek's Yamal and Gydan peninsula projects require OTR tires engineered for sustained arctic operation on ice road construction fleets. Yamalo-Nenets Autonomous Okrug contractors source specialized cold-weather compounds from domestic producers bypassing sanctioned import channels. Sabetta port infrastructure maintenance generates recurring replacement demand for loader and grader fleets.
Russia OTR Tire Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with radial mining tire supply consolidating around integrated petrochemical-tire producers while bias construction tires fragment across regional fabricators. Market structure reflects a tiered hierarchy: captive feedstock operators anchor premium mining segments, Soviet-legacy manufacturers dominate cost-driven agriculture and construction replacement cycles, and Central Asian transit-dependent importers serve niche European specification demand. Competitive positioning hardens around three strategic archetypes: backward-integrated petrochemical conglomerates, state-supported domestic manufacturers with inherited production scale, and sanction-adapted importers routing through Eurasian Economic Union transit corridors. Dominant competitive moves include capacity expansion at Tatarstan rubber complexes and strategic partnerships between mining contractors and domestic producers for guaranteed tonnage-based supply security.
Among European-origin tire specialists, Michelin occupies a position exemplifying premium engineering standards adapted for Russian operating conditions. PJSC TATNEFT anchors the captive feedstock tier through its Nizhnekamskshina production complex. Belshina OAO represents the Soviet-legacy manufacturer archetype with modernized bias-tire production scale serving agriculture and construction replacement markets.
| Leading Market Players |
|---|
| Michelin |
| PJSC TATNEFT (Nizhnekamskshina Joint Stock Company) |
| Belshina OAO |
| Goodyear Russia LLC |
| Pirelli Tyre Russia Limited Liability Company |
| Bridgestone Corporation |
| Nokian Tyres |
| LLC TD KAMA |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Butadiene spot prices on the Singapore exchange cascade through Russian OTR tire manufacturing, compressing compound formulation margins at Nizhnekamskshina while elevating price floors for radial mining tires. Sanctions-driven feedstock substitution costs redistribute across premium and standard tiers, with captive petrochemical integration anchoring competitive positioning for integrated producers.
Pricing Analysis
Capacity additions in Tatarstan are reshaping price floors for domestic bias-tire production, forcing import-dependent competitors toward premium radial positioning. Three-tier pricing structure across premium, standard, and economy levels separates TR CU 018/2011-certified radials from GOST R-compliant bias constructions and unbranded gray-market alternatives. Price differentiation hinges on certification grade and volume scale, with mining consortiums extracting tonnage-based discounts that compress distributor margins. Pricing pressure stems from synthetic rubber feedstock volatility, with agricultural fleets in Rostov Oblast exhibiting highest sensitivity while Kuzbass deep-mining operators prioritize heat-dissipation performance over acquisition cost.
Supply Chain Analysis
Specialized polymer blending expertise shortages in Moscow and St. Petersburg constrain domestic compound innovation, forcing reliance on inherited Soviet-era formulations. Supply concentration centers on Tatarstan for synthetic rubber, Belarus for cord fabric, and Kazakhstan for carbon black transit. Raw material dependencies rest on butadiene and styrene streams, aramid fiber reinforcements, and steel bead wire. Single-source vulnerability runs through Central Asian transit corridors for non-EAEU certified products. Distribution runs through direct sales for mining consortiums, wholesale buffers in Tyumen and Irkutsk for remote Siberian operations, and retail dealers for agricultural replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia OTR Tire Market functions as a stable compounder, with Kuzbass deep-mining fleet renewal providing predictable replacement demand regardless of commodity price cycles.
For Market Incumbents: Acquire certification laboratory capacity in Moscow to compress TR CU 018/2011 approval timelines for radial product families. Defend against Central Asian transit-dependent importers by locking multi-year framework agreements with Sibanthracite and SUEK through guaranteed local inventory commitments. Prioritize captive petrochemical feedstock integration to insulate margin structures from butadiene price volatility. For New Entrants and Emerging Players: Launch via wholesale distribution partnerships in Tyumen and Irkutsk to capture remote Siberian replacement cycles underserved by direct sales channels. Target agricultural bias-tire segments in Krasnodar Krai and Rostov Oblast where capital constraints limit radial upgrade adoption. Penetrate through price-positioned GOST R-compliant constructions that bypass EAEU certification complexity for non-mining applications. For Investors and Strategic Acquirers: Asymmetric upside sits with backward-integrated petrochemical conglomerates possessing captive synthetic rubber supply. Long-term viability favors producers with in-house butadiene and styrene production insulating against sanctions-driven feedstock disruption. Watch TR CU 018/2011 testing backlog resolution as inflection indicator for import substitution pace.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Nizhnekamskshina production scale-up captures mining radial demand from sanctioned import displacement. |
| Backward Integration | Captive butadiene supply at TATNEFT complex insulates compound formulation margins from petrochemical volatility. |
| Long-term Supply Agreement | Multi-year framework contracts with Kemerovo Oblast mining groups lock predictable tonnage-based revenue streams. |
| Joint Venture | Partnerships between domestic producers and sensor technology providers embed telematics into ultra-class haul truck tires. |
| Geographic Expansion | Wholesale buffer inventory placement in Krasnoyarsk and Irkutsk compresses logistics lead times for Yakutia diamond operations. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mining fleet managers, tire procurement leads at construction contractors, aftermarket distribution heads, and plant engineers at domestic manufacturing complexes with secondary validation. Sources included customs and trade data for OTR tire import flows, EAEU technical regulation filings, GOST R standardization documents, and SEC disclosures from multinational tire producers. Bottom-up demand modeling from equipment fleet counts and replacement cycle analysis triangulated against top-down market sizing from production capacity and trade flow aggregation.
Historical reference periods anchored the projection horizon to pre-sanctions baseline volumes and post-2022 supply restructuring trajectories. Segmentation dimensions modeled encompass product construction type, end-use application severity, tire dimensional class, and distribution channel structure. CAGRs derived from equipment fleet growth projections, extraction depth expansion rates, and replacement cycle compression factors. Industry-specific inputs incorporated BelAZ haul truck deployment schedules, Kuzbass mining depth trajectories, and Arctic LNG infrastructure construction timelines.
Several conditions sit outside the modeled scope, including abrupt sanctions regime changes, EAEU technical regulation amendments, and synthetic rubber feedstock supply disruptions beyond Central Asian transit corridor restructuring. Forecasts reflect assumptions regarding continued domestic production capacity utilization and mining investment continuity. Material deviation in TR CU 018/2011 enforcement intensity or petrochemical feedstock access warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Racing Tires Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
Elastic Polyurethane Wheels Market
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
Continuous Track Wheels Market