
 Automotive Winter Tire Market | 2026-2036
Automotive Winter Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Winter Tire Market Analysis
Single-source rubber procurement is pivoting toward multi-source synthetic polymer agreements across the winter tire supply base. Continental AG leverages captive silica supply for Nordic compound grades. Nokian Tyres plc anchors its position through extreme-condition testing infrastructure in Finnish Lapland. Bridgestone Corporation competes via distributed manufacturing across multiple cold-climate zones.
Automotive winter tires are pneumatic tires engineered with specialized tread compounds maintaining elasticity below seven degrees Celsius, featuring siped tread blocks and aggressive void ratios for snow and ice traction; they serve the primary commercial purpose of reducing accident rates and maintaining vehicle mobility during legally mandated or voluntarily adopted cold-weather driving periods. Non-studded tires now lead volume shipments across European markets where stud restrictions have proliferated, while studded tires retain premium positioning in markets with minimal road-surface legislation. Performance tires within the winter category command margin concentration as SUV and light truck adoption drives larger-diameter fitments.
The EU F-Gas Regulation and REACH framework govern chemical inputs in winter tire manufacturing, while ECE R117 sets minimum wet-grip and snow-traction thresholds for type approval across member states. The US NHTSA maintains separate UTQG grading standards that do not mandate winter-specific testing, creating a regulatory divergence that shapes product portfolio allocation by geography. Stakeholders must monitor the trajectory of EU Green Deal tire-labeling requirements and anticipate how embedded carbon accounting will reshape compound formulation decisions and supplier qualification criteria.
Market Dynamics
EU F-Gas Regulation and REACH compliance are compressing compound formulation flexibility while simultaneously elevating qualification barriers for raw material suppliers serving winter tire manufacturers.
Growth Catalysts
- Nordic Legal Mandates:Norway and Finland enforce winter tire installation during statutorily defined cold-weather periods, creating non-discretionary replacement cycles that stabilize baseline demand regardless of economic conditions.
- REACH Chemical Standards:The EU's tightening material compliance framework is accelerating R&D investment in bio-based silica and alternative plasticizers that maintain low-temperature elasticity without restricted substances.
- EV OEM Bundling:Electric vehicle fitment programs are integrating winter tire packages into new vehicle purchases, capturing consumers at point-of-sale rather than aftermarket replacement intervals.
Market Restraints
- Natural Rubber Volatility:Hevea brasiliensis supply concentration across Southeast Asian plantations exposes compounders to climate-driven harvest disruptions and futures market speculation.
- Stud Prohibition Spread:Urban road-surface preservation ordinances in Germany, Sweden, and Japan are eliminating studded tire options in high-density corridors, constraining product portfolio breadth.
- Silica Processing Bottlenecks:Precipitated silica capacity for high-performance winter grades concentrates among limited chemical processors, creating input scarcity during Q3 pre-season manufacturing ramps.
Strategic Opportunities
- Polish Aftermarket Expansion:Underpenetrated vehicle parc in Poland's mountainous southern provinces presents volume upside as disposable income growth accelerates seasonal tire adoption.
- Run-Flat Winter Hybrids:Convergence of self-supporting sidewall technology with cold-weather compounds addresses EV weight penalties and eliminates spare tire packaging constraints.
- EU Green Deal Labeling:Embedded carbon accounting requirements will favor manufacturers with vertically integrated renewable energy supply chains, creating differentiation premium capture.
Industry Challenges
- Compound Formulation Talent Scarcity:Specialized polymer science expertise for sub-zero elasticity engineering concentrates among retiring cohorts, constraining R&D pipeline velocity.
- ECE R117 Certification Timelines:Extended wet-grip and snow-traction testing protocols for type approval delay new product launches by 8-14 months, compressing selling seasons.
- Multi-Source Qualification Burden:Synthetic polymer supply diversification strategies require redundant supplier audits and compound validation cycles that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Winter Tire Market |
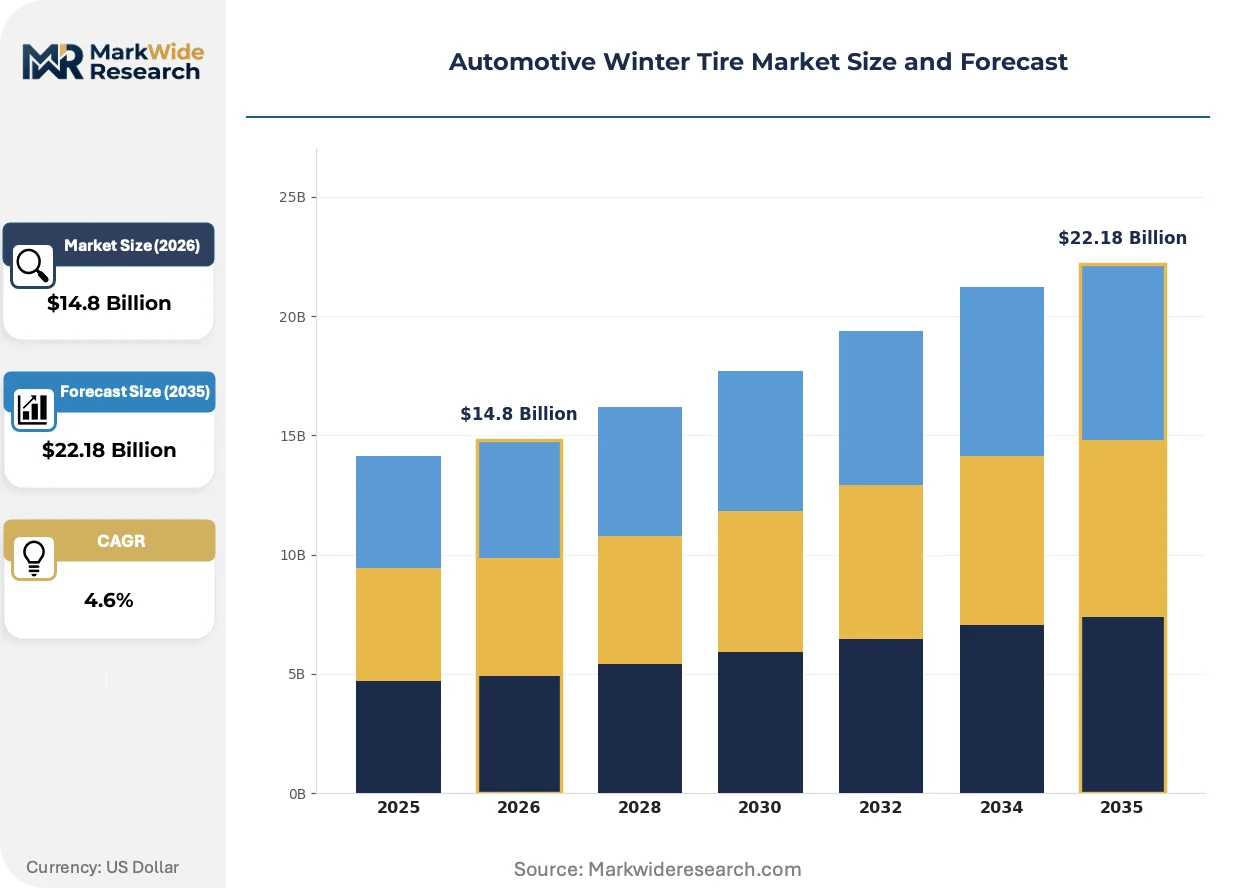
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Studded Tires, Non-Studded Tires, Performance Tires, All-Weather Tires End User: Passenger Vehicles, Light Trucks, SUVs, Commercial Vehicles Tire Size: Compact, Mid-Size, Full-Size, Heavy-Duty Distribution Channel: Online Retail, Specialty Stores, Service Centers, Supermarkets |
| Companies Covered | Bridgestone Corporation, Continental AG, The Goodyear Tire & Rubber Company, Michelin, Pirelli & C. S.p.A., Sumitomo Rubber Industries, The Yokohama Rubber Co., Ltd., Nokian Tyres plc, Hankook Tire & Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Winter Tire Market Emerging Trajectories
Material science convergence and regulatory carbon accounting are restructuring how winter tire manufacturers design compounds, qualify suppliers, and position products across price-performance tiers.
Functionalized silica-silane coupling systems are unifying grip performance across wet asphalt, packed snow, and bare ice surfaces within single compound formulations. Tier-1 suppliers are adopting these systems for SUV and light truck fitments that dominate European replacement demand. This unification is compressing the historical trade-off between ice traction and rolling resistance that previously forced segment-specific product lines.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in extender oils are forcing reformulation of tread compounds across all EU member states. Manufacturers must validate alternative plasticizers through accelerated aging tests before seasonal production windows open. Nordic markets with the longest mandated usage periods face the steepest compliance cost absorption.
Fleet procurement departments are consolidating seasonal tire decisions under total-cost-of-ownership frameworks that weigh accident rate reduction against per-unit acquisition price. Leasing companies and commercial van operators are displacing decentralized branch-level purchasing with centralized category management. This concentration is most visible in Germany's Mittelstand logistics sector where multi-vehicle contracts now specify winter tire inclusion.
Automotive Winter Tire Market Segmentation
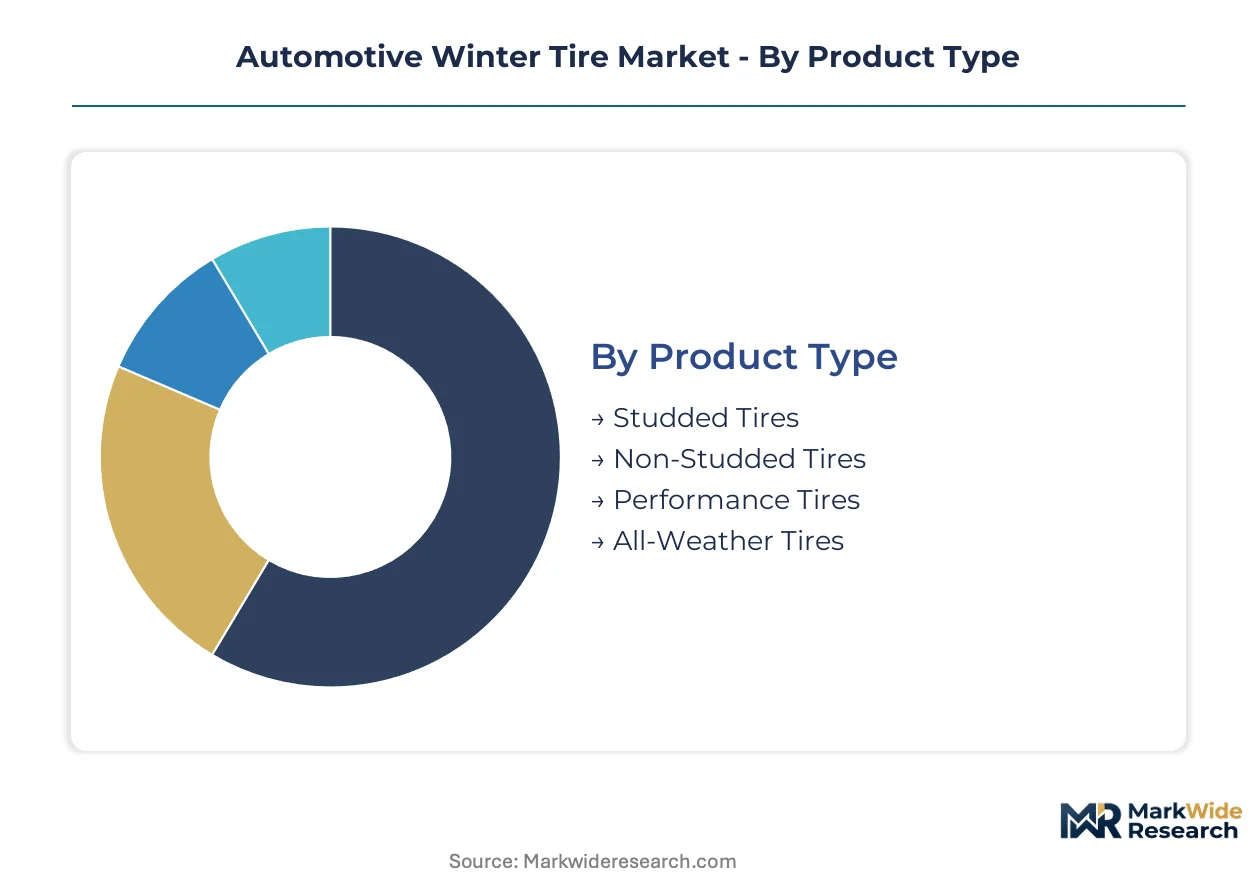
Winter tire segmentation reveals how capital allocation, regulatory pressure, and fleet procurement patterns concentrate margin capture across distinct product tiers. Manufacturers optimize compound R&D and mold investments against segment-specific volume elasticity and certification burdens.
Product Type:
Capital intensity peaks in segments requiring dual-compound molding and specialized siping equipment, where tooling amortization spans multiple seasonal cycles.
- Studded Tires:Metal pin insertion machinery and tungsten carbide tip anchoring demand dedicated production lines with limited flexibility. Norway and Finland's legal mandates sustain replacement demand despite urban stud prohibitions in Germany and Sweden compressing addressable market breadth.
- Non-Studded Tires:Advanced silica-silane coupling systems and multi-cell tread geometries dominate European volume. REACH Annex XVII compliance on extender oils accelerates reformulation costs across Nordic markets with longest mandated usage periods.
- Performance Tires:Larger-diameter fitments for SUV and light truck segments command compound complexity premiums.
- All-Weather Tires:Three-peak mountain snowflake certification bridges seasonal categories for moderate-climate drivers.
Most installed capacity flows through Non-Studded Tires. Expansion is steepest in Performance Tires.
End User:
Procurement centralization varies sharply across customer types, with fleet operators consolidating seasonal decisions under total-cost-of-ownership frameworks.
- Passenger Vehicles:Individual replacement cycles dominate volume but fragment price realization. Germany's Mittelstand logistics sector increasingly specifies winter tire inclusion in multi-vehicle contracts, displacing decentralized branch-level purchasing.
- SUVs:Heavier curb weights and larger contact patches drive demand for reinforced sidewall constructions and specialized load ratings. EV fitment programs bundle winter packages at point-of-sale, capturing consumers outside traditional aftermarket intervals.
- Light Trucks:Commercial van operators prioritize durability metrics over ice traction scores.
- Commercial Vehicles:Fleet procurement departments weigh accident rate reduction against per-unit acquisition price in centralized category management.
Volume concentrates in Passenger Vehicles. Margin expansion is strongest in SUVs.
Tire Size:
Mold inventory requirements scale non-linearly with rim diameter, creating working capital constraints for mid-size manufacturers.
- Mid-Size:European replacement demand centers on 16-18 inch fitments for compact SUVs and C-segment sedans. Silica processing bottlenecks during Q3 pre-season manufacturing ramps concentrate supply risk in this high-volume band.
- Full-Size:19-21 inch diameters for premium SUVs and electric vehicles require specialized bead construction to manage EV weight penalties. Run-flat winter hybrid development targets this segment to eliminate spare tire packaging constraints.
- Compact:Smaller urban vehicles in southern European markets with voluntary adoption patterns.
- Heavy-Duty:Commercial vehicle fitments with extended mileage warranties and retread compatibility.
Production gravity centers on Mid-Size. Technology investment is migrating toward Full-Size.
Distribution Channel:
Channel economics reflect installation service bundling requirements and seasonal inventory velocity constraints.
- Service Centers:Tire mounting and balancing equipment investments create local moats. ECE R117 certification delays of 8-14 months compress selling seasons, favoring channels with storage capacity and rapid turnover logistics.
- Specialty Stores:Expertise in load rating consultation and speed index matching sustains premium positioning. Poland's mountainous southern provinces present volume upside as disposable income growth accelerates seasonal adoption through established retail networks.
- Online Retail:Price transparency pressures margin but expands geographic reach.
- Supermarkets:Seasonal promotional cycles and limited SKU breadth.
Transaction volume flows primarily through Service Centers. Digital penetration is climbing fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting winter tire manufacturing toward jurisdictions with lower carbon-accounting compliance costs while Nordic legal mandates anchor replacement demand regardless of economic cycles.
Germany
Mittelstand logistics fleets are consolidating seasonal procurement under total-cost-of-ownership frameworks that prioritize accident-rate reduction. The KBA enforces ECE R117 type-approval timelines that compress new product launch windows. Stuttgart and Munich industrial corridors host compound R&D facilities serving premium SUV fitments.
Norway
Statutory winter tire mandates during defined cold-weather periods create non-discretionary replacement cycles stabilizing baseline demand. The Norwegian Public Roads Administration enforces stud prohibitions in urban zones that reshape product portfolio allocation. Tromsø and Bodø municipalities drive extreme-condition testing requirements for Arctic-grade compounds.
Finland
Legally mandated winter tire installation periods sustain replacement volume independent of consumer discretionary spending. Finnish Transport and Communications Agency regulations align with EU REACH Annex XVII restrictions on extender oils. Ivalo and Rovaniemi testing infrastructure anchors Nokian Tyres plc's extreme-condition validation capabilities.
Poland
Underpenetrated vehicle parc in southern mountainous provinces presents volume upside as disposable income accelerates seasonal adoption. Polish Centre for Testing and Certification aligns with ECE R117 thresholds for type approval. Kraków and Zakopane retail networks specialize in load-rating consultation for alpine driving conditions.
United States
NHTSA UTQG grading standards diverge from EU winter-specific testing mandates, shaping portfolio allocation by geography. No federal winter tire mandate exists, though state-level chain laws in Colorado and California create patchwork compliance requirements. Detroit-area OEM bundling programs for electric vehicles are integrating seasonal tire packages at point-of-sale.
Automotive Winter Tire Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue all-weather certification bridges and embedded carbon differentiation. The supplier base concentrates among integrated chemical processors and mold-fabrication specialists with multi-decade compound expertise. Three archetypes dominate: captive silica producers, distributed manufacturing networks, and extreme-condition testing specialists. Competitive moves center on backward integration into renewable energy supply chains and redundant supplier qualification for REACH-compliant raw materials.
Among Japanese fabricators, Bridgestone Corporation and Sumitomo Rubber Industries exemplify scale-driven manufacturing networks across multiple cold-climate zones. Continental AG represents the captive-input archetype through integrated silica supply chains. Nokian Tyres plc anchors the extreme-condition specialization tier through Finnish Lapland testing infrastructure.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Continental AG |
| The Goodyear Tire & Rubber Company |
| Michelin |
| Pirelli & C. S.p.A. |
| Sumitomo Rubber Industries |
| The Yokohama Rubber Co., Ltd. |
| Nokian Tyres plc |
| Hankook Tire & Technology Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Performance-mid-economy pricing stratification across winter tire tiers manifests in divergent supply chain configurations, where premium compound R&D investments in Nordic markets coexist with commoditized sourcing for southern European voluntary adoption segments. REACH Annex XVII compliance costs concentrate in mandated-usage markets while spot-market natural rubber procurement dominates price-sensitive tiers.
Pricing Analysis
Distributor markups compress as fleet procurement departments consolidate seasonal tire decisions under total-cost-of-ownership frameworks. Three-tier pricing structure across premium, standard, and economy levels tracks ECE R117 certification grades and silica-silane coupling complexity. Pricing pressure stems from silica processing bottlenecks during Q3 pre-season manufacturing ramps. Fleet operators exhibit lowest price sensitivity; individual replacement buyers in southern Europe show highest elasticity.
Supply Chain Analysis
Natural rubber supply rests on Thai, Indonesian, and Malaysian plantation networks vulnerable to climate-driven harvest disruptions. Precipitated silica for high-performance grades draws from German and Chinese chemical processors; tungsten carbide studs for Nordic markets hinge on limited metallurgical suppliers. Single-source vulnerability in functionalized silane coupling agents creates qualification bottlenecks. Distribution runs through service centers with seasonal storage capacity and rapid turnover logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the automotive winter tire market hinges on embedded carbon accounting differentiation and EV OEM bundling capture, as REACH compliance costs filter out undifferentiated compounders.
For Market Incumbents: Lock in captive silica supply agreements and redundant polymer qualification cycles before ECE R117 certification timelines compress further. Defend Nordic market position through extreme-condition testing infrastructure investments that emerging entrants cannot replicate. Prioritize backward integration into renewable energy supply chains to capture EU Green Deal labeling premiums. For New Entrants and Emerging Players: Direct-to-fleet digital platforms bypass established service center networks and capture centralized procurement decisions in Germany's Mittelstand logistics sector. Target Poland's underpenetrated southern mountainous provinces where disposable income growth accelerates seasonal adoption. Lead with run-flat winter hybrid offerings addressing EV weight penalties and spare tire elimination. For Investors and Strategic Acquirers: Consolidation pressure builds where compound formulation talent scarcity constrains R&D pipeline velocity and multi-source qualification burdens strain quality assurance bandwidth. Long-term viability favors manufacturers with vertically integrated renewable energy supply chains and Finnish Lapland testing assets. Watch silica processing capacity expansion announcements as inflection indicators for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Supply | Captive precipitated silica production insulates Continental AG from Q3 pre-season processing bottlenecks. |
| Extreme-Condition Testing Infrastructure | Finnish Lapland validation facilities anchor Nokian Tyres plc's Arctic-grade compound credibility. |
| EV OEM Bundling Partnerships | Point-of-sale winter tire packages capture consumers outside traditional aftermarket replacement cycles. |
| REACH-Compliant Bio-Based Compound Development | Alternative plasticizer validation accelerates R&D investment ahead of Annex XVII enforcement. |
| Run-Flat Winter Hybrid Technology | Self-supporting sidewall convergence addresses EV weight penalties and eliminates spare tire packaging constraints. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tire compound R&D directors, OEM platform engineers, aftermarket distributors, and fleet procurement managers with secondary validation through ECE R117 type-approval databases, REACH Annex XVII regulatory filings, and vehicle registration data from Nordic transport agencies. Bottom-up segment modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-weighting across product type, end user, tire size, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from elasticity modeling against Nordic legal mandate enforcement patterns and EV adoption curves. Forecast inputs incorporated silica processing capacity utilization rates and natural rubber futures market volatility indices.
The model assumes a particular technology adoption path; alternative pathways for functionalized silica-silane coupling systems would alter the outlook. Forecasts reflect assumptions regarding REACH enforcement consistency and ECE R117 certification timeline stability. A small set of triggers—EU Green Deal labeling implementation pace, EV OEM bundling program expansion, and Nordic stud prohibition spread—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Airless Tires Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Elastic Polyurethane Wheels Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Automotive Tubeless Tire Market