
 Carbon Wheels Market | 2026-2036
Carbon Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Wheels Market Analysis
Professional racers and custom builders are reorganizing the buyer hierarchy for carbon wheels as enthusiast cyclists defer purchases amid component cost inflation. Carbon Revolution leverages vertical integration from fiber to finished rim to control quality consistency across its Australian manufacturing base. BST Wheels competes through deep specialization in motorcycle-to-cycling technology transfer, while thyssenkrupp Carbon Components anchors European OEM supply relationships with its industrial carbon fiber pedigree.
Carbon wheels are rigid, lightweight rotational components manufactured from continuous carbon fiber reinforced polymer prepregs, typically cured under heat and pressure to achieve tensile strengths exceeding steel at one-quarter the mass, with primary purpose of reducing unsprung weight and aerodynamic drag in competitive cycling applications. Tubeless technology variants command expanding share as sealant compatibility and hookless bead standards mature, while full carbon monocoque construction dominates premium price tiers where margin pools concentrate. Clincher formats retain volume leadership among enthusiast cyclists due to compatibility with existing tire inventories, though track and triathlon segments sustain niche premium positioning.
FDA oversight of bicycle component safety in the United States intersects with ISO 4210 frame and fork testing standards that manufacturers must satisfy for international market access, while Germany's TÜV and KBA protocols impose additional fatigue-cycle verification for high-performance wheel systems sold into European racing channels. The EU Green Deal's embodied carbon tracking requirements are beginning to shape supplier selection criteria for fiber sourcing and resin chemistry. Stakeholders must monitor evolving certification harmonization between regional testing regimes to avoid duplicate validation costs that erode product line profitability.
Market Dynamics
Tubeless-ready hookless rim profiles are forcing rapid retooling across manufacturing footprints as ISO 5775 bead-seat tolerances tighten and professional teams demand sub-300-gram rim weights for climbing stages.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Fiber sourcing transparency is becoming a procurement filter for OEM wheel contracts, pushing suppliers toward recycled precursor materials and bio-based epoxy chemistries.
- Triathlon and gran fondo participation:Age-group athletes in Germany, Switzerland, and Belgium are upgrading to full-carbon wheelsets as race calendars expand and qualifying standards stiffen.
- TÜV fatigue-cycle verification:Third-party certification is unlocking access to premium retail channels where uncertified products face delisting, creating pull-through for validated manufacturers.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs swing with oil and natural gas feedstock markets, compressing margin stability for rim producers without backward integration into fiber production.
- Toray and Mitsubishi Chemical supply concentration:Three Japanese conglomerates control over seventy percent of aerospace-grade PAN precursor supply, creating bottleneck risk for cycling-specific fiber grades.
- Aluminum wheel durability perception:Recreational cyclists in cost-sensitive segments continue viewing metal rims as damage-tolerant alternatives, slowing carbon conversion in entry-level road categories.
Strategic Opportunities
- Indian domestic racing infrastructure:The country's national cycling federation is building UCI-classified velodromes and criterium circuits, creating first-mover advantage for wheel brands establishing local assembly partnerships.
- E-bike integration:Mid-drive motor systems are stressing conventional spoke tension limits, opening white space for carbon wheelsets engineered to handle regenerative braking torque loads.
- CSRD supply chain disclosure mandates:European corporate sustainability reporting is forcing fleet and team sponsors to document Scope 3 emissions, advantaging wheel suppliers with verified lifecycle data.
Industry Challenges
- Autoclave technician scarcity:Curing composite rims requires precise temperature-pressure profiles that veteran operators calibrate by intuition; training pipelines have not kept pace with Southeast Asian manufacturing expansion.
- ISO 4210 and TÜV test harmonization gaps:Wheel manufacturers face redundant validation cycles when rim profiles fail German fatigue protocols after passing international frame-level standards, extending time-to-market by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Wheels Market |
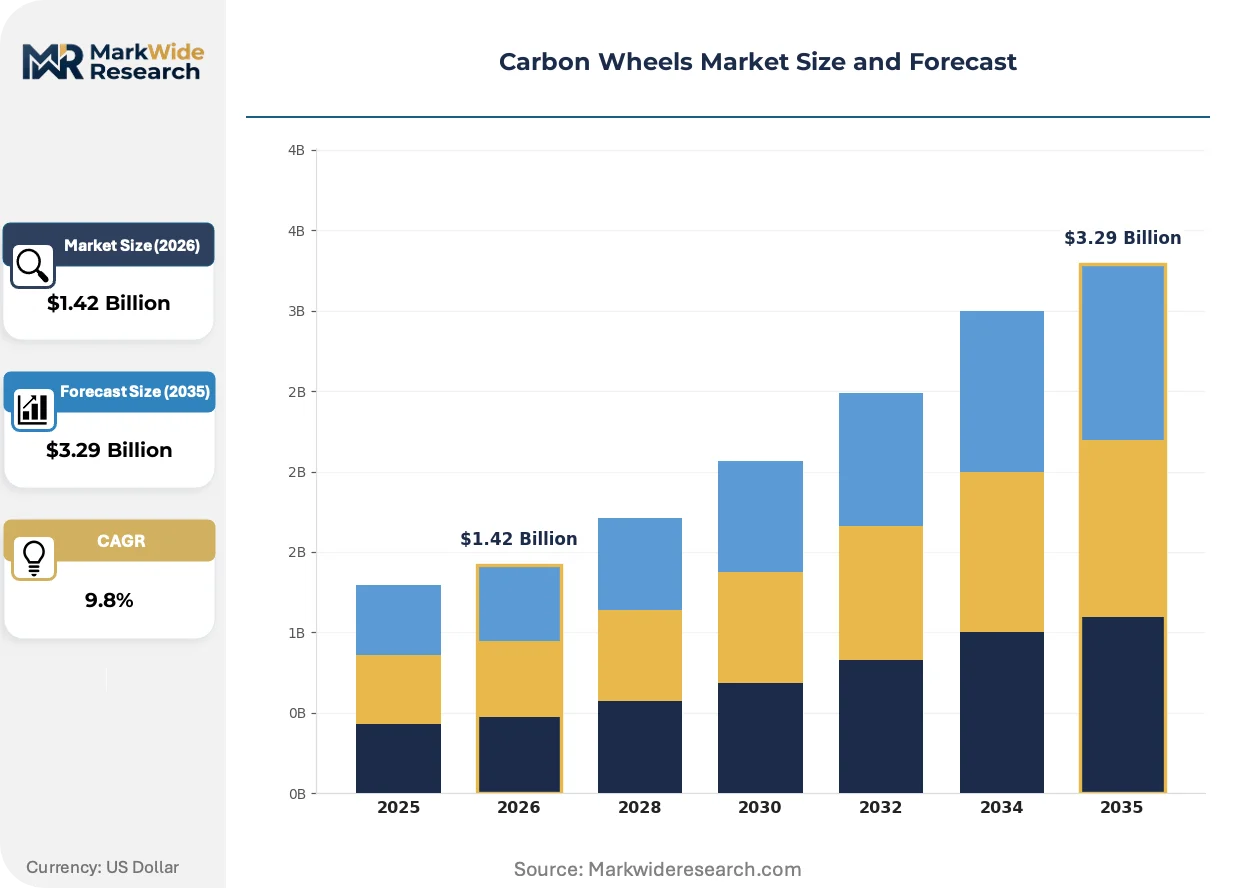
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.29 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clincher, Tubular, Tubeless, Track, Triathlon Technology: Full Carbon, Carbon Composite, Carbon Fiber Reinforced Polymer, Monocoque, Laminated Carbon Application: Road Racing, Time Trial, Cyclocross, BMX Racing, Gravel Biking End User: Professional Racers, Enthusiast Cyclists, Bicycle Manufacturers, Custom Builders |
| Companies Covered | Carbon Revolution, Dymag Group Ltd., thyssenkrupp Carbon Components, BST Wheels, Rotobox, ESE Carbon Company, HRE Performance Wheels, Ronal Group, Litespeed Racing LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Wheels Market Emerging Trajectories
Manufacturing process digitization and resin chemistry advances are compressing development cycles while regulatory pressure on material provenance is reshaping supplier hierarchies across the value chain.
Hookless bead-seat rim construction is decomposing the traditional distinction between tubeless and clincher formats. Elite road teams in the WorldTour peloton have near-universally adopted hookless profiles for training and racing. This convergence is decomplicating inventory planning for wheel brands while forcing tire manufacturers to narrow bead-diameter tolerances.
REACH restrictions on bisphenol-A and specific epoxy hardeners are accelerating resin system substitution across European-sold wheelsets. Manufacturers are qualifying bio-based alternatives from suppliers like Entropy Resins and Sicomin. German distributors now require Material Safety Data Sheets documenting SVHC content below 0.1% weight threshold for shelf placement.
Direct-to-consumer channel expansion is fragmenting the traditional bike-shop-centered distribution model. Enthusiast buyers in Australia and the United Kingdom increasingly configure wheelsets online, specifying hub color, spoke count, and decal finish before factory assembly. This bypass is compressing retail margin pools while forcing incumbent distributors to unbundle mechanical support from product margin.
Carbon Wheels Market Segmentation
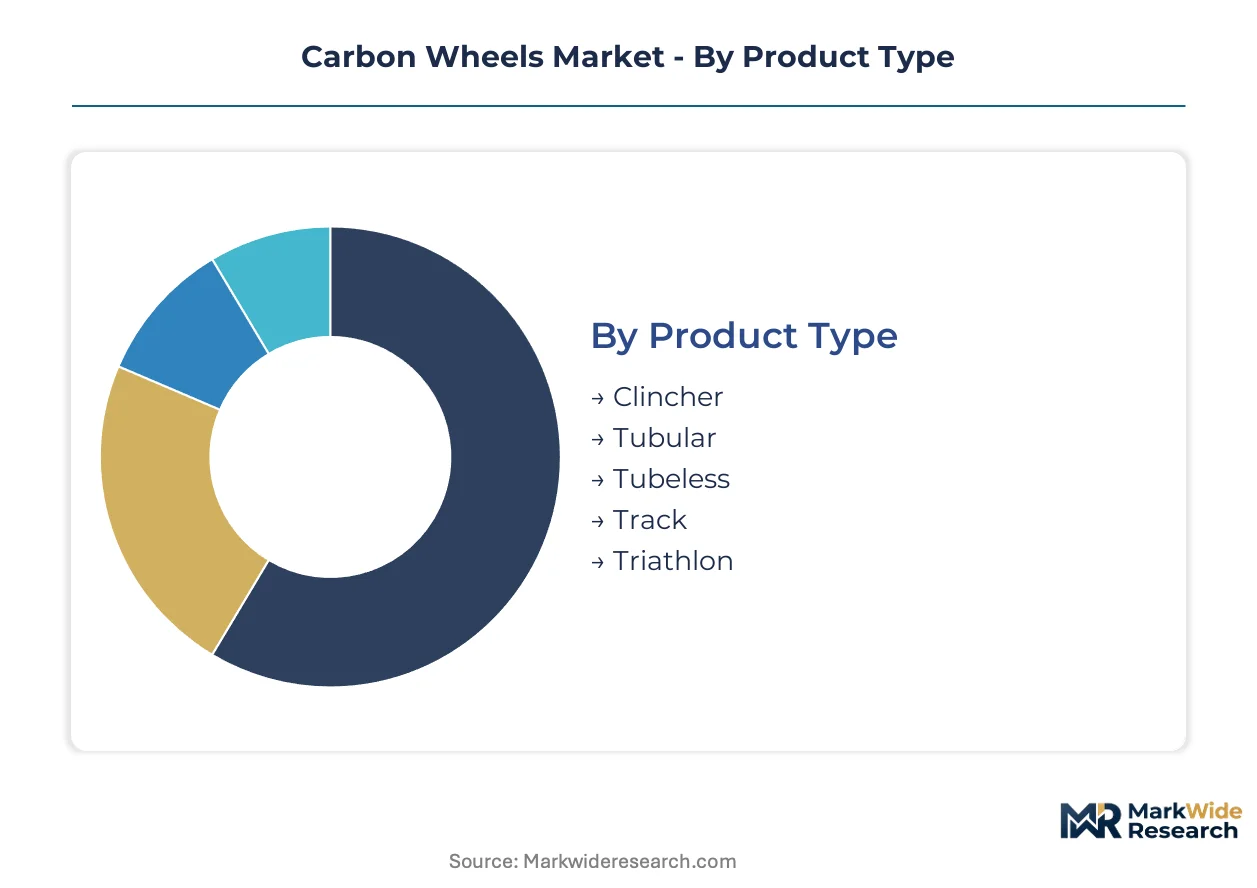
Carbon wheel segmentation reveals how margin pools concentrate around certification tiers and construction complexity. Manufacturers calibrate product line breadth against the cost of redundant validation cycles across ISO and TÜV protocols.
Product Type:
Margin concentration follows tubeless adoption curves and professional team procurement patterns.
- Tubeless:Hookless bead-seat profiles now dominate WorldTour peloton specifications. German and Belgian distributors require TÜV fatigue-cycle verification for shelf placement, compressing supplier pools to validated manufacturers. Sealant compatibility standardization is decomplicating inventory planning across retail channels.
- Clincher:Retains volume leadership among enthusiast cyclists due to existing tire inventory compatibility. Cost-sensitive recreational segments in Australia and the United Kingdom continue deferring carbon conversion, perceiving aluminum rims as damage-tolerant alternatives.
- Tubular:Sustains niche premium positioning in track and European gran fondo circuits where glue-bonded reliability outweighs service complexity.
- Track:UCI velodrome specifications drive sub-300-gram rim weight requirements with minimal aerodynamic drag tolerance.
- Triathlon:Age-group athletes in Germany, Switzerland, and Belgium upgrade as qualifying standards stiffen and race calendars expand.
The dominant share belongs to Clincher, while Tubeless is closing the gap fastest.
Technology:
Construction method determines fiber grade requirements and autoclave curing complexity.
- Full Carbon:Continuous carbon fiber reinforced polymer prepregs cured under heat and pressure achieve tensile strengths exceeding steel at one-quarter mass. Premium road racing applications in Germany and Belgium concentrate demand where TÜV certification unlocks retail channel access.
- Monocoque:Single-piece rim construction eliminates spoke hole drilling stress risers. Custom builders and professional teams in Switzerland specify monocoque for climbing stages where rim weight targets fall below 300 grams.
- Carbon Composite:Hybrid layups balance cost and performance for enthusiast cyclists in cost-sensitive segments.
- Carbon Fiber Reinforced Polymer:Standard prepreg construction dominates mid-tier road racing wheelsets.
- Laminated Carbon:Layer-specific fiber orientation enables aerodynamic profile optimization for time trial applications.
Full Carbon commands the premium tier by certification density, while Monocoque expands most quickly among custom builders.
Application:
Racing discipline dictates aerodynamic priority versus weight minimization trade-offs.
- Road Racing:Peloton dynamics require balanced drag reduction and crosswind stability. German professional teams drive specification convergence around hookless tubeless profiles validated to ISO 5775 bead-seat tolerances.
- Time Trial:Disc wheel and deep-section rim demand concentrates among triathlon and UCI hour record attempts where pure aerodynamic efficiency overrides handling considerations.
- Cyclocross:Mud clearance and impact tolerance requirements sustain aluminum rim preference in Belgian and Dutch cross circuits.
- BMX Racing:UCI track specifications and impact durability needs limit carbon penetration relative to other disciplines.
- Gravel Biking:Mixed-surface durability requirements and lower average speeds compress carbon wheel adoption rates versus road racing segments.
Road Racing maintains volume leadership, though Time Trial shows the steepest expansion trajectory as gran fondo participation rises.
End User:
Procurement authority is reorganizing as direct-to-consumer channels fragment traditional bike-shop distribution.
- Professional Racers:WorldTour and Pro Continental teams specify sub-300-gram rim weights with full TÜV and ISO 4210 validation. German squads leverage sponsorship disclosure requirements under CSRD mandates to pressure suppliers for embodied carbon documentation.
- Enthusiast Cyclists:Online configuration tools in Australia and the United Kingdom enable hub color, spoke count, and decal finish specification before factory assembly. This channel bypass compresses retail margin pools while unbundling mechanical support from product margin.
- Bicycle Manufacturers:OEM supply relationships with industrial carbon fiber pedigrees anchor European assembly operations.
- Custom Builders:Deep specialization in motorcycle-to-cycling technology transfer enables niche specification flexibility for individual athlete biomechanics.
Professional Racers anchor premium pricing power, while Enthusiast Cyclists are gaining share fastest through direct-to-consumer channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian carbon wheel exports supply German professional teams and Belgian gran fondo distributors, while Australian manufacturers ship directly to enthusiast cyclists in the United Kingdom and United States through direct-to-consumer channels.
Germany
Professional road racing squads in Baden-Württemberg and Bavaria specify TÜV-certified hookless tubeless wheelsets for WorldTour competition. KBA fatigue-cycle verification requirements filter uncertified products from premium retail channels in Stuttgart and Munich. The EU Green Deal's embodied carbon tracking pressures teams in Frankfurt-Rhine-Main to document fiber sourcing for sponsorship disclosure.
Belgium
Gran fondo age-group athletes in Flanders and Wallonia upgrade to full-carbon wheelsets as UCI race calendars expand through 2025. REACH restrictions on bisphenol-A epoxy hardeners force distributors in Brussels to require SVHC documentation below 0.1% weight threshold. The Eindhoven-Leuven carbon fiber cluster supplies rim prepregs to wheel assemblers in Liège.
United States
Enthusiast cyclists in California and Colorado configure custom wheelsets through online direct-to-consumer portals, specifying hub color and spoke count before factory assembly. FDA bicycle component safety oversight intersects with ISO 4210 frame testing standards for international market access. The Denver-Boulder corridor hosts custom builders serving triathlon athletes in Arizona and Texas.
United Kingdom
Direct-to-consumer channel expansion fragments traditional bike-shop distribution in London and the Southeast. Online configuration tools enable hub color and decal finish specification before Australian and Italian factories ship finished wheelsets. The Manchester-Liverpool industrial corridor hosts distributors importing TÜV-certified products for gran fondo participation growth.
Australia
Carbon Revolution's Geelong manufacturing base leverages captive fiber-to-finished-rim production for quality consistency control. TGA medical device standards do not apply to bicycle components, though ISO 5775 bead-seat tolerances govern export eligibility to European markets. Melbourne and Sydney enthusiast cyclists drive domestic demand through direct-to-consumer portals bypassing retail margin pools.
Carbon Wheels Market Vendor Landscape
Listed leaders compete with private specialists across certification tier access, with TÜV validation separating premium-channel suppliers from mass-market competitors. The vendor base concentrates around three strategic archetypes: vertically integrated fiber-to-rim manufacturers, motorcycle-technology transfer specialists, and industrial carbon fiber pedigree suppliers serving OEM relationships. Dominant competitive moves include backward integration into precursor fiber production and geographic expansion through local assembly partnerships in emerging racing markets.
Within the vertically integrated tier, Carbon Revolution exemplifies captive supply chain control from Australian fiber production through finished rim curing. Motorcycle-to-cycling technology transfer specialists include BST Wheels and Rotobox, occupying positions where deep specialization in rotational dynamics enables niche specification flexibility. Thyssenkrupp Carbon Components anchors industrial carbon fiber pedigree supply relationships with European bicycle manufacturers requiring ISO 4210 and TÜV dual validation.
| Leading Market Players |
|---|
| Carbon Revolution |
| Dymag Group Ltd. |
| thyssenkrupp Carbon Components |
| BST Wheels |
| Rotobox |
| ESE Carbon Company |
| HRE Performance Wheels |
| Ronal Group |
| Litespeed Racing LLC |
| Others |
Supply Flow & Price Mechanics
Hookless tubeless rim profiles substituting for legacy clincher formats are simultaneously relocating manufacturing gravity toward Southeast Asian autoclave hubs and compressing margin structures for European assemblers lacking TÜV certification. This substitution dynamic rewards validated manufacturers with premium channel access while forcing cost-pressured competitors toward direct-to-consumer bypass strategies.
Pricing Analysis
Prior-generation clincher wheelsets, current-generation hookless tubeless systems, and next-generation integrated sensor-enabled rims stratify across three performance tiers. TÜV fatigue-cycle verification and ISO 5775 bead-seat compliance function as the primary price differentiation drivers, separating certified premium products from uncertified alternatives. Pricing pressure stems from acrylonitrile precursor cost volatility feeding through Japanese PAN fiber suppliers, compressing margins for rim producers without backward integration into fiber production. Recreational cyclists in Australia and the United Kingdom exhibit highest price sensitivity, deferring carbon conversion for perceived damage-tolerant aluminum alternatives, while German professional teams demonstrate lowest sensitivity given sponsorship-funded procurement.
Supply Chain Analysis
Panama Canal transit constraints and Red Sea routing disruptions expose Southeast Asian autoclave facilities to logistics chokepoint vulnerability. Manufacturing concentrates in China, Taiwan, and Vietnam where curing infrastructure expansion has outpaced technician training pipelines. Raw material dependencies center on Toray and Mitsubishi Chemical aerospace-grade PAN precursor, Entropy Resins bio-based epoxy systems, and Entropy hardener alternatives compliant with REACH SVHC thresholds. Single-source vulnerability concentrates in Japanese fiber conglomerates controlling precursor supply. Distribution runs through German distributors requiring KBA documentation, Australian direct-to-consumer portals, and United Kingdom online configuration platforms bypassing traditional bike-shop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon wheels market constitutes a high-growth disruption propelled by EU Green Deal embodied carbon tracking mandates forcing fiber sourcing transparency across sponsorship disclosure requirements. This regulatory inflection compresses supplier pools toward validated manufacturers while opening white space for bio-based resin innovators.
For Market Incumbents: Fortify TÜV certification moats through redundant validation investment across ISO 5775 and KBA fatigue protocols, eliminating four-to-six month time-to-market penalties from harmonization gaps. Deepen captive fiber supply through Australian or Southeast Asian precursor partnerships, reducing exposure to Toray and Mitsubishi Chemical supply concentration. Channel control through German distributor exclusivity agreements defends against direct-to-consumer margin compression. For New Entrants and Emerging Players: Anchor in Indian domestic racing infrastructure where UCI-classified velodrome construction creates first-mover assembly partnership opportunities absent incumbent saturation. E-bike torque-load wheel engineering represents the most penetrable white space, as mid-drive motor systems stress conventional spoke tension limits. A go-to-market angle through gran fondo age-group athlete communities in Belgium and Switzerland leverages expanding race calendars and stiffening qualifying standards. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated fiber-to-rim manufacturers with Geelong-model captive production and established TÜV validation records, positioned for CSRD supply chain disclosure mandates. Long-term viability across the five-to-ten year window hinges on bio-based resin qualification pace and hookless bead-seat standard convergence. The signal to watch is REACH bisphenol-A restriction enforcement tightening across German and Belgian distributor SVHC documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| TÜV Certification Investment | Unlocks German and Belgian premium retail channels where uncertified products face delisting. |
| Backward Integration into PAN Precursor | Reduces exposure to Toray and Mitsubishi Chemical supply concentration and price volatility. |
| Direct-to-Consumer Portal Launch | Bypasses compressed retail margin pools in Australia and United Kingdom enthusiast segments. |
| Bio-Based Resin Qualification | Satisfies REACH SVHC thresholds and EU Green Deal embodied carbon tracking for European sales. |
| Local Assembly Partnership in India | Captures first-mover positioning in UCI-classified velodrome and criterium circuit expansion. |
Methodological Framework
A standing panel of wheelset product managers, TÜV certification engineers, professional team equipment directors, and carbon fiber procurement leads at Tier 1 suppliers provided ongoing calibration against secondary validation through customs records, UCI technical regulations, ECHA REACH substance databases, and SEC filings from Japanese fiber conglomerates. Bottom-up volume builds across tubeless, clincher, and tubular product categories triangulated with top-down market sizing from regional distributor shipment data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including rim construction technology, racing application discipline, certification tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating professional team procurement cycles, gran fondo participation trajectories, and e-bike motor system penetration rates as industry-specific forecast inputs.
Material uncertainties — acrylonitrile feedstock price swings, autoclave technician training pipeline gaps, and ISO-TÜV harmonization delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding sealant compatibility standardization and hookless bead-seat tolerance convergence. Practitioners should keep alternative scenarios live as REACH SVHC threshold enforcement and CSRD supply chain disclosure mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
Smart Tire Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Tire Cord Market