
 GCC Tire Market | 2026-2036
GCC Tire Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Tire Market Intelligence
Authorized distributor networks across the GCC is rewriting how tire manufacturers reach fleet buyers and individual consumers. Bridgestone Corporation leverages its long-standing partnerships with Saudi Arabian distributors to sustain dominant shelf presence in Riyadh and Jeddah. Michelin Group anchors premium positioning through specialized SUV and light truck tire lines tailored to desert climate conditions. Hankook Tire & Technology competes aggressively on original equipment supply contracts with Korean automakers assembling vehicles in the region.
GCC tires are pneumatic structures comprising natural rubber, synthetic rubber compounds, steel belts, and polyester casings engineered to withstand extreme thermal cycling and abrasive road surfaces across desert highways. Passenger car tires constitute the largest volume category, though heavy-duty tires command superior margin pools due to specialized load ratings and retread compatibility demanded by mining and construction fleets. Fleet operators represent the fastest-growing end user segment as Saudi Vision 2030 logistics investments and UAE port expansion multiply commercial vehicle utilization rates.
Gulf Standardization Organization (GSO) tire safety and labeling regulations, alongside Saudi Standards, Metrology and Quality Organization (SASO) energy efficiency mandates, are elevating minimum performance thresholds for products entering GCC customs territories. UAE Ministry of Industry and Advanced Technology import conformity schemes further filter substandard tire shipments through pre-shipment verification protocols. Stakeholders must monitor how evolving heat-resistance testing protocols and sustainability disclosure requirements reshape supplier qualification criteria and procurement specifications.
Market Dynamics
Fleet digitization across Saudi Arabia and the UAE is compressing replacement cycles and forcing distributors to integrate telematics-based predictive maintenance into tire service contracts.
Growth Catalysts
- SASO Energy Efficiency Mandates:Saudi Arabia's tightening fuel economy standards for commercial vehicles are accelerating demand for low-rolling-resistance tire compounds.
- Mining Fleet Expansion:Ma'aden and other extractive operators in the Eastern Province are scaling heavy-duty earthmover tire procurement as phosphate and bauxite output targets rise.
- Port Throughput Surge:Jebel Ali and King Abdullah Port container volumes are driving tractor-trailer utilization rates above regional averages, shortening replacement intervals.
Market Restraints
- Natural Rubber Price Volatility:Southeast Asian supply disruptions and currency fluctuations in Thai and Indonesian producer markets are compressing margin predictability for compounders.
- GSO Conformity Bottlenecks:Extended laboratory testing queues at Gulf Standardization Organization-accredited facilities are delaying product launches by 4-8 months for new entrants.
- Retread Technology Substitution:Advanced cold-process retreading systems are extending casing life cycles for long-haul fleets, dampening new tire volume in the premium truck radial segment.
Strategic Opportunities
- Qatar Construction Pipeline:FIFA legacy infrastructure and North Field expansion projects are creating concentrated demand for off-the-road tires in earthmoving and crane applications.
- EV-Compatible Tire Lines:Electric vehicle torque characteristics and battery weight distribution are opening white space for specialized tread compounds and reinforced sidewall constructions.
- Direct Fleet Telematics Integration:Tire pressure monitoring system data streams are enabling subscription-based fleet management services that bypass traditional distributor markups.
Industry Challenges
- Compound Formulation Talent Scarcity:GCC universities produce limited polymer chemistry and materials engineering graduates, forcing manufacturers to recruit from Indian and Southeast Asian labor pools.
- Heat-Resistance Certification Timelines:Extended desert durability testing protocols under GSO 575/2007 amendments are stretching product qualification periods beyond commercial planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Tire Market |
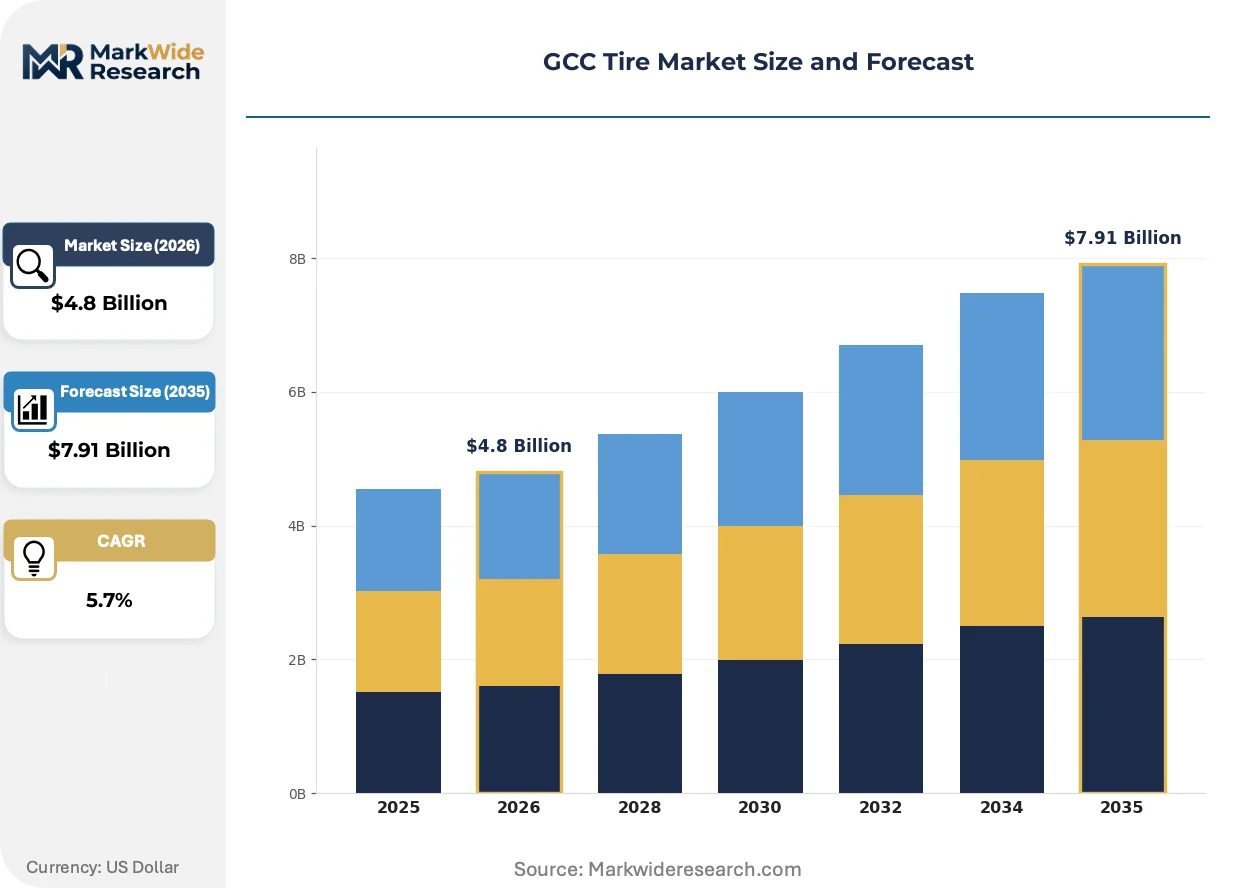
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Car Tires, Light Truck Tires, Heavy-Duty Tires, Motorcycle Tires Distribution Channel: Online Retail, Offline Retail, Wholesalers, Distributors Material: Natural Rubber, Synthetic Rubber, Steel, Polyester End User: Individual Consumers, Fleet Operators, Commercial Vehicles, Bus Operators |
| Companies Covered | Michelin Group, Toyo Tire Corp., Hankook Tire & Technology, Pirelli & C. S.p.A., Kumho Tire, Bridgestone Corporation, Continental AG, Yokohama Rubber Co., Ltd., Goodyear Tire & Rubber Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Tire Market Strategic Shifts & Innovations
Digital tire monitoring and sustainable material substitution are converging to redefine value propositions across passenger, commercial, and industrial segments.
Silica-silane reinforcement systems are hybridizing conventional carbon-black compounds to reduce rolling resistance without sacrificing wet-grip performance. Saudi fleet operators are piloting these formulations in Riyadh-Jeddah corridor long-haul routes. The technology is hybridizing procurement criteria, forcing compounders to demonstrate simultaneous fuel savings and safety retention to win OE contracts.
GSO tire labeling regulations are mandating standardized wet-grip, noise, and rolling-resistance disclosures across all GCC customs territories. Importers must now pre-register test results with notified bodies before shipment clearance. Premium SUV tire lines face the steepest compliance costs, prompting manufacturers to consolidate SKUs around certified universal compounds.
Long-haul fleet managers are unbundling tire procurement from maintenance services, negotiating direct supply agreements with manufacturers while outsourcing mounting and alignment to independent service networks. This bifurcation is eroding distributor margins in the UAE's Northern Emirates, where price transparency from regional B2B platforms has compressed negotiation leverage for traditional intermediaries.
GCC Tire Market Segmentation
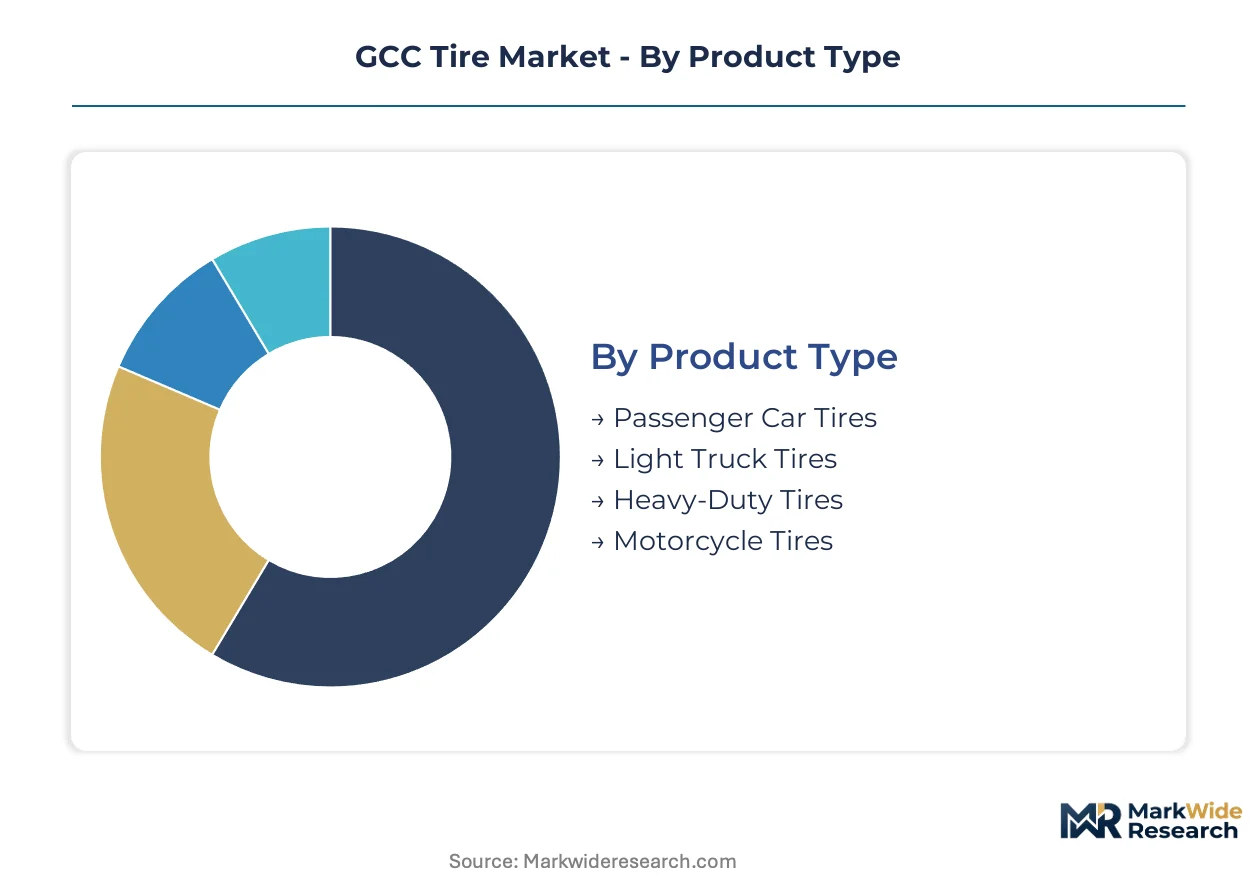
GCC tire procurement patterns diverge sharply across vehicle classes and buyer types, with replacement cycles spanning 18 months for long-haul trucks to 4-5 years for private passenger vehicles. Understanding these velocity differentials shapes inventory positioning and service bundling strategies for distributors serving Saudi Arabia and UAE markets.
Product Type:
Replacement velocity separates the four product categories, with commercial segments turning over 2-3x faster than consumer lines due to abrasive desert highways and extreme thermal loading.
- Passenger Car Tires:Radial constructions with silica-enhanced tread compounds dominate this volume-leading category. Demand clusters in Jeddah and Riyadh residential corridors where private vehicle ownership rates exceed regional averages. GSO wet-grip labeling mandates are compressing SKU proliferation as manufacturers consolidate around certified universal compounds.
- Heavy-Duty Tires:Steel-belted radial designs with reinforced sidewalls withstand 150+ tonne mining equipment loads. Ma'aden phosphate operations in Saudi Arabia's Eastern Province and UAE quarry fleets drive concentrated procurement with 12-18 month replacement cycles. Retread compatibility requirements add specification complexity for OE suppliers.
- Light Truck Tires:Hybrid car-truck constructions serve contractor and small fleet segments across Dubai's construction zones and Saudi logistics corridors.
- Motorcycle Tires:Bias-ply and radial options address limited but growing two-wheeler populations in UAE urban centers and Saudi delivery fleets.
Passenger car tires anchor the volume base while heavy-duty tires gain share at the steepest rate driven by mining fleet expansion.
Distribution Channel:
Channel economics stratify by buyer sophistication, with fleet procurement bypassing traditional retail while individual consumers remain tethered to physical inspection.
- Distributors:Authorized networks maintain dominant shelf presence across Saudi Arabia through long-standing partnerships with manufacturers. Riyadh and Jeddah distribution hubs control inventory flow to secondary cities. Fleet digitization is compressing their margin capture as telematics-enabled direct procurement expands.
- Wholesalers:Volume aggregators serve independent garages and smaller fleet operators across UAE's Northern Emirates and Saudi secondary markets. Price transparency from regional B2B platforms has eroded negotiation leverage. Cold-chain and construction equipment tire specialization differentiates surviving intermediaries.
- Offline Retail:Tire shops and automotive service centers persist for consumers requiring immediate mounting and alignment.
- Online Retail:Digital platforms gain traction among price-sensitive individual buyers in tech-forward UAE urban centers.
Distributors retain the largest revenue share while direct manufacturer-to-fleet contracting expands most quickly.
Material:
Compound formulation choices determine heat resistance certification timelines and rolling resistance performance under GSO testing protocols.
- Synthetic Rubber:Styrene-butadiene and polybutadiene blends enable consistent performance across temperature extremes. Saudi SASO energy efficiency mandates accelerate demand for low-rolling-resistance formulations. Compounders face margin pressure from Southeast Asian natural rubber price volatility.
- Natural Rubber:Hevea brasiliensis latex provides tear resistance and wet-grip properties critical for safety ratings. Thai and Indonesian supply disruptions create procurement unpredictability. Premium SUV and light truck lines maintain higher natural rubber content for desert durability.
- Steel:Belt and bead wire reinforcement enables load-bearing capacity for commercial vehicle applications.
- Polyester:Tire cord fabrics reduce weight in passenger car constructions while maintaining dimensional stability.
Synthetic rubber compounds dominate volume while natural rubber blends command premium positioning in certified performance tiers.
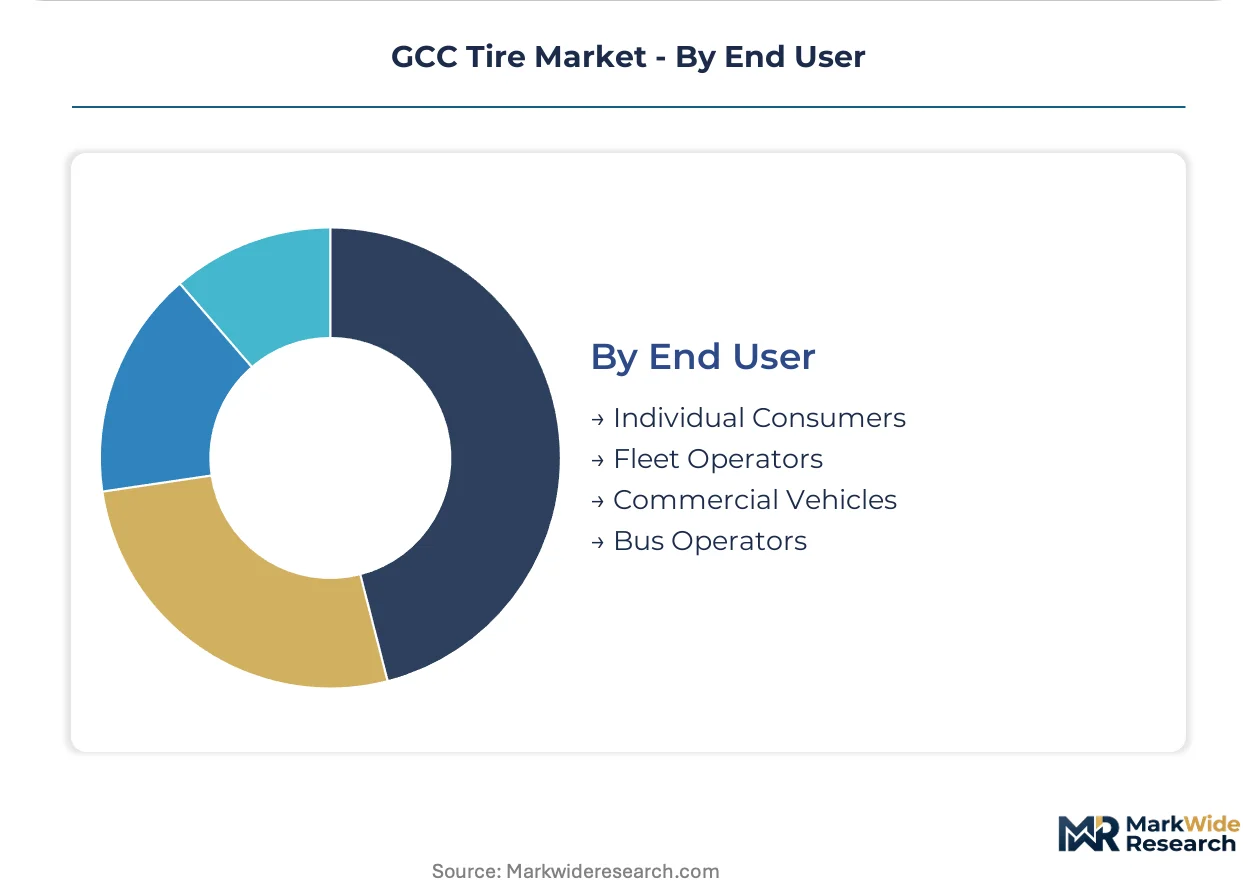
End User:
Buyer type determines specification complexity, with fleet operators driving standardization while individual consumers prioritize brand recognition and immediate availability.
- Fleet Operators:Long-haul and logistics fleets across Saudi Vision 2030 infrastructure projects negotiate direct supply agreements with manufacturers. Predictive maintenance integration via tire pressure monitoring systems is unbundling procurement from service contracts. Jebel Ali and King Abdullah Port container throughput drives above-average tractor-trailer utilization.
- Commercial Vehicles:Construction and earthmoving contractors in Qatar's North Field expansion and FIFA legacy projects require off-the-road specialty tires. Equipment leasing companies centralize procurement decisions across multi-site operations.
- Individual Consumers:Private vehicle owners in UAE expatriate communities and Saudi middle-class households respond to brand equity and GSO label ratings.
- Bus Operators:Municipal and intercity coach fleets represent a concentrated but price-sensitive procurement segment.
Fleet operators anchor commercial value pools while commercial vehicle demand climbs fastest on construction and mining expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands pricing leverage over UAE distributors due to concentrated fleet procurement volumes along the Riyadh-Jeddah corridor. The Eastern Province's mining density and King Abdullah Port throughput anchor premium tire absorption rates unmatched elsewhere in the Gulf.
Saudi Arabia
Ma'aden phosphate expansion in the Eastern Province and Saudi Vision 2030 logistics corridors drive heavy-duty tire procurement at double-digit velocity. SASO energy efficiency mandates for commercial vehicles compress replacement cycles toward low-rolling-resistance compounds. Jeddah's port infrastructure and Riyadh's distribution hub status concentrate inventory positioning for both OE and aftermarket channels.
United Arab Emirates
Jebel Ali container throughput growth and Dubai's last-mile delivery fleet densification accelerate commercial vehicle tire wear rates. MOHAP import conformity schemes filter substandard shipments through pre-shipment verification protocols. Northern Emirates wholesale networks face margin compression as telematics-enabled direct procurement expands from Dubai-based fleet operators.
Qatar
North Field gas expansion and FIFA legacy infrastructure sustain concentrated demand for off-the-road earthmover tires. The country's central procurement authority consolidates construction equipment tire purchasing across state-linked contractors. Doha-based leasing companies centralize multi-site fleet decisions for crane and heavy transport applications.
Kuwait
Mina Al-Ahmadi refinery expansion and logistics corridor investments toward the Saudi border stimulate commercial vehicle fleet growth. The national oil company's contractor procurement standards elevate minimum tire performance specifications for heavy transport. Shuwaikh Industrial Area clusters automotive service networks serving cross-border trucking routes.
Oman
Duqm Special Economic Zone port development and mining concessions in the Al Batinah region generate nascent heavy-duty tire demand. The Public Authority for Mining's equipment standards are aligning with GSO conformity protocols for earthmover applications. Sohar's industrial port complex anchors supply chain positioning for northern Oman construction and extractive operations.
GCC Tire Market Key Industry Players
Full-line multinationals and regional specialists split the market along premium-mass tier boundaries. Three to four global manufacturers capture dominant share in OE supply and fleet direct contracts, while price-focused competitors serve independent garages and secondary city wholesalers. Japanese and Korean conglomerates anchor the technology-intensive segment through desert-specific compound development. European majors defend position via SUV and light truck specialization. Strategic moves concentrate on distributor exclusivity renewals and telematics service bundling rather than capacity expansion.
Within the full-line multinational tier, Bridgestone Corporation, Michelin Group, and Hankook Tire & Technology exemplify divergent geographic anchoring strategies. Bridgestone's long-standing Saudi distributor partnerships sustain shelf dominance in Riyadh and Jeddah retail networks. Michelin occupies premium positioning through specialized SUV and light truck lines engineered for thermal cycling resistance. Hankook competes aggressively on original equipment contracts with Korean automakers assembling vehicles in the region.
| Leading Market Players |
|---|
| Michelin Group |
| Toyo Tire Corp. |
| Hankook Tire & Technology |
| Pirelli & C. S.p.A. |
| Kumho Tire |
| Bridgestone Corporation |
| Continental AG |
| Yokohama Rubber Co., Ltd. |
| Goodyear Tire & Rubber Company |
| Others |
Cost & Logistics Intelligence
Thai and Indonesian natural rubber plantation concentration funnels margin capture toward compounders with long-term offtake contracts, while downstream distributors in Riyadh and Jeddah extract service premiums from fleet buyers seeking predictive maintenance bundling. This upstream-downstream asymmetry shapes how tire manufacturers allocate working capital between feedstock hedging and distributor exclusivity renewals.
Pricing Analysis
Configured-to-order pricing for mining fleet contracts commands 15-25% premiums over standard wholesale catalogues, reflecting retread compatibility specifications and load rating customization. Three-tier pricing structure across premium, standard, and economy levels stratifies by GSO wet-grip certification grade and heat-resistance testing tier. Price erosion runs through the wholesale channel as regional B2B platforms compress negotiation leverage for Northern Emirates intermediaries. Individual consumers in UAE expatriate communities exhibit highest price sensitivity, while Ma'aden and Jebel Ali port fleet operators prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Upstream feedstock flows from Thailand, Indonesia, and Malaysia anchor natural rubber procurement, while South Korean and Japanese synthetic rubber producers supply styrene-butadiene blends for low-rolling-resistance formulations. Steel belt wire draws from Chinese and Indian metallurgical suppliers, with polyester tire cord fabrics sourced from Taiwan and South Korea. Single-source vulnerability in Southeast Asian latex supply creates margin unpredictability during monsoon disruption cycles. Distribution runs through Saudi authorized distributor networks and UAE wholesale aggregators serving secondary city garages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound formulation talent scarcity across GCC universities forces manufacturers to recruit polymer chemists from Indian and Southeast Asian labor pools, constraining R&D velocity and product qualification timelines. This capability gap rewards early movers who secure technical talent pipelines before competitor bidding intensifies.
For Market Incumbents: Harden distributor exclusivity renewals in Riyadh and Jeddah corridors against telematics-enabled direct procurement threats from Dubai-based fleet operators. Secure backward integration into natural rubber offtake contracts with Thai plantation groups to buffer margin compression from currency volatility. Invest in GSO heat-resistance certification pre-positioning before amended testing protocols extend qualification timelines.
For New Entrants and Emerging Players: Qatar's North Field expansion and FIFA legacy infrastructure projects represent the most penetrable entry point for off-the-road tire specialization without incumbent shelf dominance. EV-compatible tire lines for Saudi Vision 2030 electric logistics fleets offer white space given limited incumbent product launches. Pursue direct fleet telematics integration partnerships to bypass traditional distributor markups in UAE commercial vehicle segments.
For Investors and Strategic Acquirers: Capital is best deployed toward compounders with captive synthetic rubber blending capacity and established GSO certification track records. Long-term viability across the analysis window hinges on heat-resistance testing protocol adaptation and sustainable material substitution pipelines. Watch for SASO energy efficiency mandate tightening as the inflection signal for low-rolling-resistance compound demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Rubber Offtake | Thai plantation long-term contracts buffer currency volatility and supply disruption risks for compounders. |
| GSO Heat-Resistance Certification Pre-Positioning | Early laboratory queue access compresses product launch timelines before amended protocols take effect. |
| Direct Fleet Telematics Integration | TPMS data streams enable subscription-based services that bypass traditional distributor margin capture. |
| EV-Compatible Tire Line Development | Saudi Vision 2030 electric logistics investments create white space for torque-optimized tread compounds. |
| Distributor Exclusivity Renewal Concentration | Riyadh and Jeddah shelf presence sustains volume leadership against wholesale channel price transparency. |
Research Approach
Operator-level perspectives from fleet procurement managers, distributor network heads, GSO laboratory directors, and compound formulation engineers anchored the qualitative base for this analysis. Primary interview findings were cross-validated against Saudi Standards, Metrology and Quality Organization regulatory filings, Gulf Standardization Organization testing protocol amendments, customs import data, and automotive OEM production disclosures. Bottom-up demand modeling from vehicle parc and replacement cycle analysis was triangulated with top-down market sizing from trade flow and distributor revenue aggregation.
Scenario-bracketing around natural rubber price volatility bands and SASO mandate implementation timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, material composition, and end-user category, with vehicle utilization intensity and port throughput velocity as industry-specific forecast inputs. CAGRs were derived from replacement cycle compression rates and fleet expansion trajectories rather than extrapolated historical growth.
Practitioners should monitor Thai Baht and Indonesian Rupiah exchange rate movements, GSO laboratory accreditation queue lengths, and Saudi Vision 2030 logistics infrastructure award announcements for early signals of forecast revision triggers. Cross-checking against vehicle registration databases and port container throughput statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Low Rolling Resistance Tire Market