
 North Commercial Vehicle Tire Pressure Monitoring Systems Market | 2026-2036
North Commercial Vehicle Tire Pressure Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North Commercial Vehicle Tire Pressure Monitoring Systems Market Analytics
Silicon-based pressure sensors are recalibrating cost structures across the North Commercial Vehicle Tire Pressure Monitoring Systems landscape, displacing older ceramic transducer designs in high-volume fleet applications. Continental AG leverages in-house semiconductor fabrication to control sensor supply chains for Class 8 truck platforms. Sensata Technologies Inc. anchors its position through temperature-compensated MEMS designs purpose-built for severe-duty vocational cycles. Bendix Commercial Vehicle Systems LLC differentiates via brake-system integration, bundling TPMS data with air brake diagnostics for consolidated fleet dashboards.
North Commercial Vehicle Tire Pressure Monitoring Systems encompass sensor arrays, receiver modules, and dashboard interfaces that measure tire inflation pressure and temperature in real time, typically operating at radio frequencies near 433 MHz with pressure accuracy within 1 psi to prevent thermal runaway and irregular wear. Direct TPMS dominates OEM channels where valve-stem-integrated transmitters deliver continuous data streams, while Smart Tire Systems represent the fastest-expanding category as embedded tread sensors enable predictive replacement scheduling. Aftermarket installations lag in penetration but carry higher per-unit margins due to retrofit labor and fleet customization requirements.
The US National Highway Traffic Safety Administration enforces FMVSS 138 compliance thresholds that mandate TPMS warning activation at 25 percent underinflation, while Transport Canada's CMVSS 138 mirrors these provisions for cross-border equipment standardization. The US EPA SmartWay program rewards fleet participation with fuel efficiency benchmarking that indirectly elevates tire maintenance protocols including pressure monitoring adoption. Stakeholders must weigh cellular-connected TPMS architectures against radio frequency legacy systems as fleet telematics platforms consolidate sensor feeds into unified operations centers.
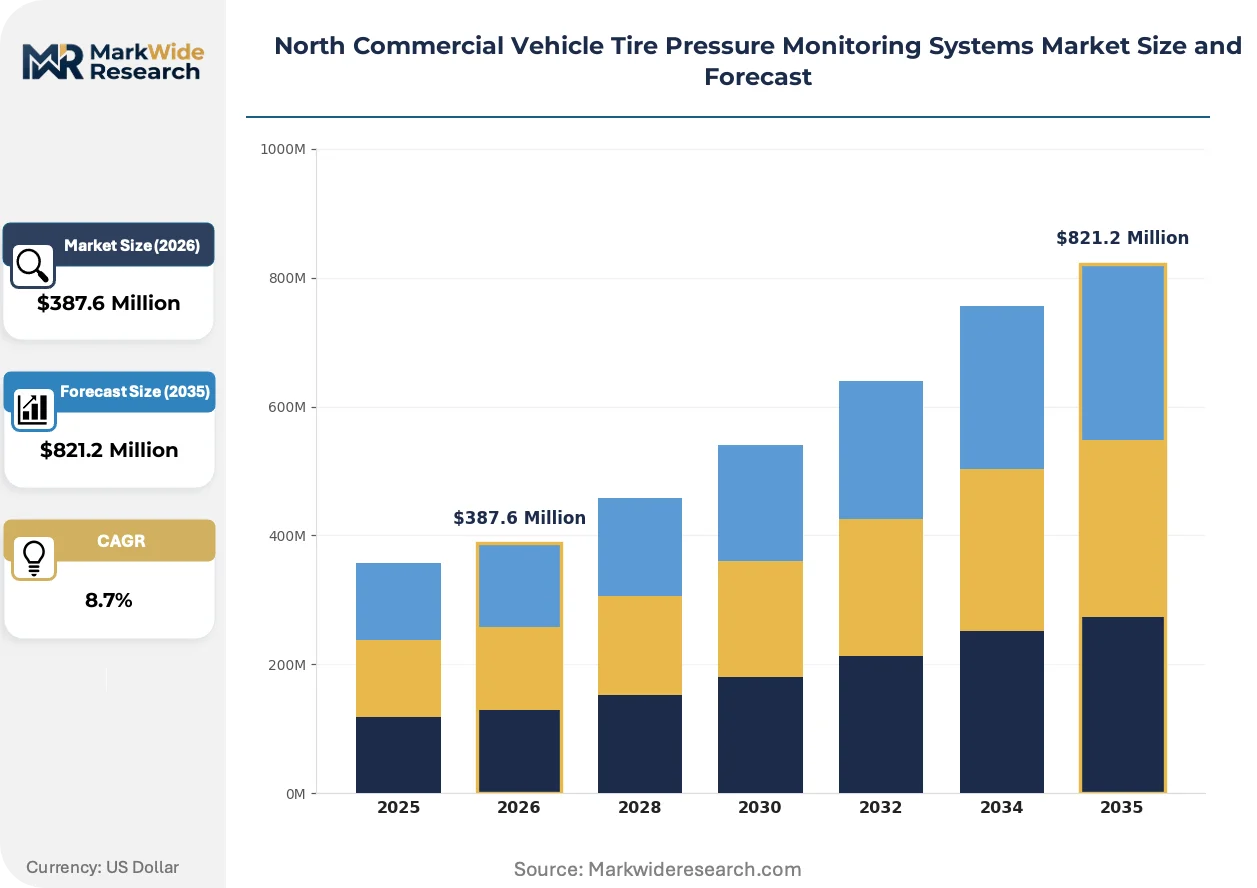
Market Dynamics
Fleet telematics consolidation is compressing TPMS architectures into unified data platforms, forcing sensor suppliers to embed cellular connectivity and API compatibility as baseline specifications rather than premium add-ons.
Growth Catalysts
- FMVSS 138 thresholds:NHTSA mandates activate warning systems at 25 percent underinflation, compelling logistics providers to retrofit legacy tractor-trailers with compliant direct TPMS hardware before enforcement deadlines.
- SmartWay benchmarking:EPA fuel efficiency protocols reward documented tire maintenance programs, elevating pressure monitoring from optional fleet practice to scored operational metric.
- Silicon MEMS migration:Semiconductor-based pressure sensing cuts unit costs below ceramic transducer equivalents, accelerating OEM fitment across Class 6-8 vocational chassis produced in Michigan-Ohio manufacturing corridors.
Market Restraints
- RF spectrum congestion:Legacy 433 MHz TPMS signals face interference from expanding fleet Wi-Fi and cellular telemetry bands, degrading transmission reliability in dense shipping terminals.
- Semiconductor foundry concentration:MEMS die fabrication concentrates in Taiwan and South Korea foundries, exposing sensor supply chains to geopolitical disruption and allocation constraints.
- Retrofit labor economics:Aftermarket direct TPMS installation requires wheel demounting and receiver programming, pushing installed costs above fleet maintenance budgets for aging trailer assets.
Strategic Opportunities
- Canadian cross-border standardization:Transport Canada's CMVSS 138 alignment with US FMVSS 138 creates unified equipment specifications for continental fleet operators seeking single-source procurement.
- Predictive tread analytics:Smart Tire Systems embedding accelerometer arrays enable remaining tread life forecasting, opening subscription-based replacement scheduling services for high-mileage linehaul operators.
- Brake-TPMS convergence:Air brake diagnostic platforms from Bendix Commercial Vehicle Systems demonstrate bundled data aggregation, creating white space for consolidated dashboard providers.
Industry Challenges
- RF-cellular architecture selection:Fleet managers face stranded asset risk when choosing between proven radio frequency TPMS and emerging LTE-M connected sensors with incompatible backend systems.
- Technician certification gaps:Commercial vehicle service bays lack standardized training for MEMS sensor calibration and telematics gateway pairing, extending installation times and error rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Commercial Vehicle Tire Pressure Monitoring Systems Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct TPMS, Indirect TPMS, Hybrid TPMS, Smart Tire Systems Installation Type: OEM, Aftermarket, Integrated Solutions, Bolt-On Systems End User: Fleet Operators, Logistics Providers, Public Transport, Construction Companies Technology: Radio Frequency, Bluetooth, Wi-Fi, Cellular |
| Companies Covered | Continental AG, Denso Corporation, Pacific Industrial Co. Ltd., Schrader Electronics, Sensata Technologies Inc., ZF Friedrichshafen AG, Bendix Commercial Vehicle Systems LLC, Delphi Automotive, Alligator Ventifabrik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Commercial Vehicle Tire Pressure Monitoring Systems Market Evolving Landscape
Sensor fusion architectures are dissolving traditional boundaries between tire monitoring, brake diagnostics, and fleet tracking, compressing multiple hardware categories into single telematics subscriptions.
Cellular-connected TPMS is expanding into long-haul fleet deployments as LTE-M and NB-IoT modems achieve cost parity with radio frequency receiver systems. Major for-hire carriers operating transcontinental routes now specify embedded connectivity as standard RFP language. This shift is expanding into predictive maintenance platforms that correlate pressure anomalies with GPS location and cargo weight data.
CMVSS 138 enforcement by Transport Canada tightens cross-border equipment compliance, eliminating grandfathering provisions for pre-2007 trailers operating in Ontario-Quebec freight corridors. Canadian provincial inspectors now reference US NHTSA technical service bulletins during roadside inspections. The regulation is compressing aftermarket upgrade timelines for US-based fleets with Canadian route authority.
Outcome-based tire service contracts are displacing transactional replacement purchasing among refrigerated carriers operating temperature-sensitive pharmaceutical lanes. Fleets now pay per monitored mile rather than per tire, transferring inflation maintenance liability to national tire service networks. The model concentrates in Midwest distribution hubs serving Chicago-Detroit-Cleveland manufacturing triangles.
North Commercial Vehicle Tire Pressure Monitoring Systems Market Segmentation
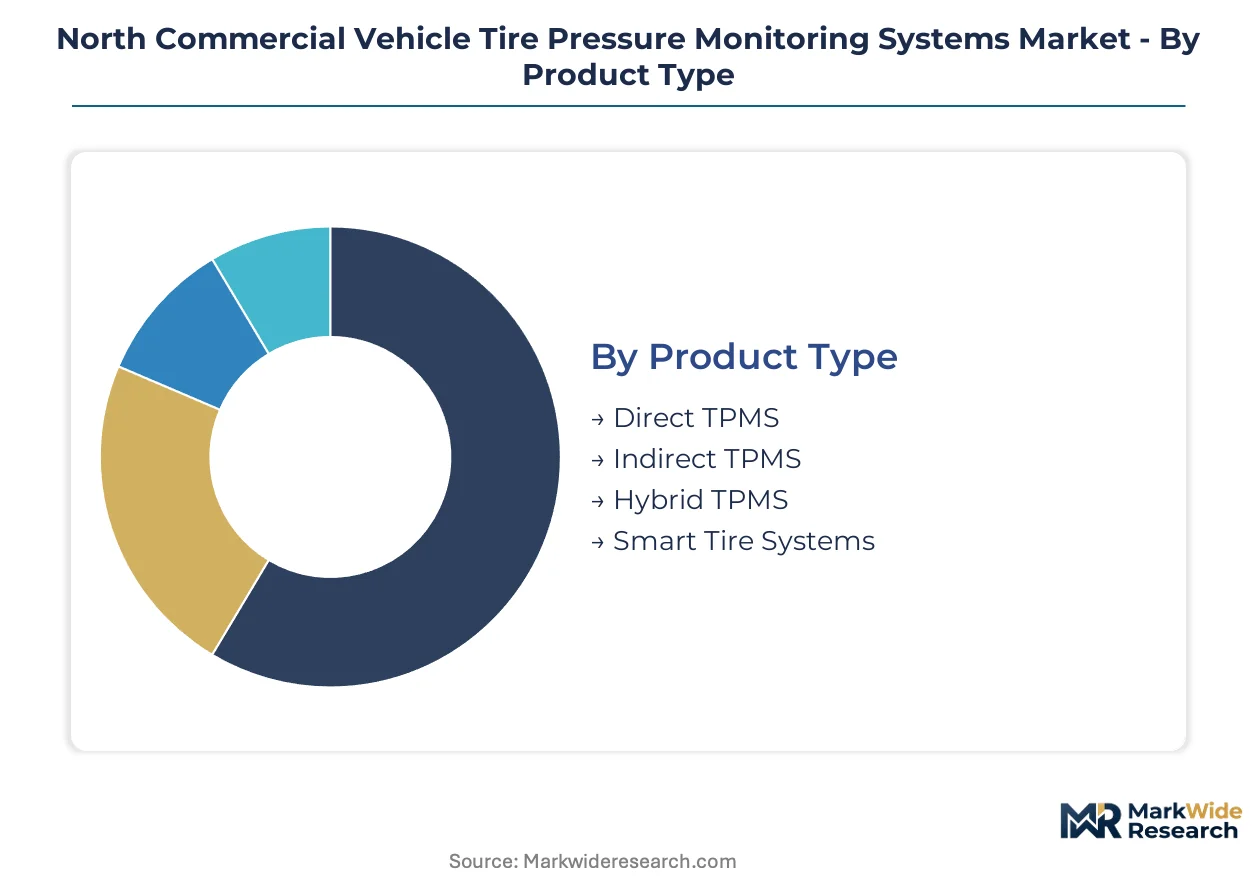
Segmentation in North American commercial vehicle TPMS reveals how fleet procurement decisions split across regulatory compliance paths, technology migration timelines, and total cost of ownership calculations. Understanding these divides exposes where sensor suppliers can capture premium pricing versus where hardware commoditization pressures concentrate.
Product Type:
Fleet managers weigh upfront hardware costs against data granularity when selecting TPMS architectures for Class 6-8 vehicles.
- Direct TPMS:Valve-stem-integrated pressure sensors transmit continuous inflation data via 433 MHz radio frequency with 1 psi accuracy. Demand clusters in OEM channels serving Michigan-Ohio heavy-duty truck manufacturing corridors where FMVSS 138 compliance is non-negotiable.
- Smart Tire Systems:Embedded tread sensors combine accelerometer arrays with machine learning to forecast remaining tire life. Refrigerated carriers operating pharmaceutical lanes in the US Midwest are adopting subscription-based replacement scheduling built on this predictive capability.
- Indirect TPMS:ABS wheel-speed differential algorithms estimate pressure loss without dedicated hardware. Cost-conscious regional LTL fleets in Texas and Florida deploy these for trailer assets with limited capital budgets.
- Hybrid TPMS:Dual-mode architectures blend direct wheel sensors with indirect algorithms for redundancy. Vocational concrete mixer operators in Pennsylvania specify these for severe-duty cycles with high thermal load variability.
Volume sits with Direct TPMS; growth tilts toward Smart Tire Systems.
Installation Type:
Procurement channel selection determines margin structure and customer relationship durability for TPMS vendors.
- OEM:Factory-integrated sensor arrays ship with Class 8 tractors from Detroit Three manufacturers. Kenworth and Peterbilt production lines in Ohio specify Continental AG silicon MEMS designs as standard fitment.
- Aftermarket:Retrofit installations demand wheel demounting, sensor programming, and telematics gateway pairing. Independent service bays in Illinois and Indiana capture labor premiums from aging trailer fleets upgrading for cross-border Canadian compliance.
- Integrated Solutions:Bundled brake-TPMS-telematics platforms consolidate multiple sensor feeds into unified fleet dashboards. Bendix Commercial Vehicle Systems anchors this category through air brake diagnostic convergence.
- Bolt-On Systems:External valve-cap transmitters clip onto existing valve stems without wheel removal. Owner-operators in the US Southeast favor these for rapid deployment on leased equipment.
Revenue concentrates in OEM; margin expansion favors Integrated Solutions.
End User:
Operational intensity and regulatory exposure shape TPMS sophistication requirements across buyer categories.
- Fleet Operators:National for-hire carriers with 500-plus power units mandate cellular-connected TPMS as standard RFP language. Schneider National and J.B. Hunt specifications drive LTE-M modem adoption for transcontinental route visibility.
- Logistics Providers:Third-party freight brokers prioritize asset-agnostic monitoring platforms compatible with shipper telematics requirements. Chicago-based 3PLs serving automotive just-in-time lanes demand API-first architectures.
- Public Transport:Municipal bus authorities in Toronto and Montreal face CMVSS 138 enforcement without grandfathering provisions. Canadian provincial inspectors reference NHTSA technical bulletins during roadside compliance checks.
- Construction Companies:Vocational fleets operating articulated dump trucks in Alberta oil sands specify temperature-compensated MEMS designs from Sensata Technologies for severe-duty thermal cycling.
Procurement scale peaks with Fleet Operators; compliance urgency steepest among Public Transport.
Technology:
Connectivity architecture selection carries stranded asset risk as fleet telematics platforms consolidate sensor feeds.
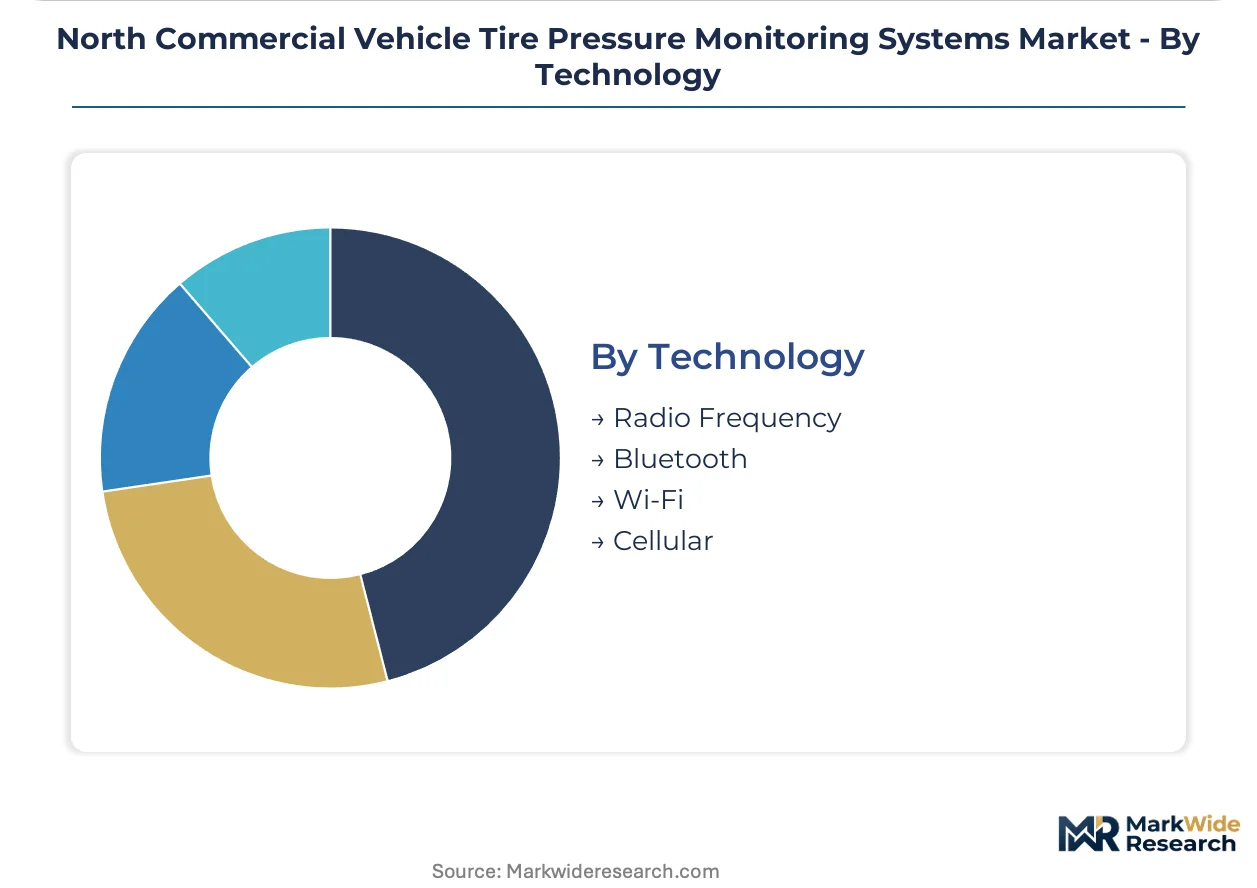
- Radio Frequency:Legacy 433 MHz systems dominate installed base but face spectrum congestion from expanding fleet Wi-Fi and cellular telemetry. Dense Chicago intermodal terminals report signal degradation requiring receiver repositioning.
- Cellular:LTE-M and NB-IoT modems achieve cost parity with RF receivers while enabling cloud-native predictive maintenance. Major carriers now specify embedded connectivity as baseline for new tractor acquisitions.
- Bluetooth:Short-range protocols suit yard management and last-mile delivery applications with limited roaming requirements. Regional foodservice distributors in Ohio deploy these for depot-based trailer pools.
- Wi-Fi:High-bandwidth transmission supports firmware over-the-air updates and bulk data offload. Smart Tire Systems manufacturers leverage this for tread sensor machine learning model refreshes.
Installed base remains with Radio Frequency; capability expansion favors Cellular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet density along the US-Canada border drives regional demand concentration, with cross-border compliance requirements synchronizing equipment specifications across both markets. Manufacturing corridors in the US Midwest and Canadian Ontario-Quebec corridor anchor OEM fitment volumes. Regulatory alignment between NHTSA and Transport Canada eliminates equipment fragmentation for continental operators.
United States
Long-haul trucking fleets operating transcontinental routes mandate cellular-connected TPMS as baseline procurement specifications. NHTSA enforces FMVSS 138 thresholds requiring warning activation at 25 percent underinflation, compelling retrofit campaigns for pre-mandate trailer assets. The Michigan-Ohio manufacturing corridor concentrates heavy-duty truck production, anchoring direct TPMS sensor demand from Detroit Three OEMs.
Canada
Cross-border freight operators face CMVSS 138 enforcement without grandfathering provisions for older trailers entering Ontario-Quebec corridors. Transport Canada's regulatory alignment with US standards enables single-source equipment procurement for continental fleet operators. Provincial inspectors in Toronto and Montreal reference NHTSA technical service bulletins during roadside compliance verification.
Mexico
Maquiladora operations serving US automotive supply chains adopt TPMS specifications matching northbound customer requirements. Mexican carriers operating cross-border lanes upgrade equipment to satisfy US DOT inspection protocols at Laredo and Otay Mesa crossings. Manufacturing clusters in Nuevo León and Baja California anchor aftermarket retrofit demand for regional logistics providers.
North Commercial Vehicle Tire Pressure Monitoring Systems Market Competitive Landscape
Strategic partnerships dominate the current landscape as sensor suppliers align with telematics platforms and brake system integrators. The vendor base separates into three distinct tiers: diversified automotive conglomerates with captive semiconductor fabrication, specialized MEMS sensor houses, and brake-system integrators bundling TPMS into broader vehicle control offerings. Two competitive vectors define positioning: backward integration into MEMS die production to control supply chains, and forward integration into fleet data platforms to capture recurring software revenue.
Within the diversified automotive tier, Continental AG and ZF Friedrichshafen AG exemplify scale-driven players leveraging in-house manufacturing breadth. Sensata Technologies Inc. occupies a specialist position focused on temperature-compensated designs for severe-duty applications. Bendix Commercial Vehicle Systems LLC represents the system-integrator archetype, consolidating tire and brake diagnostics into unified fleet dashboards.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Pacific Industrial Co. Ltd. |
| Schrader Electronics |
| Sensata Technologies Inc. |
| ZF Friedrichshafen AG |
| Bendix Commercial Vehicle Systems LLC |
| Delphi Automotive |
| Alligator Ventifabrik GmbH |
| Others |
Value Network & Pricing Analysis
Detroit Three OEM procurement concentration anchors contract-based long-term offtake agreements for direct TPMS silicon MEMS sensors, compressing spot-market premiums and favoring suppliers with captive semiconductor fabrication capacity.
Pricing Analysis
Volume concentrates in OEM channels where per-unit margins compress under multi-year supply agreements, while aftermarket retrofit installations command labor-inclusive premiums. Pricing stratifies across premium cellular-connected architectures, standard RF receiver systems, and economy bolt-on valve-cap transmitters. Cost compression in the standard tier intensifies as Taiwanese foundry output expands. Regional LTL fleets exhibit highest price sensitivity; national for-hire carriers prioritize data granularity over unit cost.
Supply Chain Analysis
Workforce availability constraints in Michigan and Ohio manufacturing corridors are pushing sensor module assembly toward Mexico's Nuevo León maquiladora zone. MEMS die fabrication draws from Taiwan and South Korea foundries; sensor housings and antenna components source from China and Mexico. Single-source vulnerability in semiconductor wafer supply exposes lead times to geopolitical disruption. Distribution runs through Tier 1 brake system integrators and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet telematics platform consolidation is accelerating vendor attrition, with cellular connectivity mandates from Schneider National and J.B. Hunt specifications forcing RF-only specialists toward exit or acquisition.
For Market Incumbents: Deploy backward integration into MEMS die production to secure allocation priority at Taiwanese foundries. Consolidate brake-TPMS data aggregation capabilities to match Bendix Commercial Vehicle Systems bundling strategies. Sensor suppliers lacking captive semiconductor fabrication face margin erosion from allocation constraints during supply shocks. For New Entrants and Emerging Players: Launch via subscription-based Smart Tire Systems platforms targeting refrigerated pharmaceutical carriers in the US Midwest. Bolt-on external valve-cap systems offer lowest barrier to entry for owner-operator segments in the US Southeast. API-first architectures attract Chicago-based 3PLs serving automotive just-in-time lanes. For Investors and Strategic Acquirers: The window for entry favors MEMS sensor houses with temperature-compensated severe-duty designs and established foundry relationships. Acquisition targets should demonstrate proven integration with fleet telematics platforms. Monitor NHTSA enforcement intensity for FMVSS 138 retrofit deadlines as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Secures wafer allocation from Taiwan Semiconductor Manufacturing for Class 8 sensor demand. |
| Cellular Modem Integration | Aligns hardware specifications with J.B. Hunt LTE-M procurement requirements. |
| Brake-TPMS Data Convergence | Matches Bendix Commercial Vehicle Systems bundled dashboard offerings. |
| Smart Tire Subscription Launch | Captures per-mile revenue from Midwest pharmaceutical refrigerated carriers. |
| Mexican Assembly Footprint | Positions module production near Kenworth and Peterbilt Ohio manufacturing lines. |
Research Methodology
SEC 10-K filings, NHTSA regulatory dockets, and commercial vehicle production databases formed the secondary backbone, cross-referenced against primary interviews with fleet telematics directors, Tier 1 brake system procurement managers, and aftermarket service bay operators. Bottom-up sensor shipment data triangulated against top-down OEM fitment rates derived from Michigan-Ohio manufacturing corridor output figures.
Bottom-up modeling aggregated sensor unit economics across direct, indirect, and Smart Tire System architectures, while top-down validation referenced fleet operator RFP specifications and EPA SmartWay participation records. Segmentation dimensions spanned product type, installation channel, end-user operational intensity, and connectivity architecture. CAGRs were computed from fitted trend lines across the projection horizon, incorporating silicon MEMS cost curves and cellular modem price parity assumptions.
The model assumes a particular technology adoption path; alternative pathways for RF-to-cellular migration would alter the outlook. Forecasts reflect assumptions regarding NHTSA enforcement intensity, foundry allocation stability, and fleet telematics platform consolidation velocity. Material deviation in CMVSS 138 Canadian enforcement timelines or Taiwan semiconductor export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
High Performance Wheels Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
GCC Tire Market
Tires and Wheels
Tire Building Machinery Market