
 Tire Bead Wire Market | 2026-2036
Tire Bead Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Bead Wire Market Analytics
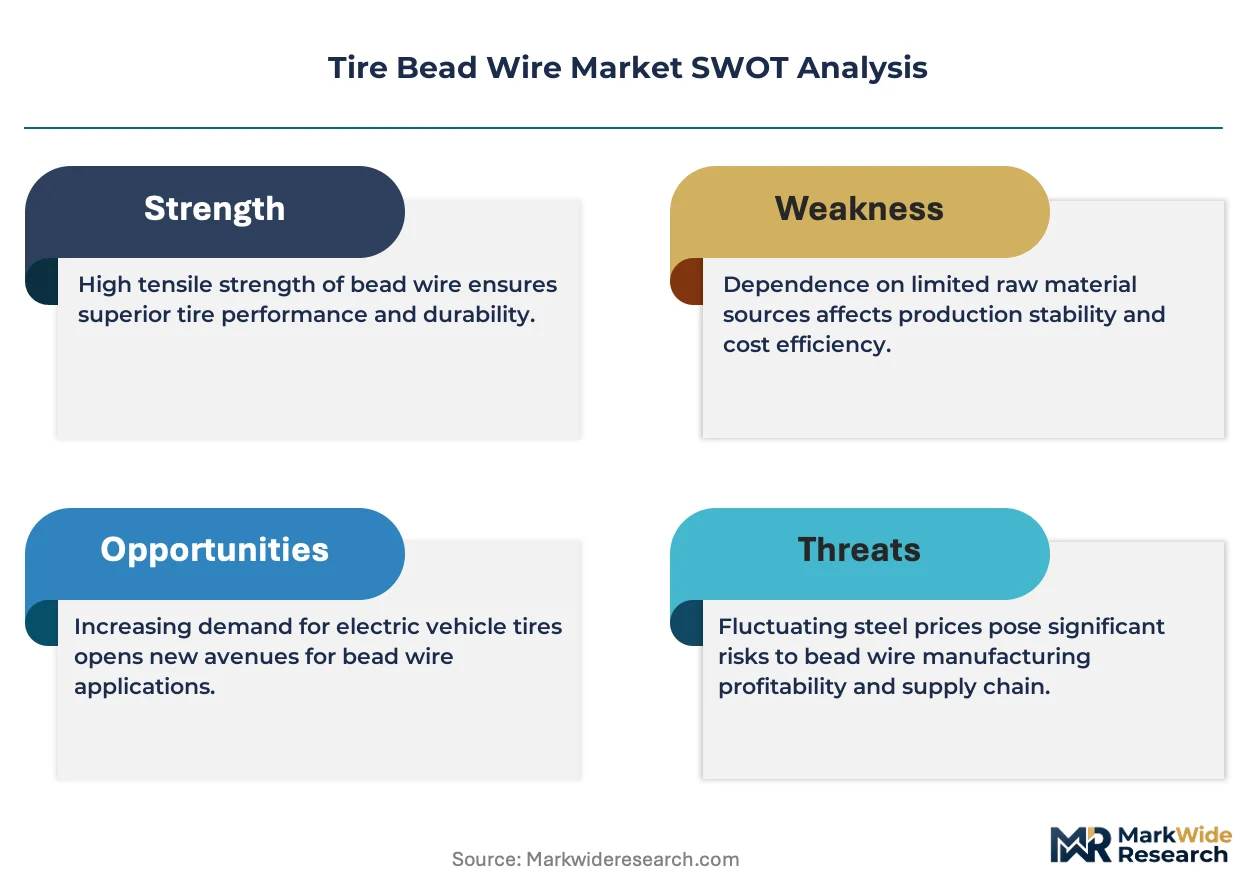
The high-tensile specification tier is unwinding legacy commodity dynamics across tire bead wire procurement. Bekaert leverages its European R&D footprint to dominate ultra-high-strength wire certification for premium tire makers. HS Hyosung Advanced Materials anchors its position through backward integration into steel rod production, cutting raw material transit costs. Rajratan Global Wire Limited specializes in brass-coated variants for the two-wheeler aftermarket across South and Southeast Asia.
Tire bead wire is a high-carbon steel filament, typically drawn to diameters between 0.78 mm and 2.0 mm and coated with brass or bronze to ensure rubber adhesion, functioning as the structural anchor that locks the tire to the wheel rim under inflation pressure. The product-type split shows bead wire and steel wire commanding the volume base while synthetic wire experiments remain marginal due to cost-performance gaps in heavy-load applications. Among coating types, brass-coated wire captures the margin pool from OEM passenger tire contracts, whereas galvanized formulations face substitution pressure in cost-sensitive commercial vehicle segments.
The EPA, REACH, and India's BIS standards collectively govern permissible tensile strength variance, coating chemistry limits, and end-of-life recyclability disclosures, pushing manufacturers toward documented batch traceability. China's GB standards and the EU's F-Gas Regulation indirectly shape demand by accelerating lightweight tire designs that redistribute stress onto bead wire specifications. Stakeholders must monitor how battery-electric vehicle weight penalties alter OEM wire tensile requirements before committing to capacity expansion.
Market Dynamics
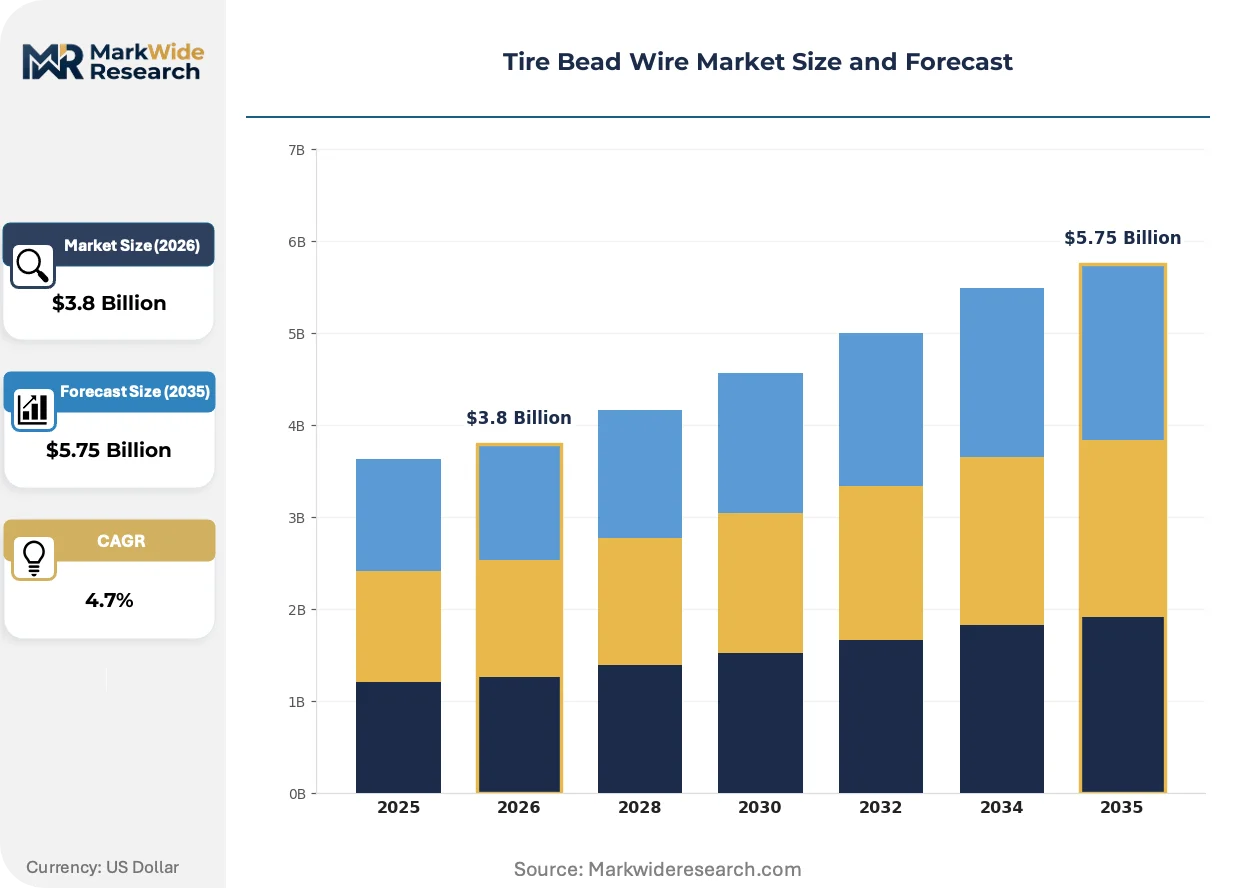
Electric vehicle platform weight penalties are forcing bead wire specification upgrades across passenger tire OEMs, compressing legacy commodity supply chains while high-tensile certification tiers capture margin concentration.
Growth Catalysts
- EPA fuel-efficiency standards:US passenger vehicle OEMs demand lighter tire assemblies that redistribute structural stress onto higher-specification bead wire, accelerating tensile grade transitions.
- Two-wheeler aftermarket density:Brass-coated wire variants command replacement cycle volume across India, Indonesia, and Vietnam where motorcycle tire refurbishment rates exceed passenger vehicle norms.
- Localized supply chain mandates:China's tire manufacturing clusters are consolidating captive wire production within 150-kilometer radius requirements under MIIT industrial zone policies.
Market Restraints
- Steel rod input volatility:Scrap steel and iron ore price swings transmit directly to bead wire margin structures, compressing converter economics during commodity spikes.
- REACH coating chemistry limits:European brass formulation adjustments face ECHA registration timelines that extend qualification windows by 12-18 months against OEM contract cycles.
- Synthetic wire substitution ceiling:Aramid and polymer alternatives fail heavy-load commercial vehicle fatigue thresholds above 3.5-ton axle ratings, locking steel wire dominance in freight segments.
Strategic Opportunities
- India BIS standard alignment:Domestic tire makers are localizing wire supply under Bureau of Indian Standards tensile variance rules, opening import substitution capacity for integrated rod-to-wire producers.
- Recyclability disclosure mandates:EU CSRD scope 3 reporting requirements create certified batch traceability premiums for wire makers with documented end-of-life steel recovery partnerships.
- EV platform specialization:Battery-electric vehicle curb weight premiums of 300-500 kg are driving OEM specification splits between standard passenger and reinforced EV-dedicated bead wire grades.
Industry Challenges
- Ultra-high-strength metallurgy talent scarcity:Wire drawing engineers with 2,000+ MPa tensile process expertise concentrate at Bekaert and HS Hyosung, constraining competitor qualification velocity.
- Dual certification timeline compression:Simultaneous GB standard (China) and ECE R30 (Europe) homologation for export tire wire requires parallel testing tracks that extend R&D payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Bead Wire Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bead Wire, Steel Wire, Synthetic Wire, Copper Wire Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Industrial Tires Coating Type: Galvanized, Brass Coated, Black Coated, Stainless Production Method: Cold Drawing, Heat Treatment, Surface Coating, Cladding |
| Companies Covered | Rajratan Global Wire Limited, SNTAI Industrial Group Ltd, Bekaert, Sumitomo Electric, HS Hyosung Advanced Materials, Kiswire, HBT Rubber Industrial Co., Ltd, Jiangsu Xingda Steel Tyre Cord Co., Ltd, WireCo World Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Bead Wire Market Evolving Landscape
Material science advances and regulatory chemistry constraints are bifurcating bead wire procurement into certified premium tiers and cost-optimized commercial grades, with coating innovation emerging as the primary differentiation vector.
Advanced brass-copper alloy coatings with sub-micron thickness control are fragmenting the traditional single-formulation brass coating market. Premium passenger tire OEMs in Germany and Japan are specifying multi-layer deposition systems that improve rubber-to-steel adhesion by 15-20% in high-humidity climates. This coating tiering is fragmenting supplier bases into certified premium wire specialists and undifferentiated commodity converters.
REACH Annex XVII restrictions on nickel and chromium release rates are forcing reformulation of traditional brass coating chemistries across European tire wire supply chains. The ECHA sunset date for certain copper salt precursors is compressing qualification timelines for alternative adhesion promoters. Wire makers serving Continental and Michelin contract tiers are accelerating bronze-nickel alloy trials to preempt regulatory displacement.
Direct mill-to-tire-plant consignment inventory models are displacing traditional distributor stocking arrangements in high-volume OEM contracts. Tier 1 tire makers in China and South Korea are mandating vendor-managed inventory with 72-hour replenishment guarantees, transferring working capital burden upstream to wire producers. This channel restructuring is most visible in Shandong and Jiangsu province tire manufacturing corridors where just-in-time wire delivery has become a contractual baseline.
Tire Bead Wire Market Segmentation
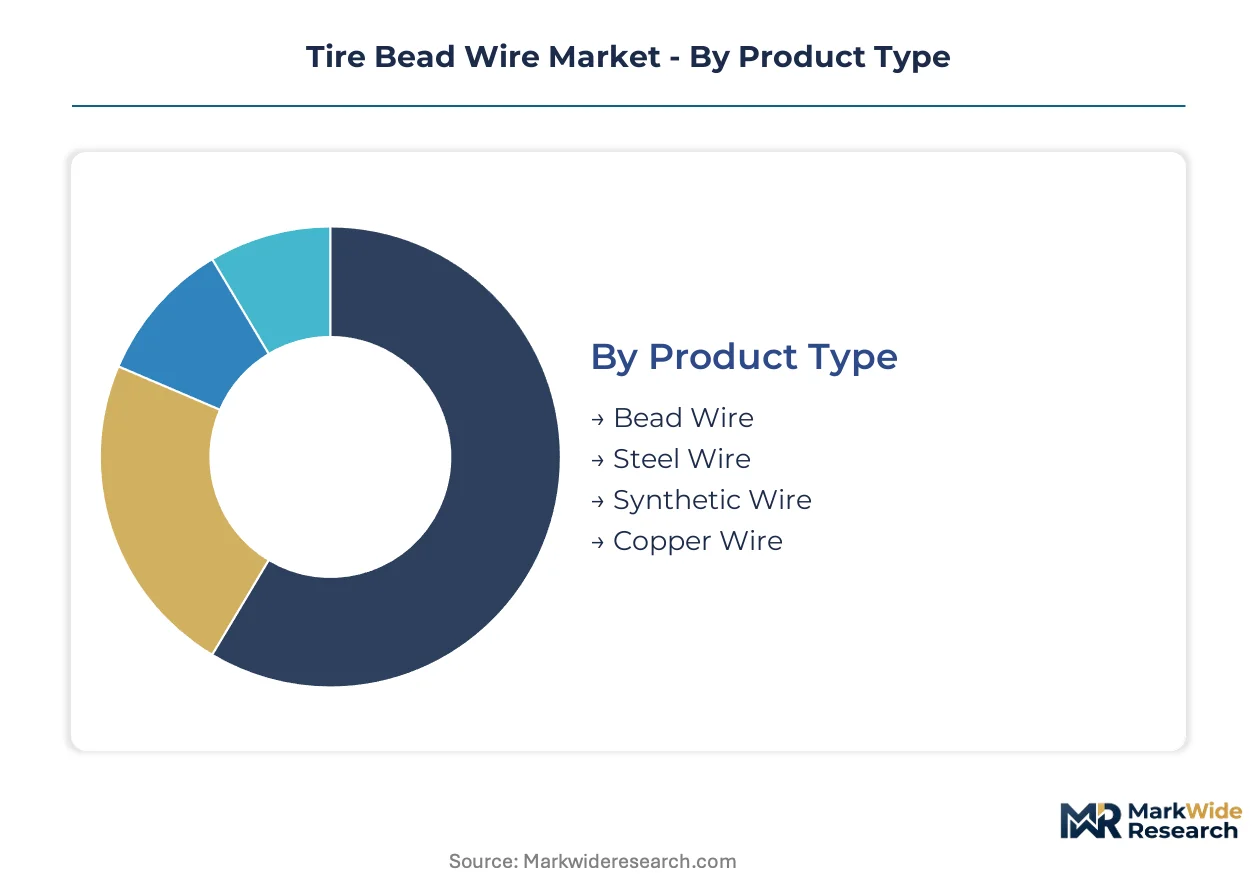
Tire bead wire procurement splits across material grades, end-use durability requirements, and coating chemistry tiers. Specification divergence between OEM passenger contracts and commercial vehicle replacement cycles fragments supplier specialization.
Product Type:
Domestic production clusters in China and India concentrate on commodity steel grades, while export-oriented capacity in Belgium and South Korea targets ultra-high-tensile certification for premium tire makers.
- Bead Wire:High-carbon steel filament drawn to 0.78-2.0 mm diameter serves as the structural anchor locking tires to wheel rims under inflation pressure. Passenger vehicle OEMs in Germany and Japan specify this grade for original equipment fitments where fatigue resistance thresholds exceed 2,000 MPa tensile strength.
- Steel Wire:Drawn from rod stock with controlled pearlite microstructure dominates commercial vehicle and heavy-truck tire construction. Demand concentrates in Shandong province tire manufacturing corridors where localized rod-to-wire integration cuts logistics costs under MIIT industrial zone mandates.
- Synthetic Wire:Aramid and polymer alternatives remain marginal due to cost-performance gaps above 3.5-ton axle ratings.
- Copper Wire:Specialized conductivity applications in industrial tire segments represent niche procurement.
Bead wire commands the established base. The steepest expansion runs through steel wire as EV platform weight penalties force specification upgrades.
Application:
Cost tier differentiation separates premium OEM contracts with batch traceability requirements from price-sensitive replacement cycles in emerging markets.
- Passenger Vehicles:OEM tire contracts specify brass-coated variants with documented tensile variance under EPA fuel-efficiency standards that redistribute structural stress onto higher-specification wire. Battery-electric vehicle curb weight premiums of 300-500 kg are driving dedicated EV-grade bead wire qualifications.
- Commercial Vehicles:Freight axle ratings above 3.5 tons lock steel wire dominance as synthetic alternatives fail fatigue thresholds. Replacement cycle volume concentrates in North American long-haul and European logistics fleets where retreading rates extend wire service life.
- Two-Wheelers:Brass-coated wire captures aftermarket density across India, Indonesia, and Vietnam where motorcycle tire refurbishment rates exceed passenger vehicle norms.
- Industrial Tires:Mining and construction equipment specifications demand heavy-gauge wire with enhanced corrosion resistance.
Commercial vehicles anchor volume throughput. Passenger vehicles are climbing the fastest as EV platform specialization fragments OEM procurement tiers.
Coating Type:
Margin concentration follows coating chemistry complexity, with multi-layer deposition systems capturing premium pricing against commodity galvanized formulations.
- Brass Coated:Multi-layer brass-copper alloy coatings with sub-micron thickness control improve rubber-to-steel adhesion by 15-20% in high-humidity climates. REACH Annex XVII restrictions on nickel and chromium release rates are forcing reformulation trials across European supply chains.
- Galvanized:Zinc-based coatings face substitution pressure in cost-sensitive commercial vehicle segments where adhesion requirements are less stringent than passenger OEM specifications.
- Black Coated:Oxidation-resistant formulations serve specific industrial tire applications with extended outdoor exposure.
- Stainless:Premium corrosion resistance for specialty mining and marine equipment represents low-volume, high-margin supply.
Brass coated wire holds the margin pool. Galvanized formulations are gaining share fastest in emerging market commercial vehicle replacement cycles.
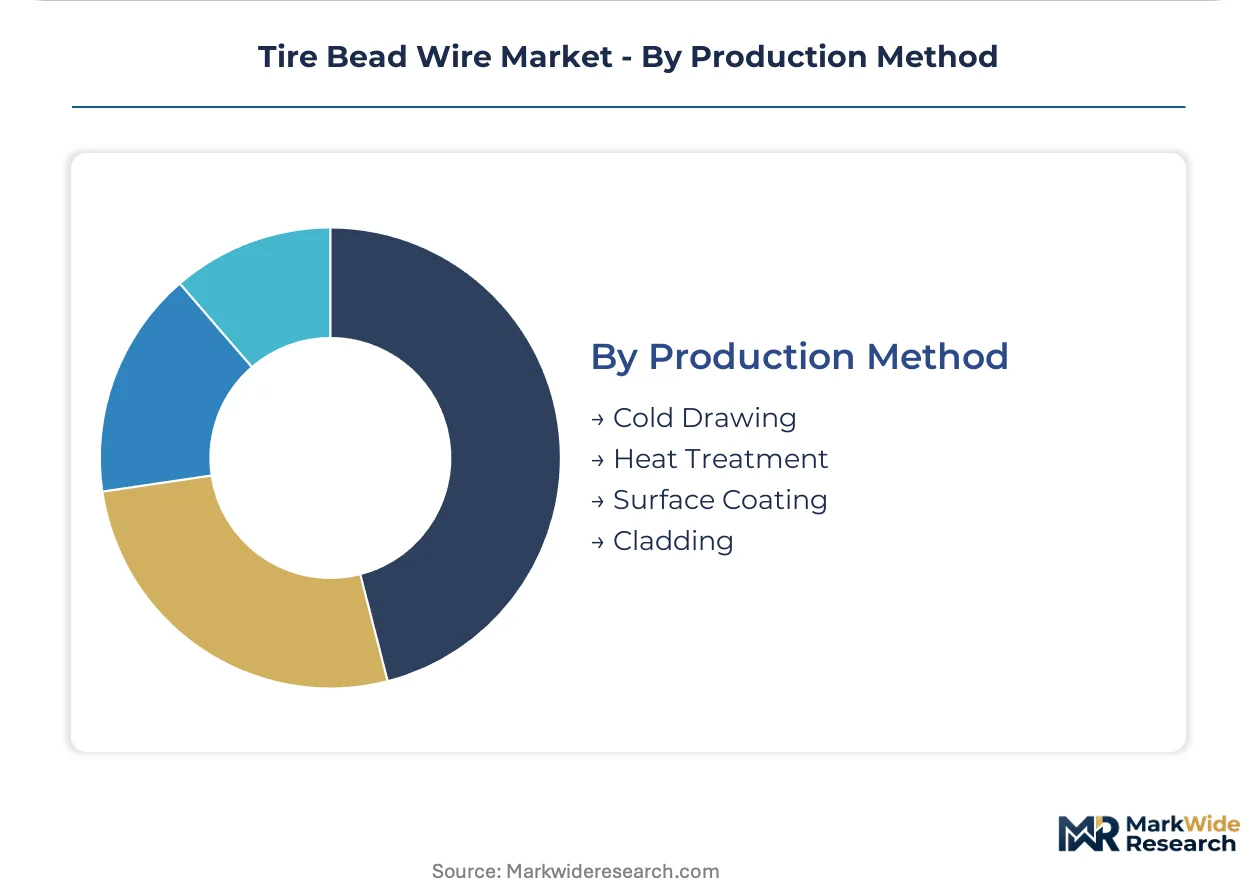
Production Method:
Supply concentration among integrated rod-to-wire producers favors captive cold drawing and heat treatment capacity over outsourced surface processing.
- Cold Drawing:Progressive die reduction from rod stock to final diameter achieves controlled work hardening and dimensional precision. Bekaert and HS Hyosung concentrate 2,000+ MPa tensile process expertise in European and South Korean facilities.
- Heat Treatment:Patenting and stress-relieving ovens tune microstructure for fatigue resistance in ultra-high-strength grades.
- Surface Coating:Electrodeposition and hot-dip lines apply brass, bronze, or zinc layers with thickness control critical to rubber adhesion.
- Cladding:Mechanical bonding of dissimilar metals serves niche corrosion-resistant specifications.
Cold drawing anchors capacity investment. Heat treatment is expanding most quickly as tensile grade transitions accelerate under EV platform requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated rod-to-wire capacity clusters in China, India, Belgium, and South Korea capture the bulk of global tire bead wire supply. Regulatory fragmentation across EPA, REACH, and BIS standards forces parallel certification tracks that advantage producers with multi-jurisdictional testing infrastructure. Localized procurement mandates in automotive manufacturing corridors are shortening supply radii to under 150 kilometers.
China
Shandong and Jiangsu province tire manufacturing corridors drive captive wire demand under MIIT industrial zone localization policies. GB standards for tensile variance and coating chemistry operate alongside evolving dual carbon goals that favor lightweight tire designs. Qingdao-based tire OEMs are mandating 72-hour vendor-managed inventory replenishment from wire producers within 150-kilometer radii.
Germany
Continental and Michelin contract tiers specify ultra-high-strength wire grades above 2,000 MPa tensile strength for premium passenger tire fitments. REACH Annex XVII restrictions on nickel and chromium release rates compress ECHA registration timelines for brass coating reformulations. Baden-Württemberg and Lower Saxony host the European R&D footprint where bronze-nickel alloy trials are accelerating.
India
Two-wheeler aftermarket density across Maharashtra, Gujarat, and Tamil Nadu sustains brass-coated wire replacement cycles exceeding passenger vehicle norms. BIS tensile variance rules are driving domestic tire makers toward localized wire supply under import substitution mandates. Pune and Chennai manufacturing clusters are consolidating captive bead wire production within state industrial corridor policies.
United States
EPA fuel-efficiency standards redistribute structural stress onto higher-specification bead wire as passenger vehicle OEMs pursue lighter tire assemblies. Long-haul freight fleets in Texas and the Midwest extend steel wire service life through retreading cycles above 3.5-ton axle ratings. Detroit-area tire plants are qualifying EV-dedicated bead wire grades to accommodate battery-electric vehicle curb weight premiums.
South Korea
Busan-Ulsan tire manufacturing corridors anchor export-oriented capacity targeting ECE R30 European homologation alongside domestic GB standard alignment. MFDS-equivalent industrial standards govern coating chemistry disclosures for wire serving premium OEM contracts. Daegu-Gyeongbuk metallurgy expertise concentrates 2,000+ MPa tensile process knowledge at integrated rod-to-wire facilities.
Tire Bead Wire Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the tire bead wire market. Ultra-high-strength certification tiers above 2,000 MPa tensile strength concentrate among European and South Korean integrated producers with captive metallurgy R&D, while commodity-grade volume flows through Chinese and Indian rod-to-wire converters optimized for logistics proximity. Three archetypes dominate: integrated premium specialists with backward control into steel rod production, regional scale converters serving localized tire clusters, and coating technology specialists differentiating on brass-bronze adhesion chemistry. Competitive dynamics center on parallel GB-ECE dual certification velocity and vendor-managed inventory working capital transfers upstream to wire producers.
Among integrated premium specialists, Bekaert anchors the European R&D footprint for ultra-high-strength wire certification, while HS Hyosung Advanced Materials occupies a parallel position in South Korea with captive steel rod production. Rajratan Global Wire Limited exemplifies the regional scale converter archetype, specializing in brass-coated variants for high-volume two-wheeler aftermarket cycles across South and Southeast Asia. These three represent the dominant competitive positions: technology-driven certification leadership, integrated cost control, and regional aftermarket density capture.
| Leading Market Players |
|---|
| Rajratan Global Wire Limited |
| SNTAI Industrial Group Ltd |
| Bekaert |
| Sumitomo Electric |
| HS Hyosung Advanced Materials |
| Kiswire |
| HBT Rubber Industrial Co., Ltd |
| Jiangsu Xingda Steel Tyre Cord Co., Ltd |
| WireCo World Group |
| Others |
Value Network & Pricing Analysis
Integrated rod-to-wire capacity utilization above 85 percent in Shandong and Jiangsu provinces anchors price floors for commodity-grade bead wire while compressing margins for non-integrated converters. Scale economies at HS Hyosung and Bekaert facilities generate cost advantages that transmit into premium-tier pricing power for ultra-high-strength certifications above 2,000 MPa tensile strength.
Pricing Analysis
EPA fuel-efficiency standards dictate the pricing tier structure across passenger tire OEM contracts, stratifying procurement across premium EV-dedicated grades, standard high-tensile tiers, and economy commercial vehicle specifications. Price differentiation rests on certification level — ECE R30 homologation commands 15-20 percent premiums over uncertified commodity wire — and volume scale, with annual offtake above 10,000 tons unlocking contract-based long-term pricing. Cost compression in galvanized commercial grades is intensifying because scrap steel volatility transmits directly to converter economics. Two-wheeler aftermarket buyers across India and Indonesia exhibit highest price sensitivity, while German premium OEMs show lowest elasticity for brass-coated multi-layer deposition systems.
Supply Chain Analysis
Rod stock availability from integrated steel mills in China, South Korea, and Belgium constitutes the critical upstream chokepoint for bead wire production globally. Raw material dependencies draw from high-carbon steel rod with controlled pearlite microstructure, brass and bronze coating chemistries, and specialized drawing lubricants. Tariff exposure on steel rod imports into the European Union presents the dominant structural risk, compressing qualification timelines for alternative Asian suppliers. Distribution runs through direct mill-to-tire-plant consignment inventory models displacing traditional distributor arrangements, with vendor-managed inventory transferring working capital burden upstream to wire producers serving Qingdao and Ulsan manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform weight penalties constitute a high-growth disruption forcing specification bifurcation across tire bead wire procurement, with battery-electric curb weight premiums of 300-500 kg creating dedicated EV-grade qualification windows before incumbent capacity locks in.
For Market Incumbents: Shield ultra-high-strength certification tiers by accelerating bronze-nickel alloy coating trials ahead of REACH Annex XVII sunset dates for copper salt precursors. Deepen backward integration into steel rod production to insulate margin structures from scrap steel volatility, while defending channel position through 72-hour vendor-managed inventory guarantees for Shandong and Jiangsu tire manufacturing clusters. For New Entrants and Emerging Players: Differentiate on coating chemistry specialization for humidity-critical markets, targeting brass-copper multi-layer deposition systems where adhesion performance gaps exceed 15 percent against commodity formulations. Penetrate the India two-wheeler aftermarket through brass-coated variants serving Maharashtra and Tamil Nadu refurbishment cycles exceeding passenger vehicle norms, leveraging BIS standard alignment as regulatory entry credential. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated rod-to-wire producers with captive metallurgy R&D and parallel GB-ECE dual certification infrastructure. Long-term viability over the next decade rests on EV platform specialization capability and documented batch traceability for EU CSRD scope 3 reporting. Watch for battery-electric vehicle penetration rates crossing 25 percent in premium passenger segments as the inflection signal for EV-dedicated bead wire grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Rod Production | Captive rod supply insulates margin structures from scrap steel volatility at Qingdao and Ulsan facilities. |
| Dual GB-ECE Certification Investment | Parallel homologation tracks accelerate export qualification velocity for premium European tire OEM contracts. |
| Coating Chemistry Reformulation | Bronze-nickel alloy trials preempt REACH Annex XVII displacement of traditional brass formulations. |
| Vendor-Managed Inventory Expansion | 72-hour replenishment guarantees lock in channel position across Shandong tire manufacturing corridors. |
| EV-Dedicated Grade Qualification | Reinforced wire specifications capture battery-electric vehicle curb weight premium demand from Detroit-area plants. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed wire producers, MIIT industrial zone policy documents, and ECHA registration databases. Primary engagement spanned tire OEM procurement directors, wire drawing plant managers, metallurgy R&D leads at integrated producers, and channel distributors across China, India, Germany, and South Korea. Bottom-up capacity modeling triangulated against top-down demand estimates from vehicle production databases and tire industry association statistics.
Segmentation dimensions modeled include product type tier, coating chemistry specification, end-use application durability requirements, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating EV platform penetration assumptions, retreading cycle intensity by freight corridor, and two-wheeler aftermarket refurbishment rates. Industry-specific forecast inputs encompassed tensile grade transition velocity under EPA fuel-efficiency standards and REACH coating chemistry compliance timelines.
Material uncertainties — steel rod input cost volatility, ECHA registration delays for alternative adhesion promoters, and battery-electric vehicle specification fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained MIIT localization mandates and continued dual certification requirements for export-oriented capacity. Revision becomes warranted when EV platform weight penalties exceed 500 kg or when synthetic wire alternatives achieve cost-performance parity above 3.5-ton axle ratings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Global Commercial Vehicle Run Flat Tire Inserts Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Connected Tire Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Wheel Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
Passenger Tire Market