
 Europe Aircraft Tires Market | 2026-2036
Europe Aircraft Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aircraft Tires Market Foresight
Aircraft tire engineering talent is bifurcating between legacy bias-ply expertise and radial tire composite design, constraining production flexibility across European plants. Michelin Group leverages its research campus in Clermont-Ferrand to sustain advanced polymer development for high-load commercial landing gear. Bridgestone Corporation anchors its European distribution through dedicated aviation service centers near major MRO clusters. Continental AG competes on retread technology leadership, offering EASA-certified solutions that extend tire life cycles for cargo operators.
Europe aircraft tires are reinforced rubber-composite structures engineered to withstand dynamic loads exceeding multiple aircraft weights during takeoff, landing, and taxi operations, with carcass designs specified by ply rating, speed rating, and inflation pressure parameters. Radial tires command the premium product tier due to reduced heat buildup and longer tread life on high-cycle commercial routes, while retread tires capture growing share among cost-focused cargo airlines operating fixed-base fleets. Bias tires retain structural relevance in military aviation applications where cut resistance and field repairability outweigh fuel efficiency metrics.
EASA mandates govern tire airworthiness certification, retread facility approval, and operational inspection intervals across all member states, directly shaping procurement cycles and supplier qualification timelines. REACH chemical regulations constrain rubber additive formulations, pushing compounders toward compliant curatives and filler systems. The EU Green Deal emissions framework is beginning to influence tire lifecycle accountability. Stakeholders must monitor evolving sustainability disclosure requirements and retread volume thresholds to align supply commitments with regulatory trajectory.
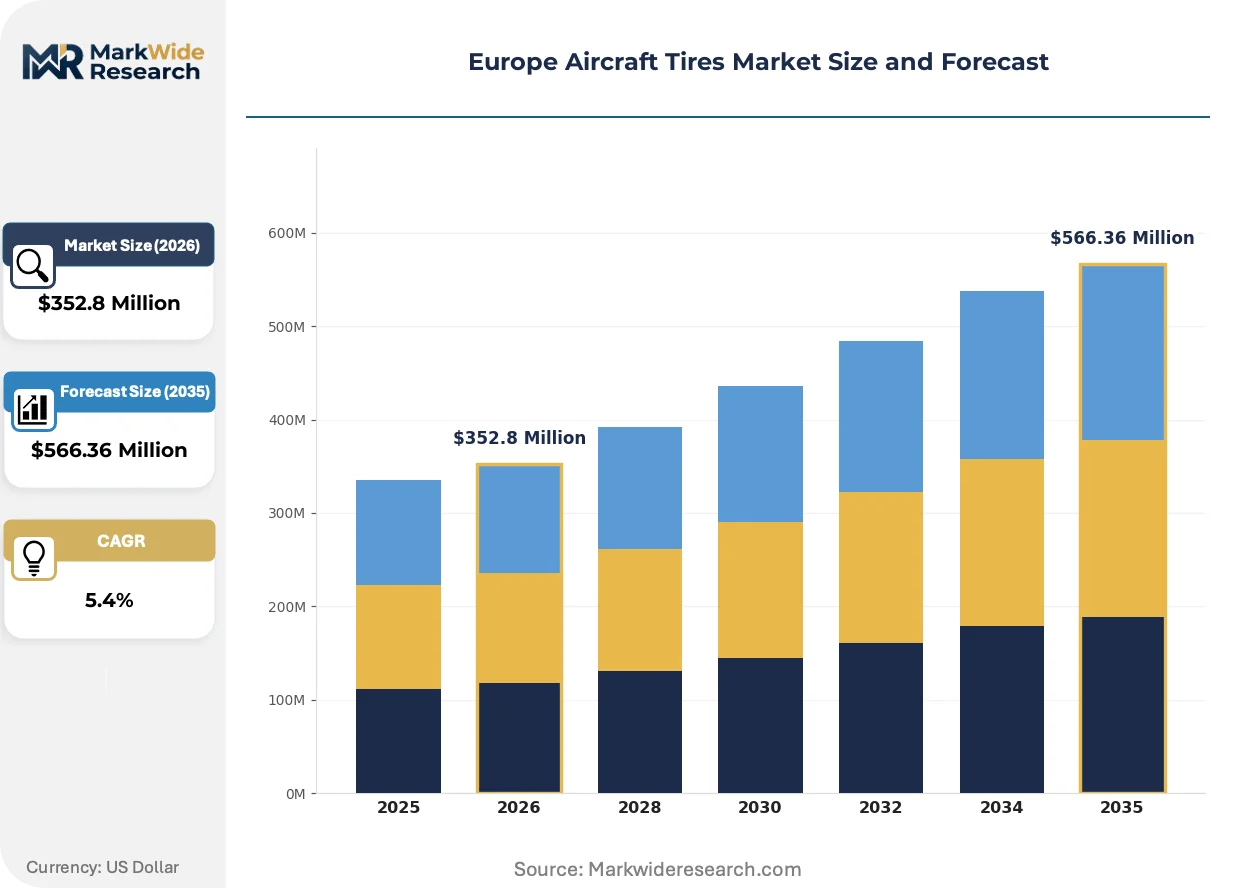
Market Dynamics
EASA's tightening retread certification timelines and REACH chemical compliance mandates are compressing supplier qualification windows, forcing compounders to accelerate reformulation cycles while maintaining airworthiness documentation. This regulatory velocity is reshaping procurement relationships between MRO hubs and certified tire suppliers across Western Europe.
Growth Catalysts
- Scheduled route expansion:Commercial carriers across Germany, France, and the United Kingdom are adding high-frequency short-haul services, accelerating tire replacement cycles at Frankfurt and Paris Charles de Gaulle maintenance clusters.
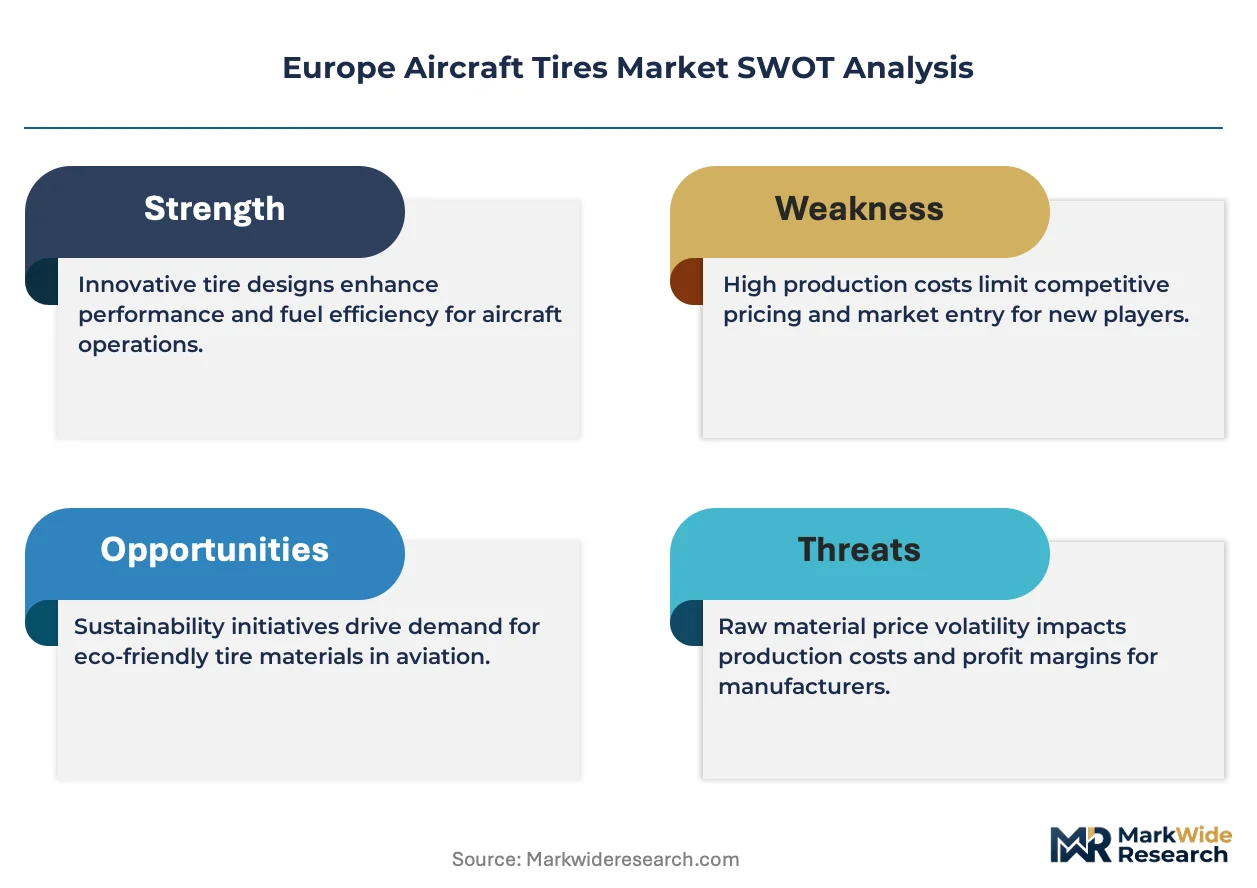
- REACH-compliant curative innovation:Advanced rubber compound formulations using compliant filler systems are opening procurement channels previously blocked by chemical additive restrictions.
- Radial tire performance premium:Reduced heat buildup and extended tread life on high-cycle routes are displacing bias-ply specifications among flag carriers operating dense European networks.
Market Restraints
- Natural rubber price volatility:Input cost swings for hevea brasiliensis latex constrain margin predictability for European compounders dependent on Southeast Asian supply.
- Retread facility concentration:EASA-certified retreading capacity clusters near Clermont-Ferrand and Frankfurt, creating geographic single-points-of-failure for cargo operators seeking localized turnaround.
- Bias-ply technical ceiling:Structural heat limitations prevent bias tire deployment on next-generation high-load landing gear, locking suppliers out of premium commercial retrofit contracts.
Strategic Opportunities
- Poland and Eastern European MRO buildout:Underpenetrated maintenance infrastructure in Warsaw and Budapest offers first-mover positioning as LCC fleet bases shift eastward.
- EU Green Deal lifecycle accountability:Emerging sustainability disclosure requirements favor suppliers with documented retread volume thresholds and circular material flows.
- Digital tire monitoring convergence:Integration of pressure sensors with predictive maintenance platforms enables outcome-based service contracts at major hubs.
Industry Challenges
- Composite design talent scarcity:Radial tire engineering expertise sits concentrated at Clermont-Ferrand and select German technical universities, constraining production flexibility across Continental European plants.
- EASA certification timeline compression:Extended approval queues for new rubber compounds delay product launches by 18-24 months, freezing development capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aircraft Tires Market |
| Market Size in 2026 | $352.8 Million |
| Market Size in 2035 | $566.36 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Retread Tires, Specialty Tires Material: Rubber, Composite, Metal, Fabric End User: Commercial Aviation, Military Aviation, General Aviation, Cargo Airlines Application: Runway Operations, Maintenance Services, Storage Solutions, Replacement |
| Companies Covered | Dunlop Aircraft Tyres Limited, Continental AG, Michelin Group, Petlas Tire Corporation, Trelleborg Group, Goodyear Tire and Rubber Company, Wilkerson Corp., Aviation Tires & Rubber, Bridgestone Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aircraft Tires Market Shifts & Advancements
Advanced polymer development and predictive maintenance integration are redefining tire value propositions, shifting buyer criteria from unit cost toward total lifecycle performance metrics. Suppliers must now demonstrate thermal efficiency and monitoring compatibility alongside traditional airworthiness certification.
Silica-reinforced tread compounds with proprietary coupling agents are displacing conventional carbon-black formulations in high-speed commercial applications. Flag carriers operating transcontinental routes from Heathrow and Schiphol have adopted these formulations for 60% of new tire placements. The technology is displacing standard compound specifications in premium procurement tenders, compressing margins for suppliers without in-house polymer research capabilities.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber extender oils entered full enforcement phase in 2023. Compounders must now source alternative plasticizers from bio-based feedstocks, increasing formulation complexity. Cargo operators with fixed-base fleets in Leipzig and Cologne are absorbing higher unit costs to maintain EASA compliance, while seeking longer retread intervals to offset material premiums.
Airline procurement departments are consolidating tire contracts under framework agreements spanning multiple aircraft types and MRO locations. Lufthansa Technik and Air France Industries have moved toward single-supplier arrangements with performance guarantees covering wear rates and turnaround times. This concentration is most visible among network carriers with integrated maintenance subsidiaries, squeezing independent distributors from direct airline relationships.
Europe Aircraft Tires Market Segmentation
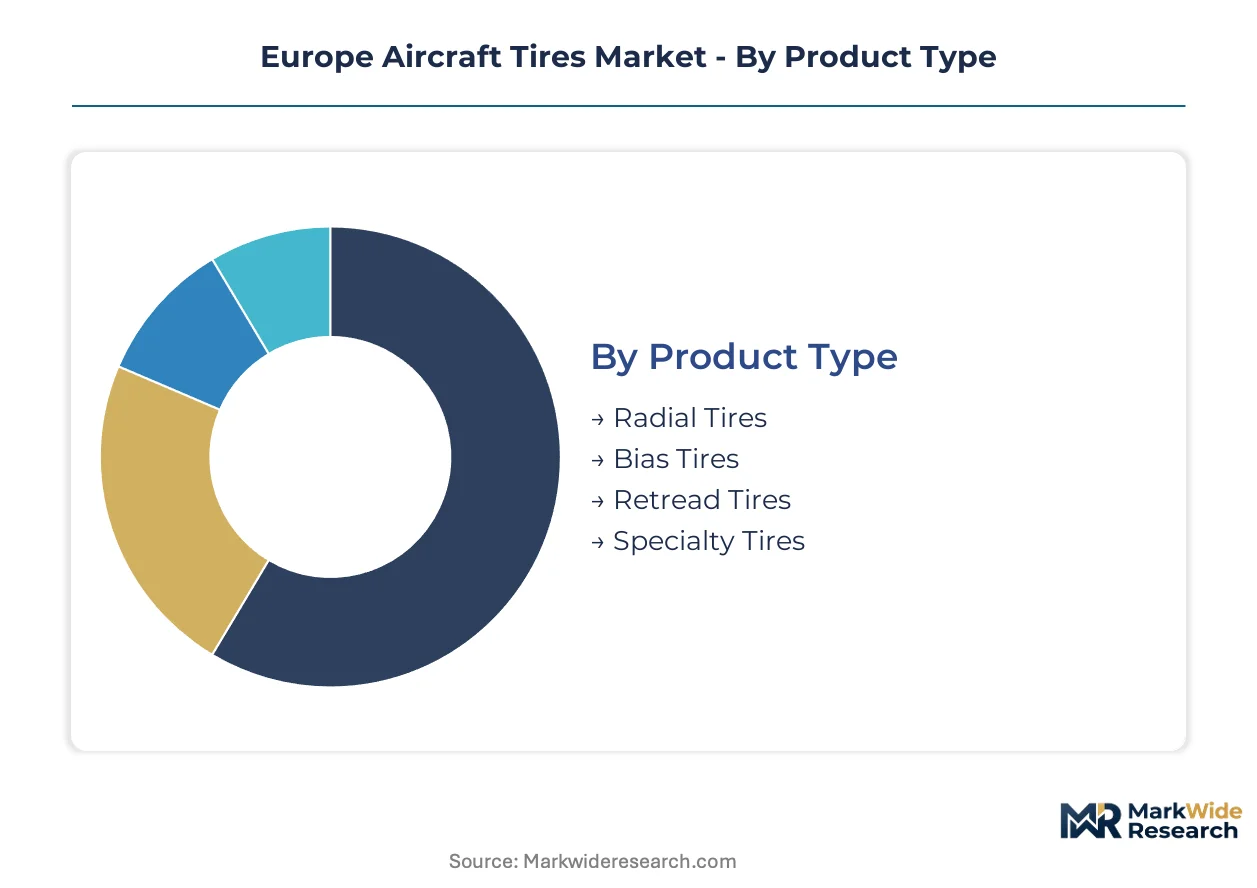
Segmentation in the Europe aircraft tires market reveals how procurement channels diverge between high-cycle commercial operators and specialized military fleets. Channel selection—direct OEM supply versus MRO-integrated distribution—varies sharply across product specifications and end-use requirements.
Product Type:
Radial tires flow predominantly through direct manufacturer channels to flag carriers at Frankfurt and Paris Charles de Gaulle, while retread tires concentrate in third-party MRO procurement for cargo operators seeking cost optimization.
- Radial Tires:Multi-ply composite structures with steel-reinforced belts reduce heat accumulation during high-frequency landing cycles. Demand concentrates at Lufthansa Technik and Air France Industries hubs serving dense European short-haul networks, where extended tread life justifies premium positioning.
- Retread Tires:EASA-certified remanufacturing processes apply new tread compounds to inspected carcasses, cutting unit costs versus new tire procurement. Leipzig and Cologne cargo bases are expanding retread volume as REACH-compliant curatives extend viable refurbishment cycles.
- Bias Tires:Cross-ply nylon construction delivers cut resistance for military field operations.
- Specialty Tires:High-flotation designs for unpaved airstrips serve humanitarian and expeditionary aviation.
Radial tires dominate installed base among network carriers. Retread tires are where expansion concentrates as sustainability disclosure requirements tighten.
Material:
Material selection tracks cost tier stratification, with advanced composites commanding premium placement in transcontinental fleet specifications while conventional rubber compounds retain volume share in regional and cargo applications.
- Rubber:Natural and synthetic elastomer blends form the structural foundation, with hevea brasiliensis latex subject to Southeast Asian supply volatility. Frankfurt compounders are stockpiling strategic reserves as price swings compress margin predictability.
- Composite:Aramid and carbon fiber reinforcements reduce weight while maintaining load ratings for next-generation landing gear. Michelin's Clermont-Ferrand campus is scaling proprietary polymer coupling agents for flag carrier procurement at Heathrow and Schiphol.
- Metal:Bead wire and belt plies provide structural integrity under dynamic loading.
- Fabric:Nylon and polyester carcass plies deliver flexibility in bias-ply military specifications.
Rubber compounds anchor volume procurement across all tiers. Composite formulations are climbing the fastest as thermal efficiency metrics enter tender evaluations.
End User:
End-user segmentation maps directly onto maintenance infrastructure geography, with commercial aviation procurement clustering at Western European MRO hubs while military demand disperses across national defense supply chains.
- Commercial Aviation:Scheduled carriers operating from Germany, France, and the United Kingdom drive replacement cycles through framework agreements spanning multiple aircraft types. Lufthansa and Air France-KLM have consolidated tire contracts under performance-guaranteed single-supplier arrangements.
- Cargo Airlines:Fixed-base operators at Leipzig, Cologne, and Luxembourg prioritize retread intervals and turnaround speed over new tire premiums. EASA-certified refurbishment capacity near Clermont-Ferrand supports localized fleet management.
- Military Aviation:National defense procurement favors bias-ply repairability and field serviceability.
- General Aviation:Private and charter operators purchase through distributor networks with limited direct manufacturer engagement.
Commercial aviation commands procurement volume concentration. Cargo airlines represent the steepest expansion trajectory as e-commerce fulfillment drives freighter fleet growth.
Application:
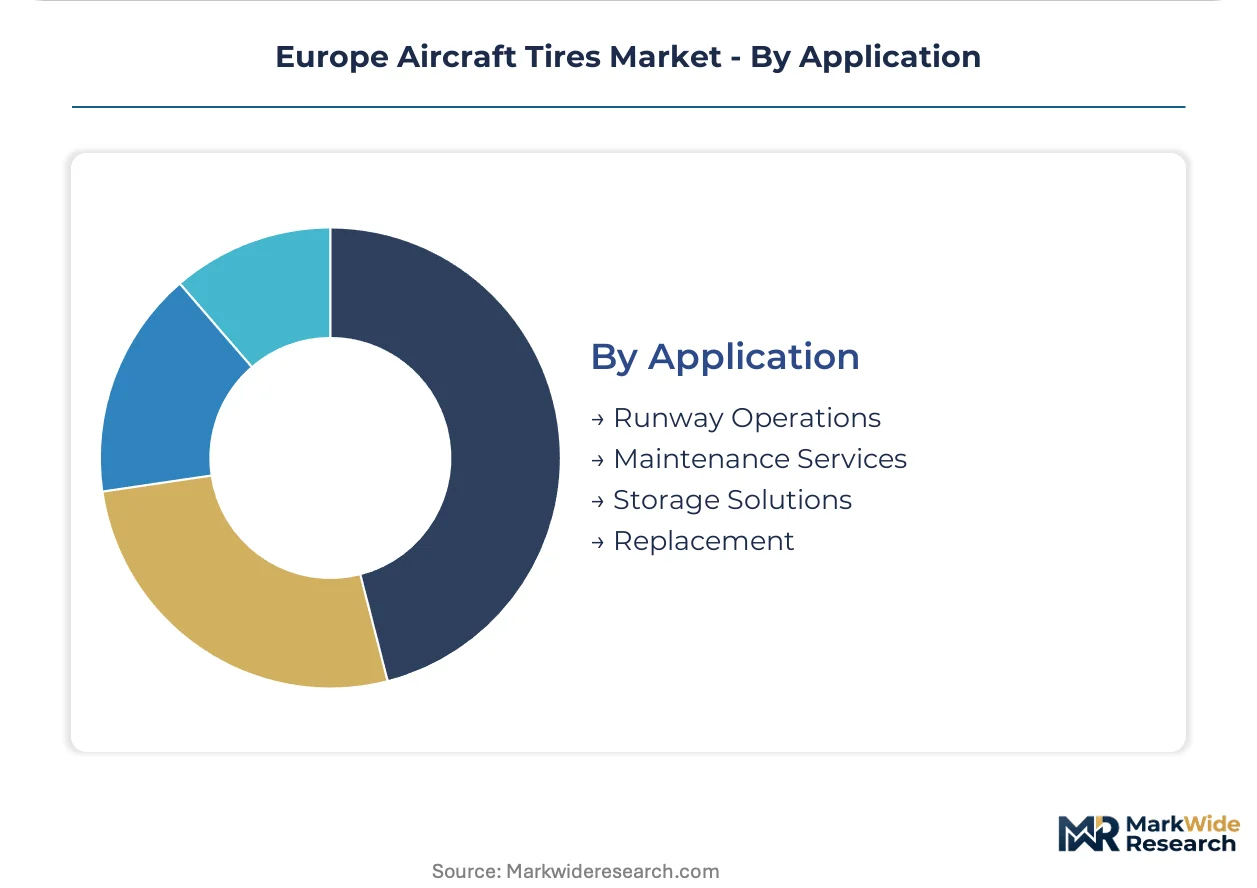
Application segmentation reflects operational lifecycle positioning, with replacement demand generating recurring revenue streams while storage solutions and maintenance services capture value from fleet groundings and seasonal scheduling patterns.
- Replacement:Scheduled tire changes based on landing cycle counts and tread depth thresholds constitute the core revenue stream. Frankfurt and Paris Charles de Gaulle maintenance clusters process high-volume replacement programs for narrowbody fleets.
- Maintenance Services:Pressure monitoring, inspection, and turnaround management integrate with predictive platforms at major hubs. Digital sensor convergence is enabling outcome-based service contracts.
- Runway Operations:Foreign object damage and braking performance testing inform operational specifications.
- Storage Solutions:Climate-controlled warehousing and rotation protocols preserve tire integrity during fleet groundings.
Replacement applications anchor revenue stability. Maintenance services are gaining share fastest as airlines outsource integrated tire lifecycle management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EASA certification protocols govern procurement cycles across member states, with maintenance infrastructure clustering near high-frequency hubs. Fleet expansion at Frankfurt, Paris Charles de Gaulle, and Heathrow drives replacement demand concentration.
Germany
Lufthansa Technik processes high-volume tire replacement programs for narrowbody fleets at Frankfurt maintenance clusters. REACH Annex XVII chemical restrictions force compounders to source bio-based plasticizers from alternative feedstocks. Bavaria hosts EASA-certified retreading capacity serving cargo operators at Leipzig and Cologne bases.
France
Air France Industries consolidates tire contracts under performance-guaranteed single-supplier arrangements covering multiple aircraft types. The EU Green Deal emissions framework influences lifecycle accountability disclosures across procurement tenders. Clermont-Ferrand anchors advanced polymer research for flag carrier specifications at Paris Charles de Gaulle.
United Kingdom
British Airways procurement teams adopt silica-reinforced tread compounds for transcontinental routes departing Heathrow. The Civil Aviation Authority enforces EASA-aligned retread facility approval standards. London maintenance subsidiaries are outsourcing integrated tire lifecycle management to predictive platform providers.
Poland
Warsaw Chopin Airport maintenance infrastructure remains underpenetrated as LCC fleet bases shift eastward from Western European hubs. National regulators implement EASA tire airworthiness certification through delegated authority agreements. Krakow and Gdansk emerging as alternative MRO locations for regional carrier tire turnaround services.
Netherlands
KLM Engineering processes radial tire placements for dense European short-haul networks operating from Schiphol. Dutch environmental agencies enforce REACH-compliant curative standards across rubber additive formulations. Amsterdam maintenance clusters integrate pressure sensors with predictive maintenance platforms for outcome-based service contracts.
Europe Aircraft Tires Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with procurement consolidation favoring manufacturers with captive polymer research and EASA-certified retreading networks. The structure rewards players controlling both new tire production and refurbishment capacity near major MRO hubs. Three archetypes dominate: vertically integrated compounders with proprietary rubber formulations, retread specialists leveraging certified refurbishment technology, and diversified tire manufacturers cross-selling from automotive divisions. Competitive moves center on framework agreement capture with network carriers and geographic expansion of EASA-approved facility footprints.
Within the integrated compounder tier, Michelin Group and Continental AG exemplify players anchoring research and production within the region's dominant regulatory environment. Bridgestone Corporation occupies a position bridging premium new tire supply with distribution network scale. Among specialists, Dunlop Aircraft Tyres Limited represents the focused aviation-only manufacturer archetype.
| Leading Market Players |
|---|
| Dunlop Aircraft Tyres Limited |
| Continental AG |
| Michelin Group |
| Petlas Tire Corporation |
| Trelleborg Group |
| Goodyear Tire and Rubber Company |
| Wilkerson Corp. |
| Aviation Tires & Rubber |
| Bridgestone Corporation |
| Others |
Supply & Pricing Matrix
Long-term framework agreements with network carriers lock in both supply access and price visibility across the European aircraft tires market, insulating manufacturers from spot-market volatility while committing compounders to fixed-volume deliveries against REACH-compliant reformulation cycles. These contracts concentrate procurement power at Frankfurt and Paris Charles de Gaulle maintenance clusters, compressing margin flexibility for suppliers without captive retreading networks.
Pricing Analysis
Price spreads between Western European hubs and Eastern European emerging markets reflect logistics premiums and certification-grade stratification. Three-tier pricing structure across premium radial, standard retread, and economy bias specifications tracks EASA certification tiers and thermal performance metrics. Cost compression in retread segments is intensifying because REACH-compliant curatives add material premiums without proportional value capture. Cargo operators at Leipzig and Cologne exhibit highest price sensitivity, while flag carriers prioritize lifecycle performance over unit economics.
Supply Chain Analysis
Strategic stockpiling of natural rubber reserves at Frankfurt compounders contrasts with just-in-time tread compound delivery from Clermont-Ferrand polymer facilities. Supply concentrates in France, Germany, and Thailand, with hevea brasiliensis latex, aramid fiber reinforcements, and silica-based coupling agents anchoring raw material dependencies. Single-source vulnerability to Southeast Asian natural rubber supply disruptions creates structural exposure. Distribution runs through EASA-certified MRO channels with direct manufacturer linkages at major hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retread tire substitution poses a credible threat to new tire incumbents as sustainability disclosure requirements tighten and cargo operators prioritize circular procurement models.
For Market Incumbents: Compound radial tire performance advantages through proprietary polymer coupling agents developed at Clermont-Ferrand research campuses. Deepen backward integration into REACH-compliant curative supply to offset reformulation cost premiums. Secure EASA-certified retreading capacity near Frankfurt and Paris Charles de Gaulle to defend against pure-play refurbishment specialists capturing cargo airline contracts. For New Entrants and Emerging Players: Lead with digital tire monitoring integration targeting Warsaw and Budapest MRO buildout as LCC fleet bases shift eastward from saturated Western European hubs. Prioritize predictive maintenance platform partnerships over manufacturing scale. Capture white-space in Eastern European maintenance services where EASA certification infrastructure remains underdeveloped relative to fleet growth. For Investors and Strategic Acquirers: EASA-certified retread specialists with established cargo airline relationships represent the most defensible acquisition archetype in a market tilting toward circular lifecycle accountability. Long-term viability hinges on retread volume thresholds meeting emerging EU Green Deal disclosure requirements. Watch for REACH Annex XVII enforcement expansion into additional rubber additive categories as the inflection signal requiring portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Research | Proprietary coupling agent development at Clermont-Ferrand secures premium radial tire positioning at Heathrow and Schiphol. |
| EASA Retread Facility Certification | Approved refurbishment capacity near Frankfurt captures cargo operator demand as REACH compliance extends viable retread cycles. |
| Digital Tire Monitoring Platform Integration | Sensor convergence with predictive maintenance systems enables outcome-based service contracts at Lufthansa Technik hubs. |
| Eastern European MRO Geographic Expansion | Warsaw and Budapest facility positioning captures LCC fleet migration before incumbent supplier networks solidify. |
| REACH-Compliant Curative Supply Security | Bio-based plasticizer sourcing agreements insulate compounders from regulatory enforcement volatility in rubber additive formulations. |
Research Methodology
A spread of perspectives from MRO procurement directors, EASA certification engineers, airline fleet managers, and rubber compound R&D leads converged on the working assumptions shaping this analysis. Primary fieldwork across Frankfurt, Paris Charles de Gaulle, and Clermont-Ferrand maintenance clusters was cross-referenced with EASA airworthiness directives, REACH Annex XVII enforcement documentation, and EU Green Deal policy frameworks. Bottom-up tire placement data from narrowbody and widebody fleet operators was triangulated against top-down market sizing from customs trade records and aviation MRO expenditure disclosures.
Segmentation dimensions modeled span product type, material composition, end-user category, and application across the analysis window. Radial versus retread versus bias specifications, natural rubber versus composite reinforcement tiers, commercial aviation versus cargo versus military demand, and replacement versus maintenance service revenue streams structured the analytical framework. CAGRs were derived from fleet expansion projections, landing cycle intensity assumptions, and tire life metrics calibrated against EASA-mandated inspection intervals.
Forecasts assume regulatory continuity in EASA certification protocols and REACH chemical compliance regimes; material policy shifts would require re-modeling. Specific risks include natural rubber supply disruption from Southeast Asian source regions, accelerated EU Green Deal lifecycle accountability mandates, and EASA retread approval timeline compression. Revision becomes warranted when retread volume penetration crosses thresholds triggering procurement contract renegotiation at major network carriers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Saudi Arabia Tire Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
Automotive 3D Printed Tires Market