
 Automotive Green Tires Market | 2026-2036
Automotive Green Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Green Tires Market Intelligence
ISO 14040 lifecycle assessment certification is collapsing the supplier base for European OEM qualification. Michelin Group leverages captive silica supply chains to secure raw material continuity. Bridgestone Corporation anchors its position through advanced tread design patents. Continental AG differentiates via polymer blending R&D intensity in German facilities.
Automotive green tires incorporate silica-enhanced compounds and natural rubber blends to reduce rolling resistance below conventional tires by optimizing hysteresis loss. Low rolling resistance tires now command premium positioning as fleet operators prioritize fuel economy compliance. Bio-based compound tires represent the fastest-growing product category as polymer blending technology matures. OEM channel access dominates margin pools compared with aftermarket distribution.
The EU Green Deal and REACH chemical restrictions constrain hydrocarbon oil plasticizer use in European tire production. EPA fuel economy standards and California's LCFS program shape North American product specifications. China's GB standards and dual carbon goals enforce domestic manufacturing emission ceilings. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
The EU Green Deal's embedded carbon rules are compressing allowable lifecycle emissions for tire imports, forcing manufacturers to requalify supply chains around ISO 14040 certification. This regulatory compression is restructuring competitive access to European OEM channels.
Growth Catalysts
- REACH chemical restrictions:Hydrocarbon oil plasticizer bans in European tire production are accelerating silica-enhanced compound adoption among domestic manufacturers seeking compliance advantage.
- Fleet operator fuel economy compliance:Commercial vehicle procurement departments in Germany and Japan are mandating low rolling resistance specifications in new tire contracts.
- Jiangsu and Shandong manufacturing clusters:Concentrated domestic capacity expansion in China's eastern provinces is driving export cost competitiveness for bio-based compound tires.
Market Restraints
- Natural rubber price volatility:Southeast Asian latex supply disruptions and climate-induced harvest variability are compressing margin predictability for bio-based blend producers.
- Silica supplier concentration:Captive supply chains controlled by integrated tire-silica conglomerates are limiting raw material access for independent compounders in Europe.
- GB standards enforcement lag:China's dual carbon emission ceilings for domestic manufacturing remain inconsistently applied across provincial jurisdictions, creating competitive distortion.
Strategic Opportunities
- California LCFS program expansion:Carbon credit monetization for low rolling resistance tire penetration in heavy-duty fleet retrofits is creating new revenue streams for qualifying products.
- Polymer blending R&D convergence:Integration of advanced tread design simulation with bio-based compound formulation is enabling next-generation hysteresis optimization.
- Aftermarket channel digitization:Direct-to-fleet e-procurement platforms are disintermediating traditional wholesale distribution in North American commercial vehicle segments.
Industry Challenges
- ISO 14040 certification timeline compression:European OEM qualification windows are narrowing faster than third-party assessor capacity can accommodate, creating backlog risk for suppliers.
- Polymer blending talent scarcity:Cross-functional expertise spanning materials science, regulatory compliance, and automotive engineering commands premium compensation and constrains R&D scaling.
- Legacy ERP integration friction:Carbon accounting module deployment across multi-tier supply chains requires substantial capex and disrupts existing procurement workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Green Tires Market |
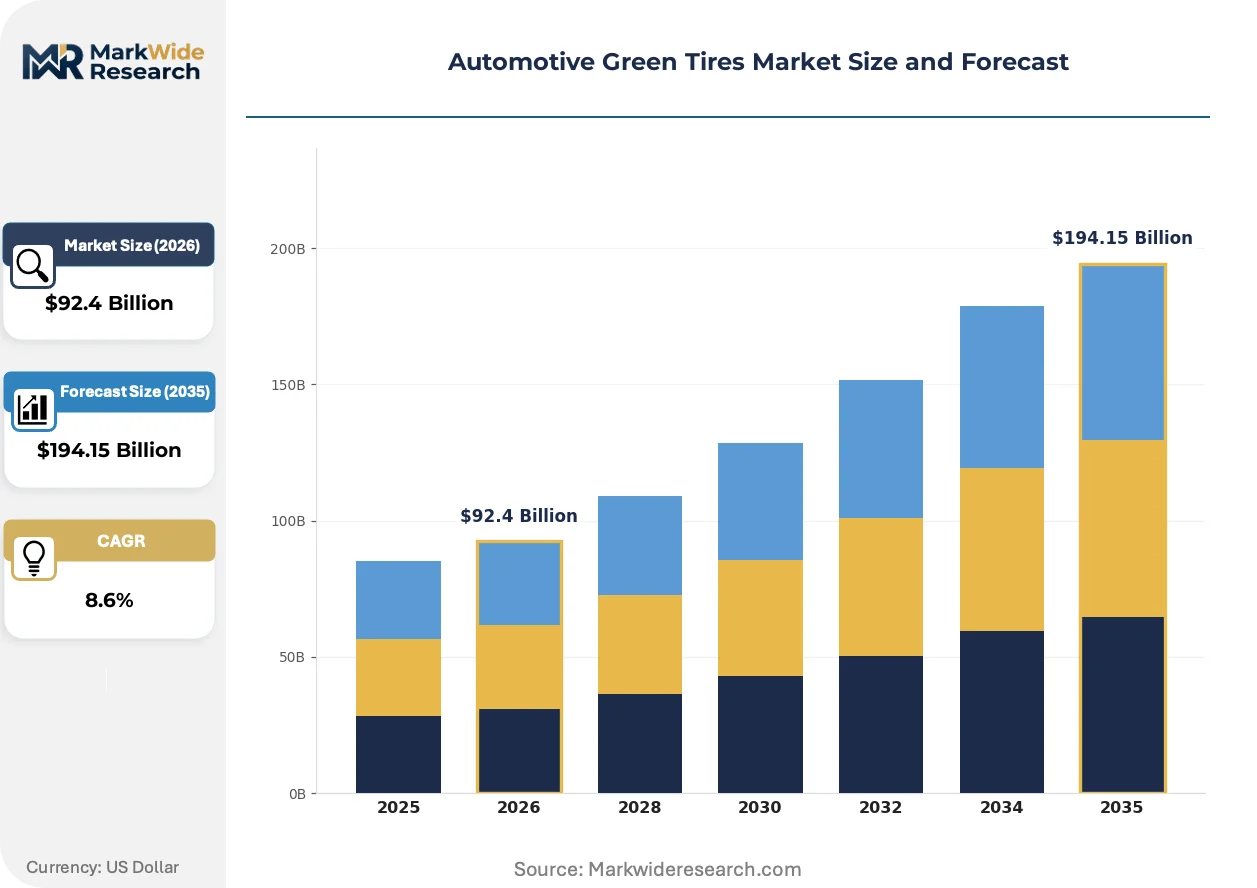
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $194.15 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eco-Friendly Rubber Tires, Recycled Material Tires, Low Rolling Resistance Tires, Bio-Based Compound Tires Technology: Silica Enhancement, Natural Rubber Reinforcement, Polymer Blending, Advanced Tread Designs Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Off-Road Vehicles, Agricultural Machinery End User: OEMs, Aftermarket Suppliers, Fleet Operators, Tire Retreaders |
| Companies Covered | Michelin Group, Bridgestone Corporation, Continental AG, The Goodyear Tire & Rubber Company, Pirelli & C. S.p.A., Hankook Tire & Technology, Sumitomo Rubber Industries Ltd., Nokian Tyres plc, Toyo Tire Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Green Tires Market Strategic Shifts & Innovations
Silica-enhanced compound technology is actively restructuring raw material sourcing patterns and manufacturing process flows across tire production networks. Three concurrent developments are compressing traditional competitive positions.
Advanced solution-polymerized styrene-butadiene rubber (SSBR) formulations are supplanting conventional emulsion-SBR in premium tire segments. Passenger vehicle OEMs in Germany and Japan are accelerating procurement of SSBR-dominant compounds for original equipment fitment. This material transition is enabling hysteresis loss reduction below 0.15 coefficient thresholds previously unattainable with legacy polymer systems.
REACH chemical restrictions on polycyclic aromatic hydrocarbons in tire oils are forcing reformulation of plasticizer packages across European production facilities. The industrial consequence is accelerated R&D investment in bio-based process oil alternatives derived from tall oil fatty acids. Tread compound suppliers serving German OEM channels are most affected, with several facilities completing qualification trials ahead of enforcement deadlines.
Fleet procurement departments are consolidating tire specifications around total cost-of-ownership metrics rather than upfront unit pricing. This behavioral shift is disrupting traditional aftermarket wholesale relationships and elevating direct manufacturer-fleet contracting. The pattern is most visible in North American heavy-duty trucking segments, where EPA fuel economy standards have made rolling resistance performance a contract-tiering criterion.
Automotive Green Tires Market Segmentation
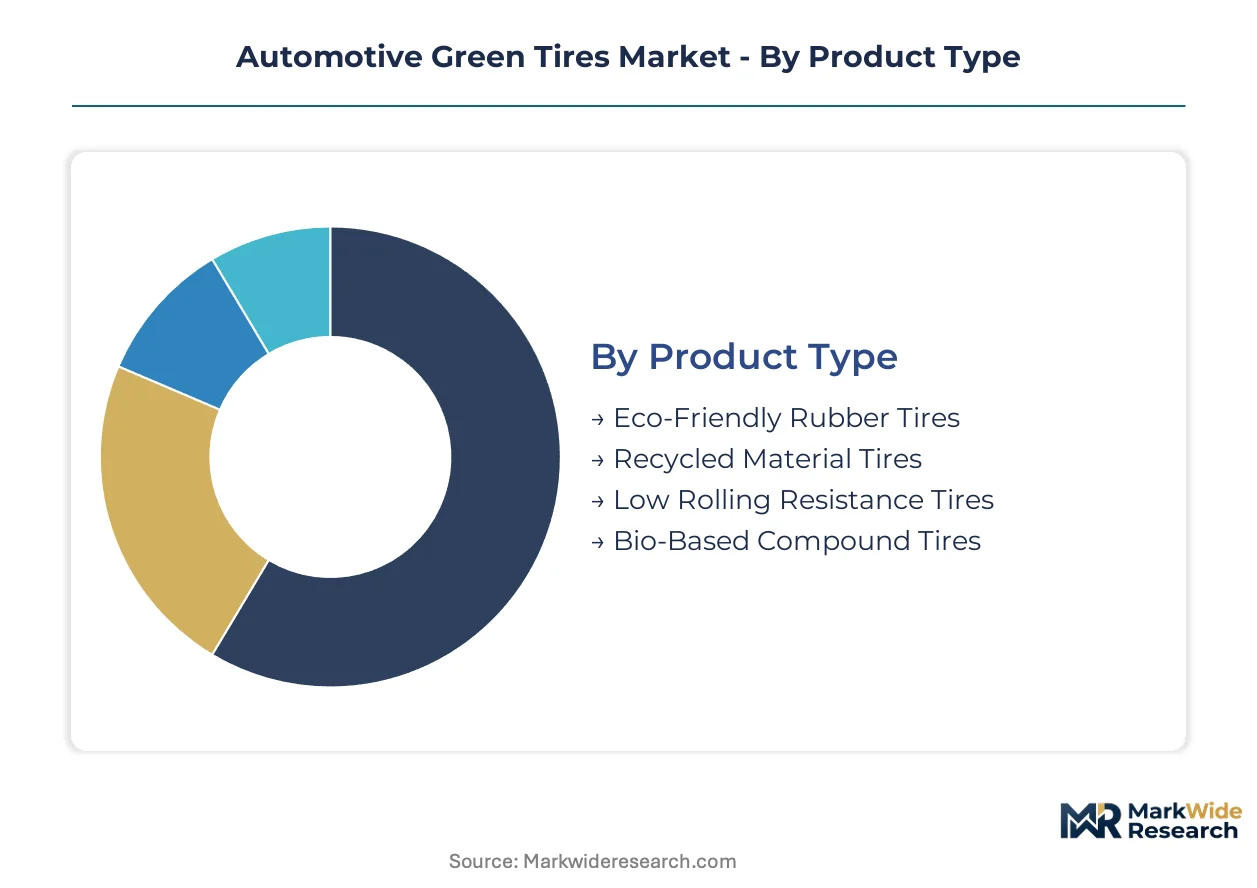
Segmentation in automotive green tires reveals how regulatory pressure and material substitution reshape procurement patterns across product categories. Understanding these divisions exposes where margin pools concentrate and which technologies face displacement risk from next-generation compounds.
Product Type:
Substitution pressure from bio-based alternatives is compressing demand for conventional eco-friendly formulations, with fleet operators and OEMs requalifying specifications around lifecycle carbon metrics.
- Eco-Friendly Rubber Tires:Conventional formulations incorporating modest recycled content and reduced aromatic oils. Demand concentrates in European aftermarket channels where REACH compliance creates baseline entry requirements, though margin compression from bio-based alternatives limits growth.
- Recycled Material Tires:Compounds integrating ground tire rubber and reclaimed carbon black at 15-30% content ratios. Procurement from German passenger vehicle OEMs is accelerating as embedded carbon rules under the EU Green Deal tighten import qualification thresholds.
- Low Rolling Resistance Tires:Silica-dominant tread compounds optimizing hysteresis loss below 0.20 coefficients.
- Bio-Based Compound Tires:Natural rubber and tall oil-derived plasticizer formulations replacing petroleum-based process oils.
Low rolling resistance tires anchor the volume base while bio-based compound tires gain share at the steepest rate.
Technology:
Cost tier stratification separates premium R&D-intensive methods from commoditized processes, with polymer blending commanding the highest qualification barriers for European OEM access.
- Silica Enhancement:Precipitated silica loadings above 80 parts per hundred rubber replacing carbon black in tread compounds. Jiangsu and Shandong manufacturing clusters in China are expanding precipitated silica capacity to serve export demand from Japanese OEMs seeking supply chain redundancy.
- Polymer Blending:Solution-polymerized styrene-butadiene rubber (SSBR) and bio-based elastomer co-formulation. German R&D facilities are concentrating SSBR expertise as the primary differentiator for qualifying supply to domestic passenger vehicle manufacturers.
- Natural Rubber Reinforcement:High-cis polyisoprene integration for reduced heat buildup in heavy-duty applications.
- Advanced Tread Designs:Simulation-optimized patterns reducing contact patch deformation.
Silica enhancement dominates current production volumes while polymer blending commands the premium tier expansion trajectory.
Application:
Customer type fragmentation splits the market between specification-heavy OEM contracts and price-sensitive replacement cycles, with fleet procurement consolidation disrupting traditional wholesale channels.
- Passenger Vehicles:Original equipment fitment requiring ISO 14040 certification and sub-0.15 rolling resistance coefficients. German and Japanese OEM procurement departments are mandating bio-based content minimums in new tire supply agreements.
- Commercial Trucks:Heavy-duty specifications prioritizing total cost-of-ownership over upfront unit pricing. California LCFS program participation is enabling carbon credit monetization for low rolling resistance retrofits in North American fleet operations.
- Two-Wheelers:High-volume, price-sensitive replacement demand concentrated in Asian urban markets.
- Off-Road Vehicles:Durability-focused compounds tolerating higher hysteresis loss for traction performance.
- Agricultural Machinery:Flotation tire designs minimizing soil compaction with moderate rolling resistance requirements.
Passenger vehicles generate the largest revenue pool while commercial trucks show the most rapid specification upgrading.
End User:
Supply concentration among integrated tire-silica conglomerates is constraining raw material access for independent compounders, reshaping competitive dynamics across procurement channels.
- OEMs:Direct manufacturer relationships with multi-year qualification cycles and embedded carbon auditing. The EU Green Deal's lifecycle emission rules are compressing allowable thresholds for tire imports faster than third-party assessor capacity can accommodate.
- Fleet Operators:Consolidated procurement departments mandating fuel economy compliance metrics in contract tiering. North American heavy-duty trucking segments are adopting direct-to-fleet e-procurement platforms that disintermediate traditional wholesale distribution.
- Aftermarket Suppliers:Fragmented wholesale and retail channels serving replacement demand.
- Tire Retreaders:Secondary processors extending casing life for commercial vehicle applications.
OEMs command the premium margin tier while fleet operators are expanding the fastest as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal embedded carbon rules are compressing lifecycle emission thresholds for tire imports faster than supplier requalification timelines can accommodate. German and Japanese passenger vehicle OEMs are accelerating procurement of low rolling resistance specifications. Manufacturing capacity is concentrating in China's eastern provinces as domestic dual carbon goals reshape export competitiveness.
Germany
Passenger vehicle OEM procurement departments in Stuttgart and Munich are mandating bio-based content minimums in new tire supply agreements. REACH chemical restrictions on polycyclic aromatic hydrocarbons in tire oils are forcing reformulation of plasticizer packages across domestic production facilities. The Baden-Württemberg polymer blending R&D corridor is concentrating SSBR expertise as the primary qualification differentiator for European OEM access.
China
Jiangsu and Shandong manufacturing clusters are expanding precipitated silica capacity to serve export demand from Japanese OEMs seeking supply chain redundancy. GB standards and dual carbon goals enforce domestic manufacturing emission ceilings, though enforcement remains inconsistently applied across provincial jurisdictions. Qingdao-based tire compounders are driving export cost competitiveness for bio-based formulations through concentrated capacity scaling.
United States
California LCFS program participation is enabling carbon credit monetization for low rolling resistance tire penetration in heavy-duty fleet retrofits. EPA fuel economy standards are shaping North American product specifications as commercial vehicle procurement departments consolidate around total cost-of-ownership metrics. The Southeast manufacturing belt is attracting compound blending investments to serve domestic OEM channels.
Japan
METI efficiency standards are accelerating OEM adoption of silica-dominant tread compounds optimizing hysteresis loss below 0.15 coefficients. Passenger vehicle manufacturers in Toyota City and Hiroshima are requalifying specifications around lifecycle carbon metrics ahead of export market access requirements. The Kanto region is anchoring advanced solution-polymerized styrene-butadiene rubber formulation expertise for premium tire segments.
Automotive Green Tires Market Key Industry Players
Player mix skews toward integrated tire-silica conglomerates with captive raw material supply chains. Tiered competitive structure separates premium R&D-intensive compounders from scale-driven manufacturers serving price-sensitive aftermarket channels. Strategic archetypes include backward-integrated material specialists, polymer blending technology leaders, and fleet-direct contract specialists. Dominant competitive moves center on silica supply chain control and direct-to-fleet e-procurement platform deployment.
Within the integrated conglomerate tier, Michelin Group, Bridgestone Corporation, and Continental AG exemplify archetypes defined by captive supply chain configuration and regional R&D concentration. The French limited company represents material-integrated positioning through silica supply chain control. The Japanese corporation anchors advanced tread design patent portfolios. The German Aktiengesellschaft occupies the polymer blending technology leader position through German facility R&D intensity. These three entities collectively illustrate how geographic origin and corporate structure map to competitive archetype differentiation in European OEM qualification channels.
| Leading Market Players |
|---|
| Michelin Group |
| Bridgestone Corporation |
| Continental AG |
| The Goodyear Tire & Rubber Company |
| Pirelli & C. S.p.A. |
| Hankook Tire & Technology |
| Sumitomo Rubber Industries Ltd. |
| Nokian Tyres plc |
| Toyo Tire Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Japanese OEMs and Jiangsu silica producers lock in both raw material access and cost visibility across volatile commodity cycles. These agreements compress spot market participation for independent compounders while embedding REACH compliance premiums into European supply tiers.
Pricing Analysis
Certification level creates the primary spread between supply tiers, with ISO 14040-qualified compounds commanding substantial premiums over uncertified alternatives. Contract-based long-term offtake dominates OEM channels, while aftermarket transactions retain spot-market flexibility. Price differentiation hinges on embedded carbon audit depth and bio-based content ratios. Pricing pressure stems from Southeast Asian natural rubber harvest variability, which squeezes margin predictability for blend producers. Fleet operators show the least price sensitivity due to total cost-of-ownership procurement frameworks, whereas Asian two-wheeler replacement channels remain highly elastic.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for precipitated silica shipments. Supply concentrates in China, Thailand, and Germany, with Jiangsu and Shandong clusters anchoring global precipitated silica capacity. Raw material sourcing draws from Southeast Asian latex plantations, Qatari petroleum feedstocks for synthetic rubber, and Nordic tall oil derivatives for bio-based plasticizers. Single-source vulnerability around captive silica supply chains controlled by integrated conglomerates constrains independent compounder access. Distribution runs through direct manufacturer-fleet platforms in North America and tiered wholesale networks in European aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal embedded carbon rules are compressing qualification timelines faster than supplier requalification capacity can accommodate, creating a high-growth disruption window for certified compound producers.
For Market Incumbents: Consolidate silica supply chain control through backward integration into precipitated capacity or exclusive offtake arrangements with Jiangsu producers. Deepen polymer blending R&D investment in German facilities to defend OEM qualification positioning against emerging SSBR specialists. Lock in multi-year fleet-direct contracts before aftermarket digitization accelerates channel disintermediation. For New Entrants and Emerging Players: ISO 14040 fast-track certification programs offer the most penetrable entry vector for European OEM channel access. Target California LCFS carbon credit monetization as a white-space revenue stream for heavy-duty fleet retrofit specifications. Pursue bio-based compound formulation partnerships with Qingdao-based manufacturers to bypass captive silica constraints. For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors material-integrated compounders with captive supply chains. Long-term viability centers on five-to-ten-year embedded carbon rule convergence across major import jurisdictions. Acquisition archetypes include independent SSBR formulation specialists and direct-to-fleet platform operators. Monitor third-party assessor capacity expansion as the critical signal for qualification bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Production | Captive precipitated capacity secures raw material continuity against REACH-driven supply compression. |
| ISO 14040 Certification Fast-Track | Accelerated lifecycle assessment qualification unlocks German and Japanese OEM procurement channels. |
| Fleet-Direct E-Procurement Platform | Direct contracting with North American heavy-duty operators disintermediates wholesale margin erosion. |
| SSBR Polymer Blending R&D Expansion | Solution-polymerized expertise in Baden-Württemberg facilities differentiates hysteresis performance tiers. |
| Bio-Based Plasticizer Formulation Partnership | Tall oil derivative integration replaces hydrocarbon oils ahead of EU Green Deal enforcement deadlines. |
Research Approach
Desk research of customs trade databases, ECHA regulatory filings, and tire industry association capacity reports preceded structured interviews with OEM procurement directors, compound R&D leads, and fleet operations managers. Primary fieldwork captured qualification timeline dynamics and procurement specification evolution across German, Japanese, and North American channels. Secondary validation drew from SEC filings of integrated tire-silica conglomerates, METI efficiency standard disclosures, and California Air Resources Board LCFS program data. Bottom-up capacity modeling and top-down demand segmentation were triangulated to reconcile volume estimates.
Variance decomposition across product type, technology tier, application segment, and end-user channel shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled dimensions included silica loading ratios, bio-based content minimums, and regional regulatory cluster stringency. Forecast inputs incorporated fleet operator fuel economy compliance deadlines and OEM platform electrification roadmaps without specific year anchoring.
Underlying assumptions cover sustained REACH enforcement trajectory and consistent GB standards provincial application, with deviation risk concentrated in natural rubber harvest variability and third-party assessor capacity constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Global Automotive Tire Inflator Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
Tire Changers Market