
 Tire & Wheel Cleaners Market | 2026-2036
Tire & Wheel Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Tire & Wheel Cleaners Market Insights
Market Context
Biodegradable surfactant systems are recalibrating product economics as petroleum-derived solvents face escalating compliance costs. Meguiar's Inc. leverages its professional-grade heritage to anchor the premium detailing channel with concentrated formulations. Mothers Polishes Waxes Cleaners competes through heritage brand equity and enthusiast-community loyalty. 3M sustains industrial-grade credibility with fleet and aviation maintenance accounts requiring certified performance documentation.
Technical Definition and Segment Structure
Tire and wheel cleaners comprise aqueous or solvent-based formulations engineered to dissolve brake dust, road film, and oxidized rubber residue through alkaline builders, chelating agents, or acid-based mineral dissolvers, typically applied via spray, brush, or wipe methods prior to protective dressing. The product category serves automotive aftermarket maintenance, professional detailing, and industrial fleet operations where wheel corrosion prevention extends component service life. Liquid formats dominate volume throughput due to dilution economics and refill-system compatibility, while aerosol delivery captures convenience-driven residential and commercial segments with ready-to-use positioning. The application split reveals automotive as the mature volume anchor, whereas commercial sub-segments including rental fleet operators and logistics hubs represent the fastest-growing demand pool. Packaging innovation concentrates in pouches and concentrated bottles as sustainability mandates reduce single-use plastic intensity across European and North American retail channels.
Regulatory Frame and Outlook
EPA Safer Choice certification and REACH Annex XVII restrictions on volatile organic compounds are reshaping permissible ingredient profiles, compelling manufacturers to disclose full material compositions and toxicity screening data. California's Air Resources Board (CARB) consumer products regulations impose the strictest VOC ceilings in the United States, effectively setting the compliance benchmark for national formulation strategies. OSHA hazard communication standards govern professional-use labeling and workplace exposure thresholds for concentrated alkaline and acid-based products. Stakeholders must monitor evolving state-level chemical disclosure laws and biobased content mandates to anticipate reformulation timelines and raw material sourcing requirements.
Market Dynamics
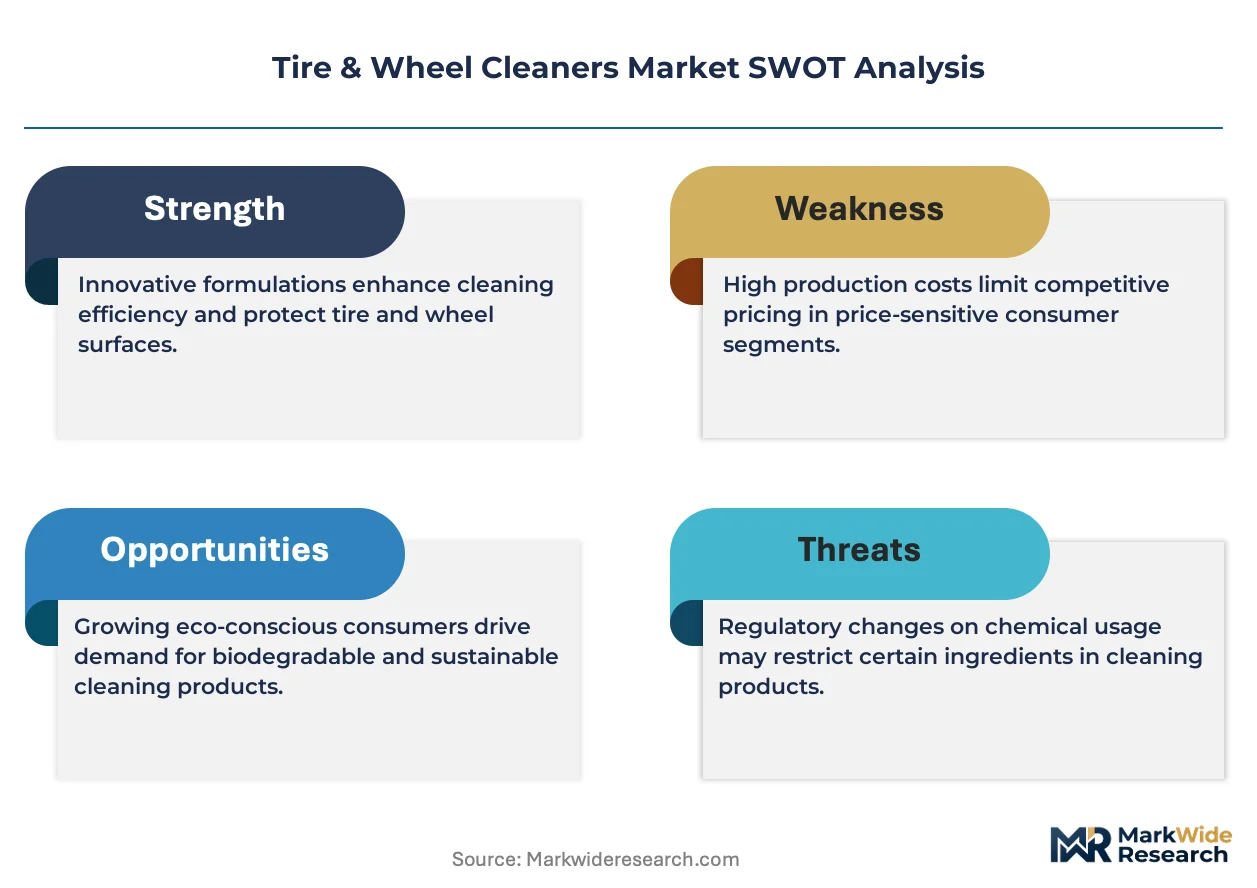
Biodegradable surfactant systems are recalibrating product economics as petroleum-derived solvents face escalating compliance costs from EPA Safer Choice and REACH Annex XVII thresholds. Fleet operators and ride-share platforms are institutionalizing wheel maintenance protocols, creating concentrated demand pull from commercial accounts.
Growth Catalysts
- EPA Safer Choice certification:Biodegradable surfactant systems gain preferential shelf placement at major retailers as solvent-based formulations face delisting pressure.
- Ride-share fleet standardization:Uber and Lyft driver cooperatives mandate weekly wheel maintenance, creating recurring volume anchors in the commercial segment.
- Aviation maintenance protocols:FAA-approved wheel corrosion prevention programs extend component service life, driving specification-grade cleaner adoption.
Market Restraints
- Petroleum-derived solvent volatility:Crude oil price swings compress margin predictability for manufacturers maintaining legacy alkaline formulations.
- REACH Annex XVII compliance timelines:European reformulation deadlines force simultaneous R&D and registration expenditures without guaranteed market retention.
- Waterless cleaning wipes:Convenience-oriented substitutes capture quick-clean occasions from residential buyers seeking spray-free application.
Strategic Opportunities
- India logistics hub expansion:Delhi-Mumbai Industrial Corridor fleet operators lack established maintenance suppliers, creating first-mover positioning for concentrate systems.
- California Air Resources Board zero-VOC pathway:CARB-compliant formulations receive automatic qualification for state procurement contracts.
- Refill pouch infrastructure:Concentrate-to-dilution systems reduce plastic intensity while locking buyers into recurring concentrate purchases.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in chelating agent stability across pH ranges commands premium compensation, constraining R&D throughput.
- Safer Choice certification timelines:EPA toxicity screening protocols extend product launch windows by 14-18 months versus conventional registration.
Report Scope
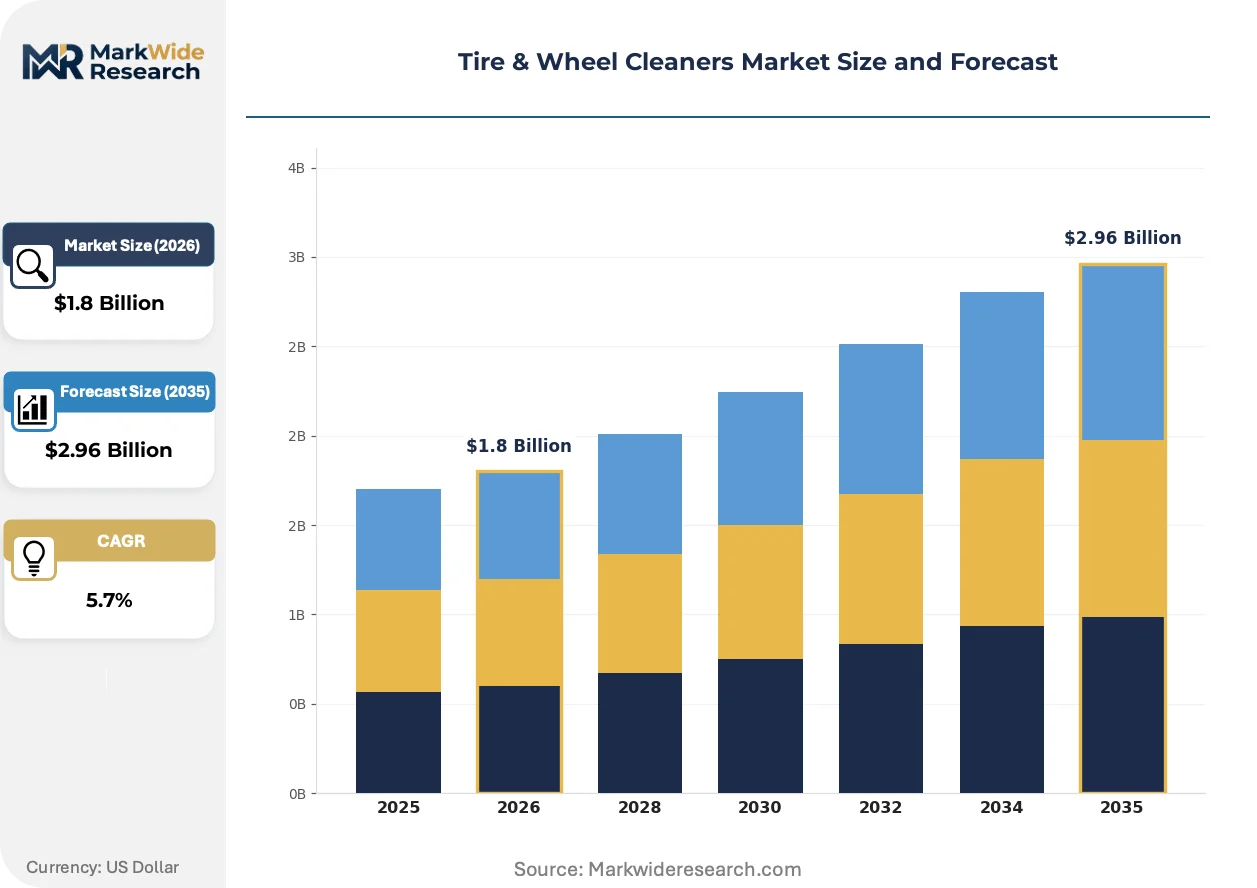
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire & Wheel Cleaners Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Liquid, Gel, Wipes Application: Residential, Commercial, Automotive, Industrial Packaging Type: Bottles, Buckets, Pouches, Canisters Distribution Channel: Online Retail, Supermarkets, Automotive Stores, Wholesale |
| Companies Covered | Meguiar's Inc., Armor All, MUC-OFF, Mothers Polishes Waxes Cleaners, Eagle One, Black Magic, Autoglym, Polishes Waxes Cleaners, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire & Wheel Cleaners Market Trends and Innovations
Formulation chemistry, regulatory disclosure requirements, and procurement centralization are converging to reshape competitive positioning. Technology providers and chemical suppliers must align innovation roadmaps with compliance trajectories.
Enzymatic brake dust digesters are decentralizing cleaning efficacy from high-pH alkaline systems. Professional detailing chains in Germany and the Netherlands pilot bio-catalytic formulations that operate at neutral pH. This technology is decentralizing the historical trade-off between cleaning power and wheel finish safety.
REACH Annex XVII restrictions on volatile organic compounds are forcing full material composition disclosure. European manufacturers must submit toxicity screening data for every ingredient above 0.1% concentration. Professional-grade concentrates face the steepest reformulation burden, as legacy solvent carriers fall outside permissible thresholds.
Fleet procurement offices now mandate certified performance documentation for wheel maintenance chemicals. Rental car operators and logistics hubs issue specification sheets requiring brake dust removal percentages and corrosion inhibition ratings. This pattern is most visible in the United States, where enterprise buyers consolidate supplier relationships around documented efficacy metrics.
Tire & Wheel Cleaners Market Segmentation
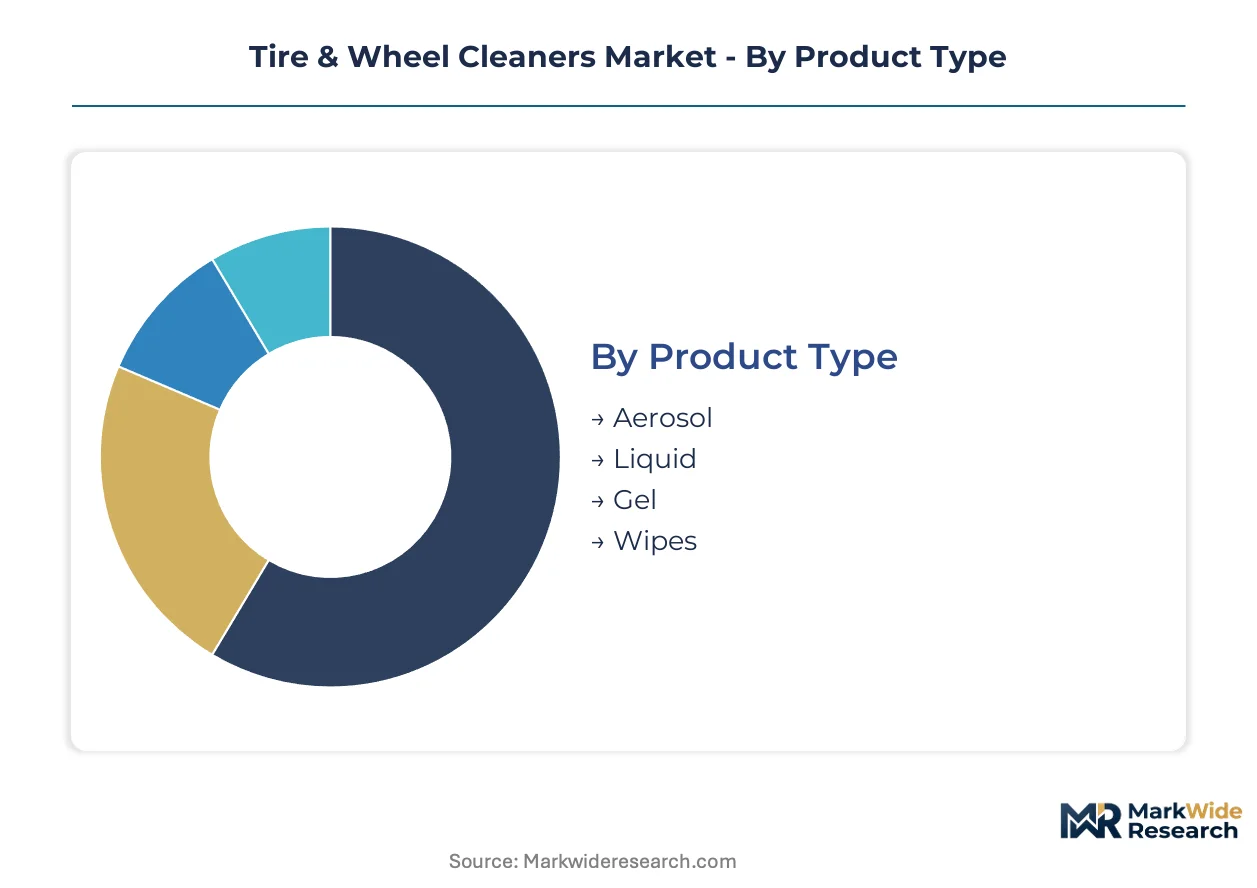
Product format, application context, and procurement channel each impose distinct formulation requirements and margin structures in tire and wheel cleaners. Segmentation clarity enables suppliers to align R&D investment with the compliance and performance thresholds that govern buyer selection.
Product Type:
Application method dictates solvent concentration, dwell time requirements, and safety labeling obligations for end-users.
- Liquid:Concentrated alkaline and acid-based formulations dominate professional detailing and fleet maintenance channels due to dilution economics and bulk refill compatibility. Demand concentrates in United States commercial accounts where OSHA hazard communication standards govern workplace exposure thresholds for high-pH systems.
- Aerosol:Ready-to-use solvent carriers capture residential convenience buyers and quick-service commercial applications requiring minimal equipment investment. California Air Resources Board VOC ceilings force reformulation toward compressed air or pump-spray alternatives in West Coast distribution.
- Gel:Thickened surfactant systems cling to vertical wheel surfaces during extended dwell periods for heavy brake dust accumulation. Preferred by enthusiast detailers seeking controlled application without runoff.
- Wipes:Pre-saturated substrates target ride-share drivers and fleet operators prioritizing speed over deep cleaning efficacy. Waterless positioning competes with spray formats for quick-clean occasions.
Liquid leads on scale; aerosol leads on momentum as VOC regulations compress solvent-based alternatives.
Application:
End-use environment determines corrosion risk exposure, maintenance frequency, and specification documentation requirements.
- Commercial:Rental fleet operators and logistics hubs mandate certified brake dust removal percentages and corrosion inhibition ratings in procurement specifications. United States enterprise buyers consolidate supplier relationships around documented performance metrics and recurring volume commitments.
- Automotive:Original equipment service channels and aftermarket retailers sustain mature volume through seasonal promotional cycles and bundled car care assortments. EPA Safer Choice certification increasingly influences shelf placement decisions at major retailers.
- Residential:Enthusiast communities drive premium concentrate adoption through heritage brand loyalty and online tutorial influence. Price sensitivity constrains penetration of professional-grade alkaline systems.
- Industrial:Aviation maintenance and heavy equipment operations require FAA-approved or manufacturer-certified formulations extending component service life. Specification-grade documentation creates high switching costs for incumbent suppliers.
Automotive leads on scale; commercial leads on momentum as fleet procurement centralization accelerates.
Packaging Type:
Sustainability mandates and dilution economics reshape material selection across retail and professional channels.
- Pouches:Flexible concentrate refills reduce single-use plastic intensity by 60-80% versus conventional bottles while locking buyers into recurring purchases. European REACH compliance timelines accelerate adoption in Germany and Netherlands retail channels.
- Bottles:HDPE and PET containers dominate residential spray-and-wipe applications with trigger-spray or flip-cap dispensing. Concentrate bottles with measurement dosing capture professional dilution workflows.
- Buckets:Institutional and fleet volumes utilize pail packaging for high-throughput dilution stations and automated wash systems. Closed-loop refill infrastructure reduces per-use packaging cost.
- Canisters:Wet wipe substrates require moisture-barrier packaging preserving surfactant stability through distribution. Compact footprint suits glove compartment and mobile detailer storage.
Bottles lead on scale; pouches lead on momentum as plastic reduction mandates tighten.
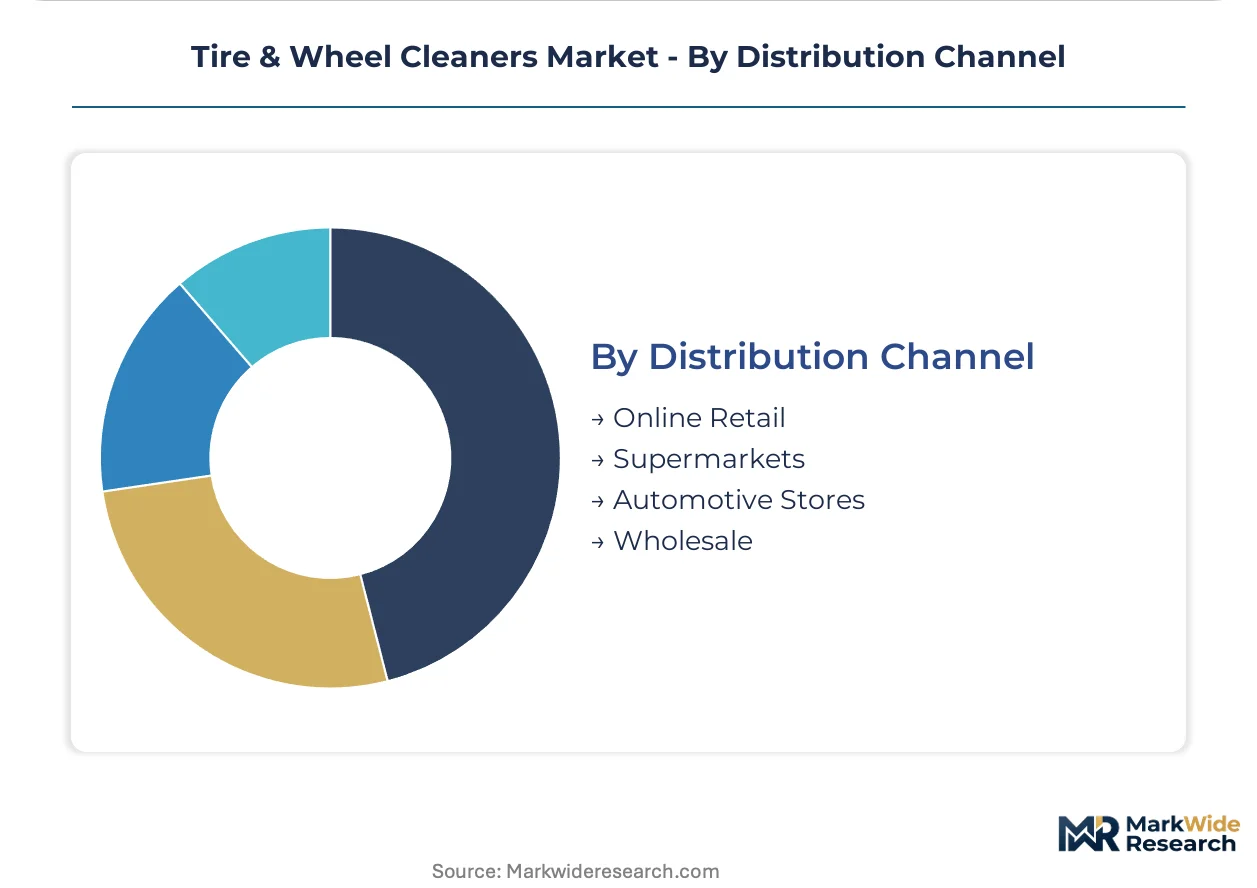
Distribution Channel:
Channel selection governs margin structure, brand positioning, and technical support obligations.
- Automotive Stores:Specialty retailers anchor enthusiast and professional-grade volume through trained counter staff and application guidance. United States chains like AutoZone and O'Reilly sustain above-average category velocity through private label and national brand assortment depth.
- Wholesale:Industrial distributors and fleet supply houses manage specification compliance documentation and bulk pricing for enterprise accounts. Technical field support differentiates incumbent suppliers from commodity entrants.
- Online Retail:Amazon and direct-to-consumer platforms concentrate review-driven residential purchases and subscription concentrate refills. Search visibility and influencer affiliation determine new brand discovery.
- Supermarkets:Mass retail placement captures impulse and seasonal car care purchases through end-cap displays and promotional pricing. Limited shelf space favors established heritage brands with consumer recognition.
Automotive stores lead on scale; wholesale leads on momentum as fleet procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive manufacturing corridor anchors tire and wheel cleaner demand through captive fleet maintenance operations and tier-one supplier detailing protocols. Professional auto detailing services in Michigan, Ohio, and Indiana institutionalize weekly wheel maintenance schedules for corporate vehicle pools. The EPA's Safer Choice program and state-level VOC regulations fragment compliance requirements across domestic markets.
United States
Ride-share fleet operators in California and Texas mandate standardized wheel maintenance protocols, creating recurring commercial volume anchors. The California Air Resources Board imposes the strictest VOC ceilings nationally, forcing reformulation toward compressed air delivery systems. Chicago's logistics hub concentrates demand from rental fleet operators requiring certified brake dust removal documentation.
Germany
Professional detailing chains in Bavaria and Baden-Württemberg pilot enzymatic brake dust digesters operating at neutral pH. REACH Annex XVII restrictions compel full material composition disclosure for every ingredient above threshold concentrations. Stuttgart's automotive engineering cluster drives specification-grade cleaner adoption through manufacturer-certified maintenance programs.
China
Logistics fleet expansion along the Beijing-Tianjin-Hebei corridor generates concentrated demand for industrial-grade wheel corrosion prevention. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate biodegradable surfactant adoption in chemical formulations. Shanghai's Yangtze River Delta manufacturing belt hosts domestic concentrate producers targeting commercial vehicle maintenance depots.
India
Delhi-Mumbai Industrial Corridor fleet operators lack established maintenance suppliers, creating first-mover positioning opportunities for concentrate systems. The Bureau of Indian Standards implements phased chemical disclosure requirements aligned with international norms. Maharashtra's automotive component manufacturing zones drive specification documentation demands from export-oriented suppliers.
United Kingdom
London's ride-share driver cooperatives institutionalize weekly wheel maintenance through mobile detailing networks. The Health and Safety Executive governs workplace exposure thresholds for professional-grade alkaline formulations. Birmingham's West Midlands automotive cluster sustains heritage brand distribution through specialist retailer channels.
Tire & Wheel Cleaners Market Competitive Landscape
Portfolio diversification dominates the current landscape as heritage automotive care brands extend into adjacent surface protection categories. The vendor base organizes around three strategic archetypes: professional-grade concentrate specialists, mass-market convenience format providers, and industrial specification-grade suppliers. M&A activity concentrates among mid-cap heritage brands seeking geographic footprint expansion. Technology licensing partnerships accelerate enzymatic formulation deployment without captive R&D investment.
Among heritage automotive care specialists, Meguiar's Inc., Mothers Polishes Waxes Cleaners, and 3M occupy distinct positioning tiers. Meguiar's exemplifies the professional-grade heritage archetype through concentrated formulation credibility. Mothers represents enthusiast-community loyalty and heritage brand equity in residential channels. 3M anchors the industrial specification tier with certified performance documentation for fleet and aviation maintenance accounts.
| Leading Market Players |
|---|
| Meguiar's Inc. |
| Armor All |
| MUC-OFF |
| Mothers Polishes Waxes Cleaners |
| Eagle One |
| Black Magic |
| Autoglym |
| Polishes Waxes Cleaners |
| 3M |
| Others |
Pricing and Supply Chain Analysis
Specialized formulation chemists concentrated in Germany and the United States command premium compensation that directly widens spreads between professional-grade concentrates and economy-tier alternatives. Labor-cost differentials between these technical hubs and emerging formulation centers in India and China shape tiered pricing architectures across export markets.
Pricing Analysis
Input-cost pass-through from petroleum-derived solvent volatility and chelating agent price swings compresses margin predictability for legacy alkaline formulations. Pricing stratifies across EPA Safer Choice-certified premium tiers, standard professional concentrates, and economy residential sprays. Cost compression in solvent-based tiers is intensifying because REACH Annex XVII compliance forces simultaneous R&D and registration expenditures. Fleet procurement offices exhibit the lowest price sensitivity due to specification-grade documentation requirements, while residential buyers concentrate price elasticity in mass-market spray formats.
Supply Chain Analysis
Certification gating through EPA Safer Choice and REACH Annex XVII restricts supplier qualification to manufacturers with full toxicity screening infrastructure. Raw material sourcing concentrates in Germany, the United States, and China for chelating agents, biodegradable surfactant feedstocks, and corrosion inhibitor compounds. Formulation chemistry rests on specialty chemical inputs including ethylenediaminetetraacetic acid derivatives, alkyl polyglucosides, and quaternary ammonium compounds. Single-source vulnerability persists in enzymatic brake dust digester bio-catalyst supply. Distribution runs through automotive specialty retailers, industrial fleet supply houses, and direct-to-consumer platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Safer Choice certification timelines and REACH Annex XVII reformulation deadlines perpetually reshape competitive viability. CARB zero-VOC pathways in California create automatic procurement qualification advantages that compound over successive compliance cycles.
For Market Incumbents: Deploy enzymatic formulation licensing partnerships to neutralize captive R&D investment burdens from legacy solvent reformulation. Deepen channel control through refill pouch infrastructure that locks fleet operators into recurring concentrate purchases. Meguiar's and 3M must accelerate bio-catalytic pilot programs in Germany and the Netherlands before professional detailing chains consolidate supplier relationships around neutral-pH alternatives. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting enthusiast communities with heritage-brand price positioning gaps. Concentrate white-space penetration on Delhi-Mumbai Industrial Corridor fleet operators lacking established maintenance suppliers. Prioritize concentrate-to-dilution systems with Bureau of Indian Standards disclosure alignment to capture first-mover procurement relationships before logistics hub consolidation accelerates. For Investors and Strategic Acquirers: Mid-cap heritage automotive care specialists are the most active acquirer in this space, seeking geographic footprint expansion through technology licensing rather than captive formulation development. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Acquisition targets should demonstrate EPA Safer Choice certification pipelines and enzymatic formulation partnerships. Monitor California Air Resources Board zero-VOC procurement contract awards as the inflection indicator for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Formulation Licensing | Bio-catalytic partnerships neutralize R&D burden while accelerating neutral-pH product pipelines. |
| Refill Pouch Infrastructure | Concentrate-to-dilution systems reduce plastic intensity and secure recurring fleet purchase commitments. |
| EPA Safer Choice Certification Investment | Certified formulations gain preferential shelf placement as solvent-based alternatives face delisting pressure. |
| India Logistics Hub First-Mover Positioning | Delhi-Mumbai corridor fleet operators lack established suppliers, creating procurement relationship opportunities. |
| CARB Zero-VOC Pathway Qualification | California-compliant formulations receive automatic state procurement contract eligibility. |
Research Methodology
Direct dialogue with formulation chemists, fleet procurement managers, professional detailing chain operators, and automotive specialty retail buyers grounded qualitative assessments in operational reality. Secondary validation drew from EPA Safer Choice certified product listings, REACH Annex XVII regulatory filings, California Air Resources Board consumer products databases, and automotive aftermarket trade association shipment data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to constrain variance bands.
Bottom-up modeling anchored volume projections in application-specific maintenance frequency assumptions and fleet penetration rates across commercial, automotive, residential, and industrial end-uses. Segmentation dimensions included product format, application context, packaging type, and distribution channel. CAGRs were derived from regression analysis against historical compliance-driven reformulation cycles and procurement centralization patterns. Industry-specific forecast inputs incorporated ride-share fleet standardization protocols and aviation maintenance specification adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH Annex XVII enforcement or petroleum price volatility spikes. A model refresh is warranted upon material change in EPA Safer Choice certification timelines or California Air Resources Board VOC ceiling revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Automotive Tire Socks Market
Tires and Wheels
Brazil Automotive Tire Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
All-Terrain Vehicle Tire Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Automotive All-Season Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Racing Tires Market