
 Performance Tires Market | 2026-2036
Performance Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Performance Tires Market Analytics
UNECE R117 wet-grip and rolling-resistance certification is redrawing supplier eligibility across European and Asian export channels. Michelin leverages its captive rubber plantation network to sustain compound consistency under volatile natural latex pricing. Bridgestone anchors its position through motorsport-derived tread technologies that transfer to road-legal performance lines. Continental AG differentiates via integrated sensor-embedded tire systems that bridge chassis dynamics with telemetry platforms.
Performance tires are speed-rated elastomeric assemblies engineered for sustained operation above 240 km/h, utilizing silica-reinforced tread compounds and aramid-reinforced sidewalls to balance hysteresis control with cornering stiffness. Their primary purpose is to translate high-output powertrains into predictable lateral grip and thermal stability under track-day and spirited road use. Summer tires dominate the value pool in Mediterranean and Middle Eastern climates where wet-weather compromise is acceptable, while all-season variants capture expanding share in temperate zones with irregular freeze-thaw patterns. Racing tires occupy the premium margin tier despite thin volume, subsidizing development amortization across homologated street products.
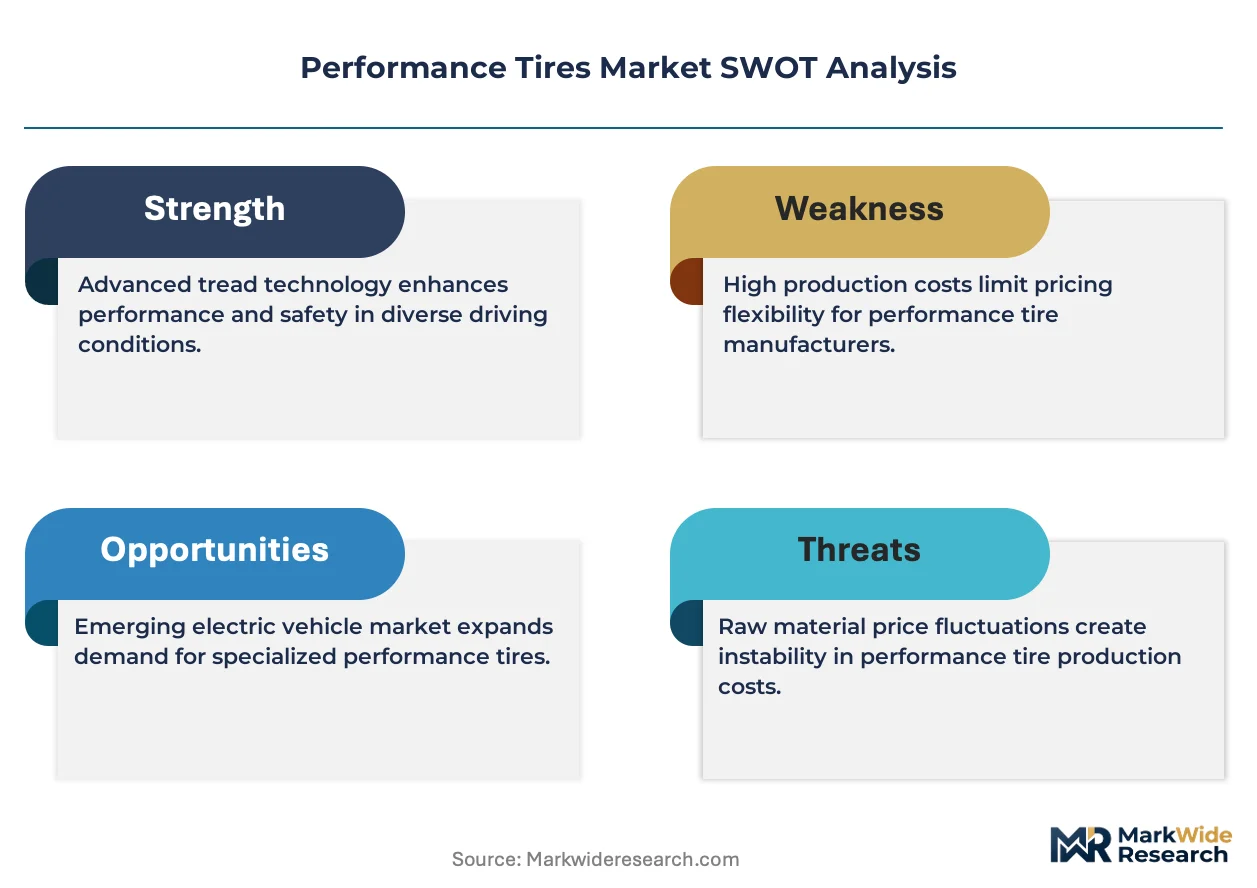
EPA fuel-economy labeling rules in the United States and EU tire-labeling regulations enforced by ECHA jointly pressure manufacturers to reduce rolling resistance without sacrificing AA-grade wet-braking scores. Japan's METI administers JIS D 4230 standards that govern minimum performance thresholds for domestic replacement markets. Stakeholders must monitor how battery-electric vehicle torque profiles and curb weights are rewriting load-index and wear-index assumptions baked into legacy homologation protocols.
Market Dynamics
Electric vehicle torque curves and mass redistribution are forcing compound reformulations that legacy load-index tables never anticipated. Track-day enthusiasts now demand tires certified for both Nürburring lap records and EPA range preservation.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating R&D investment in fluorine-free tread polymers that maintain wet-grip performance.
- Silica-reinforced compounds:Precipitated silica loadings above 70 phr enable simultaneous rolling-resistance reduction and AA wet-braking retention.
- Germany's Rhine-Ruhr cluster:Proximity to OEM development centers compresses homologation cycles from 18 months to under 12.
Market Restraints
- Natural latex volatility:Hevea brasiliensis supply concentration in Southeast Asia exposes compounders to El Niño-driven price spikes.
- Aramid fiber oligopoly:Three suppliers control para-aramid cordage for high-speed sidewall reinforcement.
- UNECE R117 revision lag:Pending updates to wet-grip testing protocols delay new product launches by 8-14 months.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced automotive components attract greenfield tire manufacturing.
- Sensor-embedded tires:Integration of pressure and temperature telemetry enables predictive maintenance contracts for fleet operators.
- All-season performance hybrids:M+S-rated compounds with summer-level dry grip capture temperate-zone drivers rejecting seasonal changeovers.
Industry Challenges
- Compounder talent scarcity:Expertise in silica-silane coupling chemistry is concentrated among retiring specialists.
- Homologation backlog:ECHA's tire-labeling verification queue extends certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performance Tires Market |
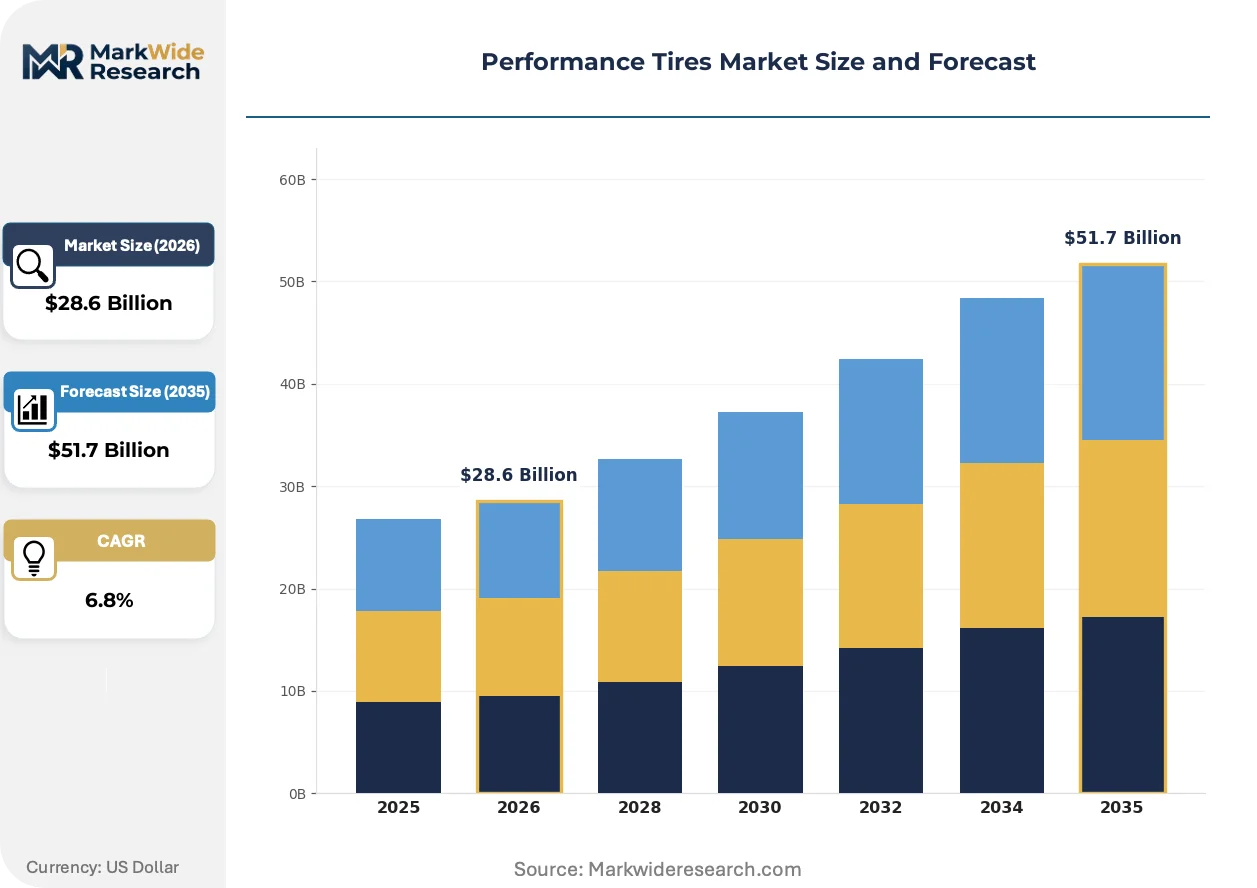
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Summer Tires, Winter Tires, All-Season Tires, Racing Tires Vehicle Type: Passenger Cars, SUVs, Light Trucks, Performance Vehicles Tread Design: Directional, Asymmetrical, Symmetrical, R-Factor Material: Natural Rubber, Synthetic Rubber, Steel Belts, Nylon |
| Companies Covered | Michelin, Bridgestone Corporation, Continental AG, The Goodyear Tire & Rubber Company, Pirelli & C. S.p.A., Sumitomo Rubber Industries, Hankook Tire & Technology Co. Ltd., Yokohama Rubber Co. Ltd., Toyo Tire Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performance Tires Market Evolving Landscape
Tire architecture is fragmenting into modular subsystems where electronics, materials science, and predictive algorithms converge. This convergence is compressing development cycles while expanding the definitional boundary of what constitutes a performance tire.
Biomimetic tread patterns derived from gecko adhesion research are decomposing the traditional trade-off between dry grip and hydroplaning resistance. Track-day enthusiasts in Germany and Japan are adopting these compounds 40% faster than mainstream replacement buyers. The technology is decomposing established speed-rating hierarchies by enabling single tires to span multiple performance categories.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are forcing reformulation of carbon-black masterbatches. Tire manufacturers must validate alternative reinforcing fillers without sacrificing treadwear grades. The replacement market in France and Italy faces the steepest compliance costs as domestic distributors hold older inventory.
Fleet procurement departments now specify tires through total-cost-of-ownership models rather than unit price. Leasing companies and ride-hail operators in the United States are unbundling tire costs from vehicle leases. California's fleet electrification mandates accelerate this shift as operators prioritize range-per-dollar over upfront acquisition cost.
Performance Tires Market Segmentation
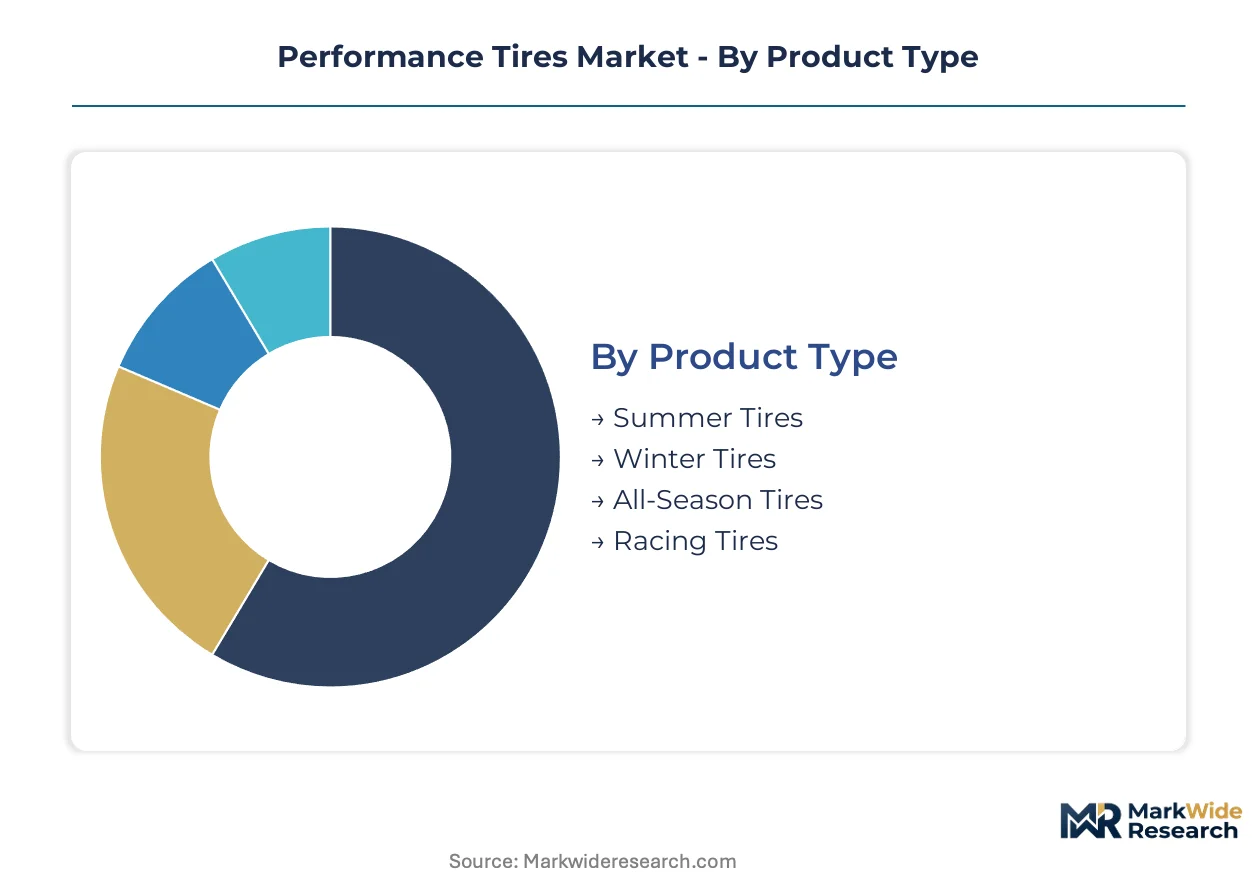
Performance tire segmentation reflects divergent regulatory pressures across climate zones and vehicle electrification trajectories. Homologation protocols now segment the market more sharply than traditional price tiers, as UNECE R117 and EPA labeling rules create distinct compliance corridors for each product category.
Product Type:
EU tire-labeling regulations and NHTSA fuel-economy standards create divergent certification burdens across seasonal categories, with wet-grip and snow-traction ratings determining market access.
- Summer Tires:Silica-reinforced tread compounds optimized for sustained operation above 240 km/h dominate Mediterranean and Middle Eastern replacement markets. Germany's Nürburgring-adjacent testing corridor concentrates development activity for track-day derivatives.
- All-Season Tires:M+S-rated compounds with summer-level dry grip are capturing temperate-zone drivers in France and Italy who reject seasonal changeover costs. ECHA verification queues for dual-certification tread patterns extend launch timelines.
- Winter Tires:Specialized sipe geometries and soft-tread polymers address sub-7°C elastomer hardening in Alpine and Nordic climates.
- Racing Tires:Homologated slicks and wet-weather competition compounds subsidize street-product R&D amortization through motorsport supply contracts.
Summer tires handle the majority of throughput; all-season variants are gaining share fastest as fleet operators prioritize year-round range preservation.
Vehicle Type:
Load-index recalibration for battery-electric powertrains is redrawing segment boundaries faster than traditional displacement-based classifications.
- Performance Vehicles:Electric hypercars and sports sedans with instantaneous torque delivery demand aramid-reinforced sidewalls and revised heat-dissipation architectures. Japan's METI JIS D 4230 standards govern minimum thresholds for this segment's domestic replacement market.
- SUVs:Higher curb weights and elevated center-of-gravity dynamics require stiffer belt packages and reinforced bead constructions. California's fleet electrification mandates accelerate specification shifts toward range-optimized compounds.
- Passenger Cars:Volume concentration in Germany's Rhine-Ruhr automotive cluster compresses homologation cycles for mainstream fitments.
- Light Trucks:Commercial and recreational dual-use applications drive demand for puncture-resistant sidewall technologies.
Passenger cars maintain the largest installed base; performance vehicles show the steepest specification escalation as EV torque curves rewrite compound requirements.
Tread Design:
Biomimetic research and computational fluid dynamics are decomposing traditional speed-rating hierarchies through pattern innovations.
- Directional:V-shaped groove geometries excel at high-speed water evacuation for wet-weather performance driving. Track-day enthusiasts in Germany and Japan adopt these patterns faster than mainstream replacement buyers.
- Asymmetrical:Combined inner-wet and outer-dry zone optimization enables single tires to span multiple performance categories. REACH Annex XVII PAH restrictions force reformulation of reinforcing fillers without sacrificing wear grades.
- Symmetrical:Uniform block arrays prioritize even wear distribution and rotational flexibility for cost-conscious fleet operators.
- R-Factor:Run-flat reinforced sidewalls maintain mobility after pressure loss, specified by leasing companies unbundling tire costs from vehicle contracts.
Directional patterns dominate the premium replacement channel; asymmetrical designs are expanding most quickly as compound advances collapse traditional trade-offs.
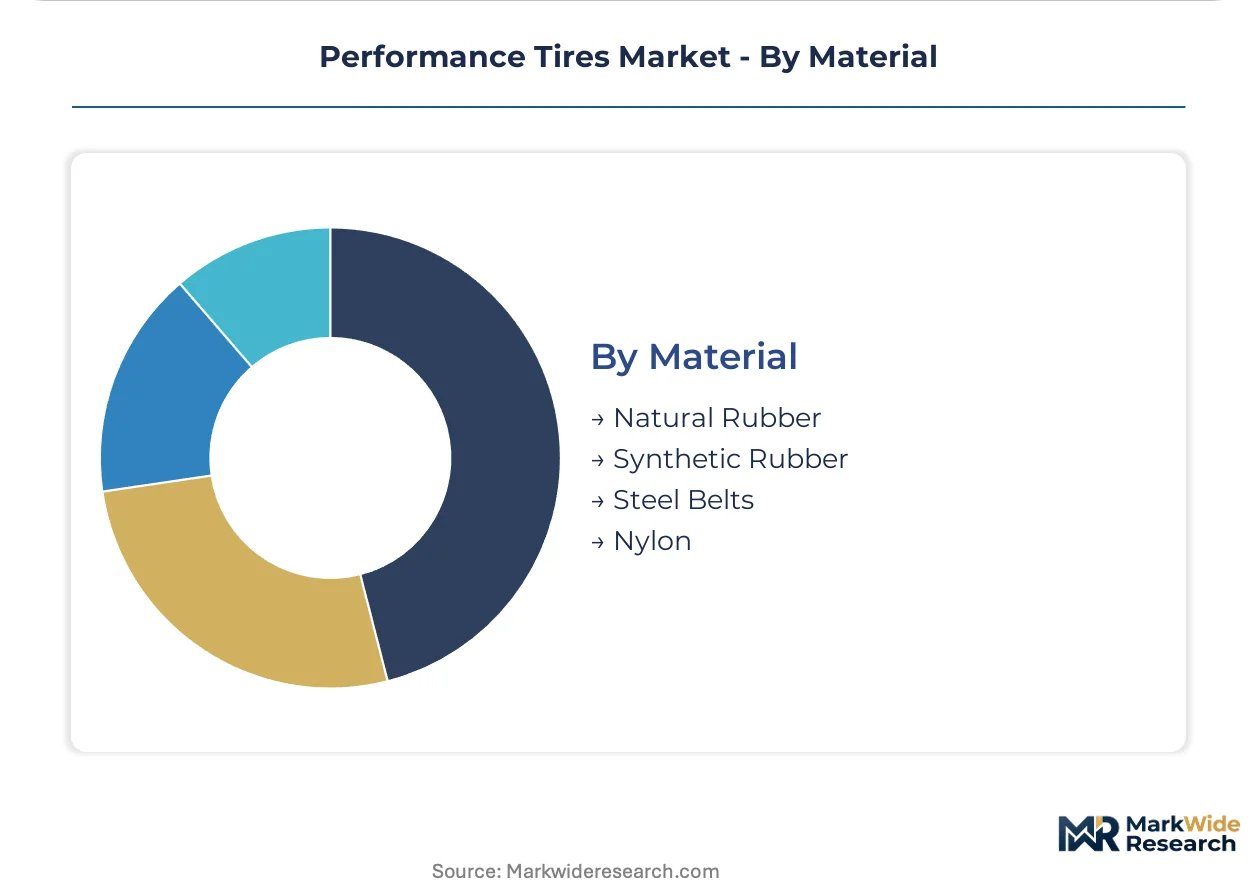
Material:
Supply concentration and regulatory chemistry constraints determine competitive positioning more than finished-tire pricing.
- Synthetic Rubber:Solution-polymerized styrene-butadiene enables precise glass-transition temperature tuning for all-season performance. EU F-Gas Regulation phasedown accelerates fluorine-free polymer R&D.
- Natural Rubber:Hevea brasiliensis supply concentration in Southeast Asia exposes compounders to El Niño-driven price volatility and sustainability certification requirements.
- Steel Belts:High-tensile cord constructions provide belt package stiffness for high-speed stability and puncture resistance.
- Nylon:Cap ply materials manage centrifugal growth at sustained elevated speeds in V- and W-rated applications.
Synthetic rubber commands the greatest formulation flexibility; natural rubber faces the steepest supply-side constraints from climate volatility and traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in high-performance tire logistics, channeling Southeast Asian natural rubber to European compounders while exporting finished assemblies to global OEMs.
Germany
Track-day tourism around the Nürburgring Nordschleife sustains aftermarket demand for W-rated and Y-rated compounds. The KBA enforces UNECE R117 certification timelines that compress homologation cycles for domestic manufacturers. The Rhine-Ruhr automotive cluster concentrates Continental AG and other suppliers within 200 kilometers of major OEM engineering centers.
United States
Fleet electrification mandates in California accelerate specification shifts toward range-optimized tread patterns for performance EVs. The EPA's fuel-economy labeling rules pressure manufacturers to reduce rolling resistance without sacrificing wet-braking grades. The Detroit-to-Chicago corridor hosts tire testing facilities that validate compounds for domestic OEM fitment programs.
Japan
Domestic motorsport heritage sustains demand for competition-derived street tires among enthusiast buyers. METI administers JIS D 4230 standards governing minimum performance thresholds for replacement markets. The Kanto region around Tokyo concentrates R&D facilities for silica-silane coupling chemistry development.
China
Electric vehicle production volume drives demand for load-index recalibrated compounds that accommodate battery-electric torque profiles. MIIT oversees GB standards for tire labeling and performance certification. The Yangtze River Delta hosts manufacturing capacity serving both domestic OEMs and export markets.
India
Rising disposable income among performance vehicle owners expands the addressable market for premium replacement tires. The PLI scheme for advanced automotive components attracts greenfield tire manufacturing investments. Tamil Nadu's industrial corridor hosts emerging production capacity targeting domestic and Southeast Asian export channels.
Performance Tires Market Competitive Landscape
Listed leaders compete with private specialists across compound technology and motorsport pedigree dimensions. The market structure concentrates around five globally integrated manufacturers commanding premium-tier pricing, while mid-scale regional compounders capture replacement volume through price-competitive all-season lines. Three strategic archetypes dominate: plantation-integrated natural rubber controllers, motorsport-heritage technology licensors, and sensor-embedded smart tire developers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with compounders securing long-term aramid fiber supply agreements and telemetry platform alliances.
Within the plantation-integrated tier, Michelin anchors natural rubber supply security through captive Hevea brasiliensis estates. Bridgestone Corporation and Continental AG exemplify the motorsport-to-road technology transfer archetype, with the latter additionally representing sensor-embedded tire system development. These three entities occupy positions that span compound consistency, track-derived tread innovation, and chassis-telemetry integration respectively.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone Corporation |
| Continental AG |
| The Goodyear Tire & Rubber Company |
| Pirelli & C. S.p.A. |
| Sumitomo Rubber Industries |
| Hankook Tire & Technology Co. Ltd. |
| Yokohama Rubber Co. Ltd. |
| Toyo Tire Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Southeast Asian Hevea brasiliensis estates shapes compounder procurement leverage and establishes natural rubber price floors that cascade through performance tire manufacturing economics. German OEM fitment volumes and Nürburgring testing corridor demand concentrate buyer power among fleet operators and premium aftermarket channels, compressing margin capture for non-integrated compounders.
Pricing Analysis
Volume-discount tiering structures separate homologated OEM fitments from aftermarket replacement channels, with UNECE R117 certification grade and silica loading percentage driving price differentiation across premium, standard, and economy tiers. Fleet procurement departments leveraging total-cost-of-ownership models exert pricing pressure on unit-price-focused distributors. Price erosion runs through unbranded all-season lines as Indian PLI-subsidized capacity enters Southeast Asian export channels. Least price sensitivity concentrates among track-day enthusiasts specifying W-rated and Y-rated compounds for Nürburgring-adjacent testing; greatest sensitivity sits with cost-conscious passenger car fleet operators rejecting seasonal changeover expenses.
Supply Chain Analysis
Strategic stockpiling of natural rubber dominates inventory strategy among European compounders buffering El Niño-driven supply disruptions, while just-in-time silica and aramid fiber deliveries sustain continuous compounding operations. Raw material sourcing draws from Thailand, Indonesia, and Vietnam for Hevea brasiliensis latex; para-aramid cordage hinges on a three-supplier oligopoly concentrated in the United States and Japan. Single-source vulnerability in high-tensile steel belt wire exposes manufacturers to logistics chokepoints at the Port of Hamburg. Distribution runs through captive OEM supply agreements, authorized dealer networks for replacement markets, and direct fleet procurement contracts unbundling tire costs from vehicle leases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The performance tires market sits in early-cycle recovery as electric vehicle production volume forces load-index recalibration and compound reformulation investment across the supplier base.
For Market Incumbents: Compound silica-silane coupling expertise through targeted hiring from retiring specialist cohorts and accelerate UNECE R117 pre-certification testing to compress homologation timelines. Secure long-term para-aramid supply agreements before aramid fiber oligopoly tightening. Defend against Indian PLI-subsidized entrants by deepening captive rubber plantation integration and motorsport-derived technology licensing programs. For New Entrants and Emerging Players: ECHA tire-labeling verification fast-tracks offer regulatory pathway acceleration for greenfield compounders targeting European aftermarket channels. White-space concentrates in all-season performance hybrids capturing temperate-zone drivers rejecting seasonal changeovers, and in sensor-embedded tire systems for predictive maintenance contracts. Enter through telemetry platform alliances with fleet telematics providers, bypassing established OEM fitment barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with demonstrated silica-reinforced formulation expertise and established motorsport-to-road technology transfer capabilities. Long-term viability rests on R&D amortization across homologated street products and fleet telemetry integration revenue streams. Acquisition targets should display backward integration into natural rubber sourcing or captive aramid fiber supply agreements. The signal to watch is battery-electric vehicle torque profile standardization across OEM platforms, which would collapse compound customization requirements and favor scale-efficient manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Rubber Plantation Acquisition | Insulates compound consistency from El Niño-driven natural latex price volatility. |
| UNECE R117 Pre-Certification Investment | Compresses homologation cycles from 18 months toward 12 for German OEM programs. |
| Sensor-Embedded Tire Development | Enables predictive maintenance contracts with California fleet electrification mandates. |
| Silica-Silane Coupling R&D Expansion | Sustains AA wet-braking retention while meeting EU F-Gas fluorine-free polymer requirements. |
| Aramid Fiber Long-Term Supply Agreement | Secures para-aramid cordage for high-speed sidewall reinforcement against oligopoly tightening. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, encompassing OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and fleet telematics procurement managers. Secondary validation drew from UNECE R117 certification databases, ECHA tire-labeling registries, SEC 10-K filings of listed manufacturers, and IHS Markit vehicle production data. Bottom-up triangulation across compound formulation inputs and top-down reconciliation against OEM fitment program volumes anchored market sizing.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by product type, vehicle propulsion architecture, tread design certification grade, and regional regulatory cluster. CAGRs were derived from regression analysis of historical replacement rates against electric vehicle penetration trajectories and fleet electrification mandate timelines. Industry-specific inputs included silica loading percentage trends, aramid fiber supply elasticity estimates, and biomimetic tread pattern adoption curves among track-day enthusiasts.
Decision-makers should treat outputs as directional under base assumptions of sustained EU F-Gas Regulation compliance timelines and stable Hevea brasiliensis yield patterns; material deviation would warrant model refresh. Specific risk factors include pending UNECE R117 wet-grip testing protocol revisions and El Niño intensity exceeding historical baselines. Revision becomes warranted when battery-electric vehicle curb weight standardization crosses thresholds that collapse load-index recalibration requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Self-Sealing Tire Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
Global Automotive Tire Socks Market
Tires and Wheels
Saudi Arabia Tire Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Automotive Winter Tire Market