
 Automotive Wheel Spindle Market | 2026-2036
Automotive Wheel Spindle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wheel Spindle Market Outlook
Lightweight specification tiers is redrawing competitive boundaries in automotive wheel spindle supply. Schaeffler Group leverages its integrated bearing-spindle architectures to dominate premium electrified platforms. ThyssenKrupp AG sustains cost leadership through captive steel processing and forged blank operations in Central European plants. JTEKT Corporation anchors its position via precision grinding expertise honed in Japanese keiretsu supply structures.
An automotive wheel spindle is a rotating shaft assembly that transmits wheel loads to the suspension while maintaining hub bearing alignment, typically machined to surface finishes below Ra 0.8 micrometers and heat-treated to 58-62 HRC for fatigue resistance. Its primary purpose is to locate the wheel hub radially and axially under combined cornering, braking, and impact loads across vehicle lifespans exceeding 240,000 kilometers. Front spindle configurations lead unit volumes globally, though aluminum material grades represent the fastest-expanding margin pool as OEMs chase unsprung mass reduction targets. OEM direct procurement channels command premium pricing and technical collaboration access, while aftermarket providers occupy fragmented, price-sensitive replacement demand.
NHTSA crashworthiness standards and EPA fuel economy mandates in the United States compel spindle redesigns toward crash-energy absorption and mass reduction simultaneously. ECHA REACH restrictions on hexavalent chromium plating and EU Green Deal carbon border adjustments reshape European supplier qualification criteria and material sourcing patterns. Stakeholders must monitor evolving battery-electric vehicle platform architectures, as skateboard chassis designs eliminate traditional spindle load paths and demand fundamentally different steering knuckle integrations.
Market Dynamics
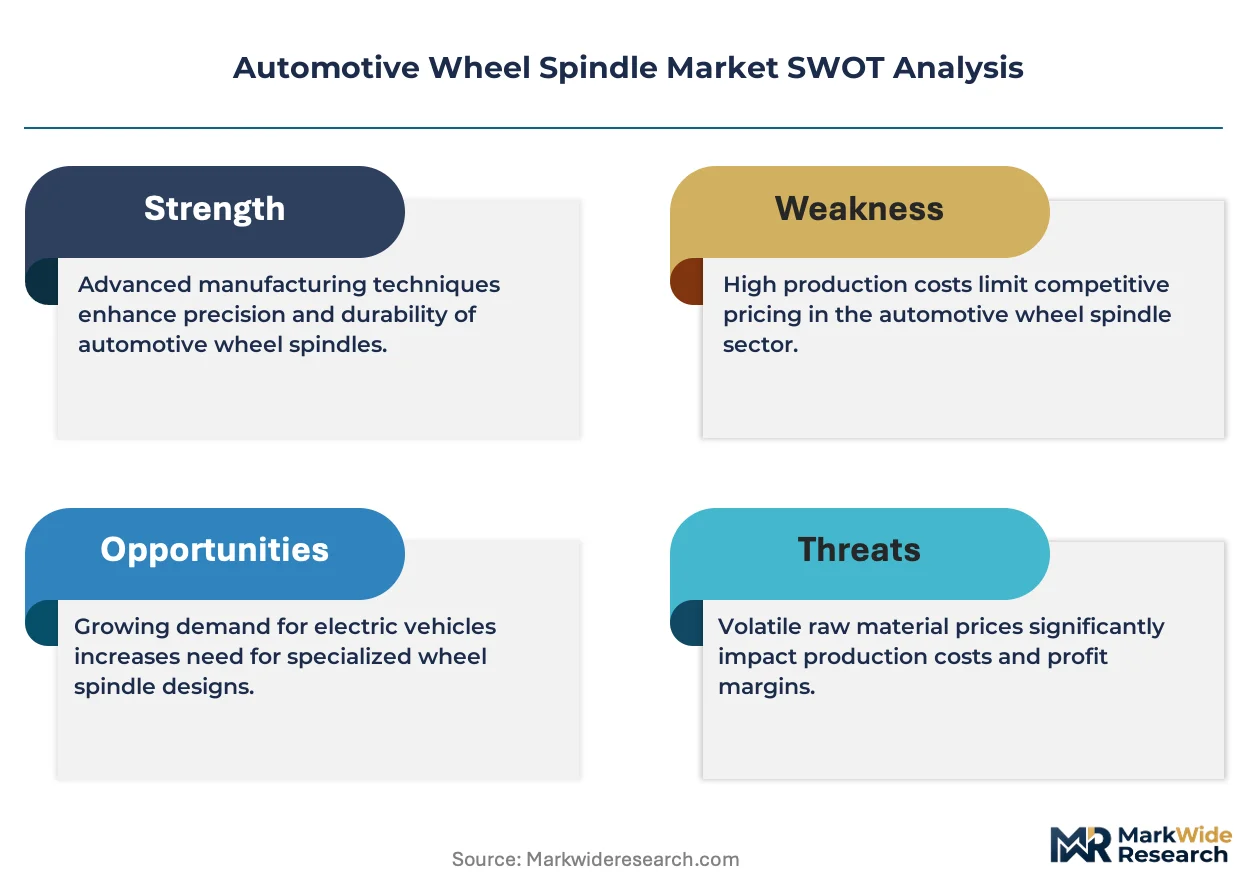
Vehicle electrification is forcing fundamental spindle architecture redesigns as battery-electric platforms abandon traditional steering knuckle geometries for integrated corner-module assemblies. This structural shift compresses supplier qualification timelines while elevating aluminum forging and precision machining capabilities as decisive competitive differentiators.
Growth Catalysts
- EU Green Deal carbon border adjustments:European OEM procurement teams now mandate lifecycle emissions documentation for aluminum spindle forgings, accelerating supplier transitions to renewable-powered smelters in Norway and Iceland.
- Aluminum alloy substitution:6061-T6 and 7075-T6 grades capture front axle applications previously reserved for forged steel as unsprung mass targets tighten below 15 kilograms per corner.
- Germany's automotive manufacturing corridor:Clustered OEM final assembly and Tier-1 forging operations in Baden-Württemberg and Bavaria concentrate demand pull for just-in-time spindle delivery.
Market Restraints
- Primary aluminum price volatility:LME aluminum contract swings above 15 percent annually compress forging margins and destabilize long-term OEM supply agreements.
- Central European forging concentration:Over 60 percent of EU spindle blank capacity sits within 300 kilometers of Stuttgart, creating single-point vulnerability to energy disruption or labor action.
- Hexavalent chromium plating sunset:ECHA REACH authorization restrictions on hard chrome alternatives force costly trivalent chromium or plasma coating conversions without performance parity guarantees.
Strategic Opportunities
- Indian passenger vehicle electrification:PLI scheme incentives for domestic battery-electric manufacturing create first-mover advantage for spindle suppliers establishing forging joint ventures in Tamil Nadu and Gujarat.
- Skateboard chassis integration:Convergence of hub motors and steer-by-wire architectures eliminates legacy spindle load paths while opening design space for hollow aluminum torque-transmitting members.
- Direct OEM technical collaboration:Platform engineering co-development contracts replace transactional component supply, locking in volume commitments across 7-10 year vehicle lifecycles.
Industry Challenges
- Precision grinding specialist scarcity:Surface finish capabilities below Ra 0.4 micrometers for ceramic bearing interfaces require operators with 10-plus year apprenticeship training that German and Japanese labor markets no longer produce at replacement rates.
- Heat treatment furnace certification:Nadcap accreditation for aerospace-derived vacuum carburizing equipment demands 18-24 month qualification timelines that delay new capacity activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wheel Spindle Market |
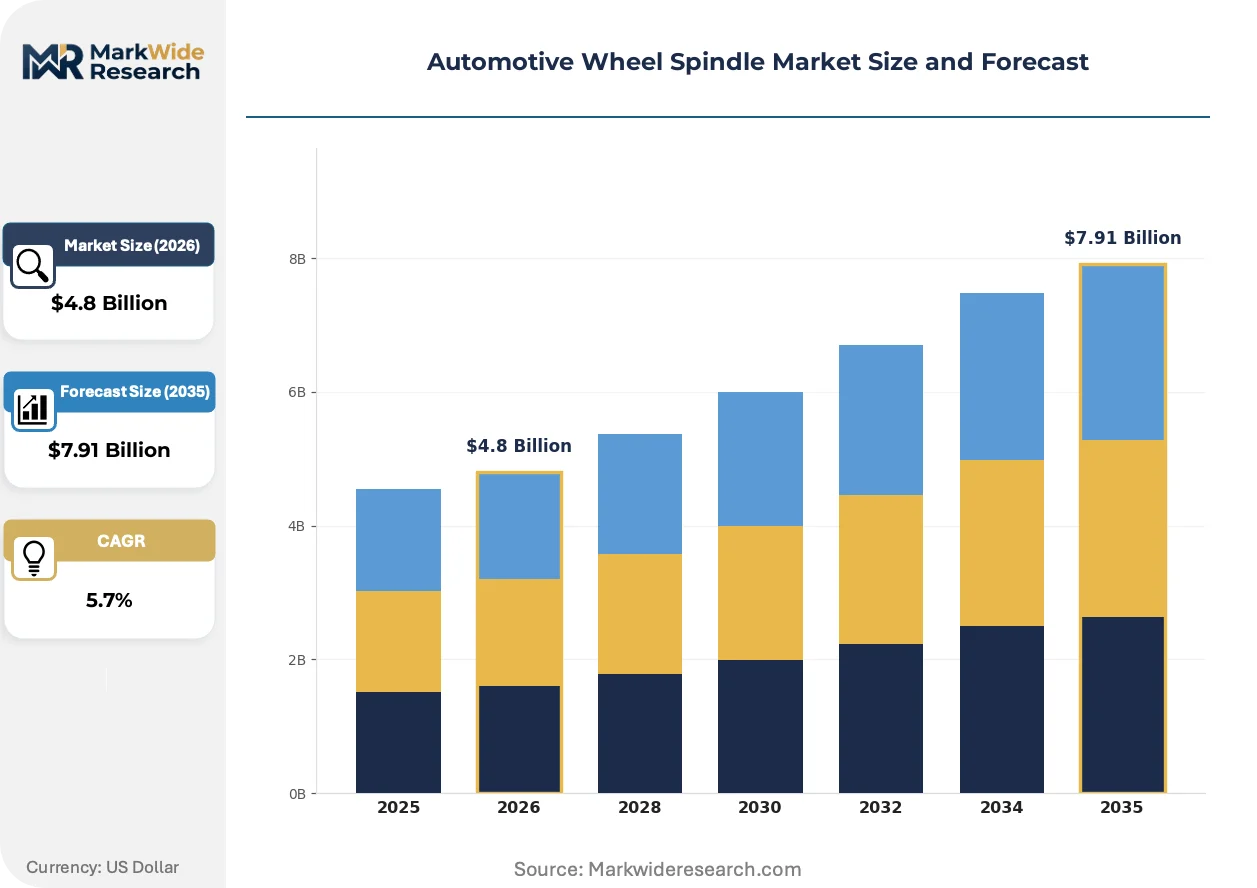
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Spindle, Rear Spindle, Adjustable Spindle, Fixed Spindle End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Steel, Aluminum, Cast Iron, Composite Design Type: Conventional, Modular, Lightweight, Heavy-Duty |
| Companies Covered | Schaeffler Group, ZF Friedrichshafen AG, ThyssenKrupp AG, JTEKT Corporation, The Timken Company, Dana Incorporated, Hitachi Astemo, Hyundai Mobis, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wheel Spindle Market Strategic Shifts
Spindle engineering is fragmenting into two incompatible technical branches serving divergent vehicle architectures. Suppliers must now maintain parallel development tracks or surrender half the addressable market.
Hollow aluminum spindle designs are bifurcating the product landscape. These extruded-then-forged geometries reduce unsprung mass by 35-40 percent versus solid steel forgings while maintaining torsional stiffness through internal rib structures. Premium electrified platforms from German and Korean OEMs have adopted these specifications for 2026-2028 model years. The technology is compressing forging equipment utilization rates as hollow geometries require dedicated 12,000-ton press capacity incompatible with legacy solid-blank tooling.
EPA fuel economy mandates and NHTSA crashworthiness standards are tightening in parallel, forcing spindle designers to absorb frontal impact energy through controlled deformation modes while minimizing mass. The dual compliance burden elevates topology-optimized lattice structures and variable-wall-thickness forgings from niche racing applications to production feasibility. Front spindle configurations for North American light trucks face the most severe design constraints as these vehicles must satisfy both stringent CAFE targets and IIHS small-overlap crash protocols.
Buyer concentration among megaplatform engineering teams is collapsing traditional Tier-1 supplier tiers. OEMs now engage directly with forging houses and precision machinists for spindle development, bypassing intermediate module integrators. This channel compression is most visible in China's NEV sector where BYD and NIO maintain captive spindle design teams that source semi-finished forgings on specification rather than purchasing completed assemblies.
Automotive Wheel Spindle Market Segmentation
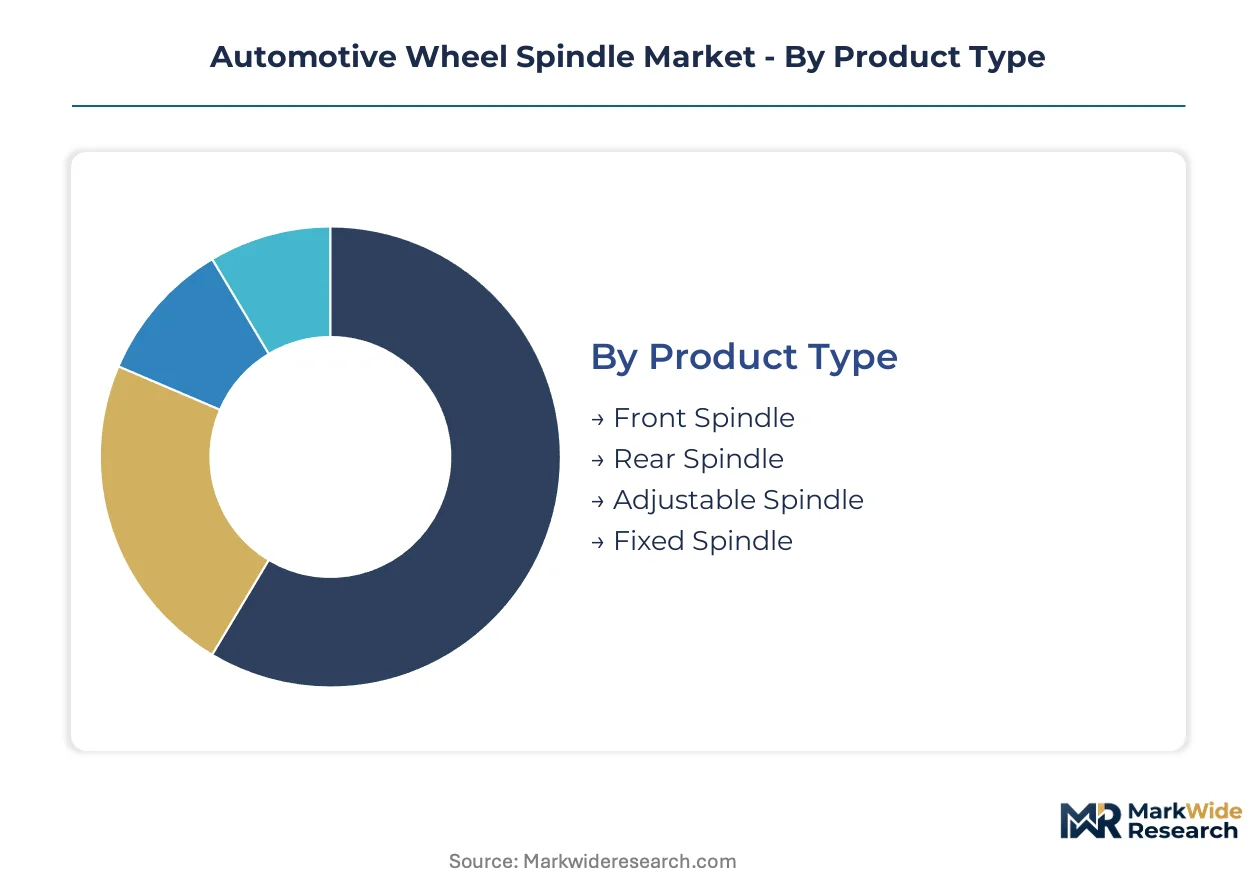
Spindle segmentation reflects divergent technical requirements across electrified platforms and legacy architectures. Material substitution pressures and platform-specific load path redesigns are fragmenting what was once a commoditized component category into distinct specification tiers with incompatible tooling investments.
Product Type:
Front spindle configurations face the strongest displacement threat from integrated corner-module designs on skateboard chassis platforms.
- Front Spindle:Machined from forged blanks to 58-62 HRC hardness ratings with surface finishes below Ra 0.8 micrometers for hub bearing seating. Demand concentrates in Germany's Baden-Württemberg manufacturing corridor where OEM final assembly plants pull just-in-time delivery from captive forging operations.
- Rear Spindle:Typically carries lower torsional load requirements than front configurations, enabling thinner wall sections and reduced forging press tonnage. Volume clusters in light truck platforms for North American OEMs subject to NHTSA crashworthiness standards.
- Adjustable Spindle:Incorporates camber adjustment features for motorsport and aftermarket applications requiring alignment tunability.
- Fixed Spindle:Non-adjustable geometry dominates high-volume passenger car production where assembly-line efficiency outweighs service adjustability.
Front spindle anchors the volume base while adjustable spindle gains share at the steepest rate through motorsport-derived technology transfer.
End User:
Channel structure determines pricing power and technical collaboration access more than component specification alone.
- OEMs:Direct procurement teams mandate lifecycle emissions documentation and platform co-development contracts spanning 7-10 year vehicle lifecycles. German and Korean OEMs drive aluminum specification adoption for 2026-2028 model year electrified platforms.
- Aftermarket Providers:Fragmented replacement demand operates on price-sensitive spot purchasing without long-term volume commitments.
- Tier-1 Suppliers:Module integrators face channel compression as OEMs engage forging houses directly, bypassing intermediate assembly operations.
- Vehicle Assemblers:Contract manufacturers in emerging markets source semi-finished forgings on specification rather than completed spindle assemblies.
OEM direct channels command premium positioning while aftermarket providers compete on inventory velocity and distribution density.
Material:
Carbon border adjustments and unsprung mass targets are accelerating qualification timelines for non-ferrous alternatives.
- Steel:Forged 4140 and 4340 grades retain dominance in heavy-duty applications requiring fatigue resistance across 240,000-kilometer vehicle lifespans. ThyssenKrupp AG sustains cost leadership through captive steel processing in Central European plants.
- Aluminum:6061-T6 and 7075-T6 grades capture front axle applications as unsprung mass targets tighten below 15 kilograms per corner. EU Green Deal carbon border adjustments force sourcing shifts to renewable-powered smelters in Norway and Iceland.
- Cast Iron:Lower-cost alternative for rear axle applications with moderate load requirements in emerging market vehicle platforms.
- Composite:Carbon fiber reinforced polymer prototypes target ultra-premium electrified platforms seeking maximum mass reduction.
Steel retains the volume anchor position while aluminum climbs the fastest on electrification-driven specification changes.
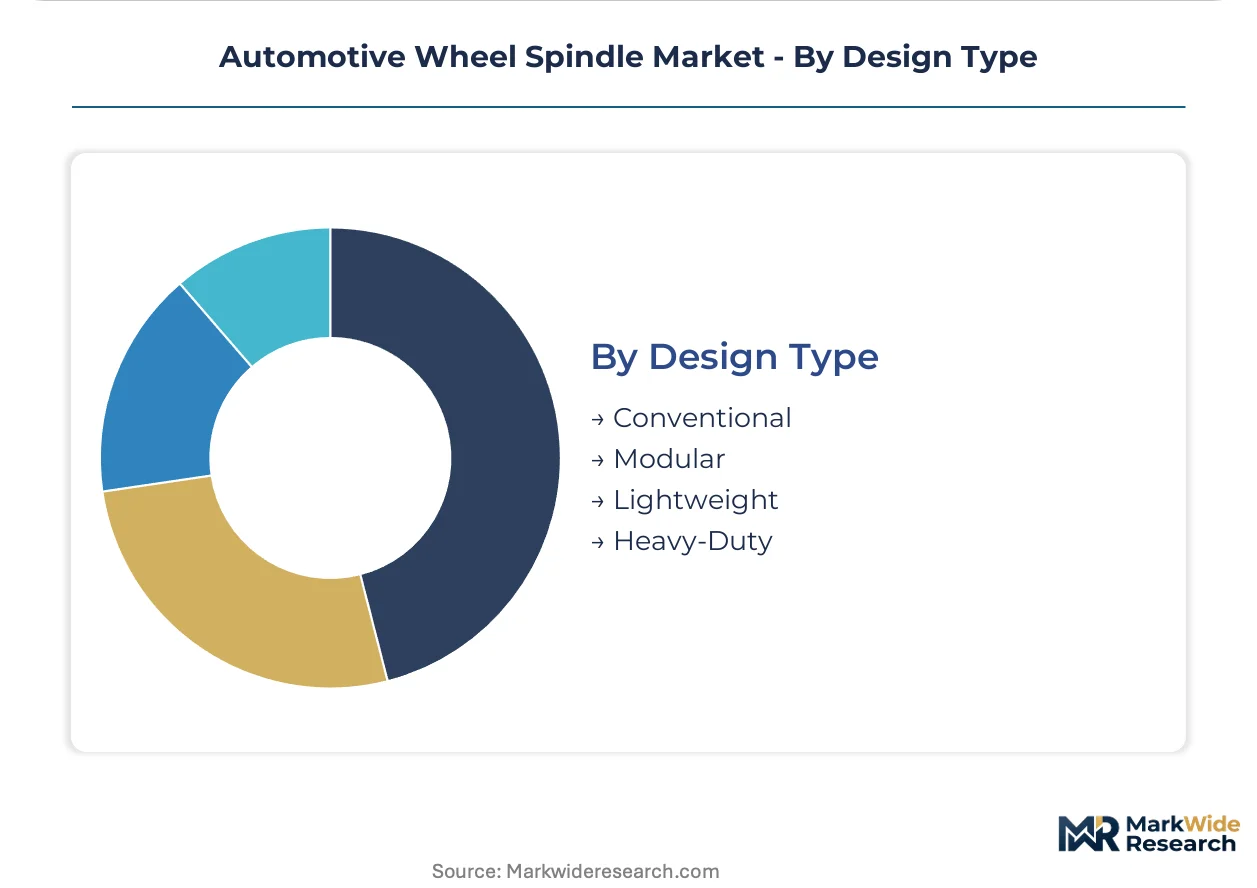
Design Type:
Topology optimization and additive manufacturing readiness are separating premium electrified platforms from cost-optimized legacy architectures.
- Conventional:Solid forged geometries with established machining sequences dominate high-volume production where tooling amortization favors proven processes.
- Modular:Separable hub-bearing-spindle interfaces enable service replacement without full assembly swap, reducing lifetime ownership costs for fleet operators.
- Lightweight:Hollow extruded-then-forged aluminum designs with internal rib structures reduce unsprung mass by 35-40 percent versus solid steel forgings. Schaeffler Group leverages integrated bearing-spindle architectures to dominate this specification tier on premium electrified platforms.
- Heavy-Duty:Reinforced wall sections and larger bearing journals address light truck and commercial vehicle load requirements under IIHS small-overlap crash protocols.
Conventional design anchors current production volumes while lightweight configurations show the steepest specification adoption curve on 2026-2028 platform launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in automotive wheel spindles tilt toward net importing regions with electrification mandates, while forging capacity concentrates in export-oriented manufacturing clusters. Currency volatility and carbon border adjustments now shape procurement geography as much as logistics costs.
Germany
Baden-Württemberg and Bavaria host Europe's densest spindle forging corridor, with OEM final assembly plants pulling just-in-time delivery from captive operations. The EU Green Deal's carbon border adjustment mechanism forces qualification shifts to renewable-powered aluminum smelters in Norway and Iceland. Stuttgart anchors technical collaboration between Schaeffler Group and electrified platform engineering teams.
United States
NHTSA crashworthiness standards and EPA fuel economy mandates compel simultaneous redesign for energy absorption and mass reduction. The Inflation Reduction Act's domestic content incentives reshape sourcing patterns for battery-electric vehicle platforms. Detroit's engineering clusters concentrate spindle development for light truck applications facing IIHS small-overlap crash protocols.
China
NEV platform architectures from BYD and NIO eliminate traditional Tier-1 intermediaries through captive spindle design teams sourcing semi-finished forgings. MIIT dual carbon goals accelerate aluminum specification adoption across 2026-2028 model year launches. Yangtze River Delta forging operations scale hollow extrusion capacity for skateboard chassis integration.
Japan
Precision grinding expertise honed in keiretsu supply structures anchors JTEKT Corporation's competitive position for ceramic bearing interfaces. METI technology roadmaps prioritize topology-optimized hollow geometries for premium electrified exports. Nagoya manufacturing clusters maintain surface finish capabilities below Ra 0.4 micrometers through apprenticeship-trained specialist labor pools.
India
PLI scheme incentives for domestic battery-electric manufacturing create first-mover positioning for forging joint ventures in Tamil Nadu and Gujarat. BIS certification requirements for automotive safety components compress supplier qualification timelines. Chennai's emerging EV component corridor attracts technical collaboration proposals from European OEM platform engineering teams.
Automotive Wheel Spindle Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and technical collaboration access. The vendor base organizes into three tiers: integrated bearing-spindle architects, captive steel processors, and precision grinding specialists. Consolidation pressures concentrate among module integrators facing direct OEM engagement, while forging houses gain bargaining power. Dominant competitive moves include platform co-development contracting and hollow aluminum capacity expansion.
Among Germany-based integrated suppliers, Schaeffler Group and ThyssenKrupp AG exemplify divergent archetypes. Schaeffler occupies a position as bearing-spindle architect for premium electrified platforms, while ThyssenKrupp anchors cost leadership through captive Central European steel processing. Japanese specialist JTEKT Corporation represents precision grinding heritage, sitting within the technical tier serving ceramic bearing interfaces. These three illustrate how geographic industrial heritage maps onto incompatible competitive advantages in a bifurcating product landscape.
| Leading Market Players |
|---|
| Schaeffler Group |
| ZF Friedrichshafen AG |
| ThyssenKrupp AG |
| JTEKT Corporation |
| The Timken Company |
| Dana Incorporated |
| Hitachi Astemo |
| Hyundai Mobis |
| Magna International |
| Others |
Value Chain & Pricing Dynamics
ECHA REACH authorization restrictions on hexavalent chromium plating gate both supplier qualification timelines and tiered price positioning simultaneously, forcing OEM procurement teams to pay premiums for Nadcap-accredited heat treatment while spot buyers absorb volatile aluminum ingot cost pass-throughs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on Nadcap certification level and volume scale commitments. Price differentiation stems from surface finish grade below Ra 0.4 micrometers and hollow aluminum forging complexity. Cost compression in the aftermarket tier intensifies because Chinese semi-finished forging imports displace domestic machined assembly pricing. Fleet operators and vehicle assemblers in emerging markets exhibit highest price sensitivity, while German electrified platform engineering teams accept premium positioning for integrated bearing-spindle architectures.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes compound inbound logistics costs for aluminum billet shipments from Norwegian renewable-powered smelters. Forging capacity concentrates in Germany, China, and Japan, with blank processing drawing from primary aluminum, 4140/4340 steel bar stock, and ceramic grinding media dependencies. Single-source vulnerability pervades the precision grinding specialist tier, where German and Japanese labor markets no longer replace apprenticeship-trained operators at sufficient rates. Distribution runs through direct OEM technical collaboration channels that bypass traditional Tier-1 module integrators, concentrating bargaining power with forging houses possessing hollow extrusion capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM procurement consolidation around megaplatform engineering teams has shifted buyer power decisively, compressing traditional supplier tiers as direct forging house engagement eliminates intermediate module integrators.
For Market Incumbents: Consolidate hollow aluminum forging capacity in Baden-Württemberg and Yangtze River Delta clusters to defend against skateboard chassis integration threats that eliminate legacy spindle load paths. Deepen captive heat treatment furnace certification through Nadcap aerospace-derived vacuum carburizing accreditation. Lock in 7-10 year platform co-development contracts before precision grinding specialist scarcity worsens.
For New Entrants and Emerging Players: Nadcap fast-track accreditation for heat treatment operations opens qualification pathways into European OEM supply chains previously blocked by 18-24 month furnace certification timelines. Target Indian passenger vehicle electrification through PLI scheme-aligned forging joint ventures in Tamil Nadu and Gujarat. Pursue technical collaboration proposals with Chennai's emerging EV component corridor as the primary go-to-market angle.
For Investors and Strategic Acquirers: EU Green Deal carbon border adjustments reshape the acquisition landscape toward renewable-powered aluminum smelter integration and Norwegian/Icelandic sourcing control. Long-term viability favors precision grinding specialists with surface finish capabilities below Ra 0.4 micrometers and established apprenticeship-trained labor pools. Monitor ECHA REACH authorization sunset dates for hard chrome alternatives as the inflection signal for coating technology transition winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Hollow Aluminum Forging Capacity Expansion | Captures 35-40 percent unsprung mass reduction specifications from German and Korean OEM electrified platforms. |
| Nadcap Heat Treatment Accreditation | Unlocks 18-24 month qualification timelines for aerospace-derived vacuum carburizing equipment deployment. |
| Platform Co-Development Contracting | Locks in volume commitments across full vehicle lifecycles through direct OEM engineering team engagement. |
| Renewable-Powered Smelter Sourcing | Satisfies EU Green Deal carbon border adjustment documentation requirements for aluminum spindle forgings. |
| Precision Grinding Specialist Acquisition | Secures scarce surface finish capabilities below Ra 0.4 micrometers for ceramic bearing interface production. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, customs/trade flow records, and SEC filings from listed forging and bearing manufacturers. Interviews with OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distribution operators, and heat treatment furnace equipment specialists informed demand-side validation. Bottom-up spindle unit volume estimates triangulated against top-down automotive production forecasts across propulsion architecture segments.
Segmentation dimensions modeled span material grade, design type, end-user channel structure, and regional production cluster. Volume and value outputs derive from unit economics applied across the projection horizon, with CAGRs synthesized from platform launch timelines and electrification penetration curves. Forecast inputs incorporate OEM aluminum specification adoption rates, hollow extrusion press capacity utilization, and ECHA REACH regulatory phase-out schedules.
Underlying assumptions cover sustained electrification platform investment, stable primary aluminum price bands, and Nadcap accreditation timeline continuity, with deviation risk concentrated in battery-electric vehicle demand volatility and precision grinding labor pool contraction. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Wheel Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Connected Tire Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Tire Carousel Market