
 Cargo Bike Tire Market | 2026-2036
Cargo Bike Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Bike Tire Market Outlook
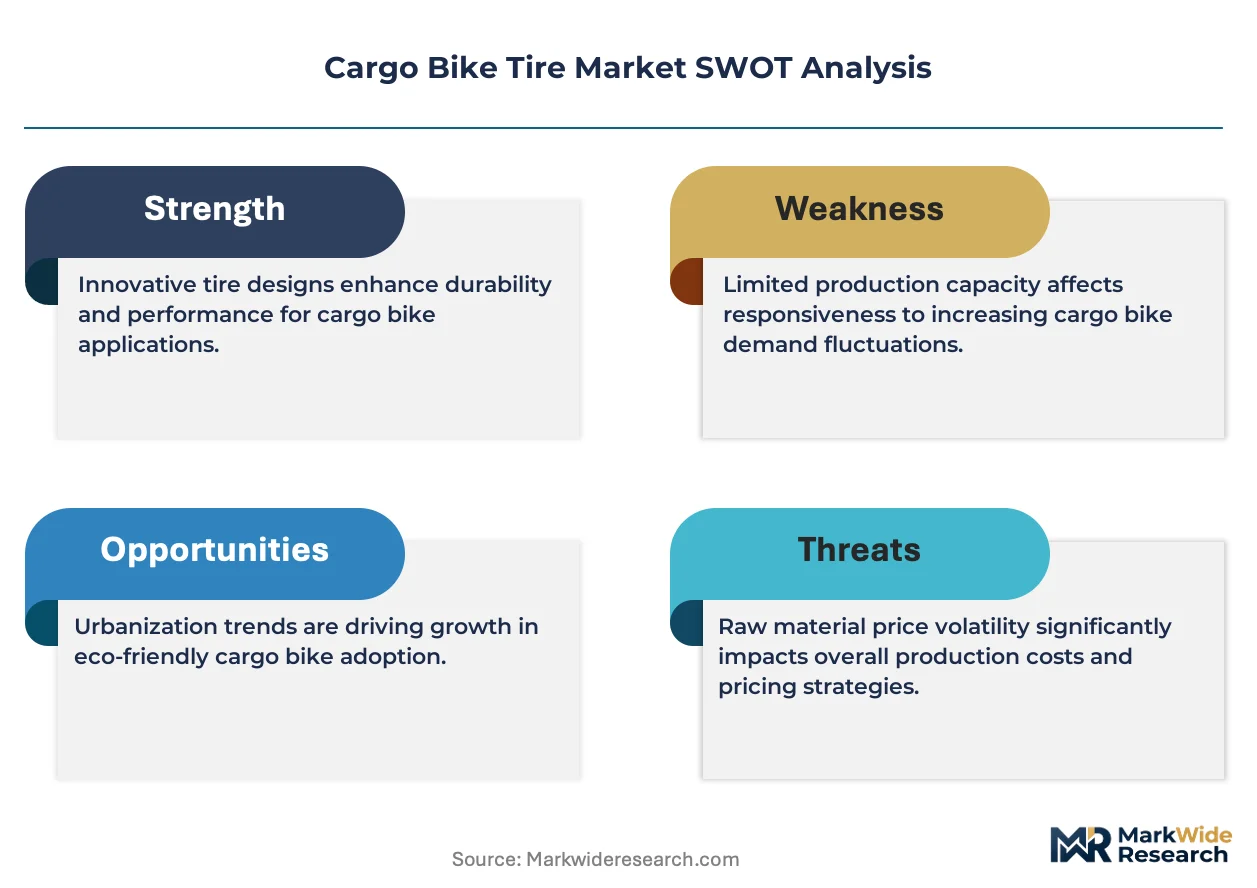
The capital-intensity divergence between premium compound formulators and commodity assemblers is unwinding competitive stability in cargo bike tire supply. Schwalbe leverages its in-house rubber compounding to command premium positioning in urban delivery specifications. Continental AG anchors European OEM relationships through integrated testing protocols that smaller suppliers cannot replicate.
Cargo bike tires are reinforced pneumatic structures engineered for loads exceeding standard bicycle ratings, typically incorporating aramid or nylon breaker layers and sidewall compounds rated for pressures above 55 PSI to support gross vehicle weights. Their primary commercial purpose is to deliver reliable rolling resistance and puncture resistance under sustained heavy-duty cycling in urban freight networks. Tubeless configurations are capturing margin pools as fleet operators prioritize downtime reduction, while Kevlar-reinforced materials command price premiums in high-theft urban corridors where debris penetration risks escalate. The 26-inch diameter segment dominates current OEM specifications, though 20-inch formats are gaining traction in compact last-mile vehicles.
EU REACH chemical standards constrain rubber additive formulations, while CE marking mandates uniform load-rating disclosures that shape procurement criteria across member states. Germany's KBA and France's national transport safety bodies enforce divergent testing protocols that complicate pan-European product homologation. Stakeholders must monitor how impending F-Gas Regulation amendments affect polyurethane foam core alternatives before committing to capacity expansion.
Market Dynamics
Fleet electrification mandates across the European Union are compressing replacement cycles for cargo bike tires as commercial operators accelerate vehicle turnover to meet emission targets. This regulatory pressure is restructuring procurement patterns toward higher-specification, longer-wear compounds.
Growth Catalysts
- EU Green Deal emission targets:Germany's KBA enforces stricter commercial vehicle standards that push last-mile logistics operators toward pedal-assist cargo bikes, expanding addressable tire demand.
- Tubeless tire technology:Fleet operators in the Netherlands prioritize downtime reduction, accelerating adoption of tubeless configurations that eliminate puncture-related service interruptions.
- Urban freight infrastructure density:Amsterdam and Copenhagen cycling network investments enable commercial freight adoption at scale, creating sustained replacement demand for heavy-duty tire specifications.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions transmit directly to compound costs, constraining margin flexibility for mid-tier assemblers dependent on spot market sourcing.
- REACH chemical compliance:ECHA additive restrictions force reformulation of sidewall compounds, extending R&D timelines and raising homologation costs for non-integrated suppliers.
- Polyurethane foam core substitution:Airless tire prototypes threaten pneumatic market share in high-theft urban corridors where debris penetration risks justify premium alternatives.
Strategic Opportunities
- French commercial freight incentives:National transport safety body subsidies for cargo bike fleet expansion create underpenetrated demand in Paris and Lyon metropolitan distribution networks.
- Kevlar-nylon hybrid breakers:Material convergence enables lighter-weight puncture resistance ratings that expand addressable applications into refrigerated last-mile delivery segments.
- Direct fleet procurement channels:Bypassing traditional distributor networks allows compound formulators to capture service revenue through integrated tire management contracts.
Industry Challenges
- Pan-European homologation fragmentation:Divergent KBA and French national transport safety testing protocols force redundant certification cycles that delay product launches.
- Aramid breaker integration complexity:Layer bonding with high-PSI sidewall compounds requires specialized curing equipment that smaller suppliers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Bike Tire Market |
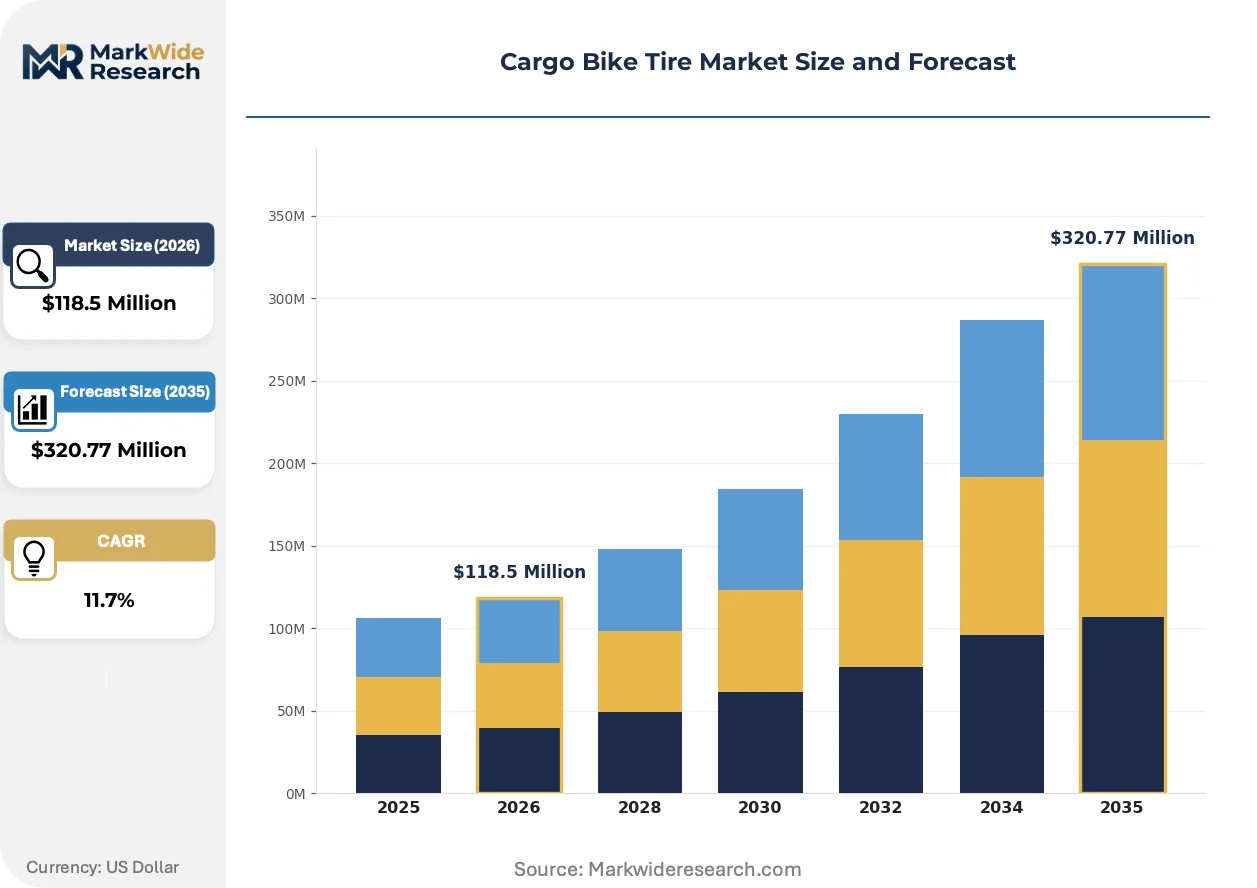
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $320.77 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: With Rim, Tubeless, Mountain, Road Material: Rubber, Synthetic, Kevlar, Nylon Diameter: 20 inch, 24 inch, 26 inch, 29 inch Use Case: Urban Delivery, Recreation, Cargo Transport, Freight |
| Companies Covered | Schwalbe, Continental AG, Michelin, Cheng Shin Rubber Ind, Kenda Tires, Maxxis International, Vittoria, Hutchinson, Pirelli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Bike Tire Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to redefine performance benchmarks for urban freight tires. Manufacturers must now optimize rolling resistance and load capacity within tightening additive restrictions.
Tubeless bead-lock configurations are supplanting traditional hooked-bead designs in commercial cargo bike specifications. Fleet maintenance departments in Dutch and German urban distribution networks are specifying tubeless as standard for vehicles above 200 kg gross weight. This transition is compressing aftermarket demand for inner tube replacements while expanding margin pools for sealant-compatible compound formulations.
EU F-Gas Regulation amendments are restricting hydrofluorocarbon propellants used in polyurethane foam core manufacturing. Tire producers dependent on airless prototypes face supply chain reconfiguration as foam-in-place alternatives require alternative blowing agents. German compound formulators are accelerating bio-based polyol development to maintain airless product roadmaps ahead of enforcement deadlines.
Consolidated fleet procurement is displacing fragmented shop-level purchasing across European last-mile operators. Large logistics integrators in Belgium and Denmark now specify tire performance metrics through centralized tender processes rather than individual vehicle maintenance decisions. This concentration shifts pricing power toward volume buyers and pressures smaller distributors to specialize in technical service capabilities.
Cargo Bike Tire Market Segmentation
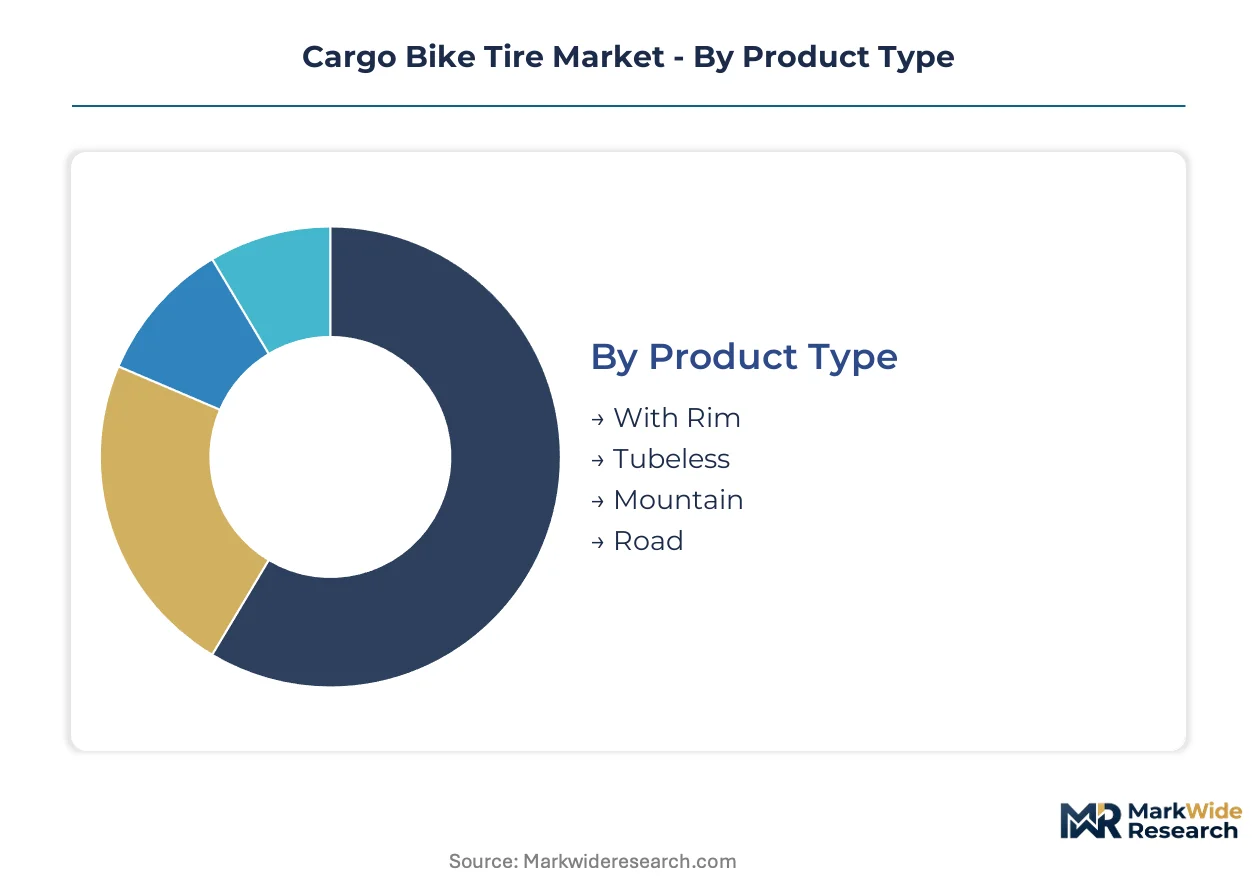
Segmentation in cargo bike tires reveals how material science and fleet procurement requirements diverge across urban freight applications. Commercial operators prioritize load ratings and downtime reduction, while recreational users emphasize rolling efficiency and terrain adaptability.
Product Type:
Tubeless configurations face intensifying substitution pressure from airless prototypes in high-theft corridors, while rim-dependent pneumatic designs confront margin compression from integrated wheel-tire systems.
- Tubeless:Bead-lock designs eliminate inner tubes through liquid sealant integration, enabling puncture self-healing under sustained loads. Dutch fleet operators specify these as standard for vehicles above 200 kg gross weight, driven by downtime reduction mandates in Rotterdam and Amsterdam distribution networks.
- With Rim:Traditional hooked-bead constructions dominate legacy fleet maintenance channels where wheel replacement cycles align with tire wear. German last-mile logistics providers favor these for compatibility with existing service infrastructure across Berlin and Hamburg urban zones.
- Mountain:Knobby tread patterns with reinforced sidewalls address unpaved access routes in peri-urban freight corridors.
- Road:Slick center-line designs optimize rolling resistance for paved last-mile circuits in Copenhagen and Brussels cycling networks.
Tubeless retains volume leadership among commercial specifications; Mountain holds the steepest expansion curve as refrigerated delivery extends into peri-urban zones.
Material:
Cost-tier stratification separates integrated compound formulators from commodity assemblers, with premium breakers capturing service revenue through integrated tire management contracts.
- Kevlar:Aramid fiber breakers deliver puncture resistance ratings at reduced weight compared to nylon alternatives. High-theft urban corridors in Paris and Lyon justify price premiums where debris penetration risks escalate for refrigerated cargo transport.
- Nylon:Woven breaker layers anchor mid-tier specifications through proven bonding compatibility with high-PSI sidewall compounds. Belgian logistics integrators specify these for standardized fleet procurement across Antwerp and Ghent metropolitan networks.
- Rubber:Natural and synthetic blends form the base compound matrix subject to EU REACH additive restrictions.
- Synthetic:Petro-derived polymers enable consistent curing properties across variable temperature production environments.
Nylon retains volume leadership across OEM specifications; Kevlar commands the steepest price premium trajectory as theft and debris risks concentrate in dense urban cores.
Diameter:
Application-driven geometry divides compact maneuverability requirements from stability-at-speed priorities in heavy-load configurations.
- 26 inch:The dominant OEM specification balances rolling efficiency with load distribution across standard cargo bike frames. German KBA homologation protocols favor this diameter for commercial vehicle certification, anchoring replacement demand in Düsseldorf and Munich fleet operations.
- 20 inch:Compact formats enable tighter turning radii in dense European city centers where parking constraints limit vehicle footprint. Danish operators in Copenhagen specify these for narrow historic street networks.
- 24 inch:Intermediate sizing addresses youth cargo bikes and compact electric assist platforms.
- 29 inch:Larger diameters optimize rollover efficiency for long-distance freight corridors with minimal stop-and-go requirements.
26 inch retains volume leadership through OEM standardization; 20 inch gains share fastest as compact last-mile vehicle formats proliferate in historic urban cores.
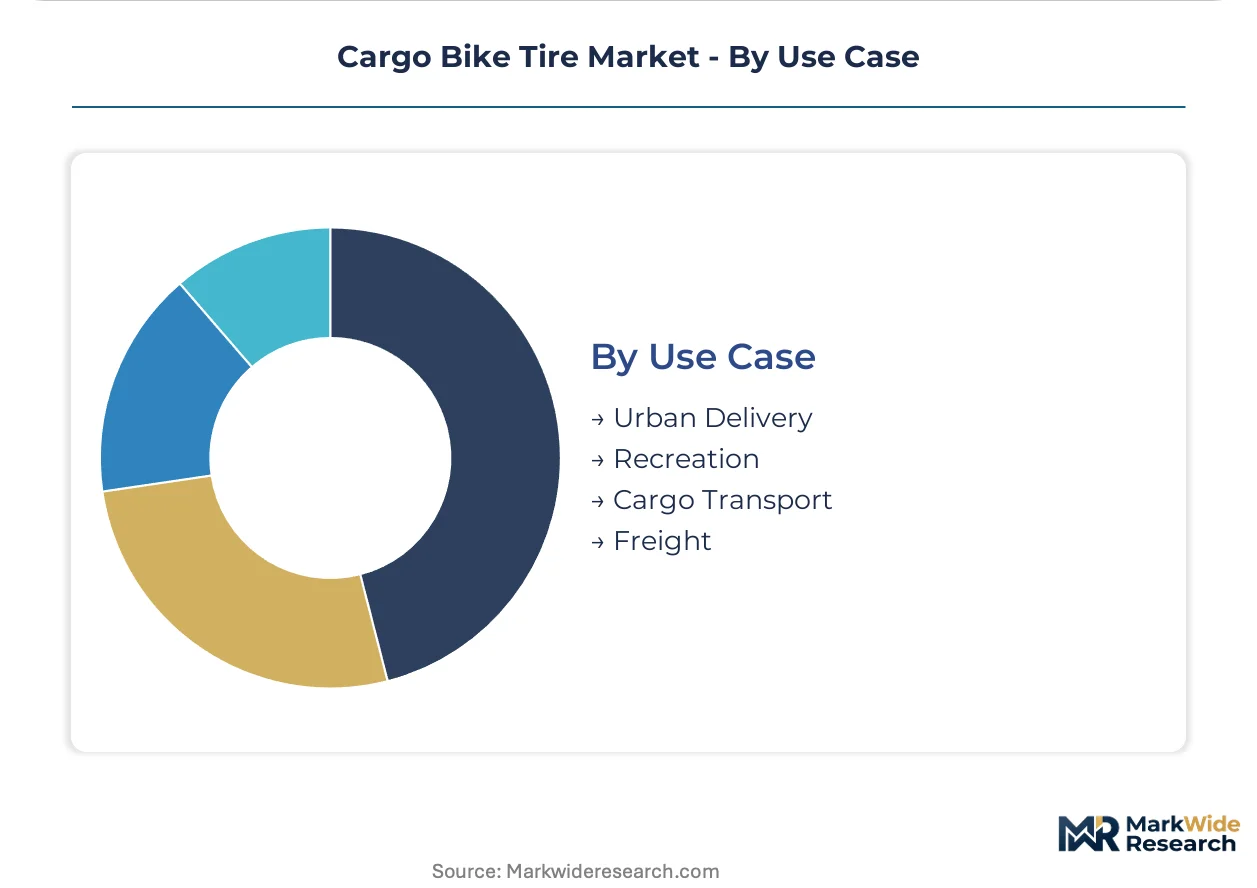
Use Case:
Customer-type concentration separates fleet procurement scale from fragmented individual purchasing, reshaping distribution channel requirements.
- Urban Delivery:Scheduled route optimization demands predictable wear rates and centralized tire management contracts. Large logistics integrators in Belgium and Denmark specify performance metrics through tender processes rather than individual maintenance decisions.
- Freight:Heavy-load specifications exceed standard bicycle ratings for gross vehicle weights above 250 kg. Amsterdam and Rotterdam cycling infrastructure density enables commercial adoption at scale, creating sustained replacement demand for aramid-reinforced constructions.
- Cargo Transport:Mixed-use configurations balance payload capacity with recreational versatility for individual owners.
- Recreation:Lower duty cycles prioritize comfort and aesthetics over puncture resistance ratings.
Freight retains volume leadership in commercial replacement cycles; Urban Delivery expands most quickly as consolidated fleet procurement displaces fragmented shop-level purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across European markets. German fleet operators absorb premium pricing for certified specifications, while Southern European buyers prioritize cost efficiency in replacement cycles.
Germany
KBA homologation protocols enforce stringent load-rating disclosures that elevate certified tire specifications. EU Green Deal emission targets compress commercial vehicle replacement cycles in Berlin and Hamburg logistics networks. Munich anchors OEM specification development through integrated testing partnerships with compound formulators.
Netherlands
Amsterdam and Rotterdam cycling infrastructure density enables commercial freight adoption at unmatched scale. National transport safety subsidies accelerate cargo bike fleet procurement across Randstad metropolitan distribution networks. Eindhoven-based logistics integrators specify tubeless configurations as standard for vehicles above 200 kg gross weight.
France
ANSM commercial freight incentives create underpenetrated demand in Paris and Lyon metropolitan corridors. Divergent national transport safety testing protocols complicate pan-European product homologation for non-integrated suppliers. Île-de-France logistics operators prioritize puncture-resistant breakers where debris penetration risks escalate in dense urban cores.
Belgium
Antwerp and Ghent logistics clusters drive standardized fleet procurement through centralized tender processes. REACH chemical compliance costs disadvantage smaller distributors lacking in-house compounding capabilities. Brussels-based integrators consolidate tire performance metrics specification, shifting pricing power toward volume buyers.
Denmark
Copenhagen historic street networks favor compact 20-inch formats with tighter turning radii. National cycling infrastructure investments sustain replacement demand for heavy-duty tire specifications. Danish operators specify aramid-reinforced constructions for refrigerated last-mile delivery extending into peri-urban zones.
Cargo Bike Tire Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated compound formulators command premium positioning through proprietary rubber formulations and captive testing protocols. Commodity assemblers compete on scale and distributor relationships. Strategic moves center on backward integration into raw material sourcing and direct fleet procurement channel development.
Within the integrated formulator tier, Schwalbe and Continental AG exemplify archetypes that anchor European OEM relationships through technical service capabilities. Cheng Shin Rubber Ind occupies a position among scale-driven Asian manufacturers supplying standardized specifications to price-sensitive replacement markets. These three represent the structural divergence between premium technical positioning and volume cost efficiency that defines competitive dynamics.
| Leading Market Players |
|---|
| Schwalbe |
| Continental AG |
| Michelin |
| Cheng Shin Rubber Ind |
| Kenda Tires |
| Maxxis International |
| Vittoria |
| Hutchinson |
| Pirelli |
| Others |
Value Chain & Pricing Dynamics
Polyurethane foam core substitution for pneumatic structures simultaneously relocates manufacturing toward German compound formulators and compresses margin pools for commodity tire assemblers. This material transition rewards integrated producers with captive R&D capabilities while exposing spot-market rubber buyers to cost volatility.
Pricing Analysis
After-sales service revenue through tire management contracts drives lifetime value for integrated formulators. Three-tier pricing structure across premium, standard, and economy levels separates Kevlar-reinforced specifications from nylon breaker tiers and basic rubber compounds. Cost compression in mid-tier segments is intensifying because REACH compliance extends R&D timelines for non-integrated suppliers. Fleet procurement managers at Belgian logistics integrators exhibit lowest price sensitivity, while individual shop-level purchasers in Southern Europe prioritize unit cost over wear ratings.
Supply Chain Analysis
Southeast Asian natural rubber sourcing channels represent the dominant chokepoint for compound cost stability. Manufacturing gravity centers on Germany, the Netherlands, and Taiwan, with raw material dependencies spanning Thai and Indonesian rubber plantations, Chinese synthetic polymer feedstocks, and Belgian aramid fiber processing. Single-source vulnerability in natural rubber supply transmits price shocks directly to mid-tier assemblers. Distribution runs through centralized fleet procurement channels in Northern Europe alongside legacy distributor networks serving fragmented replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airless tire prototypes threaten incumbent pneumatic market share, forcing compound formulators to defend their installed base through material science differentiation and service contract stickiness.
For Market Incumbents: Secure backward integration into bio-based polyol development ahead of F-Gas Regulation enforcement deadlines. Anchor OEM relationships through integrated testing protocols that smaller competitors cannot replicate. Defend against airless substitution by emphasizing tubeless downtime reduction metrics in fleet operator tenders. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany opens access to pan-European fleet procurement. Target French commercial freight incentives in Paris and Lyon metropolitan corridors where demand remains underpenetrated. Enter through direct tire management contracts bypassing established distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier assemblers lacking in-house compounding capabilities. Five-to-ten year viability hinges on material substitution defense and regulatory compliance scalability. Monitor KBA homologation backlog as inflection indicator for product launch velocity and market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polyols | German formulators accelerate development to maintain airless product roadmaps ahead of F-Gas enforcement. |
| Direct Fleet Procurement Channel Development | Compound formulators capture service revenue through integrated tire management contracts with Belgian integrators. |
| Kevlar-Nylon Hybrid Breaker R&D Investment | Material convergence enables lighter-weight puncture resistance for refrigerated last-mile delivery expansion. |
| CE Marking Fast-Track Partnership | Notified body relationships compress homologation timelines for pan-European product launches. |
| Tubeless Bead-Lock Configuration Scale-Up | Dutch fleet operators specify these as standard for vehicles above 200 kg gross weight. |
Study Parameters
A spread of perspectives from fleet procurement managers, compound formulation chemists, tire distributor principals, and KBA homologation officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through EU trade statistics, ECHA regulatory filings, customs import records, and SEC disclosures from listed tire manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the projection horizon.
Segmentation dimensions modeled include product type, material composition, diameter specification, and use case category. Value and volume outputs rest on elasticity-adjusted demand curves and replacement cycle assumptions throughout the forecast period. CAGRs derive from regression analysis against fleet electrification mandates, cycling infrastructure investment flows, and commercial vehicle registration trends.
Decision-makers should treat outputs as directional under stable regulatory enforcement and raw material supply continuity assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation amendments and REACH chemical restriction timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Industrial Tire Market