
 Automotive Airless Tire Market | 2026-2036
Automotive Airless Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Airless Tire Market Analysis
South Korean tire compounders is repositioning capacity toward thermoplastic elastomer formulations for non-pneumatic structures. Michelin Group leverages its Tweel manufacturing footprint to anchor airless tire production for industrial applications. Bridgestone Corporation sustains R&D intensity through its advanced polymer research centers in Japan and the United States. Continental AG differentiates via integrated sensor embedding for tire-health monitoring in airless architectures.
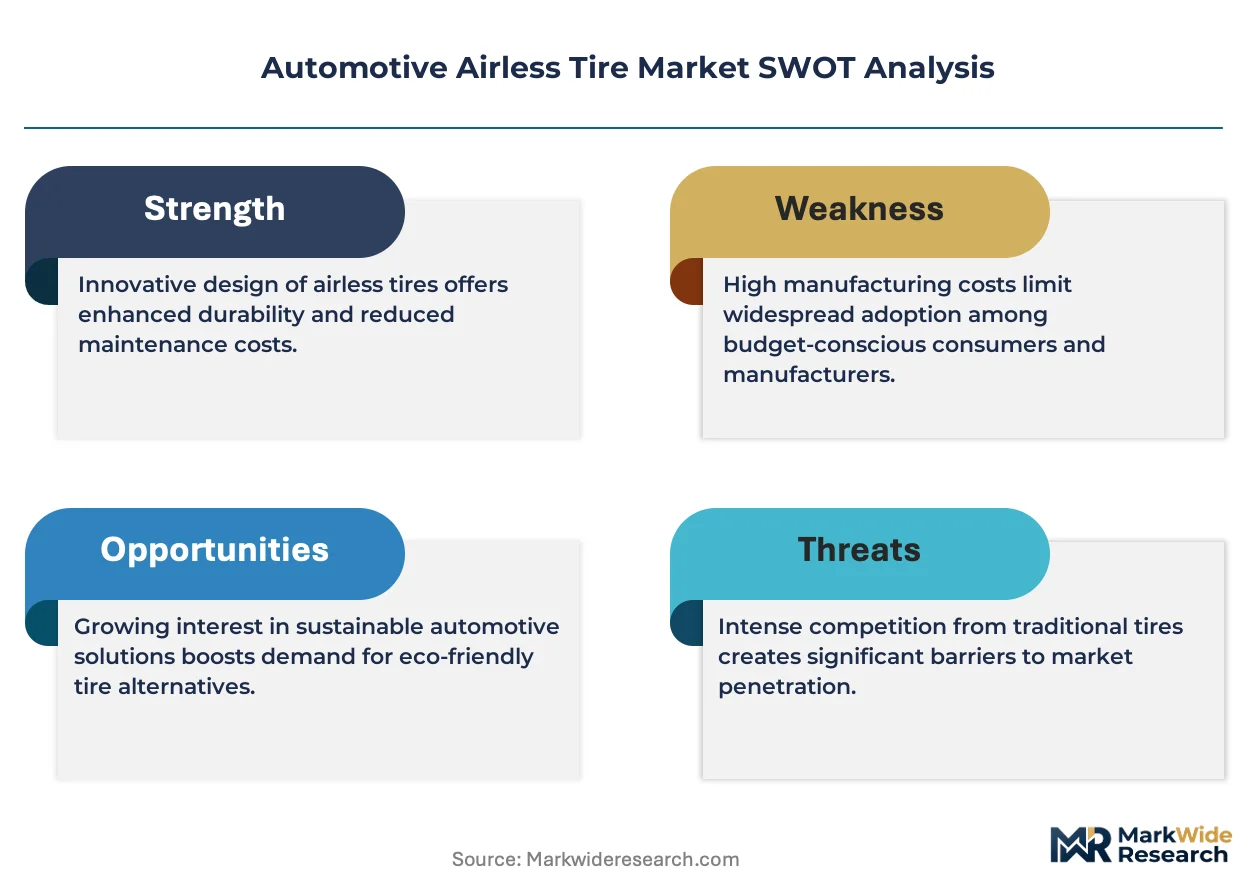
Automotive airless tires eliminate pneumatic inflation through load-bearing structures—typically polyurethane spokes, reinforced composite bands, or metallic flex-elements—engineered to deform under load while maintaining constant ground contact pressure. These structures serve commercial and mobility applications where puncture elimination, reduced maintenance intervals, and uniform wear profiles outweigh ride-comfort trade-offs. Passenger vehicles dominate current material demand, with polyurethane formulations capturing the largest volume share due to moldability and fatigue resistance. Electric vehicle applications represent the fastest-expanding application segment, as hubless and lattice-structure technologies align with torque-dense powertrains and reduced unsprung mass targets.
The U.S. Department of Transportation's Federal Motor Vehicle Safety Standards, the European Union's REACH chemicals framework, and Japan's JIS tire performance standards collectively govern material composition, rolling resistance benchmarks, and market access for non-pneumatic tire architectures. ECHA scrutiny of isocyanate-based polyurethane precursors is reshaping formulation roadmaps across compounders. Stakeholders must monitor regulatory divergence between DOT durability testing protocols and EU rolling-noise certification requirements, as compliance asymmetry will determine which technology variants achieve cross-border scale.
Market Dynamics
Fleet operators in last-mile delivery are accelerating airless tire trials as operational cost pressures mount from fuel volatility and labor shortages. This demand pull is compressing development timelines across compounders and tier suppliers.
Growth Catalysts
- Last-mile fleet electrification:Electric delivery vans require reduced unsprung mass and zero-maintenance tire architectures. Hubless designs align with torque-dense powertrains.
- DOT commercial vehicle standards:Updated Federal Motor Vehicle Safety Standards for non-pneumatic alternatives are accelerating certification pathways for heavy-duty variants.
- Thermoplastic elastomer advances:South Korean compounders are repositioning capacity toward fatigue-resistant formulations that enable thinner spoke geometries.
Market Restraints
- Isocyanate precursor costs:ECHA scrutiny of polyurethane raw materials under REACH is constraining formulation flexibility and elevating compound costs.
- Ride comfort trade-offs:Polyurethane spoke structures transmit higher vibrational frequencies than pneumatic alternatives, limiting passenger vehicle penetration.
- Tooling capital intensity:Mold fabrication for lattice geometries requires multi-axis machining capabilities concentrated in German and Japanese equipment suppliers.
Strategic Opportunities
- Autonomous shuttle deployments:Fixed-route mobility services in Germany are integrating airless prototypes to eliminate roadside maintenance events.
- Sensor-embedded architectures:Integrated tire-health monitoring systems create data monetization pathways for fleet management platforms.
- Industrial off-highway expansion:Construction and agriculture equipment operators are piloting non-pneumatic designs for puncture-prone environments.
Industry Challenges
- Cross-border certification asymmetry:Divergence between DOT durability protocols and EU rolling-noise requirements forces parallel testing tracks.
- Polymer fatigue modeling:Predictive lifespan simulation for thermoplastic elastomers under combined thermal and mechanical loading remains immature.
- Legacy wheel hub incompatibility:Existing axle standards assume pneumatic tire compliance, complicating retrofit pathways for aftermarket conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Airless Tire Market |
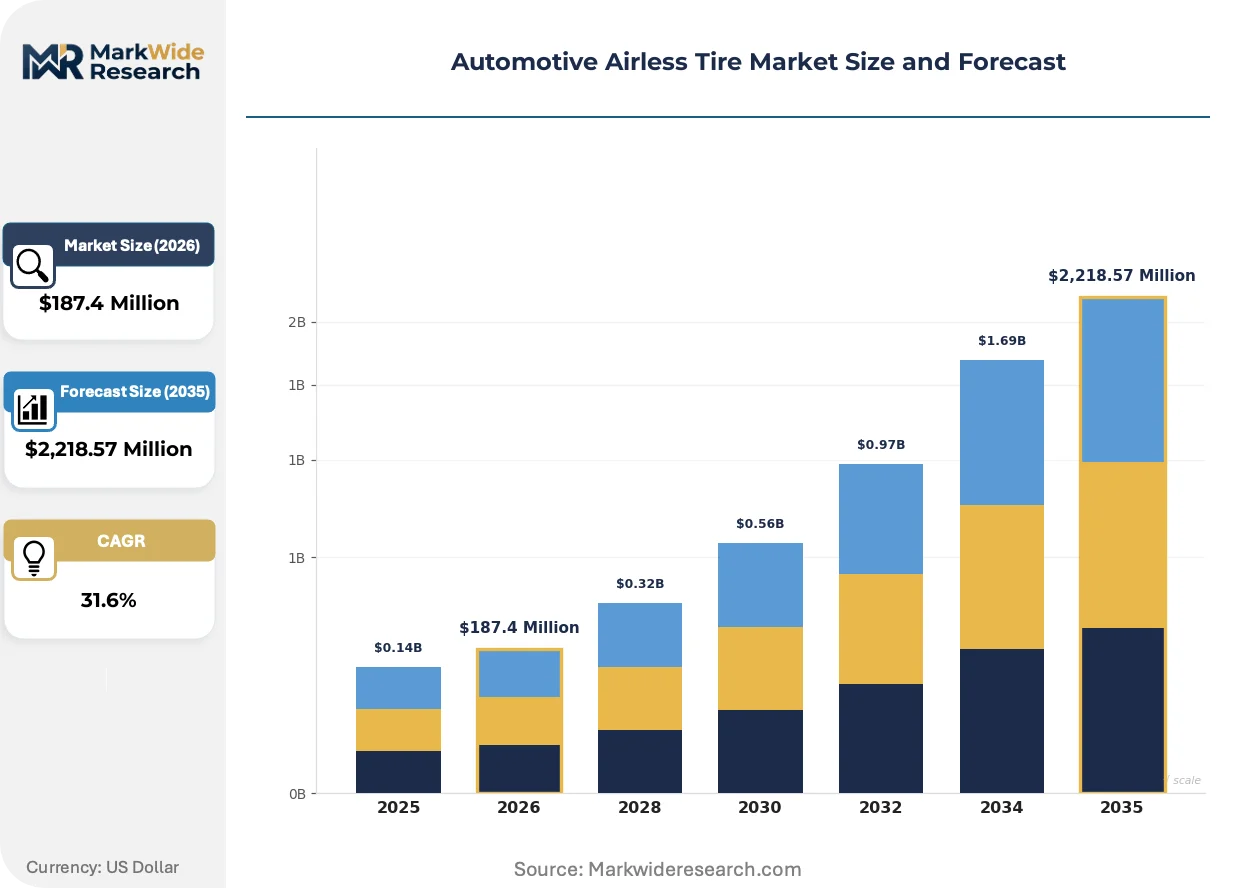
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,218.57 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vehicles, Commercial Vehicles, Specialty Vehicles, Off-Road Vehicles Material: Polyurethane, Rubber Composites, Reinforced Plastics, Metal Technology: Structural Mechanisms, Hubless Designs, Lattice Structures, Foam-Filled Designs Application: Motorcycles, Agricultural Equipment, Industrial Machinery, Electric Vehicles |
| Companies Covered | The Goodyear Tire & Rubber Company, Sumitomo Rubber Industries Ltd., Bridgestone Corporation, Yokohama Rubber Co., Ltd., Toyo Tire Corporation, Michelin Group, Hankook Tire & Technology Co., Ltd., Pirelli Tyre S.p.A., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Airless Tire Market Emerging Trajectories
Material science advances and regulatory pressure on rolling resistance are converging to reshape how tire architectures deliver performance. Three developments are commanding R&D allocation.
Lattice-structured thermoplastic elastomers are absorbing vibrational energy through geometric deformation rather than material compression. Electric vehicle platforms in Germany are adopting these designs to extend range through mass reduction. The technology is compressing the traditional trade-off between durability and ride quality that has constrained airless adoption.
REACH chemicals framework scrutiny of isocyanate-based precursors is forcing reformulation roadmaps across European compounders. The industrial consequence is accelerated development of bio-based polyurethane alternatives with equivalent fatigue resistance. Heavy-duty commercial segments are most affected, as load-bearing requirements resist simple material substitution.
Fleet procurement departments are consolidating tire specifications around total-cost-of-ownership metrics rather than unit price. This shift is displacing traditional distributor relationships with direct manufacturer partnerships in North American logistics networks. The behavioral change is most visible among regional parcel carriers operating electric van fleets.
Automotive Airless Tire Market Segmentation
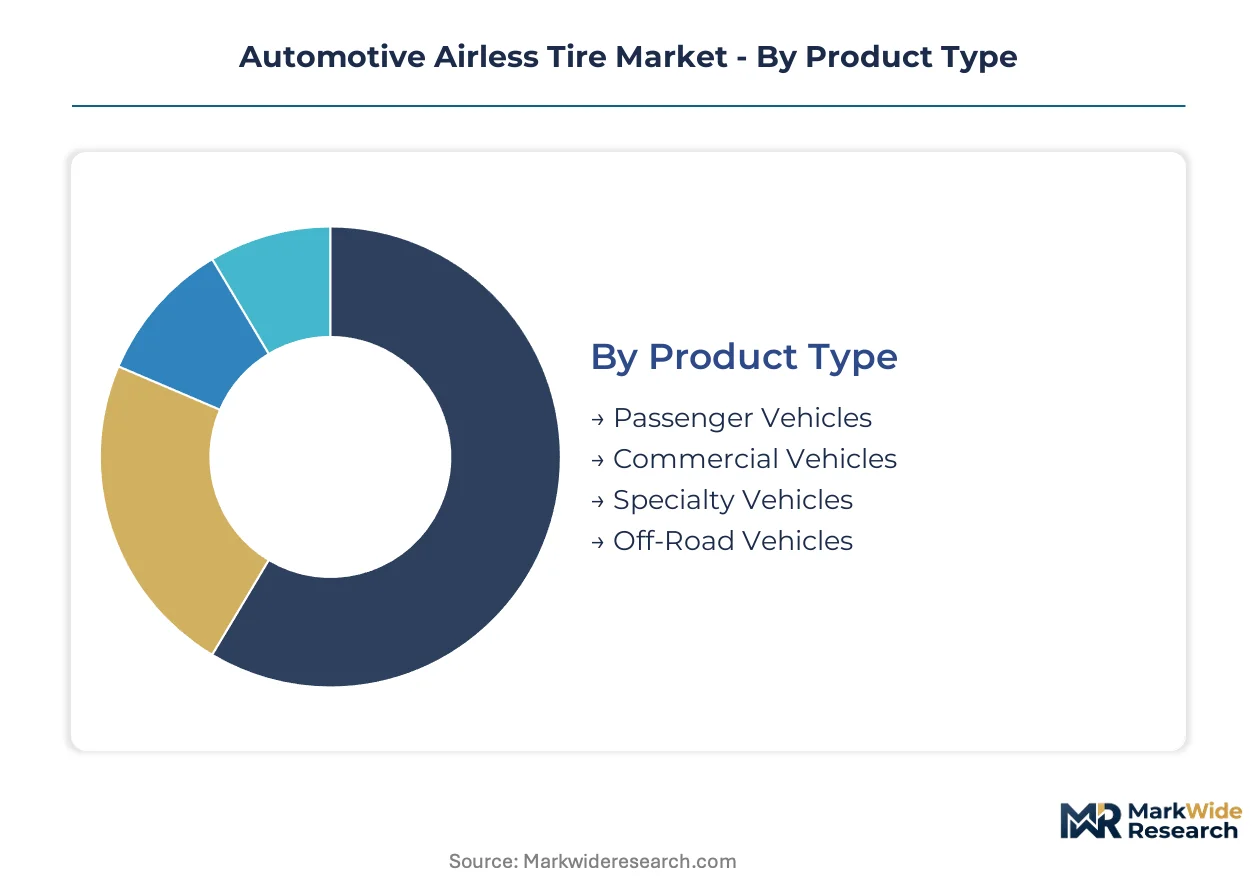
Segmentation in automotive airless tires reveals how material choices and architectural designs map to distinct operational requirements across vehicle categories. Each dimension—product type, material composition, structural technology, and end-use application—carries different margin profiles and certification burdens that reshape supplier priorities.
Product Type:
Standalone tire replacements dominate aftermarket revenue, while embedded wheel-tire assemblies capture OEM integration contracts for new vehicle platforms.
- Passenger Vehicles:Polyurethane spoke architectures with tuned stiffness profiles address ride comfort objections that previously limited consumer acceptance. German electric vehicle platforms are piloting these designs to reduce unsprung mass and extend driving range. Ride quality trade-offs remain the primary constraint against mass adoption.
- Commercial Vehicles:Reinforced composite band structures withstand higher axle loads and sustained highway speeds. Last-mile delivery fleets in the United States are accelerating trials to eliminate roadside maintenance events and reduce vehicle downtime. DOT certification timelines for heavy-duty variants are compressing as safety data accumulates.
- Specialty Vehicles:Custom geometries for emergency response and military applications prioritize puncture immunity over rolling efficiency.
- Off-Road Vehicles:Aggressive tread-integrated flex-elements handle irregular terrain without pressure loss.
Commercial vehicles lead volumes today; passenger vehicles are gaining share fastest.
Material:
Cost tiers separate commodity formulations from engineered compounds with fatigue-resistant molecular architectures.
- Polyurethane:Thermoplastic elastomer formulations enable injection molding of complex lattice geometries with consistent wall thickness. South Korean compounders are repositioning capacity toward these materials to supply German OEM programs. ECHA scrutiny of isocyanate precursors under REACH is forcing reformulation roadmaps.
- Rubber Composites:Natural rubber and synthetic blends deliver elastic recovery for high-cycle applications. Agricultural equipment operators in Brazil are testing these materials for puncture-prone field conditions. Raw material volatility constrains long-term supply contracts.
- Reinforced Plastics:Glass and carbon fiber loading improves stiffness-to-weight ratios for hubless designs.
- Metal:Titanium and aluminum flex-elements serve extreme load-bearing requirements in industrial machinery.
Polyurethane dominates current production; rubber composites are climbing the fastest.
Technology:
Maturity levels vary from proven structural mechanisms to developmental lattice architectures still resolving manufacturing repeatability.
- Structural Mechanisms:Cantilevered spoke arrays deform under load while maintaining constant ground contact pressure. These designs serve industrial forklifts and airport ground support equipment where low-speed durability outweighs ride quality concerns. Michelin's Tweel manufacturing footprint anchors production scale.
- Hubless Designs:Torque transmission through the tire periphery eliminates central axle connections. Electric vehicle platforms favor these architectures for packaging efficiency and mass distribution. Tooling capital intensity limits supplier participation.
- Lattice Structures:Triangulated thermoplastic geometries absorb energy through geometric deformation rather than material compression.
- Foam-Filled Designs:Closed-cell polyurethane cores provide pneumatic-like compliance without inflation systems.
Structural mechanisms anchor installed base; hubless designs show steepest expansion trajectory.
Application:
Customer types span individual consumers, fleet procurement departments, and industrial equipment operators with distinct total-cost-of-ownership calculations.
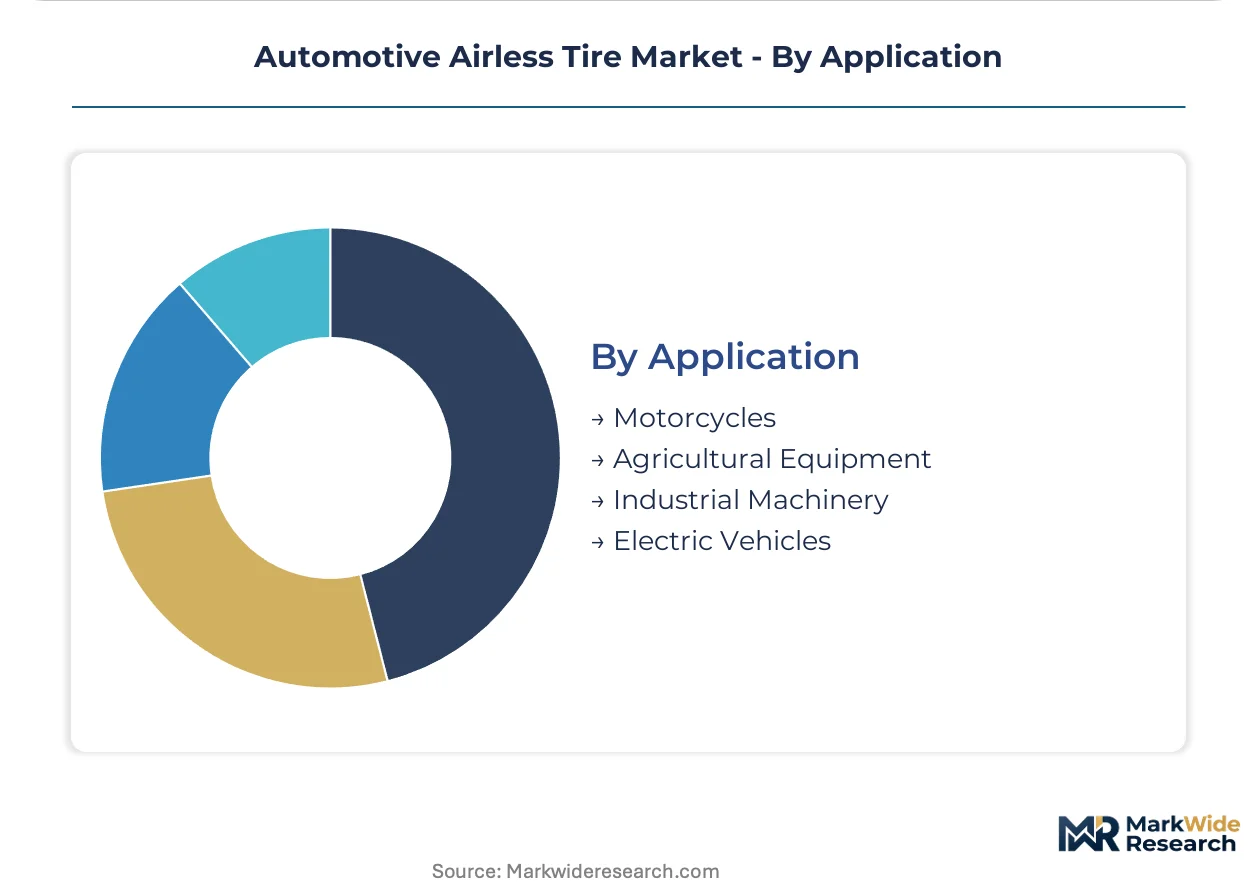
- Electric Vehicles:Hubless and lattice architectures align with torque-dense powertrains and reduced unsprung mass targets. German automotive OEMs are integrating airless prototypes into next-generation platforms. Range extension benefits justify premium pricing against conventional tires.
- Motorcycles:Two-wheel stability demands demand precise lateral stiffness control that spoke geometries struggle to deliver. Japanese manufacturers are developing motorcycle-specific variants under JIS performance standards. Market penetration remains limited by handling dynamics concerns.
- Agricultural Equipment:Puncture elimination in field debris environments drives operator interest.
- Industrial Machinery:Forklifts and port equipment prioritize zero-maintenance operation over speed ratings.
Industrial machinery leads current deployment; electric vehicles are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive OEMs integrate airless prototypes into electric vehicle platforms faster than Japanese manufacturers, where JIS certification timelines for non-pneumatic alternatives remain more conservative.
United States
Last-mile delivery fleets in California and Texas accelerate airless tire trials to eliminate roadside maintenance. NHTSA's updated Federal Motor Vehicle Safety Standards compress certification pathways for heavy-duty commercial variants. Detroit's automotive supplier corridor hosts compounders repositioning toward thermoplastic elastomer formulations.
Germany
Electric vehicle platforms from Stuttgart and Munich integrate hubless designs to reduce unsprung mass and extend range. KBA oversees rolling-noise certification requirements that diverge from DOT durability protocols. Bavaria's polymer research clusters concentrate lattice-structure tooling capabilities.
Japan
JIS tire performance standards govern material composition and rolling resistance benchmarks for non-pneumatic architectures. METI supports advanced polymer research through national technology programs. Nagoya's industrial belt anchors composite band manufacturing for reinforced structures.
South Korea
Tire compounders reposition capacity toward fatigue-resistant thermoplastic elastomer formulations. MFDS and national standards bodies monitor chemical safety in polyurethane precursors. Gyeonggi Province's materials science parks supply German OEM programs with engineered compounds.
China
MIIT's GB standards framework governs tire performance and material safety for domestic commercial vehicle deployment. Dual carbon goals accelerate interest in reduced-maintenance tire architectures for electric logistics fleets. Yangtze River Delta manufacturing hubs prototype hubless designs for torque-dense powertrains.
Automotive Airless Tire Market Vendor Landscape
German producers anchor one tier; Japanese specialists hold advanced polymer research positions. The vendor base concentrates around integrated tire-wheel assemblies and standalone replacement products. Three archetypes dominate: diversified rubber conglomerates with airless R&D divisions, pure-play non-pneumatic technology developers, and industrial equipment specialists leveraging existing maintenance-free tire footprints. Capacity expansion and strategic partnerships represent the dominant competitive vectors.
Within the diversified conglomerate tier, Michelin Group and Bridgestone Corporation exemplify scale-driven positions, while Continental AG occupies a sensor-integration specialization. Yokohama Rubber Co., Ltd. represents the Japanese specialist archetype with polymer research concentration.
| Leading Market Players |
|---|
| The Goodyear Tire & Rubber Company |
| Sumitomo Rubber Industries Ltd. |
| Bridgestone Corporation |
| Yokohama Rubber Co., Ltd. |
| Toyo Tire Corporation |
| Michelin Group |
| Hankook Tire & Technology Co., Ltd. |
| Pirelli Tyre S.p.A. |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compounders in South Korea and Germany anchor supply-side discipline, translating captive thermoplastic elastomer capacity into pricing power against commodity polyurethane importers. Fleet procurement consolidation toward total-cost-of-ownership metrics compresses distributor margins while rewarding direct manufacturer relationships with volume premiums.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for fatigue-resistant thermoplastic formulations, displacing legacy isocyanate-based compounds. Three-tier pricing structure across premium, standard, and economy levels separates sensor-embedded OEM assemblies from aftermarket standalone replacements and industrial retrofit kits. Cost compression in standard-grade polyurethane stems from ECHA reformulation mandates elevating raw material expenses. Last-mile delivery fleets exhibit highest price sensitivity due to thin operating margins, while German automotive OEMs absorb premium positioning for range-extending hubless designs.
Supply Chain Analysis
Dual-sourcing requirements from NHTSA and KBA certification protocols compounders to maintain qualified suppliers across Germany, South Korea, and Japan simultaneously. Tooling for lattice geometries draws from Bavarian and Nagoya equipment clusters, while thermoplastic elastomer feedstocks hinge on Gyeonggi Province petrochemical complexes. Single-source vulnerability concentrates in multi-axis mold fabrication capabilities. Distribution runs through Tier 1 supplier integration contracts and direct fleet procurement platforms, bypassing traditional aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Fleet procurement departments are consolidating specifications around premium sensor-embedded architectures that monetize tire-health data.
For Market Incumbents: Deepen backward integration into thermoplastic elastomer compounding to defend margin position against South Korean feedstock volatility. Anchor certification investment in parallel DOT and KBA testing tracks to preempt cross-border asymmetry risks. Prioritize lattice-structure tooling partnerships with Bavarian equipment specialists before capacity scarcity hardens. For New Entrants and Emerging Players: Capture industrial off-highway segments in Brazil and Australia where puncture-prone environments justify premium positioning against commodity pneumatic alternatives. Agricultural equipment operators present the most penetrable white space due to limited incumbent R&D focus. Pursue direct partnerships with construction fleet operators rather than distributor channel builds. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play non-pneumatic technology developers with proven JIS certification pathways. Long-term viability favors compounders with demonstrated fatigue-resistant formulation libraries and captive OEM integration contracts. Watch for inflection when German OEMs announce series-production platform commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermoplastic Elastomer Compounding | Captive feedstock supply insulates margin structure from ECHA-driven isocyanate cost volatility. |
| Dual-Certification Investment (DOT/KBA) | Parallel testing tracks unlock cross-border scale for heavy-duty commercial variants. |
| Sensor-Embedded Architecture Development | Integrated tire-health monitoring creates data monetization pathways for fleet management platforms. |
| Industrial Off-Highway Partnership Expansion | Construction and agriculture equipment pilots in Brazil establish puncture-immunity proof points. |
| Lattice-Structure Tooling Partnership | Bavarian multi-axis machining capabilities concentrate manufacturing repeatability for hubless designs. |
Methodological Framework
Direct dialogue with Tier 1 supplier procurement managers, OEM platform engineers, fleet operations directors, and aftermarket distribution heads grounded qualitative assessment. Secondary validation drew from NHTSA FMVSS filings, KBA rolling-noise certification databases, ECHA REACH substance evaluations, and vehicle production registries. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity assumptions.
Bottom-up modeling anchored volume projections across vehicle class, propulsion architecture, structural technology type, and regional production cluster. CAGRs derived from segment-level elasticity analysis applied to base-year penetration rates. Industry-specific inputs incorporated DOT certification timeline compression, JIS standard evolution, and fleet electrification capex cycles.
Regulatory divergence between DOT durability protocols and EU rolling-noise requirements, polymer fatigue modeling immaturity, and legacy axle standard incompatibility are the dominant revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Smart Tire Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Airless Tires Market