
 Latin America Automotive Parts Magnesium Die Casting Market | 2026-2036
Latin America Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Automotive Parts Magnesium Die Casting Market Foresight
Multi-source procurement for magnesium die-cast chassis components is broadening across Latin American automotive supply chains. Gibbs Die Casting Group leverages its North American footprint to serve Mexican assembly plants with just-in-time delivery. Meridian Lightweight Technologies anchors regional demand through specialized thin-wall casting capabilities for structural automotive parts. George Fischer AG competes via integrated alloy development and precision machining operations.
Automotive parts magnesium die casting employs high-pressure injection of AZ91D and AM60B alloys into hardened steel molds at temperatures exceeding 680°C, producing net-shape components with density one-quarter that of steel. The process primarily serves vehicle weight reduction mandates without sacrificing structural integrity in crash-critical assemblies. Transmission housings dominate current volume given their geometric complexity and favorable strength-to-weight ratio, while electric vehicle battery trays represent the fastest-expanding application segment as OEMs pursue range optimization. Wheels retain mature demand patterns in premium passenger segments where forged magnesium commands sustained price premiums.
INMETRO certification requirements in Brazil and NOM standards in Mexico govern alloy composition and fatigue performance for safety-critical castings, directly influencing supplier qualification timelines. The USMCA rules of origin framework shapes cross-border sourcing decisions, compelling Mexican foundries to document regional content shares for duty-free access to US vehicle assemblers. Stakeholders must monitor evolving EPA fuel economy standards and their translation into OEM lightweighting targets to anticipate procurement shifts.
Market Dynamics
USMCA rules of origin and INMETRO efficiency mandates are compressing supplier qualification timelines while forcing magnesium die casters to document regional content shares for duty-free access to Detroit Three assemblers across Mexico and Brazil.
Growth Catalysts
- INMETRO efficiency mandates:Brazil's vehicle fuel economy standards compel OEMs to source lightweight powertrain components, directly expanding magnesium procurement for transmission housings and engine blocks.
- Thin-wall casting capabilities:Specialized high-pressure die casting processes now achieve wall thickness below 1.5mm for structural automotive parts, enabling weight reductions without sacrificing crash integrity.
- Central Mexican industrial corridors:Foundry clusters in Querétaro and Guanajuato serve Detroit Three assembly plants with just-in-time delivery windows under 48 hours.
Market Restraints
- Primary magnesium supply concentration:Latin American foundries depend on Chinese smelter output for alloy feedstock, exposing margins to export quota volatility and ocean freight rate spikes.
- AZ91D alloy corrosion limitations:Magnesium-aluminum-zinc compositions require costly surface treatments for underhood applications, constraining penetration in brake and steering components.
- USMCA regional content thresholds:Duty-free vehicle access demands 75% North American content, forcing Mexican casters to source secondary alloys from captive US suppliers at premium spreads.
Strategic Opportunities
- EV battery tray architectures:Electric vehicle platforms in Mexico's Bajío region are specifying magnesium structural enclosures for thermal management and range optimization.
- Brazilian northeastern foundry greenfield:Pernambuco and Ceará offer tax incentives under the Superintendência da Zona Franca de Manaus framework for exporters serving Mercosur assemblers.
- AM60B alloy qualification:Higher-ductility magnesium-manganese formulations are penetrating suspension control arms and steering knuckles previously reserved for aluminum forgings.
Industry Challenges
- High-pressure die casting toolmaking capacity:Hardened steel mold fabrication for 680°C magnesium injection requires specialized machining centers concentrated in Monterrey and São Paulo, creating 14-18 week lead times.
- NOM fatigue certification timelines:Mexican safety-critical casting approvals demand 500,000-cycle testing protocols that extend supplier onboarding to 8-12 months for new entrants.
- AZ91D-AM60B alloy segregation:Molten metal chemistry control requires real-time spectroscopy investment that mid-tier foundries struggle to amortize across sub-50,000-unit annual volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Automotive Parts Magnesium Die Casting Market |
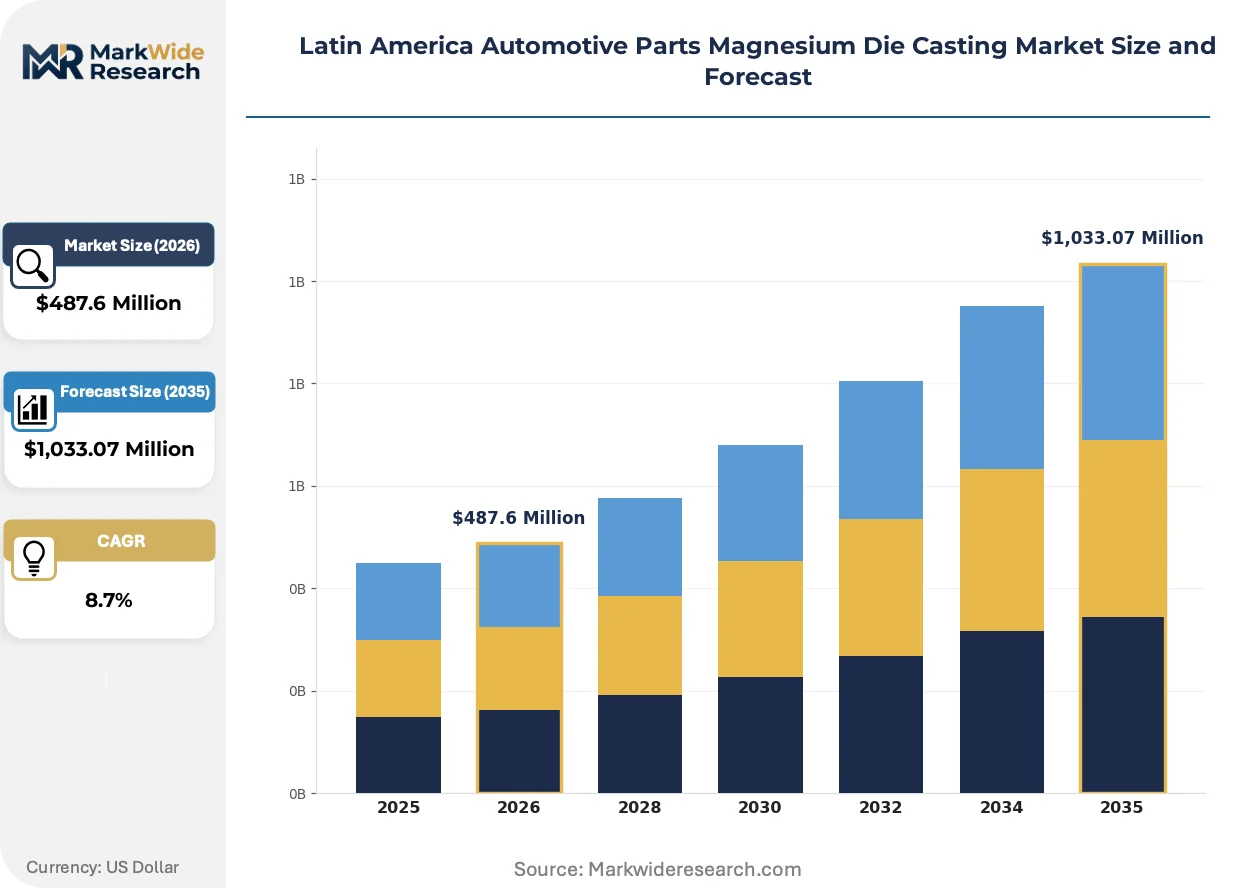
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Blocks, Transmission Housings, Wheels, Brackets Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Prototype, Mass Production, Custom Orders, High-Volume Production |
| Companies Covered | Gibbs Die Casting Group, Pace Industries, Shiloh Industries Inc., George Fischer AG, Meridian Lightweight Technologies, Brabant Alucast, Chicago White Metal Casting Inc, Continental Casting LLC, Magic Precision Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Automotive Parts Magnesium Die Casting Market Shifts & Advancements
Process metallurgy and regulatory compliance frameworks are converging to reshape how Latin American foundries qualify for OEM supply chains. Technical differentiation now hinges on alloy development capabilities and documented regional content rather than pure unit economics.
Semi-solid metal casting is absorbing investment from tier-one Mexican suppliers seeking to reduce porosity in transmission housings. OEMs in the Bajío region are qualifying thixomolded magnesium for clutch and gearbox enclosures that previously used aluminum high-pressure die casting. The technology is absorbing share from conventional processes by eliminating thermal fatigue defects that trigger warranty claims in stop-start powertrains.
USMCA regional value content rules are forcing Mexican magnesium casters to reconfigure alloy sourcing. Foundries must now document North American provenance for secondary magnesium to maintain duty-free status for finished components shipped to US vehicle assemblers. Tier-two suppliers in Querétaro are responding by establishing captive recycling partnerships with Ohio-based scrap processors.
Just-in-sequence delivery contracts are compressing inventory buffers across the Mexican supply base. Tier-one casters serving Detroit Three plants in Silao and Ramos Arizpe now hold sub-72-hour finished goods stocks, replacing traditional four-week safety inventories. This behavioral shift is most visible in transmission housing procurement, where OEMs penalize delivery variance with automatic price step-downs.
Latin America Automotive Parts Magnesium Die Casting Market Segmentation
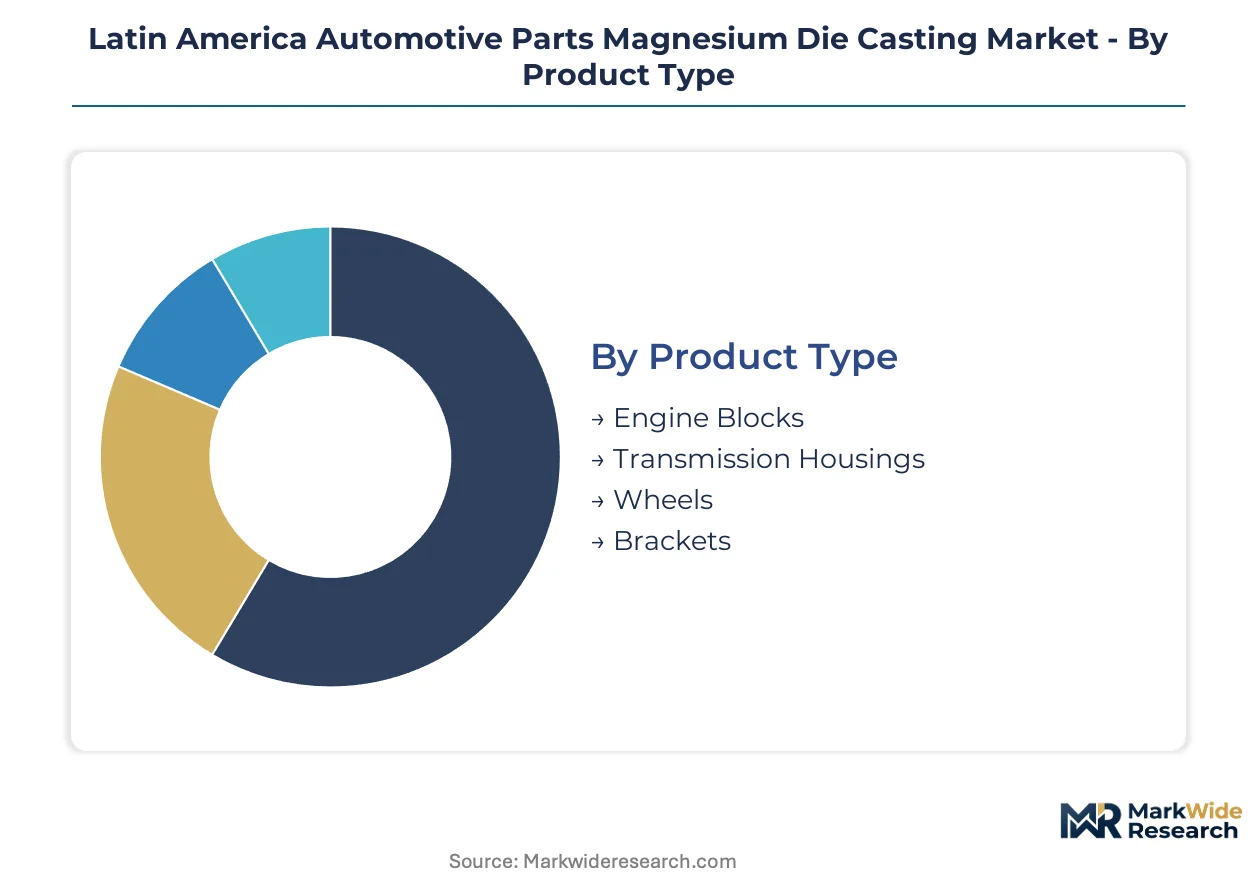
Magnesium die casting procurement patterns diverge sharply across product geometries and thermal loading requirements. OEM qualification protocols treat each segment as a distinct manufacturing competency, forcing foundries to specialize rather than compete across all categories.
Product Type:
Capital intensity clusters in segments requiring hardened steel tooling for complex geometries and sustained thermal cycling.
- Transmission Housings:These multi-cavity castings incorporate internal rib structures and bearing seats demanding 680°C injection precision. Querétaro foundries supply Detroit Three assembly plants with just-in-time delivery windows under 48 hours for clutch and gearbox enclosures. INMETRO efficiency mandates in Brazil accelerate procurement as OEMs pursue powertrain weight reduction.
- Engine Blocks:Cylinder bedplate and ladder frame castings require molten metal chemistry control with real-time spectroscopy investment. Mexican suppliers in Guanajuato concentrate capacity here due to proximity to Ramos Arizpe engine plants. AZ91D alloy segregation risks constrain mid-tier foundries from entering this segment.
- Wheels:Forged magnesium commands sustained price premiums in premium passenger segments where cosmetic finish standards apply.
- Brackets:Structural mounting hardware for HVAC and steering assemblies offers lower barrier to entry for smaller foundries.
Transmission housings absorb the bulk of installed capacity; engine blocks are expanding most quickly as EV powertrain architectures create new thermal management casting requirements.
Application:
End-use demand concentrates where vehicle weight directly correlates with regulatory compliance or range optimization.
- Electric Vehicles:Battery tray architectures in Mexico's Bajío region specify magnesium structural enclosures for thermal management. OEMs specify AM60B alloy formulations for improved ductility in crash-critical assemblies. USMCA regional content thresholds force casters to document North American provenance for duty-free status.
- Passenger Vehicles:High-pressure die casting for door inner panels and seat frames serves volume production in São Paulo and Mexico City metropolitan markets. Thin-wall capabilities below 1.5mm enable weight reductions without sacrificing structural integrity.
- Commercial Vehicles:Fleet operators in Brazil prioritize durability over lightweighting, constraining magnesium penetration in heavy-duty segments.
- Motorcycles:Premium two-wheeler assemblers specify magnesium wheels and engine covers for performance positioning.
Passenger vehicles retain the deepest supplier qualification rosters; electric vehicle applications are climbing the fastest as OEMs pursue range optimization.
End User:
Procurement authority determines technical specification control and inventory liability allocation.
- OEMs:Direct sourcing of safety-critical castings requires NOM fatigue certification timelines extending 8-12 months for new entrants. Detroit Three assemblers in Silao specify alloy composition and surface treatment protocols that tier-one suppliers must execute.
- Tier-1 Suppliers:Gibbs Die Casting Group and Meridian Lightweight Technologies anchor regional demand through specialized thin-wall capabilities and just-in-sequence delivery contracts compressing inventory buffers to sub-72-hour stocks.
- Vehicle Assemblers:Bajío region plants integrate magnesium castings into final assembly sequences with minimal handling.
- Aftermarket Providers:Replacement wheel and bracket demand follows vehicle parc aging patterns with lower technical barriers.
Tier-1 suppliers command the majority of qualified production capacity; OEM direct sourcing is gaining share fastest as assemblers consolidate supply base control.
Manufacturing Stage:
Production scale determines tooling amortization feasibility and alloy sourcing economics.
- Mass Production:Annual volumes exceeding 50,000 units justify real-time spectroscopy investment for AZ91D-AM60B chemistry control. Central Mexican industrial corridors concentrate capacity serving Detroit Three with documented regional content shares.
- High-Volume Production:Dedicated lines for transmission housings achieve 14-18 week toolmaking lead times through Monterrey machining centers.
- Prototype:Low-volume validation castings support OEM platform development with softer tooling alloys.
- Custom Orders:Specialized geometries for motorsport and premium segments operate outside standard qualification protocols.
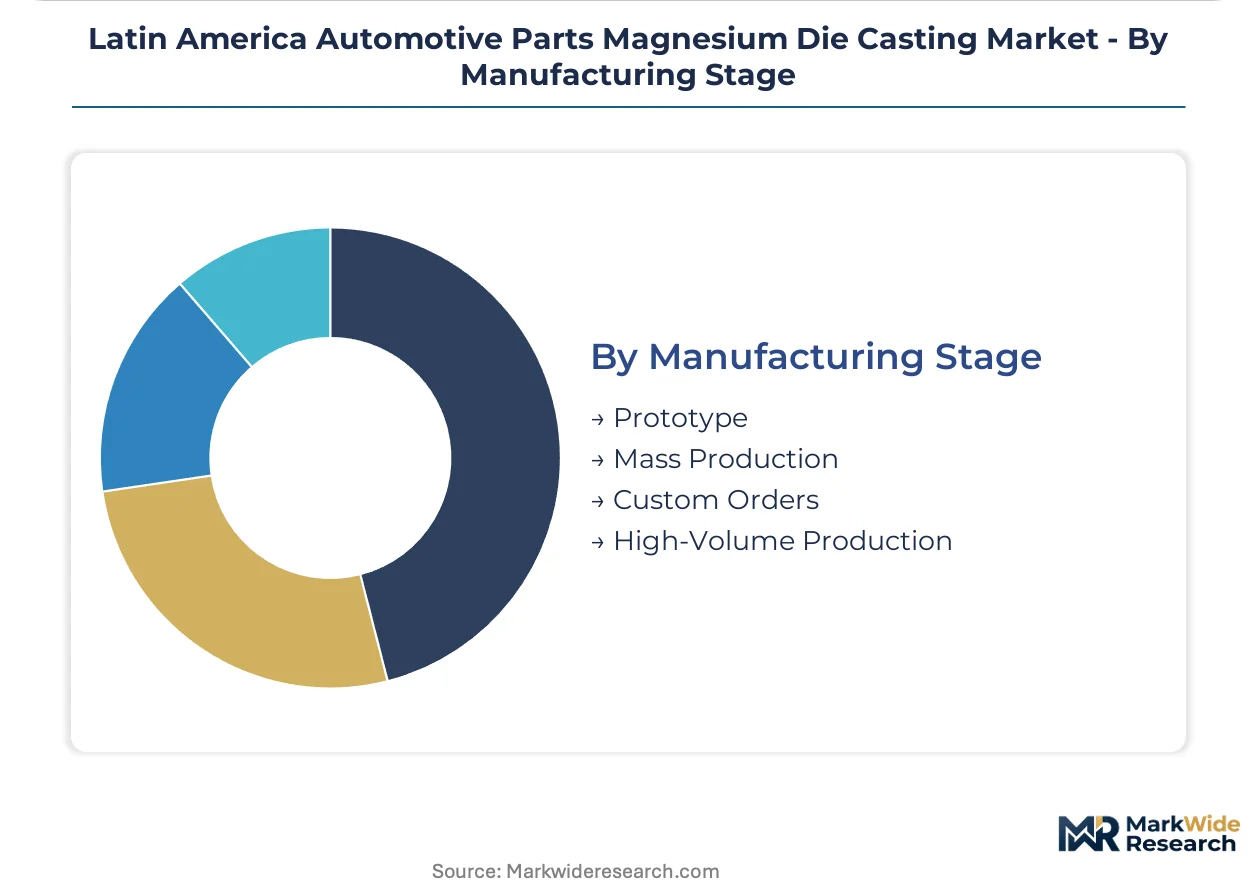
Mass production absorbs dominant tooling investment; high-volume production is scaling fastest as EV platform launches accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit Three assembly plants in central Mexico absorb the majority of qualified magnesium die casting capacity across Latin America. Brazilian OEMs drive secondary demand through INMETRO-mandated powertrain lightweighting programs.
Mexico
Querétaro and Guanajuato foundry clusters supply transmission housings to Ramos Arizpe and Silao assembly plants under 48-hour delivery windows. NOM fatigue certification protocols extend supplier qualification to 8-12 months for safety-critical castings. USMCA regional content thresholds compel casters to document North American alloy provenance for duty-free access to US markets.
Brazil
São Paulo metropolitan foundries concentrate capacity for passenger vehicle door inner panels and seat frames serving domestic OEMs. INMETRO vehicle efficiency mandates accelerate magnesium procurement for transmission housings and engine blocks. Pernambuco and Ceará offer Superintendência da Zona Franca de Manaus tax incentives for exporters targeting Mercosur assemblers.
Argentina
Córdoba industrial corridors host tier-two suppliers producing structural brackets for HVAC and steering assemblies. The country's national automotive regulator enforces alloy composition standards for crash-critical components. Buenos Aires province foundries struggle with AZ91D feedstock import dependence from Chinese smelters.
Chile
Santiago-based fabricators serve niche motorsport and premium motorcycle segments with custom magnesium wheels. The central bank's foreign exchange protocols influence capital equipment import timelines for high-pressure die casting machinery. Northern mining regions generate limited local demand for heavy-duty commercial vehicle applications.
Colombia
Bogotá metropolitan suppliers focus on aftermarket replacement wheels following vehicle parc aging patterns. The national standards body governs surface treatment specifications for corrosion-prone underhood applications. Medellín industrial zones attract limited OEM direct sourcing due to qualification timeline constraints.
Latin America Automotive Parts Magnesium Die Casting Market Competitive Landscape
Capacity expansion dominates the current landscape as tier-one suppliers retrofit lines for EV battery tray architectures. The vendor base concentrates around three strategic archetypes: North American multinationals with just-in-sequence delivery capabilities, European alloy specialists with integrated precision machining operations, and regional Mexican fabricators leveraging USMCA proximity advantages. M&A activity and captive recycling partnerships represent the primary competitive vectors as casters secure qualified secondary magnesium supply.
Among North American-based fabricators, Gibbs Die Casting Group and Pace Industries exemplify scale-driven archetypes with established Detroit Three relationships. Shiloh Industries Inc. occupies a position within the tier-one supplier tier serving structural automotive applications. European specialists George Fischer AG and Meridian Lightweight Technologies represent integrated alloy development capabilities with precision machining operations. These named entities anchor the competitive structure without exhaustively mapping the full vendor landscape.
| Leading Market Players |
|---|
| Gibbs Die Casting Group |
| Pace Industries |
| Shiloh Industries Inc. |
| George Fischer AG |
| Meridian Lightweight Technologies |
| Brabant Alucast |
| Chicago White Metal Casting Inc |
| Continental Casting LLC |
| Magic Precision Inc |
| Others |
Supply & Pricing Matrix
INMETRO efficiency mandates in Brazil gate qualified supply and premium-tier pricing access, forcing foundries to absorb NOM fatigue certification costs before capturing OEM contracts. Mexican suppliers face parallel pressure from USMCA regional content thresholds that document North American alloy provenance for duty-free status.
Pricing Analysis
Volume-scale producers command margin premiums while mid-tier foundries compete on unit economics. Three-tier pricing structure across premium, standard, and economy levels separates NOM-certified safety-critical castings from aftermarket brackets and prototype volumes. Price differentiation hinges on real-time spectroscopy investment and documented regional content shares. Cost compression in standard-tier transmission housings is intensifying because Chinese smelter export quota volatility feeds raw material uncertainty.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through just-in-sequence contracts compressing inventory buffers to sub-72-hour stocks. Geographic supply concentration centers on China for primary magnesium feedstock, the United States for secondary alloy scrap, and Mexico for finished casting production. Raw material dependencies rest on AZ91D and AM60B alloy formulations, hardened steel mold fabrication, and surface treatment chemicals. Single-source vulnerability from Chinese smelter concentration exposes Latin American foundries to ocean freight rate spikes and export license delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semi-solid metal casting is displacing conventional high-pressure die casting for transmission housings, creating technology-transition winners among alloy specialists with thixomolding capabilities.
For Market Incumbents: Deploy captive recycling partnerships to secure qualified secondary magnesium supply against Chinese export quota volatility. Foundries must retrofit lines for EV battery tray architectures before OEM platform launches consolidate supplier rosters. Backward integration into Ohio-based scrap processing addresses USMCA regional content thresholds. NOM fatigue certification investment defends share against mid-tier entrants lacking 8-12 month qualification timelines. For New Entrants and Emerging Players: Tier-two aftermarket providers in Colombia and Chile represent the most penetrable buyer archetype for corrosion-resistant bracket supply outside OEM qualification protocols. Pernambuco and Ceará tax incentives under Superintendência da Zona Franca de Manaus offer greenfield entry points for Mercosur exporters. Target motorsport and premium motorcycle wheel segments where cosmetic finish standards command price premiums and lower volume barriers apply. For Investors and Strategic Acquirers: AM60B alloy qualification for suspension control arms is the leading indicator that higher-ductility formulations are penetrating aluminum-forged applications. Long-term viability favors integrated alloy development capabilities with precision machining operations over pure-play foundries. Monitor thixomolding equipment orders from Querétaro suppliers as inflection signal for process technology displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycling Partnership | Secures USMCA-compliant secondary magnesium supply from Ohio-based scrap processors. |
| Thixomolding Capacity Addition | Enables porosity reduction for EV battery trays serving Bajío region OEM platforms. |
| NOM Fatigue Certification Investment | Unlocks 8-12 month supplier qualification for safety-critical Detroit Three contracts. |
| Pernambuco Greenfield Expansion | Leverages Superintendência da Zona Franca de Manaus incentives for Mercosur export access. |
| Real-Time Spectroscopy Deployment | Controls AZ91D-AM60B chemistry segregation for mass production volumes exceeding 50,000 units. |
Research Methodology
Trade databases, foundry association reports, and OEM procurement disclosures formed the secondary backbone of this analysis. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and foundry operations managers validated alloy sourcing patterns and qualification timelines. Bottom-up and top-down triangulation cross-checked production capacity estimates against vehicle build forecasts across the analysis window.
Bottom-up modeling aggregated individual foundry capacity and utilization rates while top-down approaches calibrated against vehicle production and content-per-vehicle assumptions. Segmentation dimensions included product type, propulsion architecture, OEM tier, and regional production cluster. CAGRs were derived from weighted average growth across these segments. Forecast inputs incorporated INMETRO mandate compliance trajectories and USMCA regional content threshold enforcement patterns.
Revisions become necessary when Chinese smelter export quotas tighten, USMCA rules of origin shift, or EV platform launches accelerate beyond base assumptions. Forecasts reflect documented assumptions about alloy price trajectories and certification timeline stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Fluids Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Russia Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Global Automotive Gear Shift System Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
Automotive OEM Brake Friction Material Market