
 United States Luxury Yacht Market | 2026-2036
United States Luxury Yacht Market Size, Share, and Industry Trends Forecast 2026-2036
United States Luxury Yacht Market Intelligence
Hybrid-electric propulsion architecture is reshaping how luxury yachts are engineered and commissioned in American shipyards. Trinity Yachts leverages its Gulf Coast facilities to anchor large-custom construction programs for clients seeking diesel-electric range extension. Westport Yachts sustains high-volume fiberglass production out of Washington State, competing on speed-to-delivery for semi-custom motor yacht buyers. Christensen Yachts specializes in carbon-composite superyacht hulls, differentiating through weight reduction that extends cruising range without sacrificing interior volume.
United States luxury yachts constitute privately owned, crewed vessels exceeding 24 meters in length, built from steel, aluminum, or advanced composites to deliver extended offshore cruising with hotel-grade amenities. Motor yachts dominate domestic order books due to their spacious deck plans and shorter delivery cycles, while sailing yachts retain niche appeal among performance-oriented owners who prioritize transoceanic autonomy. Eco-friendly solutions represent the fastest-growing technology segment as builders integrate battery banks and shore-power interfaces to meet emerging emissions protocols. Charter services now drive the largest share of new-build specification changes, with owners configuring layouts for dual private-commercial use to maximize asset utilization.
The EPA enforces Tier 4 marine engine standards that limit nitrogen oxide and particulate emissions from diesel propulsion, pushing builders toward exhaust after-treatment or alternative powertrains. The U.S. Coast Guard administers safety certification under 46 CFR subchapters that govern structural fire protection and lifesaving equipment, creating compliance cost barriers for smaller entrants. OSHA maritime standards govern shipyard worker exposure to fiberglass particulates and heavy-lift operations, shaping where and how hull construction expands. Stakeholders must monitor how California's proposed harbor electrification mandates spread to other coastal states, as shore-power readiness could become a decisive specification for resale value.
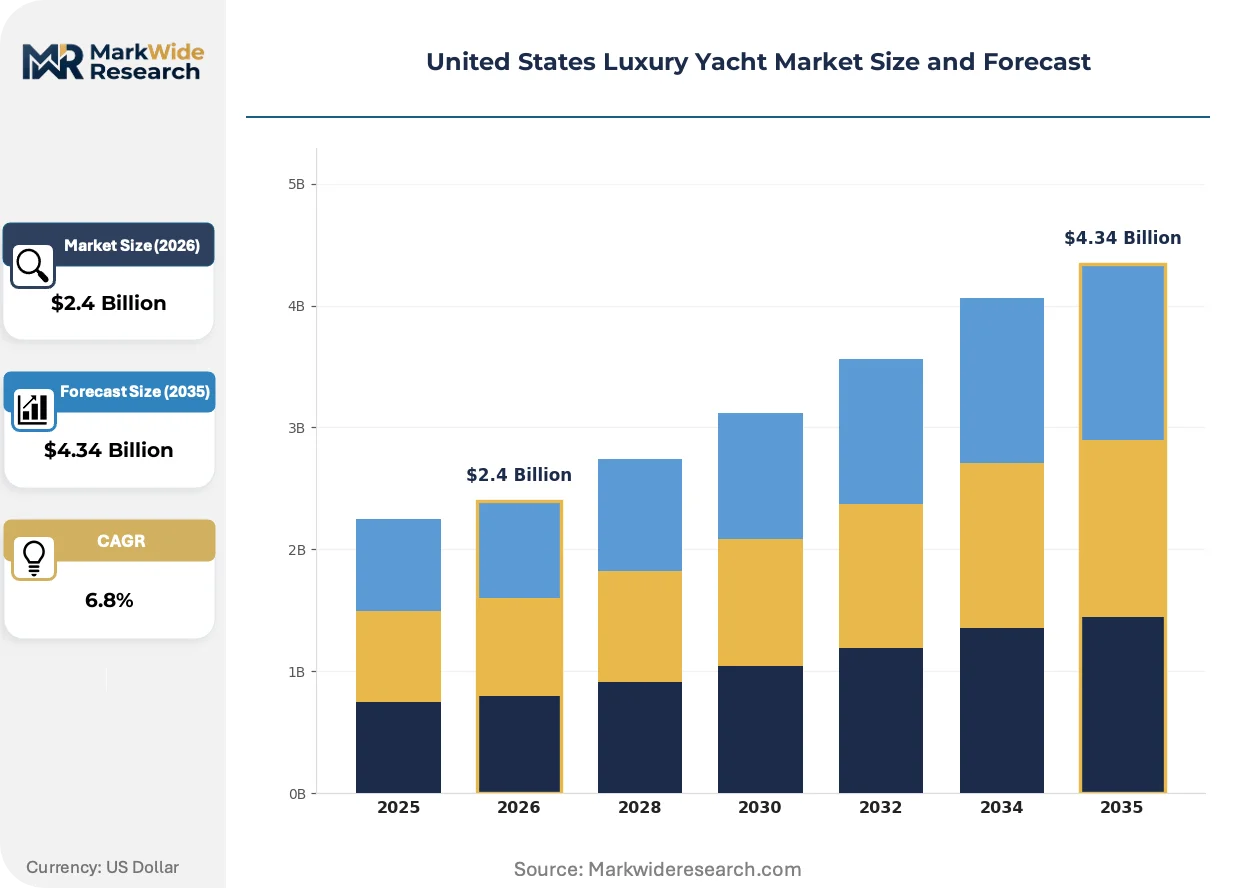
Market Dynamics
Hybrid-electric propulsion mandates from the EPA are compressing engine supplier margins while forcing shipyards to reconfigure hull architecture around battery placement and thermal management systems.
Growth Catalysts
- Fractional Ownership Models:High-net-worth individuals in South Florida and the Northeast Corridor increasingly prefer charter-access arrangements over full asset commitment, expanding the addressable buyer pool beyond traditional owner-operators.
- California Harbor Electrification:Proposed shore-power mandates at major Pacific Coast marinas are accelerating specification of shore-power-ready electrical architectures in new builds destined for West Coast home-porting.
- Carbon-Composite Hull Fabrication:Advanced laminate processes are reducing displacement-to-volume ratios, enabling extended transoceanic range without sacrificing interior amenity space or crew quarters.
Market Restraints
- EPA Tier 4 Compliance Costs:Exhaust after-treatment systems and selective catalytic reduction hardware add substantial capital burden to diesel propulsion packages, particularly for semi-custom production lines with thinner margin structures.
- Skilled Laminate Technician Scarcity:The concentration of experienced carbon-fabrication specialists in the Pacific Northwest and Gulf Coast creates geographic hiring bottlenecks that constrain hull production scaling.
- Aluminum Plate Supply Concentration:Domestic mills capable of certifying marine-grade 5083 alloy plate for superyacht scantlings number fewer than four, exposing build schedules to single-source disruption risk.
Strategic Opportunities
- Great Lakes Underpenetration:The freshwater superyacht segment centered on Chicago and Detroit remains structurally underserved, with no dedicated large-yacht shipyard operating between the Atlantic and Pacific construction clusters.
- Dual-Use Charter Specification:Owners configuring layouts for simultaneous private residence and commercial charter operation can access accelerated depreciation schedules and charter revenue offsetting carrying costs.
- Battery-Electric Harbor Craft Convergence:Integration of automotive-derived solid-state battery architectures with marine DC distribution systems opens specification pathways for zero-emission operation in emission-control areas.
Industry Challenges
- Naval Architect Talent Pipeline:US maritime academies graduate fewer than fifty yacht-specialized designers annually, forcing shipyards to recruit from European institutions or retrain commercial marine architects.
- Coast Guard Certification Timelines:Subchapter T and K plan review backlogs at Marine Safety Center offices extend delivery schedules by four to eight months, compressing shipyard cash conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Luxury Yacht Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sailing Yachts, Motor Yachts, Catamarans, Superyachts End User: Private Owners, Charter Services, Corporate Clients, Sailboat Enthusiasts Technology: Navigation Systems, Communication Equipment, Engine Technology, Eco-Friendly Solutions Size: Small Yachts, Medium Yachts, Large Yachts, Mega Yachts |
| Companies Covered | Trinity Yachts, Derecktor Shipyards, Delta Marine, Satorin Development Company, Campbell Industries, Westport Yachts, Swiftships, Viking Yachts, Christensen Yachts, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Luxury Yacht Market Strategic Shifts & Innovations
Digital twin technology is compressing the design-to-sea-trial interval while enabling remote diagnostics that extend service intervals and reduce crew technical burden.
Digital twin hull modeling is virtualizing the traditional tank-testing and sea-trial sequence. Semi-custom motor yacht buyers now expect photorealistic virtual walkthroughs before hull cutting begins. This compression of the specification phase is virtualizing the historical role of physical mockups and reducing costly late-stage change orders.
EPA enforcement of Tier 4 marine engine standards is forcing exhaust after-treatment integration into machinery spaces with limited volume. Large-custom builders with flexible hull architecture adapt more readily than high-volume fiberglass producers constrained by fixed mold geometries. The Gulf Coast construction cluster faces particular pressure due to its concentration of diesel-electric hybrid programs.
Charter-first specification is displacing owner-priority layouts in new-build contracts. Buyers in South Florida and the Caribbean home-porting segment now lead with revenue-optimized cabin counts and crew service flows rather than private-use amenity preferences. This behavioral pivot is most visible among spec-build investors targeting the Mediterranean summer charter season from Florida winter bases.
United States Luxury Yacht Market Segmentation
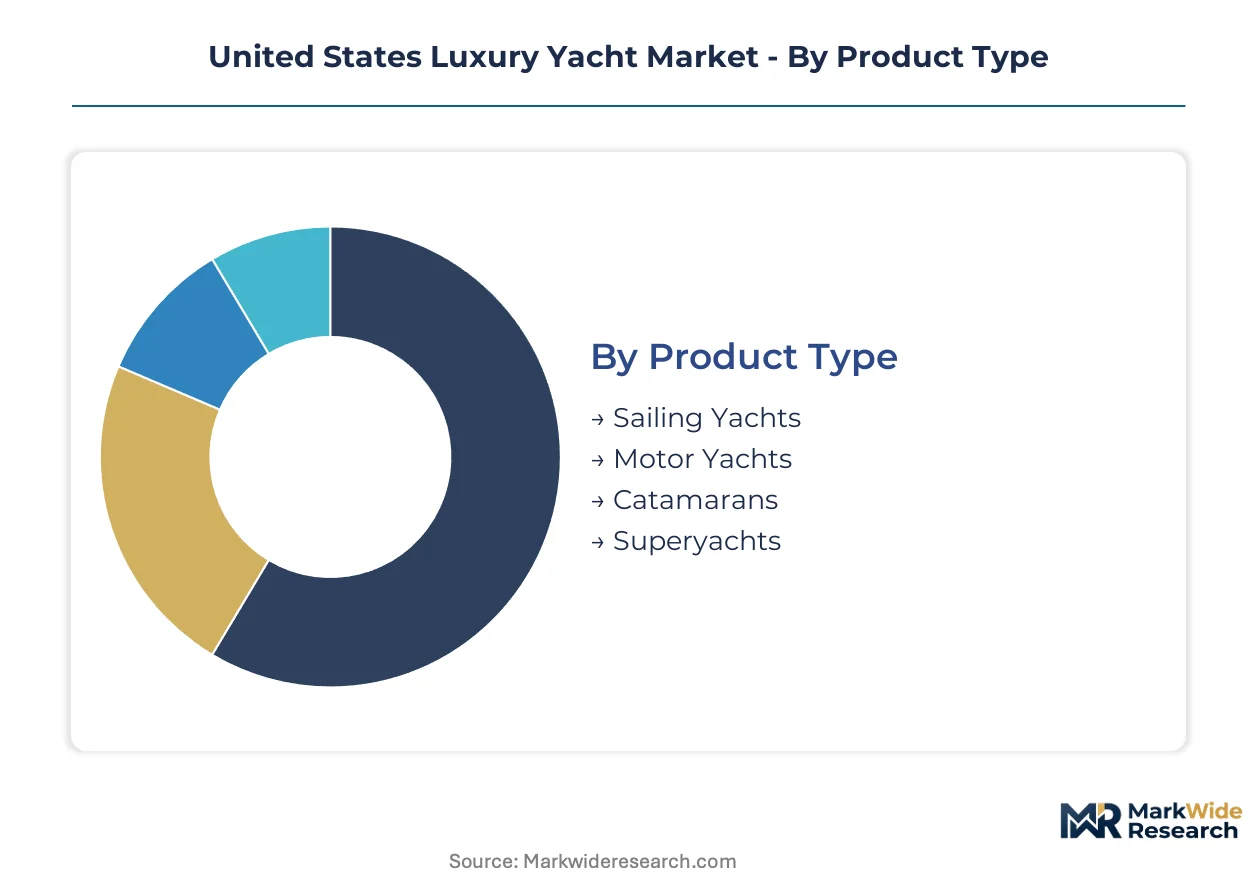
Segmentation in the United States luxury yacht market determines commissioning patterns, service network requirements, and resale liquidity profiles. Builders configure production lines around product type and size class while technology choices increasingly dictate regulatory compliance pathways and harbor access privileges.
Product Type:
After-sales-service intensity varies sharply across hull configurations, with complex propulsion architectures demanding specialized technician networks.
- Motor Yachts:Diesel-electric and conventional diesel propulsion systems dominate this segment, offering expansive deck plans and shorter delivery cycles that appeal to buyers prioritizing onboard entertainment space. Demand concentrates in South Florida from charter-first investors seeking dual-use layouts that maximize revenue potential during Mediterranean summer seasons.
- Superyachts:Steel and aluminum hulls exceeding 60 meters require dedicated crew complements and bespoke interior fit-outs that extend build timelines to 36-48 months. Gulf Coast shipyards anchor this segment, with Trinity Yachts and large-custom builders capturing orders from ultra-high-net-worth individuals prioritizing extended transoceanic range and helicopter landing capabilities.
- Sailing Yachts:Performance-oriented carbon-composite hulls with transoceanic autonomy appeal to owner-operators in the Northeast Corridor.
- Catamarans:Twin-hull stability and shallow draft configurations attract Caribbean home-porting buyers prioritizing beach access and reduced crew requirements.
By volume, motor yachts lead. By growth pace, superyachts are expanding most quickly as fractional ownership models broaden access.
End User:
Customer type determines specification priorities, with commercial-use buyers driving faster depreciation schedules and revenue-optimized layouts.
- Charter Services:Fleet operators and individual investors configure layouts for simultaneous private residence and commercial operation, accessing accelerated depreciation and charter revenue offsets. South Florida dominates this segment, with Fort Lauderdale and Miami serving as the nation's brokerage hub where spec-build investors target Mediterranean summer seasons.
- Private Owners:Full-asset-commitment buyers prioritize personalized interior amenity spaces and reduced cabin counts, often retaining vessels for 5-7 year holding periods before resale.
- Corporate Clients:Entertainment and hospitality-focused configurations with conference facilities and guest accommodation predominate among Fortune 500 purchasers.
- Sailboat Enthusiasts:Performance-racing and bluewater-cruising specialists drive demand for carbon-composite construction and advanced sail handling systems.
By fleet count, private owners lead. By specification influence, charter services are gaining share fastest as builders prioritize dual-use layouts.
Technology:
Margin structures compress around EPA compliance hardware while emerging technologies command specification premiums.
- Eco-Friendly Solutions:Battery banks, shore-power interfaces, and hybrid-electric architectures represent the fastest-growing technology segment as builders integrate EPA Tier 4 compliance pathways. West Coast buyers accelerate adoption ahead of California harbor electrification mandates, with shore-power readiness becoming decisive for resale value in Pacific Coast home-porting segments.
- Engine Technology:Diesel-electric hybrid systems and exhaust after-treatment hardware dominate large-custom programs, with Gulf Coast facilities facing particular pressure from selective catalytic reduction integration requirements.
- Navigation Systems:Integrated bridge electronics with autonomous routing capabilities reduce crew technical burden on extended offshore passages.
- Communication Equipment:Starlink maritime terminals and redundant satellite connectivity now standard for owner-operators requiring remote work capabilities.
By installation base, engine technology leads. By specification momentum, eco-friendly solutions show the steepest expansion trajectory.
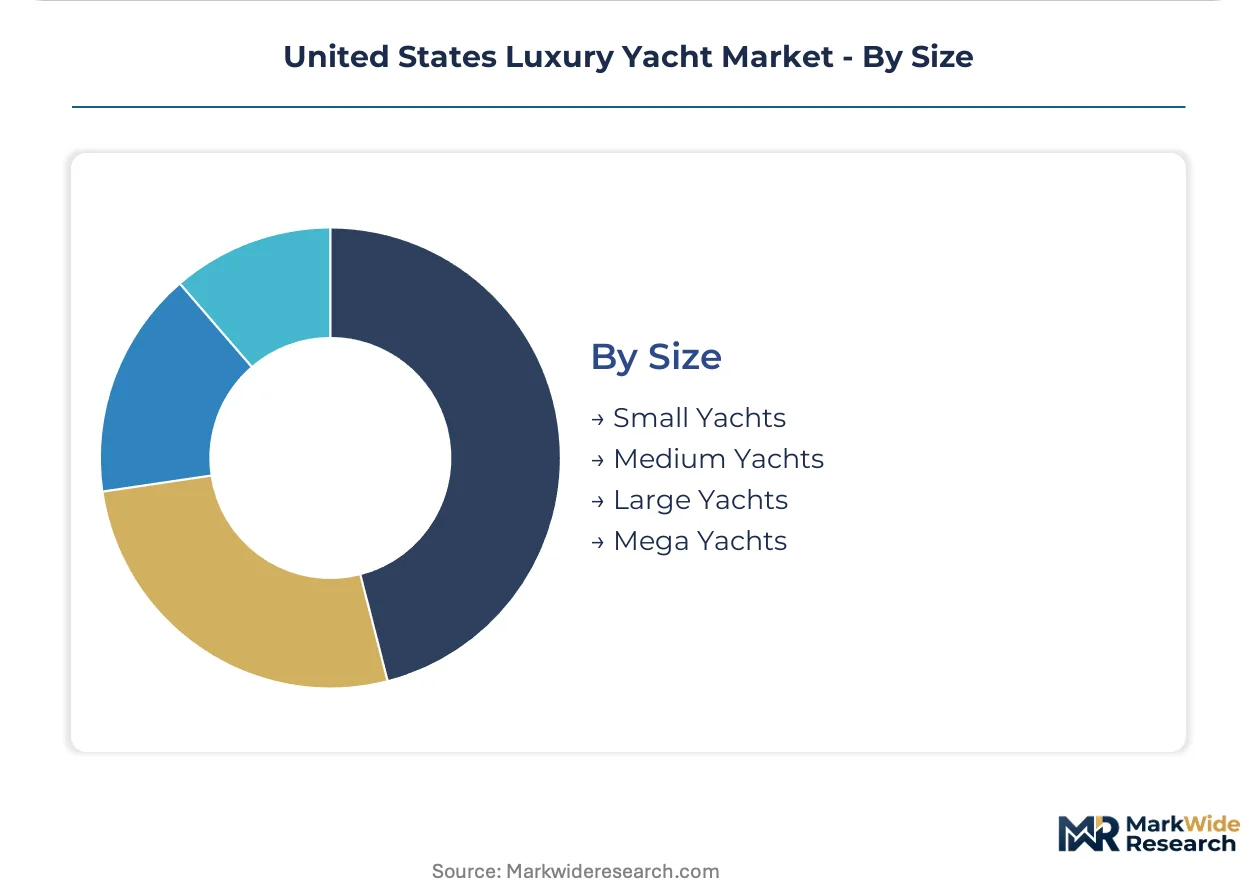
Size:
Production economics and certification complexity scale non-linearly with length, creating distinct competitive arenas.
- Large Yachts:Steel and aluminum vessels in the 40-60 meter range balance interior volume with manageable crew requirements, capturing orders from experienced owners transitioning from smaller platforms. Christensen Yachts and Pacific Northwest builders specialize in carbon-composite variants that reduce displacement-to-volume ratios for extended range.
- Mega Yachts:Exceeding 80 meters, these vessels require foreign-flag registration for many owners and involve 4-8 year build cycles with dedicated project management teams.
- Medium Yachts:Semi-custom fiberglass production from Washington State shipyards competes on speed-to-delivery for time-sensitive buyers.
- Small Yachts:Entry-level luxury segment under 30 meters serves first-time owners and regional cruising preferences.
By hull completions, medium yachts lead. By revenue concentration, large yachts are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charter-first buyers concentrate in coastal states with established brokerage infrastructure and favorable tax treatment for vessel registration. Florida and Washington anchor construction output, while California regulatory pressure accelerates electrification adoption among Pacific Coast owners.
South Florida
Fort Lauderdale and Miami host the nation's densest concentration of yacht construction and charter brokerage activity. The Florida Department of Revenue's sales tax exemption for vessel repairs and refits sustains maintenance spending at local shipyards. Trinity Yachts operates large-custom facilities along the Gulf Coast, capturing orders from ultra-high-net-worth buyers seeking diesel-electric range extension.
Pacific Northwest
Washington State shipyards specialize in high-volume fiberglass production for time-sensitive semi-custom buyers. The Washington State Department of Ecology enforces vessel sewage discharge regulations that accelerate specification of advanced wastewater treatment systems. Westport Yachts sustains rapid delivery cycles from its Washington facilities, competing on speed-to-market for motor yacht investors.
California
Los Angeles and San Diego harbors face accelerating shore-power mandates under the California Air Resources Board's proposed harbor electrification rules. The California Energy Commission's funding programs for maritime decarbonization incentivize battery-electric architecture in new builds. Christensen Yachts maintains carbon-composite specialization for West Coast buyers prioritizing weight reduction and extended cruising range.
Gulf Coast
Louisiana and Mississippi facilities anchor superyacht construction for extended-range diesel-electric programs. The EPA's Tier 4 marine engine standards impose selective catalytic reduction requirements that compress margins for Gulf Coast builders. Delta Marine and Derecktor Shipyards occupy positions within the large-custom fabrication tier, serving owners configuring dual-use private-charter layouts.
United States Luxury Yacht Market Key Industry Players
Channel-controlling players compete with product-specialist players across distinct fabrication tiers. Large-custom steel and aluminum builders maintain concentrated order books for 60-meter-plus vessels, while semi-custom fiberglass producers compete on delivery velocity for 40-60 meter segments. Three archetypes dominate: Gulf Coast superyacht specialists, Pacific Northwest volume producers, and carbon-composite performance builders. Competitive moves center on hybrid-electric propulsion integration and charter-optimized layout engineering.
Among Gulf Coast fabricators, Trinity Yachts and Delta Marine exemplify the large-custom diesel-electric tier, while Westport Yachts anchors high-volume fiberglass production from Washington State. Christensen Yachts occupies a position within the carbon-composite specialization segment, serving buyers prioritizing displacement reduction. These three named entities represent distinct competitive vectors: range-extended hybrid architecture, speed-to-delivery manufacturing, and advanced material performance.
| Leading Market Players |
|---|
| Trinity Yachts |
| Derecktor Shipyards |
| Delta Marine |
| Satorin Development Company |
| Campbell Industries |
| Westport Yachts |
| Swiftships |
| Viking Yachts |
| Christensen Yachts |
| Others |
Cost & Logistics Intelligence
Single-source aluminum plate dependency from domestic mills certifying marine-grade 5083 alloy compresses both pricing tier spreads and supply chain resilience, forcing builders to absorb volatility or pass through costs to charter-first buyers.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange aluminum pricing dominate large-custom builds, with premium-mid-economy pricing differentiation separating carbon-composite superyachts from semi-custom fiberglass motor yachts. EPA Tier 4 after-treatment hardware intensifies cost compression in diesel-electric propulsion packages, while charter service investors show lowest price sensitivity due to revenue offset structures.
Supply Chain Analysis
Tariff exposure between the United States and European carbon-fiber suppliers dominates supply chain risk planning for Pacific Northwest hull fabricators. Carbon-prepeg and marine-grade aluminum plate feed from Japan, Germany, and domestic mills, with logistics chokepoints at Gulf Coast deepwater ports constraining mega-yacht module delivery. Distribution runs through Fort Lauderdale brokerage houses for Atlantic-facing buyers and San Diego harbor agents for Pacific Coast home-porting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fractional ownership penetration remains below saturation thresholds, positioning the market for early-cycle expansion as high-net-worth individuals shift from full asset commitment to charter-access models.
For Market Incumbents: Entrench diesel-electric hybrid expertise through backward integration into battery system assembly, countering margin pressure from EPA Tier 4 compliance costs. Secure long-term aluminum supply agreements with domestic mills to defend production schedules against single-source disruption.
For New Entrants and Emerging Players: Establish a beachhead in the Great Lakes freshwater superyacht segment, where Chicago and Detroit buyers face structural underservice from coastal construction clusters. Pursue carbon-composite specialization for sailing yacht performance buyers, leveraging automotive battery supply chain spillover for cost advantage.
For Investors and Strategic Acquirers: California Air Resources Board harbor electrification mandates reshape the acquisition landscape toward shore-power-ready electrical architecture capabilities. Target shipyards with Coast Guard certification track records and existing Pacific Coast home-porting relationships, monitoring EPA enforcement intensity as the inflection signal for compliance cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Integration | EPA Tier 4 compliance pathways anchor competitive positioning for Gulf Coast builders. |
| Carbon-Composite Hull Fabrication | Advanced laminate processes extend transoceanic range for Christensen Yachts buyers. |
| Dual-Use Charter Specification | Revenue-optimized layouts accelerate depreciation schedules for South Florida investors. |
| Shore-Power Architecture Readiness | California Energy Commission incentives drive West Coast specification premiums. |
| Digital Twin Virtualization | Remote diagnostics compress design-to-sea-trial intervals for semi-custom programs. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with yacht design executives, shipyard operations directors, charter fleet managers, and Coast Guard certification officers; and secondary validation through EPA enforcement records, U.S. Coast Guard Marine Safety Center plan review databases, Florida Department of Revenue vessel transaction filings, and customs import data for marine-grade aluminum and carbon-fiber inputs. Bottom-up hull completion tallies by builder and top-down brokerage transaction values were triangulated to anchor market sizing.
Forecast inputs considered propulsion technology adoption curves, regional harbor electrification regulatory trajectories, and fractional ownership penetration rates across the analysis window. Segmentation dimensions modeled include hull material class, size tier, end-use configuration, and home-porting geography. CAGRs were derived from trend extrapolation of historical commissioning data against projected buyer demographic expansion and technology substitution patterns, with battery-electric architecture cost curves and EPA compliance timeline uncertainty as primary variance factors.
Macroeconomic conditions sit as an overlay; deviation in luxury asset discretionary spending, marine construction labor availability, and aluminum commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and charter market seasonality patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
North America Hovercraft Market
Recreational Vehicles
Malaysia Trailer Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
United States RV Rental Market