
 North America Sea Freight Forwarding Market | 2026-2036
North America Sea Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sea Freight Forwarding Market Insights
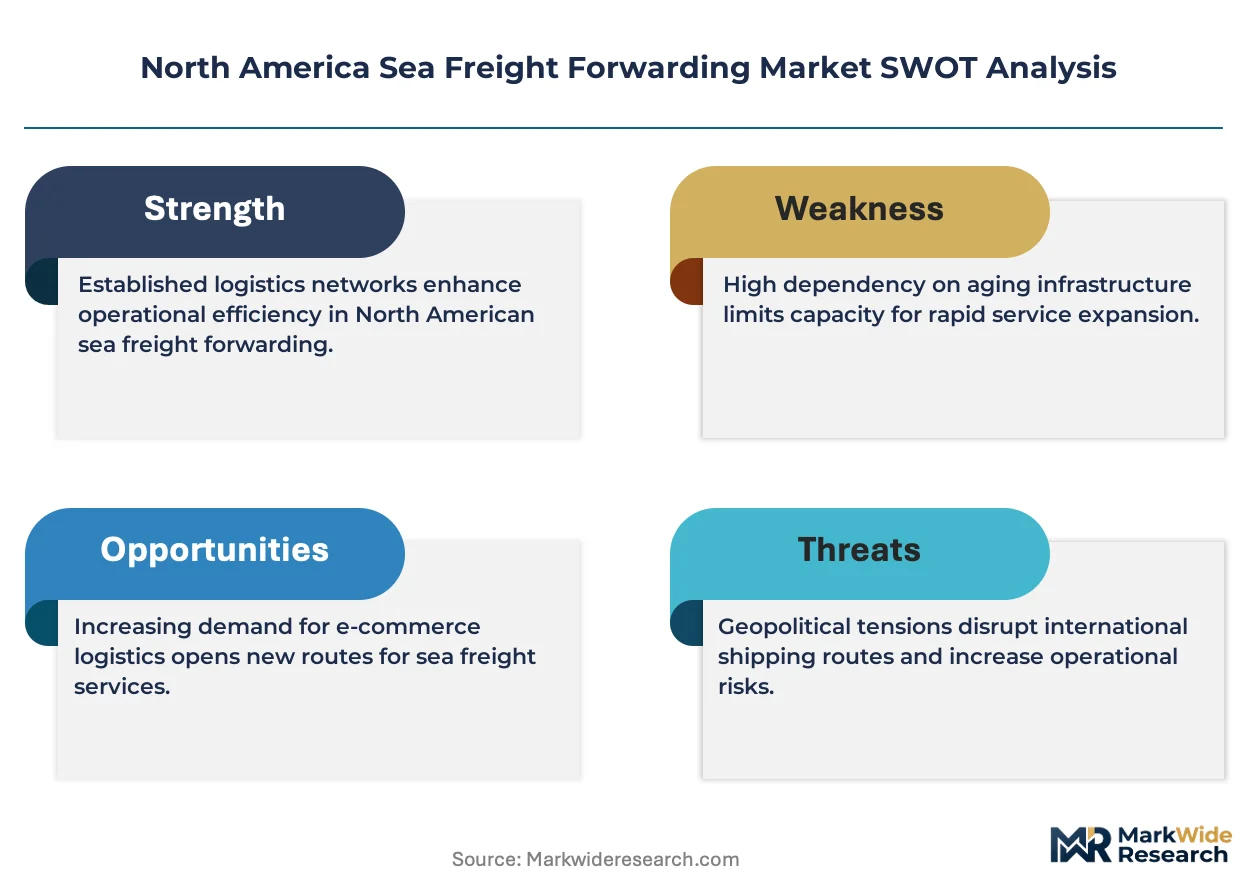
Software-defined freight visibility is rebalancing what shippers pay for in ocean forwarding contracts. DHL Supply Chain & Global Forwarding leverages its proprietary digital platforms to anchor trans-Pacific lane control. Kuehne + Nagel sustains margin pools through specialized pharmaceutical cold-chain services. C.H. Robinson competes by aggregating fragmented less-than-container-load demand across Midwest manufacturing belts.
Sea freight forwarding encompasses the coordination of ocean cargo movement, customs brokerage, and multimodal interchange, typically operating with vessel sharing agreements, container yard management, and harmonized tariff schedule classification. Its primary commercial purpose is to reduce shipper logistics expenditure while ensuring compliant, time-definite delivery across maritime supply chains. Full container load services dominate volume throughput but generate thinner margins than breakbulk project cargo, where specialized equipment and charter coordination command premium pricing. Refrigerated container segments are expanding fastest as perishable e-commerce and pharmaceutical cold chains displace traditional air freight on cost-sensitive lanes.
The U.S. Federal Maritime Commission enforces ocean shipping reform mandates that constrain carrier detention billing practices, while Transport Canada administers marine safety regulations affecting port access and vessel standards. Mexico's Secretariat of Communications and Transportation coordinates cross-border freight integration under USMCA logistics protocols. Stakeholders must monitor how emissions reporting requirements from the International Maritime Organization reshape carrier fuel surcharge structures and forwarding cost allocation models.
Market Dynamics
The U.S. Federal Maritime Commission's updated detention and demurrage rules are compressing carrier-shipper contracting timelines and forcing forwarders to reprice risk exposure in trans-Pacific lane agreements.
Growth Catalysts
- E-commerce consolidation demand:Online retailers are expanding their reliance on consolidated ocean freight services to reduce per-unit shipping costs on bulky goods. This pattern concentrates volume through Los Angeles-Long Beach and Vancouver gateway ports.
- USMCA logistics protocols:Mexico's Secretariat of Communications and Transportation coordinates cross-border freight integration, accelerating bonded warehouse expansions along the Laredo-Nuevo Laredo corridor.
- Refrigerated container technology:Pharmaceutical cold chains are displacing traditional air freight on cost-sensitive lanes, with reefer box deployments expanding fastest through Gulf Coast petrochemical terminals.
Market Restraints
- Carrier concentration risk:Vessel sharing agreements among top ocean alliances limit forwarder negotiating leverage on spot rates and capacity allocation during peak seasons.
- Fuel surcharge volatility:International Maritime Organization emissions reporting requirements are reshaping carrier fuel surcharge structures, creating unpredictable cost pass-through to shippers.
- Port infrastructure bottlenecks:Chassis shortages and container yard congestion at the Port of Los Angeles-Long Beach complex extend dwell times and inflate detention exposure.
Strategic Opportunities
- U.S. Gulf Coast expansion:Petrochemical corridor investments near Houston and Corpus Christi create specialized breakbulk and tank container forwarding demand.
- Software-defined visibility platforms:Integration of IoT sensors with customs brokerage systems enables real-time harmonized tariff schedule classification and duty optimization.
- Midwest manufacturing belt aggregation:Less-than-container-load consolidation hubs in Ohio and Illinois capture fragmented industrial export demand underserved by direct carrier networks.
Industry Challenges
- Customs brokerage talent scarcity:Licensed customs house broker capacity constraints delay entry filings during volume surges, particularly for complex agricultural and chemical classifications.
- Multimodal interchange coordination:Rail drayage handoffs between marine terminals and inland distribution centers generate detention liability disputes requiring automated documentation reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sea Freight Forwarding Market |
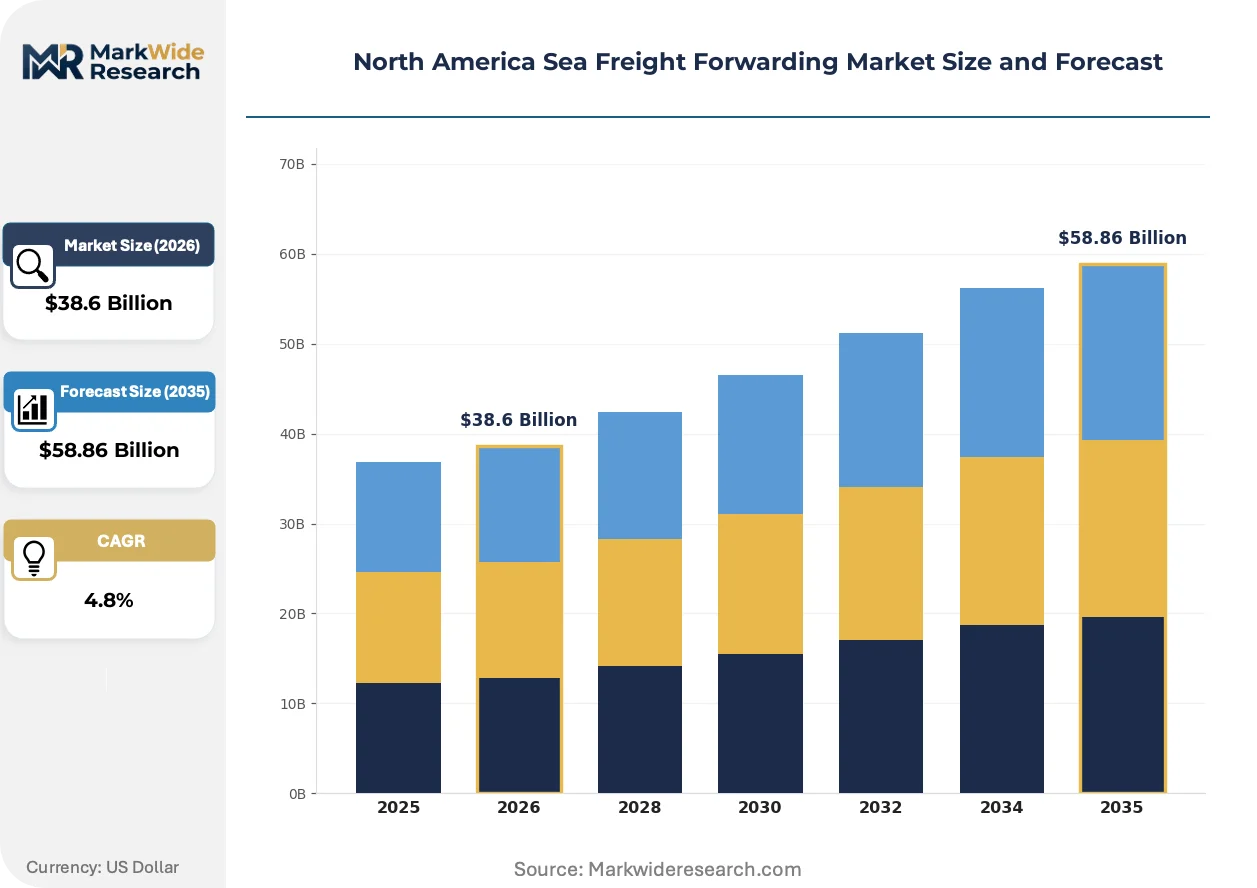
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Container Load, Less than Container Load, Breakbulk, Ro-Ro End User: Manufacturers, Retailers, E-Commerce, Distributors Delivery Model: Door-to-Door, Port-to-Port, Port-to-Door, Door-to-Port Container Type: Open Top, Flat Rack, Refrigerated, Standard |
| Companies Covered | DSV A/S, DHL Supply Chain & Global Forwarding, Kuehne + Nagel, C.H. Robinson, Expeditors International of Washington, DB Schenker, CEVA Logistics, GEODIS, Worldwide Logistics Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sea Freight Forwarding Market Trends and Innovations
Digital freight platforms are compressing the information asymmetry that historically anchored forwarder margins, while regulatory pressure on emissions transparency reshapes carrier pricing architectures.
Blockchain-enabled bill-of-lading verification is automating document reconciliation between shippers, carriers, and customs authorities. Mid-sized manufacturers in automotive and industrial machinery are piloting these systems for Asia-North America lanes. The technology is automating release-from-hold decisions that previously required manual broker intervention, cutting port dwell times by eliminating paperwork bottlenecks.
The U.S. Federal Maritime Commission enforces ocean shipping reform mandates that constrain carrier detention billing practices and require invoice itemization. Shippers now dispute charges more aggressively, forcing forwarders to absorb verification costs or renegotiate agency terms. Container lines serving the trans-Pacific trade are responding by unbundling inland haulage from ocean rates to limit FMC exposure.
Shippers are consolidating vendor relationships around forwarders offering integrated customs brokerage and visibility rather than transactional spot-rate booking. Retail and consumer goods importers are displacing fragmented broker-forwarder combinations with single-source contracts spanning origin consolidation through final-mile deconsolidation. This pattern is most visible among direct-to-consumer brands importing through Vancouver and Prince Rupert to bypass U.S. West Coast congestion.
North America Sea Freight Forwarding Market Segmentation
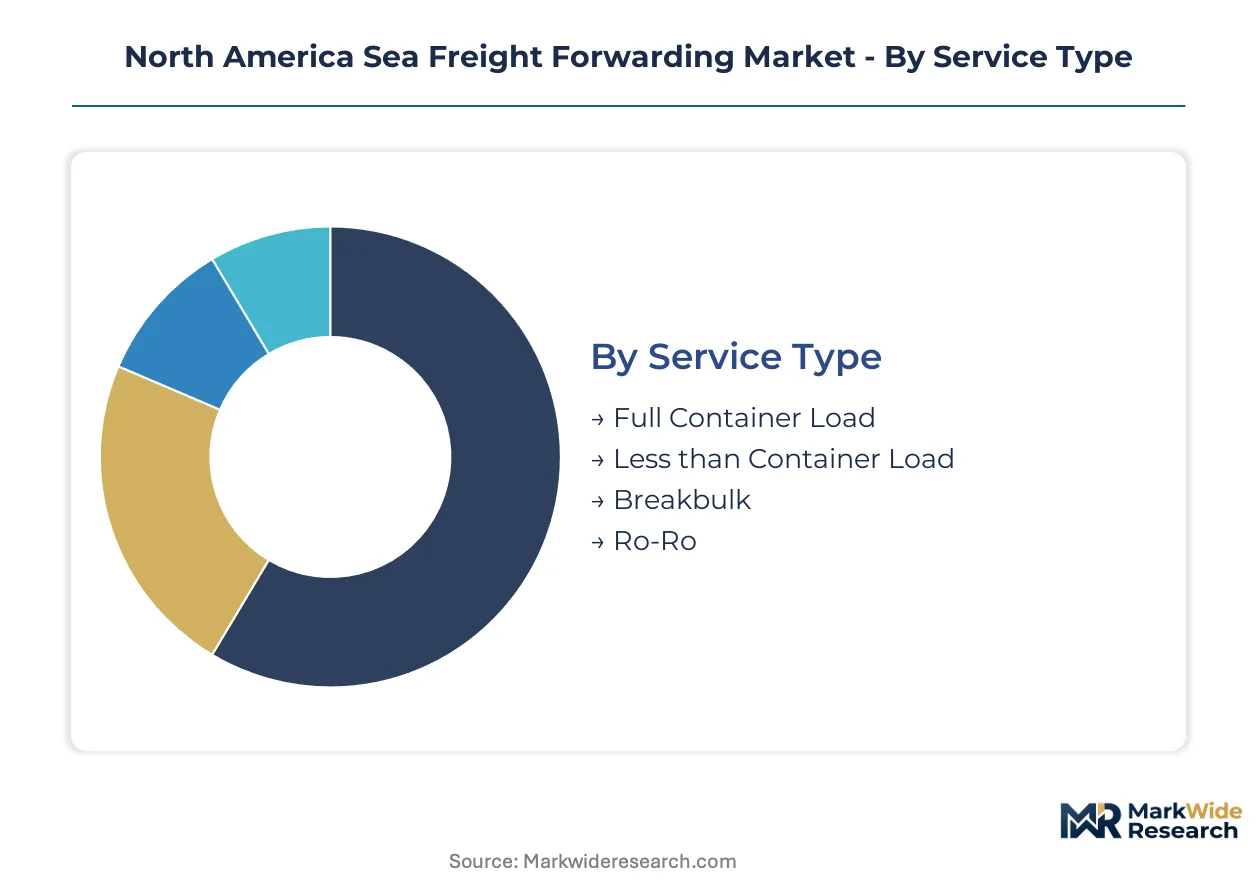
Segmentation in sea freight forwarding determines which service configurations capture margin premiums versus commodity volume. Container specifications, delivery responsibility boundaries, and customer operational models each reshape contract structures and capital deployment priorities across North American maritime corridors.
Service Type:
FMC ocean shipping reform mandates impose distinct documentation and detention liability frameworks on each service tier, with breakbulk and project cargo facing the most complex harmonized tariff schedule classifications.
- Full Container Load:Dedicated twenty-foot or forty-foot container allocation for single-shipper cargo. Manufacturers along the Ohio River industrial belt dominate demand, though thinning margins pressure forwarders to unbundle inland haulage from ocean rates to limit FMC billing exposure.
- Less than Container Load:Consolidated multi-shipper cargo requiring container yard coordination and deconsolidation services. E-commerce retailers importing through Vancouver and Prince Rupert drive fastest expansion as they bypass Los Angeles-Long Beach congestion for cost-sensitive bulky goods.
- Breakbulk:Non-containerized project cargo requiring specialized lifting equipment and charter coordination. Petrochemical corridor investments near Houston generate premium-priced demand for oversized machinery and modular components.
- Ro-Ro:Roll-on/roll-off vessel services for wheeled and tracked cargo. Automotive manufacturers in Michigan and Ontario anchor volume through Baltimore and Charleston gateway ports.
Full Container Load sits at the top of the volume ranking, with Less than Container Load climbing the fastest.
End User:
Customer procurement sophistication varies sharply, with direct-to-consumer brands demanding integrated visibility while legacy manufacturers tolerate transactional spot-rate relationships.
- Manufacturers:Industrial producers with predictable production schedules and high cargo density. Midwest machinery exporters in Illinois and Ohio favor long-term contracts with embedded chassis guarantees to avoid rail drayage detention disputes.
- Retailers:Big-box and specialty store chains with seasonal volume spikes. These shippers are consolidating vendor relationships around forwarders offering bundled customs brokerage rather than fragmented broker-forwarder combinations.
- E-Commerce:Direct-to-consumer brands with fragmented SKU profiles and velocity unpredictability. This segment expands most quickly through bonded warehouse networks along the Laredo-Nuevo Laredo corridor under USMCA logistics protocols.
- Distributors:Wholesale intermediaries serving fragmented downstream customers. Their consolidation demand concentrates through Los Angeles-Long Beach for trans-Pacific consumer goods.
Manufacturers generate the deepest contract penetration, while E-Commerce shows the steepest expansion trajectory.
Delivery Model:
Responsibility handoff points determine which party bears detention liability and chassis access risk, with door-to-door contracts commanding premium pricing for risk absorption.
- Door-to-Door:Forwarder assumes liability from shipper facility through consignee facility. Retailers importing perishables favor this model to ensure reefer box integrity across multimodal handoffs.
- Port-to-Port:Ocean carrier liability confined to marine terminal boundaries. Commodity chemical shippers along the Gulf Coast prefer this stripped-down structure to self-manage inland tank container haulage.
- Port-to-Door:Forwarder accepts cargo at destination terminal and manages final delivery. E-commerce brands use this to control last-mile deconsolidation while avoiding origin consolidation complexity.
- Door-to-Port:Forwarder collects at origin and relinquishes at destination marine terminal. Midwest agricultural exporters select this model to retain control over foreign customs clearance.
Port-to-Port retains the largest volume footprint, though Door-to-Door gains share fastest as shippers outsource detention risk.
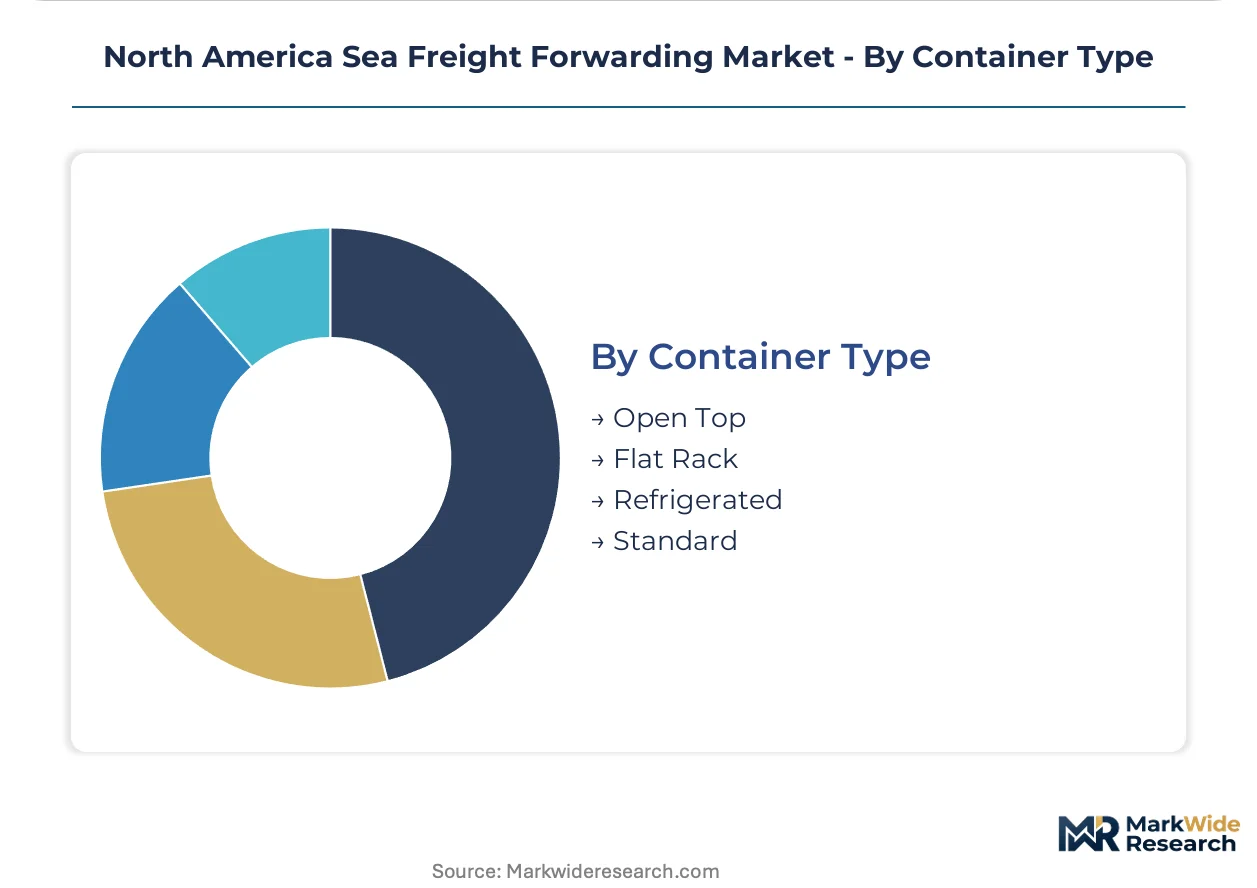
Container Type:
Equipment specialization drives pricing stratification, with temperature-controlled and open-configuration boxes capturing premiums over commodity standard units.
- Refrigerated:Temperature-controlled containers for perishables and pharmaceuticals. Gulf Coast petrochemical terminals deploy these fastest as cold chains displace air freight on cost-sensitive lanes.
- Standard:Dry van containers for non-perishable general cargo. This segment anchors volume throughput across all major North American gateway ports.
- Open Top:Removable-roof containers for oversized vertical cargo. Breakbulk project demand near Corpus Christi drives specialized deployments.
- Flat Rack:Collapsible-side platforms for heavy machinery and vehicles. Automotive and industrial equipment exporters in Ontario and Michigan generate concentrated demand.
Standard containers dominate volume rankings, with Refrigerated units expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantially higher forwarding volume than Canada, though Mexico's cross-border corridor expansion is narrowing the growth rate gap. Regulatory divergence across the three USMCA partners creates distinct operational frameworks for detention liability and customs clearance.
United States
Petrochemical corridor investments near Houston and Corpus Christi drive specialized breakbulk demand, while Midwest manufacturing belts in Ohio and Illinois anchor LCL consolidation networks. The Federal Maritime Commission's updated detention and demurrage rules constrain carrier billing practices and force forwarders to reprice risk exposure. The Port of Los Angeles-Long Beach complex concentrates trans-Pacific volume but suffers chassis shortages and yard congestion that extend dwell times.
Canada
Vancouver and Prince Rupert gateway ports capture e-commerce diversion demand from congested U.S. West Coast terminals, particularly for direct-to-consumer brands importing bulky goods. Transport Canada administers marine safety regulations affecting port access and vessel standards, including emissions reporting protocols aligned with International Maritime Organization frameworks. Bonded warehouse expansions in the Lower Mainland support cross-border fulfillment integration with U.S. distribution networks.
Mexico
The Laredo-Nuevo Laredo corridor accelerates bonded warehouse development under USMCA logistics protocols, serving manufacturing reshoring demand from automotive and electronics sectors. Mexico's Secretariat of Communications and Transportation coordinates cross-border freight integration with standardized customs procedures. Altamira and Veracruz Gulf Coast terminals expand refrigerated container handling capacity for perishable exports to U.S. markets.
Southeast U.S. Manufacturing Belt
Automotive and industrial machinery producers in Georgia and South Carolina generate concentrated Ro-Ro demand through Charleston and Savannah ports. State-level infrastructure investments in rail intermodal terminals reduce drayage detention exposure for Midwest-connected supply chains. The region's port authorities compete for petrochemical project cargo with specialized heavy-lift capabilities.
Great Lakes Industrial Corridor
Agricultural exporters in Minnesota and Wisconsin utilize Door-to-Port forwarding models to retain control over foreign customs clearance for grain and processed food shipments. Canadian National and Canadian Pacific Kansas City rail networks provide multimodal interchange options that bypass Chicago congestion. Cold storage infrastructure investments near Milwaukee support pharmaceutical reefer box consolidation for European lanes.
North America Sea Freight Forwarding Market Competitive Landscape
Top-tier vendors anchor trans-Pacific lane control through proprietary digital platforms, while mid-tier specialists compete on pharmaceutical cold-chain and breakbulk project expertise. The vendor base stratifies across integrated global networks, regional consolidation hubs, and niche equipment specialists. Three archetypes dominate: scale-driven platform operators, cold-chain certification holders, and petrochemical corridor project coordinators. Competitive moves concentrate on unbundling inland haulage from ocean rates to limit regulatory exposure, and on acquiring licensed customs house broker capacity to reduce filing delays.
Among integrated global networks, DHL Supply Chain & Global Forwarding and Kuehne + Nagel occupy positions exemplifying platform-scale and specialized cold-chain anchoring respectively. C.H. Robinson represents the aggregation archetype, capturing fragmented LCL demand across Midwest manufacturing belts through digital freight matching capabilities. These three firms illustrate how market positioning diverges between technology-led visibility platforms, certification-dependent temperature-controlled services, and demand-aggregation intermediation.
| Leading Market Players |
|---|
| DSV A/S |
| DHL Supply Chain & Global Forwarding |
| Kuehne + Nagel |
| C.H. Robinson |
| Expeditors International of Washington |
| DB Schenker |
| CEVA Logistics |
| GEODIS |
| Worldwide Logistics Group |
| Others |
Pricing and Supply Chain Analysis
International Maritime Organization emissions reporting requirements gate qualified supply access and premium-tier pricing for forwarders serving carbon-accounting shippers. The mandate compresses carrier fuel surcharge structures and forces forwarding cost allocation models that reward verified low-emission vessel operators with contract premiums.
Pricing Analysis
Capacity additions in Mexico's bonded warehouse corridor are reshaping price floors for cross-border LCL consolidation services. Pricing stratifies across premium door-to-door contracts with detention risk absorption, standard port-to-port arrangements favored by Gulf Coast chemical shippers, and economy spot-rate bookings for commodity Midwest manufacturing exports. Price differentiation rests on customs brokerage integration depth and reefer box certification tier. Cost compression in standard FCL services is intensifying because FMC invoice itemization rules force forwarders to absorb verification overhead. E-commerce retailers importing through Vancouver demonstrate highest price sensitivity, while pharmaceutical cold-chain shippers accept premium positioning for temperature integrity guarantees.
Supply Chain Analysis
Licensed customs house broker scarcity in Ohio and Illinois manufacturing belts constrains container yard coordination capacity for LCL deconsolidation networks. Supply concentration centers on China for origin consolidation equipment, South Korea for reefer box manufacturing, and the United States for chassis and intermodal rail assets. Raw material dependencies span steel for container fabrication, refrigerants for temperature-controlled units, and specialized lifting gear for breakbulk project cargo. Single-source vulnerability runs through concentrated vessel sharing agreements among top ocean alliances. Distribution feeds from Los Angeles-Long Beach and Prince Rupert gateway ports through Chicago rail intermodal terminals to Midwest manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between U.S. Gulf Coast petrochemical corridor investments and Mexican bonded warehouse development, where labor cost differentials under USMCA protocols create forwarding margin expansion opportunities.
For Market Incumbents: Lock in trans-Pacific lane control through proprietary IoT-integrated visibility platforms that anchor shipper vendor consolidation trends. Defensive moves center on acquiring licensed customs house broker capacity to reduce filing delays during volume surges, and unbundling inland haulage from ocean rates to limit FMC detention billing exposure. The threat of digital freight platforms compressing information asymmetry demands counter-investment in real-time harmonized tariff schedule classification systems. For New Entrants and Emerging Players: Launch via specialized pharmaceutical cold-chain services targeting the fastest-expanding reefer box segment displacing air freight on cost-sensitive lanes. The most penetrable white space sits in breakbulk project coordination for Houston and Corpus Christi petrochemical corridor investments, where charter coordination expertise commands premium pricing. A go-to-market angle anchored in USMCA cross-border bonded warehouse integration captures manufacturing reshoring demand from automotive and electronics sectors. For Investors and Strategic Acquirers: Roll-up economics work for Midwest LCL consolidation specialists because fragmented less-than-container-load demand across Ohio and Illinois manufacturing belts resists direct carrier network capture. Long-term viability frames around software-defined freight visibility platforms that rebalance shipper contract value toward data services. The acquisition target archetype combines digital freight matching capabilities with embedded customs brokerage licenses. Watch for FMC enforcement intensity on detention invoice itemization as the inflection signal for forwarder margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Customs Brokerage Acquisition | Licensed capacity reduces entry filing delays during agricultural and chemical volume surges. |
| Reefer Box Fleet Expansion | Temperature-controlled container deployments capture pharmaceutical cold-chain demand from air freight displacement. |
| USMCA Bonded Warehouse Development | Cross-border fulfillment integration serves automotive and electronics manufacturing reshoring. |
| IoT Visibility Platform Integration | Real-time sensor data automates release-from-hold decisions and cuts port dwell times. |
| Inland Haulage Unbundling | Separating ocean rates from drayage limits Federal Maritime Commission detention billing exposure. |
Research Methodology
Bottom-up e-commerce and manufacturing shipper modeling reconciled against top-down vessel capacity and port throughput tracking forms the analytical core. Primary interviews with freight forwarder operations directors, licensed customs house brokers, carrier alliance network managers, and shipper procurement leads combined with secondary validation. Secondary sources span U.S. Federal Maritime Commission enforcement filings, Transport Canada marine safety regulations, Mexico Secretariat of Communications and Transportation cross-border protocols, and customs/trade data from gateway port authorities.
Historical volume and rate trendlines across the analysis window establish baseline trajectory patterns. The quantitative framework models service type segmentation, container equipment specialization, delivery responsibility boundaries, and end-user procurement sophistication as independent demand drivers. CAGRs derive from slope analysis of segment-specific growth trajectories adjusted for regulatory intervention effects. Industry-specific forecast inputs include FMC detention rule implementation pacing and International Maritime Organization emissions reporting compliance timelines.
Several conditions sit outside the modeled scope, including sudden ocean alliance restructuring, extreme weather port closures, and trade policy renegotiation outside USMCA frameworks. Forecasts reflect assumptions about regulatory enforcement continuity and carrier fuel surcharge pass-through stability. Material deviation in FMC rulemaking intensity or IMO emissions compliance deadlines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
United States Automotive Logistics Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
North America Logistics Automation Market