
 Saudi Arabia Secure Logistics Market | 2026-2036
Saudi Arabia Secure Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Secure Logistics Market Insights
Modular service bundling is broadening buyer choice across the Saudi Arabia secure logistics sector. Brink's Co leverages its armored fleet infrastructure to dominate cash management contracts in Riyadh. G4S sustains competitive positioning through integrated guarding and technology solutions for pharmaceutical cold chains. Loomis AB anchors its regional presence with specialized high-value transportation services linking Jeddah Islamic Port to inland distribution hubs.
Saudi Arabia secure logistics encompasses the specialized movement, storage, and protection of high-value assets, sensitive materials, and confidential data through armored vehicles, biometric access-controlled vaults, and real-time surveillance systems operating under strict chain-of-custody protocols. The sector serves critical functions across banking, precious metals, pharmaceuticals, and government sectors where asset integrity and regulatory compliance are non-negotiable. GPS tracking and IoT Solutions represent the fastest-expanding technology segments as fleet operators demand granular visibility across Saudi Arabia's vast desert corridors. Transportation services command the largest service-type revenue pool, though Security Consulting margins expand as SAMA compliance deadlines tighten. Retail and Pharmaceuticals end-user segments attract disproportionate investment as e-commerce fulfillment and temperature-controlled drug distribution strain legacy infrastructure.
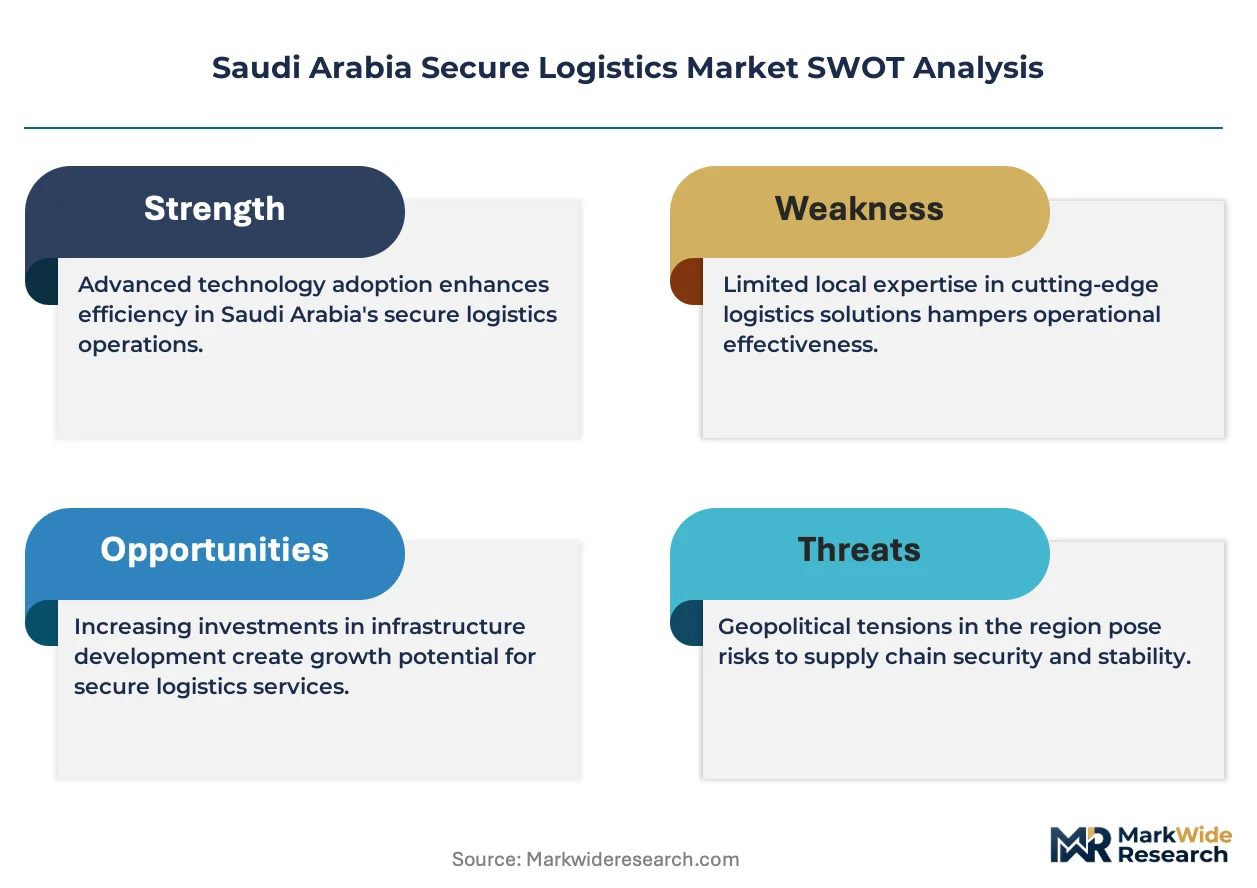
SAMA, the General Authority of Civil Aviation, and the Saudi Food and Drug Authority collectively shape operational standards through cybersecurity mandates, air cargo screening protocols, and pharmaceutical distribution integrity requirements. These frameworks elevate capital barriers for new entrants while accelerating replacement cycles for non-compliant legacy equipment. Stakeholders must weigh technology refresh timelines against evolving biometric authentication and blockchain audit trail requirements that SAMA and sectoral regulators are embedding into licensing conditions.
Market Dynamics
SAMA's Cybersecurity Framework is compressing operational timelines across the Saudi Arabia secure logistics sector. Fleet operators must retrofit biometric authentication and blockchain audit trails into legacy armored vehicle networks before licensing deadlines expire, forcing simultaneous capital deployment across multiple compliance layers.
Growth Catalysts
- Banking digitization:SAMA's push for cash-lite economies paradoxically elevates cash-in-transit security requirements as physical currency concentrates in fewer high-volume corridors. Financial institutions demand premium custody protocols for remaining cash infrastructure.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution from Jeddah Islamic Port requires specialized armored refrigeration units with continuous monitoring. The Saudi Food and Drug Authority mandates end-to-end chain-of-custody documentation.
- GPS-IoT convergence:Real-time fleet visibility across Saudi Arabia's desert highway network reduces insurance premiums and accelerates incident response. Transport operators deploy granular tracking to satisfy SAMA operational risk standards.
Market Restraints
- Armored vehicle import dependency:Domestic production capacity for ballistic-rated chassis remains negligible. Fleet expansion relies on European and North American suppliers with extended order backlogs.
- Specialized technician scarcity:Biometric system maintenance and blockchain integration require certified personnel. Training pipelines through Saudi technical institutes have not scaled to match SAMA compliance deadlines.
- Vault construction material costs:Reinforced concrete and blast-resistant steel pricing fluctuates with global commodity markets. Cash management infrastructure projects face margin compression from input volatility.
Strategic Opportunities
- Neom logistics corridor:The planned smart city requires ground-up secure logistics architecture without legacy system constraints. Operators can deploy fully integrated biometric-blockchain infrastructure from inception.
- Red Sea coastal integration:Port-centric secure warehousing at Yanbu and Duba connects to inland distribution with shorter exposure windows than Jeddah-Riyadh corridors. Specialized operators can capture transshipment volume.
- Renewable energy component security:Solar panel and battery storage facilities require anti-theft transportation and vaulting. SAMA's operational risk frameworks extend to critical infrastructure protection mandates.
Industry Challenges
- Multi-regulator compliance synchronization:SAMA cybersecurity mandates, Saudi Food and Drug Authority pharmaceutical protocols, and General Authority of Civil Aviation air cargo screening create overlapping audit requirements. Single-platform reporting solutions remain immature.
- Legacy fleet retrofit complexity:Armored vehicles with 15-20 year service lives lack native IoT architecture. Aftermarket sensor integration compromises ballistic integrity certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Secure Logistics Market |
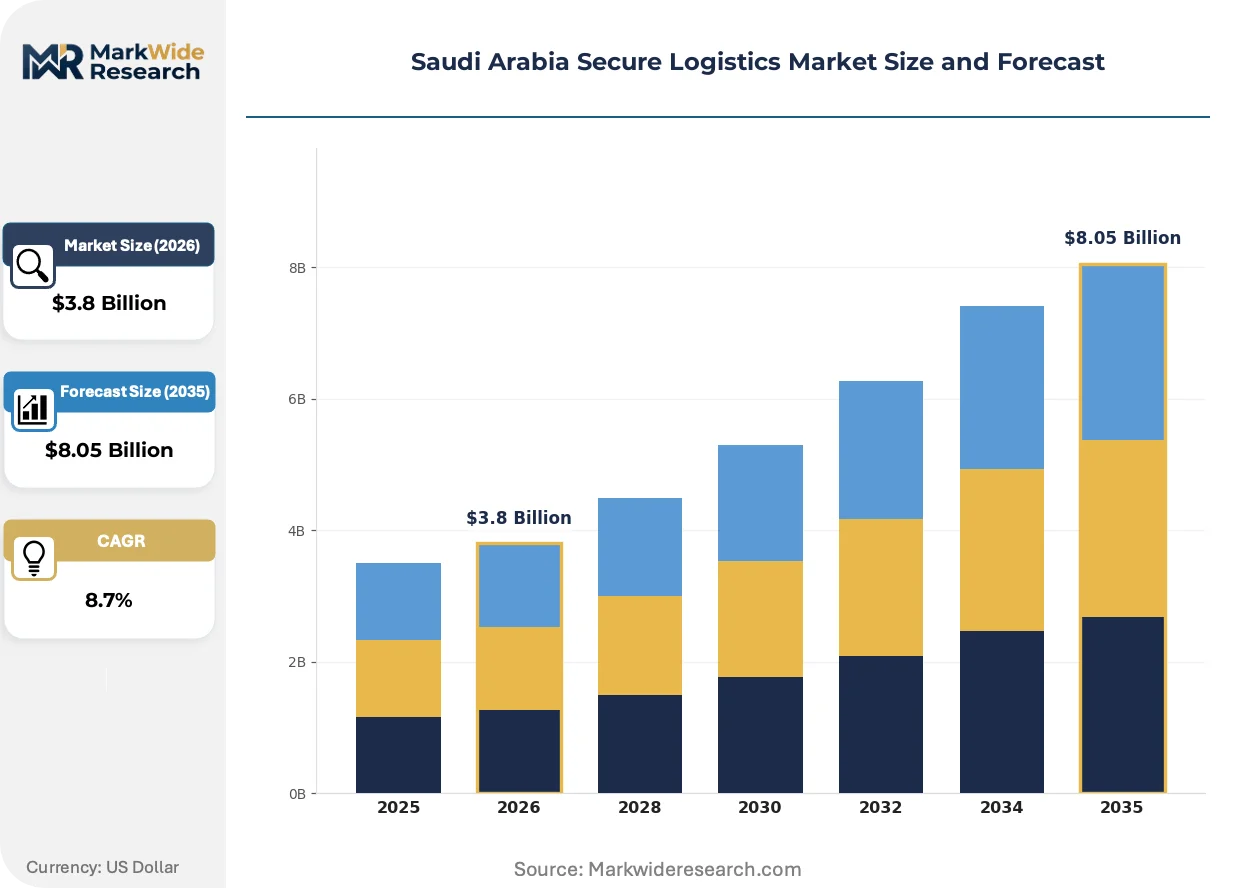
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Security Consulting, Inventory Management Technology: GPS Tracking, RFID, IoT Solutions, Blockchain End User: Retail, Pharmaceuticals, Automotive, Aerospace Distribution Channel: Direct Sales, Online Platforms, Third-Party Logistics, Freight Forwarders |
| Companies Covered | The Brink's Co, G4S, Prosegur, Loomis AB, GardaWorld, CMS Info Systems, CargoGuard, Lemuir Group, Allied Universal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Secure Logistics Market Trends and Innovations
Operational technology stacks across Saudi Arabia's secure logistics sector are fragmenting into interoperable components. Buyers now assemble solutions from specialized vendors rather than accepting monolithic service bundles, compressing vendor lock-in and accelerating replacement cycles.
Blockchain-enabled audit trails are modularizing custody documentation across pharmaceutical and precious metals transportation. Major hospital networks and gold refineries in Riyadh now mandate distributed-ledger verification for high-value shipments. This technology is compressing dispute resolution timelines from weeks to hours while elevating data storage requirements for transport operators.
SAMA's phased implementation of biometric driver authentication is reshaping fleet personnel protocols. The framework mandates fingerprint and facial recognition for vehicle access and route authorization, with full compliance required for license renewal. Cash-in-transit operators in the Eastern Province are deploying pilot programs to validate system integration with existing dispatch platforms.
Consolidated service purchasing is displacing single-function contracts among Saudi banking institutions. Treasury departments now bundle cash management, ATM replenishment, and vault storage under unified performance metrics with penalty clauses for custody breaches. This pattern is most visible among Riyadh-based retail banks with 50+ branch networks seeking operational simplification.
Saudi Arabia Secure Logistics Market Segmentation
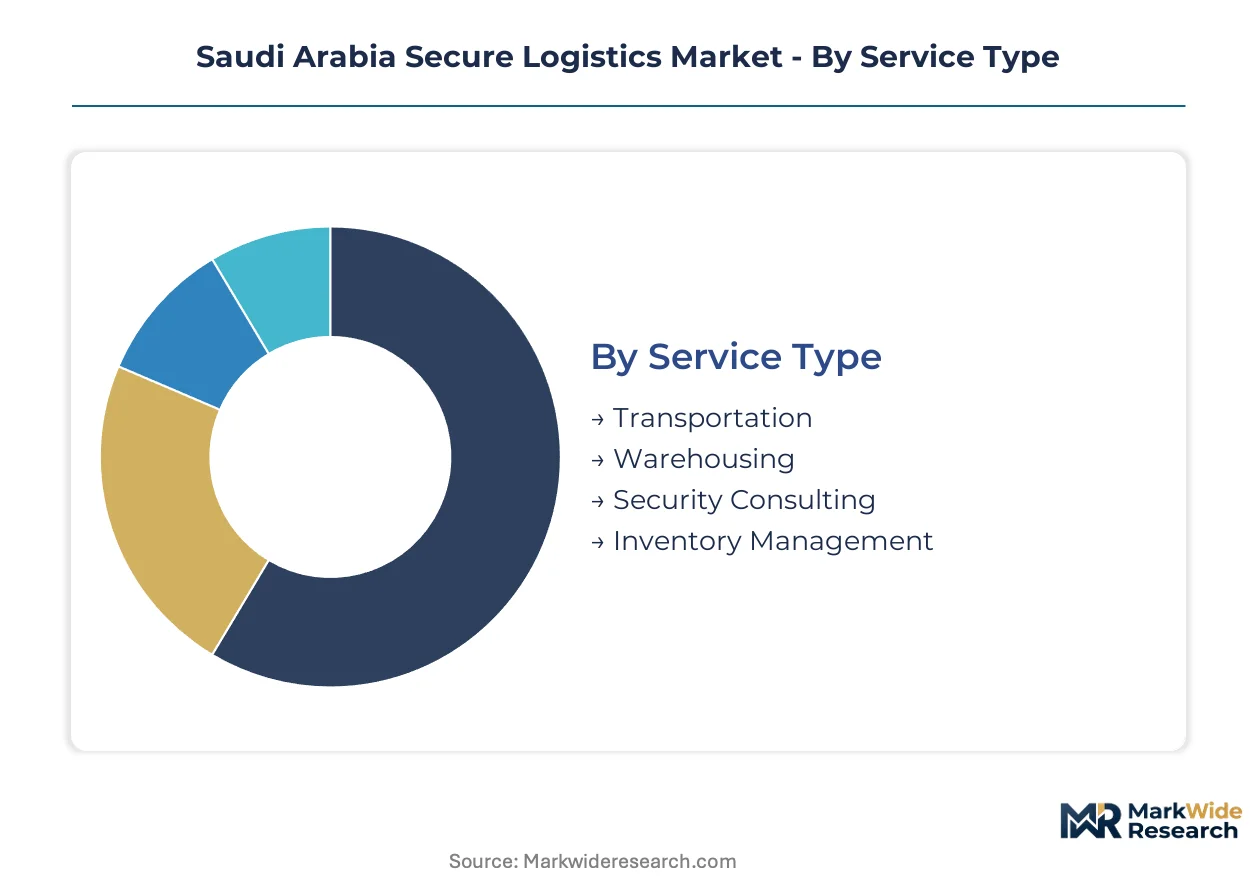
Segmentation in Saudi Arabia's secure logistics market reveals how SAMA compliance mandates and infrastructure modernization are fragmenting procurement patterns. Buyers now assemble solutions across service types, technologies, and distribution channels rather than accepting bundled offerings from single vendors.
Service Type:
Replacement cycles for legacy service contracts are compressing as SAMA's phased compliance deadlines force simultaneous upgrades across custody protocols. Fleet operators and vault providers face overlapping capital commitments.
- Transportation:Armored vehicle networks with biometric driver authentication and real-time GPS monitoring form the revenue core. Demand concentrates along Riyadh-Jeddah corridors where cash-in-transit volumes remain highest despite banking digitization. SAMA's operational risk standards mandate continuous fleet visibility upgrades.
- Warehousing:Blast-resistant vault construction with biometric access control and climate monitoring for pharmaceutical storage. Jeddah Islamic Port's cold chain expansion drives specialized facility investment. The Saudi Food and Drug Authority mandates end-to-end chain-of-custody documentation for temperature-sensitive biologics.
- Security Consulting:SAMA Cybersecurity Framework compliance advisory and risk assessment services for banking institutions.
- Inventory Management:Vaulted asset tracking and reconciliation systems with blockchain audit trail integration.
Transportation sits at the top of the volume ranking, with Security Consulting climbing the fastest as compliance deadlines tighten.
Technology:
Cost tiers for technology deployment separate premium integrated platforms from modular point solutions, with mid-tier hybrid architectures gaining traction among regional operators.
- GPS Tracking:Satellite-based fleet positioning with geofencing and route deviation alerts across Saudi Arabia's desert highway network. Insurance underwriters now mandate granular visibility for premium armored vehicle coverage. Eastern Province cash-in-transit operators deploy enhanced systems to satisfy SAMA incident response requirements.
- IoT Solutions:Sensor networks for continuous environmental monitoring, vehicle diagnostics, and cargo condition verification. Pharmaceutical cold chains from Jeddah to Riyadh require temperature and humidity logging with automated alert escalation. Real-time data streams reduce spoilage liability for biologics distributors.
- RFID:Automated asset identification and custody transfer verification for high-value inventory.
- Blockchain:Distributed-ledger documentation for immutable audit trails in precious metals and pharmaceutical transportation.
IoT Solutions capture the steepest expansion trajectory, while GPS Tracking retains the largest installed base across operational fleets.
End User:
Application-specific requirements drive divergent technology specifications, with pharmaceutical and retail segments demanding incompatible custody protocols.
- Retail:ATM replenishment, cash vaulting, and point-of-sale cash management for banking networks with 50+ branch footprints. Treasury departments in Riyadh consolidate service purchasing under unified performance metrics with penalty clauses for custody breaches. E-commerce fulfillment strain is elevating last-mile security requirements.
- Pharmaceuticals:Temperature-controlled distribution of biologics and controlled substances with continuous chain-of-custody documentation. Jeddah Islamic Port serves as the primary entry point for imported vaccines and specialty drugs. The Saudi Food and Drug Authority mandates specialized armored refrigeration units with redundant monitoring systems.
- Automotive:Secure transport of high-value components and finished vehicles for domestic assembly and export.
- Aerospace:Custody protocols for aircraft parts and maintenance equipment requiring traceability certification.
Retail commands the deepest service penetration, though Pharmaceuticals is gaining share fastest on cold chain infrastructure investment.
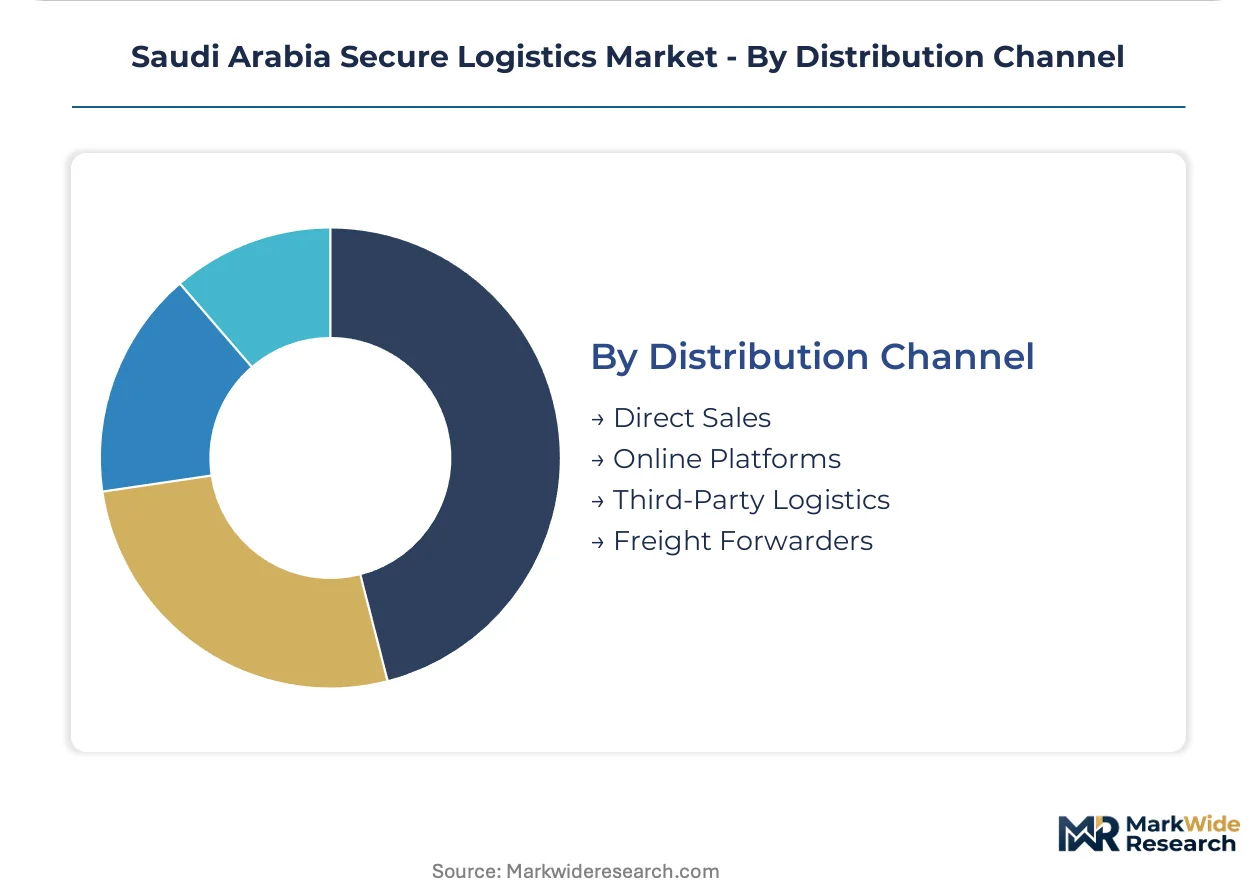
Distribution Channel:
Customer type determines channel preference, with institutional banking clients favoring direct relationships while mid-market operators route through intermediaries.
- Direct Sales:Long-term contractual relationships between secure logistics operators and major banking institutions or government entities. SAMA licensing requirements favor established vendors with demonstrated compliance histories. Riyadh-based retail banks with extensive branch networks negotiate multi-service bundles directly.
- Third-Party Logistics:Intermediary coordination of secure transport and warehousing for clients without dedicated logistics infrastructure. Jeddah's port logistics corridors concentrate 3PL activity for pharmaceutical and precious metals transshipment. Operators leverage existing relationships to access SAMA-compliant capacity.
- Online Platforms:Digital procurement interfaces for standardized security services and equipment.
- Freight Forwarders:International shipment coordination with secure custody handoffs at Saudi entry points.
Direct Sales dominates contract value, with Third-Party Logistics expanding most quickly among mid-market pharmaceutical distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Saudi Arabia secure logistics sector traces its modern infrastructure to the banking consolidation waves of the 1970s-1980s, when Riyadh's emergence as a financial hub necessitated armored cash transport networks across the Arabian Peninsula.
Riyadh
Central bank headquarters proximity drives premium cash-in-transit demand from SAMA-regulated institutions. The Saudi Central Bank's Cybersecurity Framework mandates biometric authentication for all fleet operators serving the financial district. King Abdullah Financial District concentrates multi-vendor service contracts as retail banks consolidate treasury operations.
Eastern Province
Petrochemical facility security and energy sector payroll distribution create specialized high-value transport requirements. The General Authority of Civil Aviation coordinates air cargo screening protocols for Dammam King Fahd International Airport's secure freight terminals. Jubail Industrial City hosts dedicated armored fleets serving refinery and downstream chemical complexes.
Western Region
Jeddah Islamic Port's pharmaceutical import volume necessitates temperature-controlled armored refrigeration units with continuous monitoring. The Saudi Food and Drug Authority mandates end-to-end chain-of-custody documentation for biologics transshipment. Makkah and Madinah pilgrimage corridors generate seasonal spikes in cash management infrastructure deployment.
NEOM Northwest
The planned smart city requires ground-up secure logistics architecture without legacy system constraints. SAMA's operational risk frameworks extend to critical infrastructure protection mandates for renewable energy component security. The Red Sea coastal zone enables shorter exposure windows for high-value cargo than traditional Jeddah-Riyadh corridors.
Saudi Arabia Secure Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance certification depth and biometric technology integration. The vendor base clusters around three strategic tiers: multinational incumbents with SAMA licensing histories, regional specialists leveraging port proximity, and technology-forward entrants targeting blockchain audit trail niches. Dominant competitive moves include portfolio diversification into pharmaceutical cold chains and strategic partnerships with biometric authentication providers.
Within the multinational incumbent tier, The Brink's Co and Loomis AB occupy positions shaped by armored fleet scale and established central bank relationships. G4S represents the integrated guarding-technology archetype, anchoring competitive positioning through combined physical and digital security protocols. These three entities exemplify how SAMA compliance histories and biometric infrastructure investments separate premium-tier operators from mid-market challengers.
| Leading Market Players |
|---|
| The Brink's Co |
| G4S |
| Prosegur |
| Loomis AB |
| GardaWorld |
| CMS Info Systems |
| CargoGuard |
| Lemuir Group |
| Allied Universal |
| Others |
Pricing and Supply Chain Analysis
SAMA's phased biometric authentication mandates are compressing procurement timelines for cash-in-transit operators, forcing simultaneous fleet retrofit investments that reshape vendor pricing power across Riyadh and Jeddah corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Saudi Arabia secure logistics, with premium tiers capturing SAMA-compliant operators with biometric-blockchain integration while economy tiers serve non-banking sectors with basic GPS tracking. Price differentiation hinges on certification depth against SAMA's Cybersecurity Framework and fleet scale economies for armored vehicle density. Pricing pressure stems from European armored vehicle import backlogs that extend delivery timelines and elevate leasing rates. Mid-market pharmaceutical distributors exhibit highest price sensitivity due to thin biologics margins, whereas Riyadh-based retail banks with consolidated treasury operations prioritize compliance assurance over unit cost.
Supply Chain Analysis
Armored vehicle refurbishment flows from Saudi fleet operators back to European ballistic chassis manufacturers create reverse logistics complexity, with 15-20 year service lives demanding aftermarket sensor integration without compromising certification integrity. Supply concentrates in Germany, Italy, and the United States for ballistic-rated chassis and blast-resistant steel components. Raw material dependencies span reinforced concrete for vault construction, biometric authentication hardware from East Asian semiconductor fabricators, and specialized refrigeration compressors for pharmaceutical cold chains. Single-source vulnerability permeates the armored vehicle chassis tier where European suppliers maintain order backlogs exceeding twelve months. Distribution runs through direct contractual relationships with SAMA-licensed operators for banking sector procurement, while third-party logistics intermediaries serve mid-market pharmaceutical distributors in Jeddah's port logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia secure logistics has entered a late-cycle quality phase where SAMA compliance certification separates viable operators from stranded legacy assets, with banking institutions consolidating procurement around premium-tier vendors.
For Market Incumbents: Cement biometric authentication infrastructure as the non-negotiable competitive moat by deepening partnerships with specialized hardware providers and securing exclusive technician training pipelines through Saudi technical institutes. Defend against technology-forward entrants targeting blockchain audit trail niches by accelerating pilot programs in the Eastern Province that validate system integration with existing dispatch platforms. Prioritize capacity addition in Jeddah's pharmaceutical cold chain corridor where temperature-controlled armored refrigeration units command premium margins. For New Entrants and Emerging Players: Third-party logistics intermediaries represent the most accessible channel for market penetration, particularly for mid-market pharmaceutical distributors lacking dedicated SAMA-compliant infrastructure. White-space targets include Yanbu and Duba port-centric secure warehousing along the Red Sea coastal zone, where shorter exposure windows than traditional Jeddah-Riyadh corridors enable competitive positioning. Target NEOM's ground-up logistics architecture as a design-build opportunity without legacy retrofit constraints, leveraging direct sales relationships with the smart city's procurement authority. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing established port proximity in Jeddah and demonstrated Saudi Food and Drug Authority compliance histories for pharmaceutical distribution. Long-term viability favors operators with integrated guarding-technology capabilities that span physical and digital security protocols across the projection horizon. Monitor SAMA licensing renewal deadlines as the critical inflection indicator, with mass expiration windows creating forced vendor switching opportunities for compliant acquirers.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Fleet Retrofit Program | SAMA compliance deadlines force simultaneous capital deployment across authentication and blockchain layers. |
| Pharmaceutical Cold Chain Expansion | Jeddah Islamic Port biologics volume mandates specialized armored refrigeration with redundant monitoring. |
| NEOM Design-Build Partnership | Smart city ground-up architecture enables fully integrated infrastructure without legacy constraints. |
| Red Sea Coastal Warehousing | Yanbu and Duba transshipment hubs capture volume with shorter exposure windows than inland corridors. |
| Technician Training Pipeline | Saudi technical institute partnerships address certified personnel scarcity for blockchain integration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, SAMA compliance officers, pharmaceutical supply chain managers, and biometric technology integrators with secondary validation against SAMA regulatory filings, Saudi Food and Drug Authority pharmaceutical distribution guidelines, General Authority of Civil Aviation air cargo protocols, and armored vehicle import customs records. Bottom-up service-type revenue modeling triangulated against top-down macroeconomic indicators across the Saudi logistics sector.
Comparable-period anchoring tied projection assumptions to historical compliance implementation cycles and fleet replacement patterns observed across prior SAMA mandate phases. The analytical framework segmented by service type, technology tier, end-user industry, and distribution channel, with additional dimensioning by regional corridor density and certification compliance level. CAGRs derived from fitted growth curves calibrated to documented infrastructure investment timelines and regulator-stated implementation deadlines. Forecast inputs incorporated armored vehicle order backlogs reported by European manufacturers and pharmaceutical import volume trajectories through Jeddah Islamic Port.
Revisions become necessary when SAMA accelerates compliance deadlines, European armored vehicle export restrictions materialize, or renewable energy component security mandates expand beyond current critical infrastructure protection scope. Practitioners should monitor biometric authentication technology cost curves and blockchain audit trail standardization progress for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Digital Freight Matching Market
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Air Freight Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market