
 Electric Baby Car Market | 2026-2036
Electric Baby Car Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Baby Car Market Foresight
Subscription-based leasing and asset-light rental models is fragmenting capital requirements across the Electric Baby Car competitive landscape. Peg Perego leverages multi-generational brand equity in European specialty retail to sustain premium positioning. Kid Trax anchors North American mass-market distribution through big-box partnerships. Zhejiang Jiajia competes on integrated manufacturing scale, controlling component costs from plastic molding through final assembly.
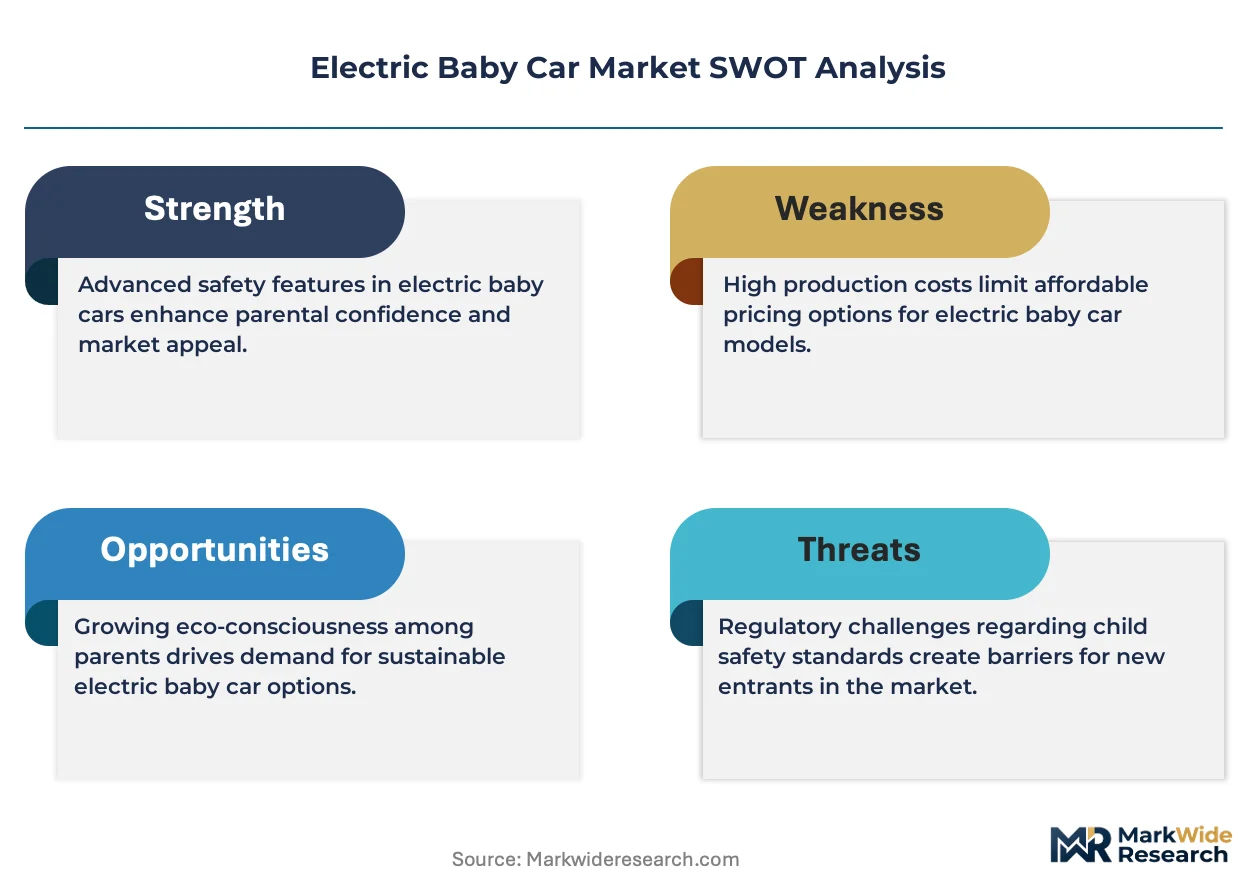
An electric baby car is a battery-powered, child-scaled ride-on vehicle designed for children aged one to five years, typically operating on six- or twelve-volt sealed lead-acid or lithium-ion systems with maximum speeds of two to five miles per hour for safety containment. These products serve dual commercial purposes: developmental motor-skill toys for home use and enrichment equipment for early childhood centers. The SUV product type dominates unit volume due to parental familiarity with full-size vehicle aesthetics, while battery electric technology leads installed base as plug-in hybrid configurations remain cost-prohibitive at this scale. Autonomous features represent the fastest-growing technology segment, though margin pools concentrate in specialty stores where assisted selling justifies price premiums over online channels.
The US Consumer Product Safety Commission enforces mandatory toy safety standards including electrical and mechanical hazard testing, while EU REACH restricts phthalates and heavy metals in plastic housings. China's SAMR coordinates national standards through GB certification for battery-powered toys, creating a three-jurisdiction compliance burden for exporters. Stakeholders must monitor evolving lithium-ion transportation regulations and decide whether to absorb certification costs or retreat to single-region concentration.
Market Dynamics
Dual-income household expansion in China, the United States, and Germany is compressing purchase cycles for premium ride-on toys, while EU REACH and US CPSIA battery safety mandates are forcing manufacturers to absorb certification costs or retreat to single-region concentration.
Growth Catalysts
- EU REACH phthalate restrictions:Compliance-driven material upgrades are creating tiered product lines that command price premiums in specialty retail channels.
- Autonomous feature modules:Sensor-assisted steering and remote parental control systems are expanding addressable demand among safety-conscious urban households.
- Zhejiang-Hebei production clustering:Integrated plastic molding and battery assembly capabilities are compressing unit economics for export-oriented manufacturers.
Market Restraints
- Lithium-ion cell cost volatility:Sealed lead-acid batteries retain cost advantage but face weight and cycle-life limitations that constrain product performance ceilings.
- Three-jurisdiction compliance burden:Exporters must simultaneously satisfy US CPSC electrical testing, EU REACH substance restrictions, and China SAMR GB certification.
- Plug-in hybrid configuration economics:Dual-powertrain complexity at child-scale volumes renders hybrid architectures commercially unviable versus pure battery electric.
Strategic Opportunities
- Subscription-based leasing models:Asset-light rental platforms are fragmenting capital requirements and opening access to price-sensitive trial buyers.
- Early childhood center enrichment procurement:Institutional bulk purchasing represents an underpenetrated channel with standardized specification requirements.
- India BIS toy safety certification:Formalized national standards are reducing import friction and enabling organized retail penetration in tier-1 cities.
Industry Challenges
- Lithium-ion transportation certification timelines:UN 38.3 testing and IATA shipping documentation are extending new product introduction cycles by 8-14 weeks.
- Cross-border e-commerce return logistics:Battery-powered product reverse flows face hazardous material handling restrictions that erode margin on direct-to-consumer sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Baby Car Market |
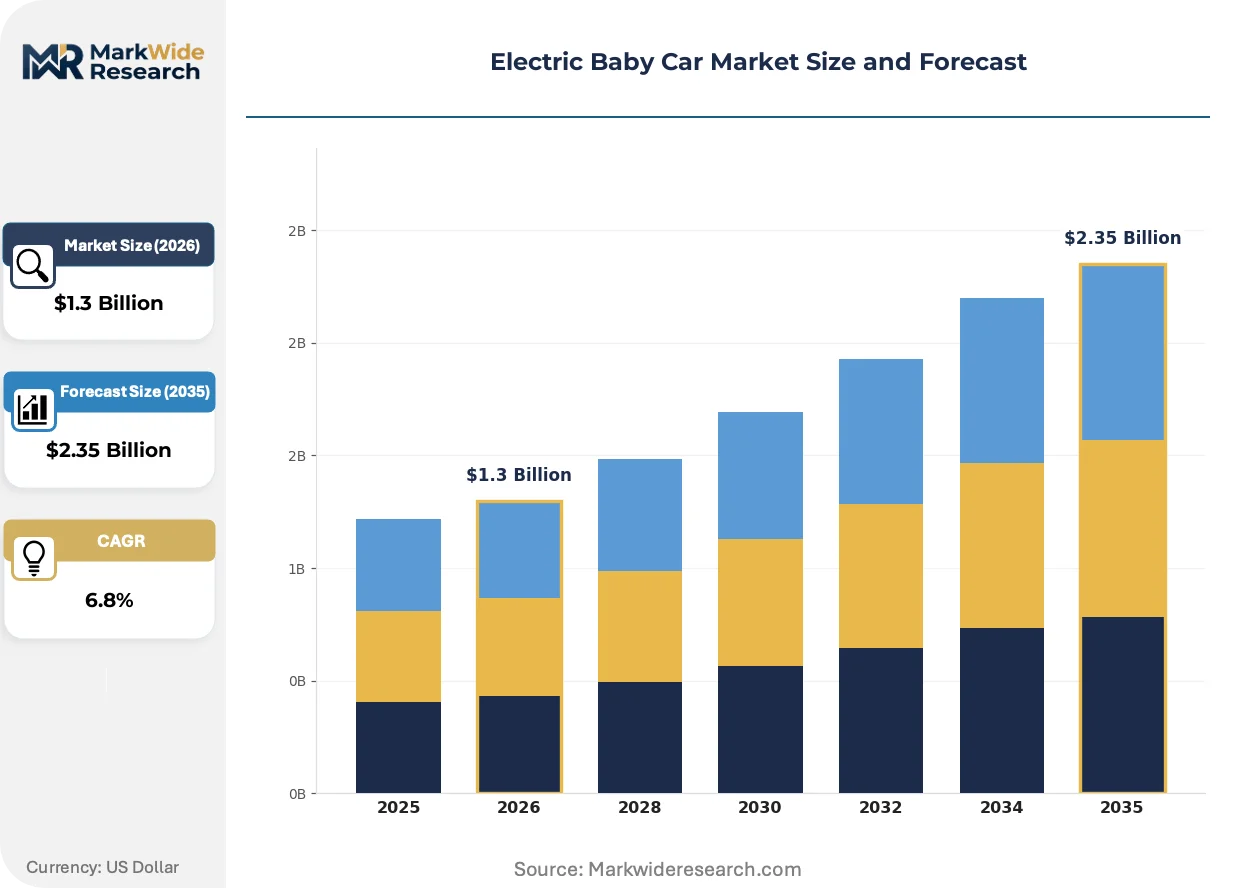
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convertible, Sports, SUV, Hatchback Technology: Battery Electric, Plug-in Hybrid, Solar-Powered, Autonomous End User: Parents, Early Childhood Centers, Retailers, Educational Institutions Distribution Channel: Online, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Peg Perego, Kid Trax, Mattel, Fisher-Price, Zhejiang Jiajia, Hebei Province Manufacturers, Power Wheels, Dynacraft BSC, Ryder Toys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Baby Car Market Shifts & Advancements
Sensor integration and connectivity modules are digitizing product architectures, while regulatory substance restrictions and procurement model fragmentation are simultaneously reshaping competitive positioning and channel economics.
Bluetooth-enabled parental override systems are digitizing traditional ride-on controls by allowing smartphone-based speed limiting and geofencing. Premium buyer segments in Germany and the United States are adopting these features at twice the rate of mass-market channels. This capability compression is enabling subscription-based rental platforms to offer differentiated service tiers without hardware proliferation.
EU REACH Annex XVII phthalate restrictions are tightening permissible concentrations in plastic housings and steering components. Manufacturers serving European specialty retail must reformulate resin compounds or source alternative elastomers, raising bill-of-materials costs. The SUV product category, with its larger plastic surface area, faces disproportionate compliance burden versus compact ride-on formats.
Direct-to-institutional procurement is displacing traditional distributor intermediaries in early childhood center supply chains. Facility operators in China and the United States are consolidating vendor relationships through group purchasing organizations. This channel compression is most visible in urban districts with high childcare center density, where specification standardization reduces sourcing complexity.
Electric Baby Car Market Segmentation
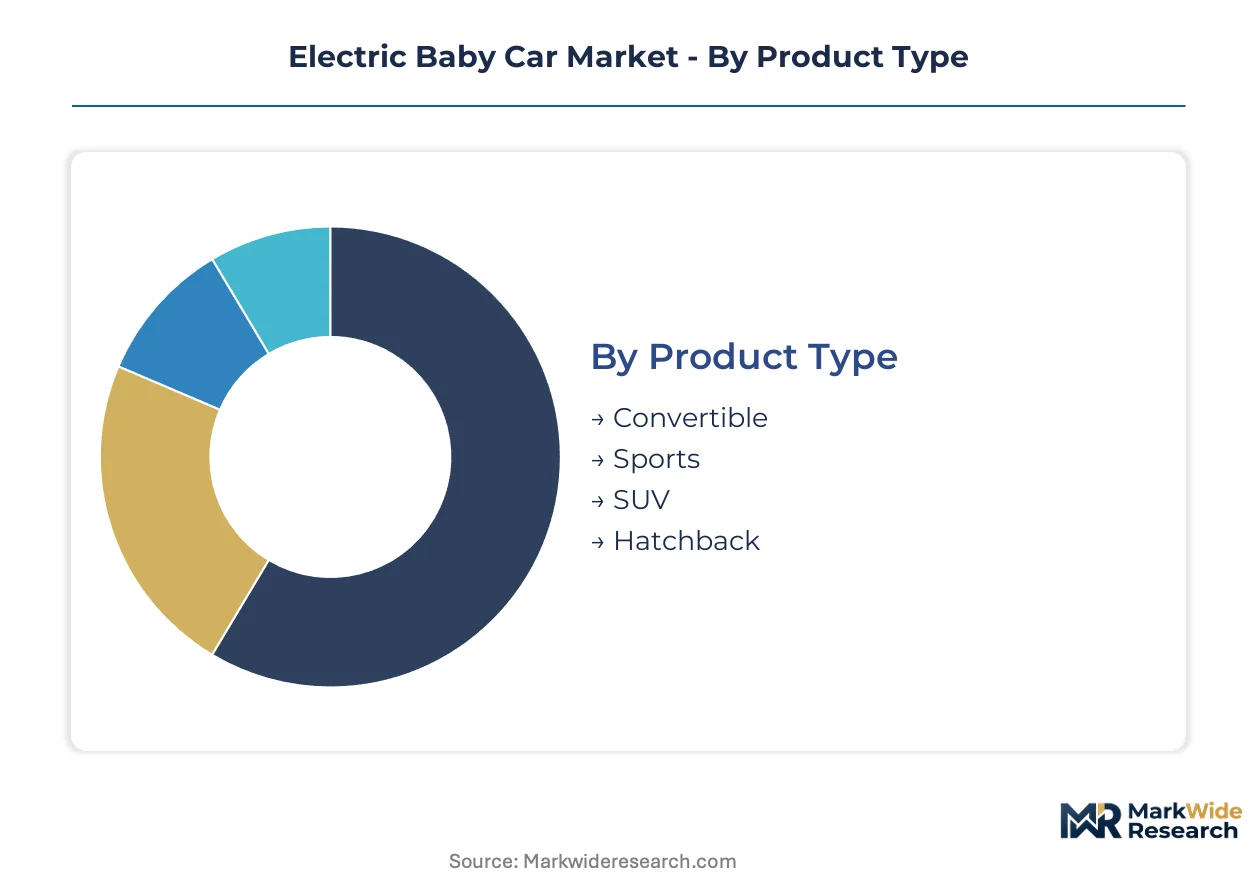
Segmentation in the Electric Baby Car Market reveals how purchase frequency, safety certification tiers, and channel economics fragment buyer behavior across product configurations. Understanding these divides exposes where margin pools concentrate versus where volume scales.
Product Type:
SUV configurations turn over fastest as parental familiarity with full-size vehicle aesthetics compresses replacement cycles, while Convertible formats exhibit slower refresh rates tied to seasonal purchasing patterns.
- SUV:These child-scaled replicas of sport utility vehicles carry the largest plastic surface area among all formats, exposing manufacturers to disproportionate EU REACH phthalate compliance costs. Demand clusters in China and the United States where dual-income households prioritize recognizable automotive branding for developmental play value.
- Sports:Low-slung aerodynamic designs with two-seat configurations appeal to performance-oriented parents seeking motorsport aesthetics. Germany and California represent concentration zones where premium positioning justifies higher price points through assisted selling in specialty retail.
- Convertible:Retractable roof mechanisms add mechanical complexity that extends product development timelines. These formats attract gift purchasers seeking novelty appeal over long-term utility.
- Hatchback:Compact footprints suit urban apartment dwellers with limited storage space. Zhejiang province manufacturers favor this format for export economics due to reduced shipping cube.
SUV dominates installed base. Sports is where expansion concentrates.
Technology:
Cost tier stratification separates sealed lead-acid legacy systems from lithium-ion premium architectures, with autonomous modules commanding the steepest price premiums.
- Battery Electric:Six- and twelve-volt sealed lead-acid or lithium-ion configurations constitute the overwhelming majority of installed units. Zhejiang-Hebei production clusters achieve vertical cost control from cell assembly through final integration.
- Autonomous:Sensor-assisted steering and remote parental override systems are expanding addressable demand among safety-conscious urban households. Bluetooth-enabled geofencing and smartphone speed limiting command price premiums at twice the adoption rate of mass-market channels in Germany and the United States.
- Plug-in Hybrid:Dual-powertrain complexity at child-scale volumes renders this architecture commercially unviable versus pure battery electric. Manufacturers have largely abandoned development.
- Solar-Powered:Photovoltaic panel integration remains niche due to inconsistent charging performance and higher bill-of-materials costs. Early childhood centers in sun-belt geographies represent the primary procurement channel.
Battery Electric dominates installed base. Autonomous is climbing the fastest.
End User:
Application context fragments procurement specifications, with institutional buyers demanding standardized durability ratings that diverge from parental purchase criteria.
- Parents:Dual-income households in China, the United States, and Germany compress purchase cycles for premium ride-on toys. This segment drives autonomous feature adoption through safety-conscious urban demand.
- Early Childhood Centers:Facility operators in China and the United States consolidate vendor relationships through group purchasing organizations. Direct-to-institutional procurement is displacing traditional distributor intermediaries in urban districts with high childcare center density.
- Retailers:Mass-market and specialty channels maintain divergent specification requirements. Big-box partnerships anchor volume while specialty stores justify price premiums through assisted selling.
- Educational Institutions:Schools and enrichment programs prioritize durability and multi-child usage patterns over aesthetic features. Procurement runs through formalized bidding processes with extended decision timelines.
Parents dominates installed base. Early Childhood Centers is gaining share fastest.
Distribution Channel:
Geography of fulfillment reshapes margin structures, with cross-border e-commerce facing hazardous material handling restrictions that erode direct-to-consumer economics.
- Online:Direct-to-consumer sales face battery-powered product reverse flow restrictions under UN 38.3 and IATA documentation requirements. Subscription-based leasing platforms fragment capital requirements through asset-light rental models.
- Specialty Stores:Assisted selling justifies price premiums over online channels. EU REACH compliance-driven material upgrades create tiered product lines that command premiums in this channel.
- Supermarkets:Mass-market volume concentrates here with standardized specifications and compressed margins. Big-box partnerships anchor North American distribution for volume-focused manufacturers.
- Direct Sales:Manufacturer-controlled fulfillment bypasses intermediary margins but absorbs logistics complexity. Early childhood center procurement increasingly shifts to this channel as group purchasing organizations consolidate vendor relationships.
Specialty Stores dominates installed base. Online is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsidy programs for early childhood development equipment and tightening toy safety certifications are reshaping procurement patterns across major demand centers. Dual-income household expansion accelerates premium ride-on purchases in urban clusters. Production gravity concentrates in manufacturing belts with integrated plastic molding and battery assembly capabilities.
United States
Mass-market big-box partnerships anchor volume distribution while specialty retail commands price premiums through assisted selling. The US Consumer Product Safety Commission enforces mandatory electrical and mechanical hazard testing under federal toy safety standards. California and Texas metro areas concentrate autonomous feature adoption among safety-conscious urban households with higher disposable income.
China
Zhejiang and Hebei province production clusters supply both domestic retail and export channels with integrated manufacturing from plastic molding through final assembly. The State Administration for Market Regulation coordinates national GB certification standards for battery-powered toys. Dual-income household compression in tier-1 cities accelerates purchase cycles for premium ride-on configurations.
Germany
EU REACH phthalate restrictions drive compliance-driven material upgrades that create tiered product lines commanding premiums in specialty retail. The European Chemicals Agency enforces Annex XVII restrictions on plastic housings and steering components. Bavaria and North Rhine-Westphalia concentrate demand for Bluetooth-enabled parental override systems with smartphone geofencing capabilities.
India
Bureau of Indian Standards toy safety certification is reducing import friction and enabling organized retail penetration in tier-1 cities. The national standards body formalized safety requirements that previously fragmented state-level enforcement. Maharashtra and Delhi-NCR concentrate early childhood center procurement through emerging group purchasing organization structures.
Japan
Compact urban dwelling patterns favor hatchback formats with reduced storage footprints over SUV configurations. The Ministry of Economy, Trade and Industry oversees product safety frameworks aligned with international IEC standards. Kanto and Kansai metropolitan areas concentrate demand for sensor-assisted steering modules among safety-conscious urban households.
Electric Baby Car Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. The vendor base fragments between mass-market volume anchors and premium-tier specialists, with subscription-based leasing platforms emerging as a third competitive vector. Three archetypes dominate: European heritage brands leveraging multi-generational equity, Chinese integrated manufacturers controlling upstream component costs, and North American mass-market distributors securing big-box shelf space. Capacity expansion in Zhejiang-Hebei clusters and strategic partnerships for autonomous module sourcing represent the dominant competitive moves.
Within the heritage-brand tier, Peg Perego occupies a position exemplifying European specialty retail positioning through multi-generational brand equity. Among Chinese integrated manufacturers, Zhejiang Jiajia represents the scale-driven archetype with captive control over plastic molding and battery assembly operations. At the mass-market vector, Kid Trax anchors North American distribution architecture through big-box partnership structures.
| Leading Market Players |
|---|
| Peg Perego |
| Kid Trax |
| Mattel |
| Fisher-Price |
| Zhejiang Jiajia |
| Hebei Province Manufacturers |
| Power Wheels |
| Dynacraft BSC |
| Ryder Toys |
| Others |
Supply & Pricing Matrix
Yantian-Shenzhen container corridor freight volatility compresses export margins for Zhejiang-Hebei manufacturers while amplifying price spreads between mass-market and specialty retail tiers. Battery chemistry selection and certification grade separate premium autonomous-enabled units from sealed lead-acid economy configurations.
Pricing Analysis
Certification level (EU REACH/China GB/US CPSC-grade) creates the primary spread between premium specialty-store positioning and mass-market supermarket tiers. Three-tier pricing structure across premium autonomous, standard battery-electric, and economy sealed lead-acid levels reflects material compliance costs and feature bundling. Pricing pressure stems from lithium-ion cell cost volatility and three-jurisdiction testing burdens. Early childhood centers exhibit highest price sensitivity through consolidated procurement, while safety-conscious urban parents in Germany and the United States show lowest sensitivity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for export-oriented manufacturers. Production concentrates in Zhejiang and Hebei provinces with integrated plastic molding and battery assembly operations. Raw material dependencies center on lithium-ion cells, ABS resin compounds, and electronic control modules. Distribution runs through big-box partnerships for volume and specialty retail for premium tiers, with direct-to-institutional procurement gaining share in childcare center supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. Certification breadth across US, EU, and Chinese jurisdictions creates switching costs that protect incumbent positioning.
For Market Incumbents: Pre-empt subscription-based leasing platforms by piloting asset-light rental models in tier-1 Chinese and US cities. Deepen captive control over lithium-ion cell sourcing to insulate margin from transportation certification delays. Counter emerging autonomous module specialists through exclusive sensor supplier partnerships.
For New Entrants and Emerging Players: Build out India BIS-certified manufacturing for organized retail penetration in Maharashtra and Delhi-NCR. Target early childhood center procurement through group purchasing organization relationships as the most penetrable institutional channel. Lead with direct sales capability to bypass entrenched distributor intermediaries.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified toy conglomerates with under-optimized ride-on divisions. Long-term viability hinges on autonomous feature integration and regulatory certification breadth. Watch lithium-ion transportation documentation timelines as the inflection signal for new product introduction cycle competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Module Integration | Sensor-assisted steering and parental override systems command price premiums in Germany and US specialty retail. |
| Subscription Leasing Platform Launch | Asset-light rental models fragment capital requirements and open trial access among price-sensitive urban households. |
| Direct-to-Institutional Procurement Buildout | Group purchasing organization relationships displace distributor intermediaries in China and US childcare center supply chains. |
| Multi-Jurisdiction Certification Investment | Simultaneous US CPSC, EU REACH, and China SAMR compliance creates tiered product lines and defensible positioning. |
| Zhejiang-Hebei Capacity Expansion | Integrated plastic molding and battery assembly operations compress unit economics for export-oriented manufacturers. |
Research Methodology
A standing panel of product development directors at ride-on toy manufacturers, procurement managers at early childhood center chains, specialty retail buyers, and lithium-ion battery logistics specialists provided ongoing calibration. Primary interview insights combined with customs trade data, SAMR GB certification filings, CPSC recall databases, and EU REACH substance restriction updates. Bottom-up unit shipment modeling and top-down retail audit triangulation anchored volume estimates.
Scenario-bracketing framed demand trajectories across the projection horizon. Segmentation dimensions modeled include product type, battery chemistry tier, end-user application, and distribution channel. CAGRs derived from fitted growth curves applied to parental household formation rates and institutional procurement cycle analysis. Forecast inputs incorporated autonomous feature adoption curves and lithium-ion transportation certification timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese manufacturers or autonomous technology specialists would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Leisure Boat Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Recreational Vehicle Rental Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
United States RV Rental Market